
 Asia Pacific Drug Development Market | 2026-2036
Asia Pacific Drug Development Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Drug Development Market Insights
Drug development investment is shifting toward complex biologics and gene therapy platforms, widening the gap between premium capability providers and commodity small-molecule manufacturers. WuXi AppTec leverages integrated discovery-to-commercialization services across multiple modalities. Samsung Biologics anchors large-scale biologics manufacturing with dedicated mammalian cell culture facilities. WuXi Biologics specializes in antibody-drug conjugate and bispecific antibody development, competing on technical depth rather than volume.
Asia Pacific drug development encompasses the full sequence of preclinical discovery, clinical trial execution, regulatory submission, and commercial manufacturing for pharmaceutical therapeutics, with biologics requiring living-cell production systems operating at precise temperature, pH, and dissolved-oxygen parameters to maintain protein folding integrity. Small molecules retain volume leadership but face margin compression as generic competition intensifies, while gene therapy represents the fastest-expanding segment despite manufacturing complexity and limited viral vector capacity. Injectable delivery dominates biologics administration, though oral formulations for peptide drugs are gaining structural attention from pharmaceutical companies seeking patient compliance advantages.
China's NMPA accelerates oncology drug review timelines, while India's CDSCO aligns bioequivalence standards with WHO prequalification to expand export access. South Korea's MFDS enforces GMP-Biosafety guidelines that shape facility investment requirements for contract research organizations. Stakeholders must monitor regulatory divergence between national pharmacopoeias as complexity rises across cell and gene therapy submissions.
Market Dynamics
Biologics manufacturing complexity is concentrating value capture among contract development organizations with mammalian cell culture expertise, while small-molecule commoditization squeezes margins for legacy chemistry-focused providers across Asia Pacific.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for active pharmaceutical ingredients attract greenfield manufacturing investments and reduce import dependency for critical drug intermediates.
- NMPA Accelerated Review Pathways:China's streamlined oncology drug approval timelines compress development cycles and incentivize domestic clinical trial infrastructure expansion.
- Antibody-Drug Conjugate Demand:Precision oncology applications drive specialized bioconjugation capacity investments across South Korea and Singapore manufacturing clusters.
Market Restraints
- Viral Vector Scarcity:Gene therapy manufacturing faces binding constraints from limited AAV and lentiviral production capacity, creating queue bottlenecks for clinical programs.
- Single-Use Component Costs:Bioprocessing bags, connectors, and filtration assemblies experience price volatility tied to specialized polymer supply chains concentrated in North America and Europe.
- MFDS GMP-Biosafety Compliance:South Korea's stringent facility certification requirements extend capital deployment timelines and raise barrier-to-entry thresholds for new contract manufacturers.
Strategic Opportunities
- Vietnam Clinical Trial Expansion:Underserved patient populations and improving regulatory alignment with ASEAN standards attract Phase II-III oncology studies previously concentrated in China.
- Continuous Manufacturing Adoption:Flow chemistry integration for small-molecule APIs offers quality consistency advantages and regulatory appeal for export-oriented Indian manufacturers.
- CDSCO WHO Prequalification Alignment:India's bioequivalence standard harmonization unlocks institutional procurement access across Africa and Southeast Asia for generic drug exporters.
Industry Challenges
- Cell Line Development Expertise Gap:Shortage of scientists proficient in CRISPR-edited CHO cell engineering limits biologics productivity gains for mid-tier contract research organizations.
- Legacy Quality System Integration:Paper-based batch records and isolated data repositories obstruct real-time release testing adoption at established small-molecule facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Drug Development Market |
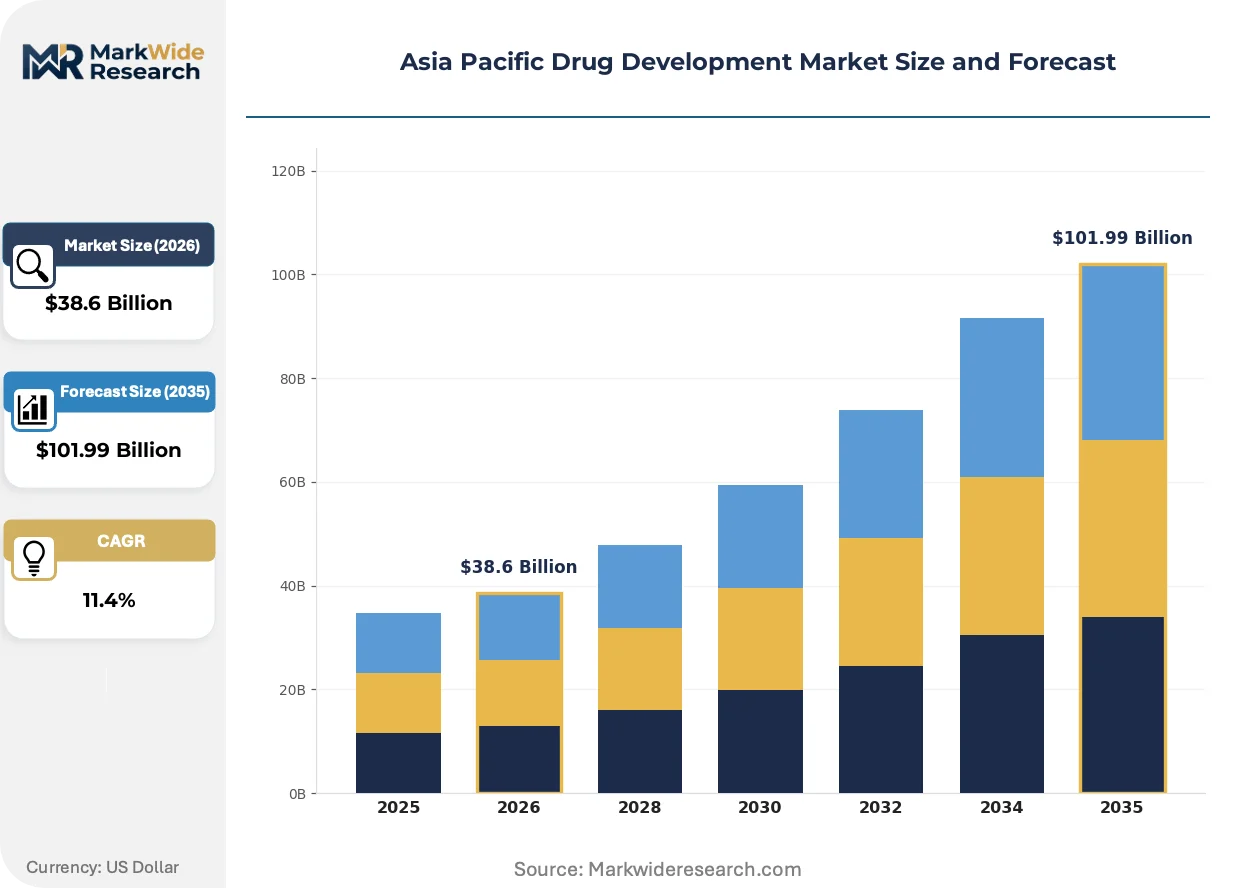
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Vaccines, Gene Therapy Delivery Mode: Injectable, Oral, Transdermal, Intranasal End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutes, Hospitals Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | WuXi AppTec, Samsung Biologics, WuXi Biologics, CELLTRION INC, Takeda Pharmaceutical Company, Novartis AG, Pfizer Inc, PT Kalbe Farma Tbk., Biocon, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Drug Development Market Trends and Innovations
Process analytical technology and closed-system bioreactor design are compressing contamination risk profiles while enabling real-time quality assurance across Asia Pacific manufacturing networks.
Single-use bioreactor technology is automating clean-in-place elimination and reducing cross-batch contamination exposure in multi-product contract manufacturing facilities. Large-scale biologics producers in South Korea and Singapore are adopting these systems at commercial scale to accommodate rapid product changeovers. This automation is compressing facility downtime between campaigns and enabling higher asset utilization rates for antibody manufacturing.
China's NMPA has implemented conditional approval frameworks for breakthrough oncology therapies, permitting earlier market access based on surrogate endpoints. This regulatory shift accelerates revenue realization timelines for domestic innovators and multinational joint ventures. Oncology developers are responding by front-loading China-specific clinical trial investments and establishing localized regulatory affairs capabilities.
Pharmaceutical procurement from government tenders is fragmenting into indication-specific contracts with distinct technical scoring criteria. Hospital systems and national purchasing agencies are disaggregating large therapeutic category awards into smaller, specialized lots favoring niche capability providers. This pattern is most visible in Australia's PBS procurement and Thailand's universal coverage scheme, where biosimilar and originator sourcing now follows separate competitive pathways.
Asia Pacific Drug Development Market Segmentation
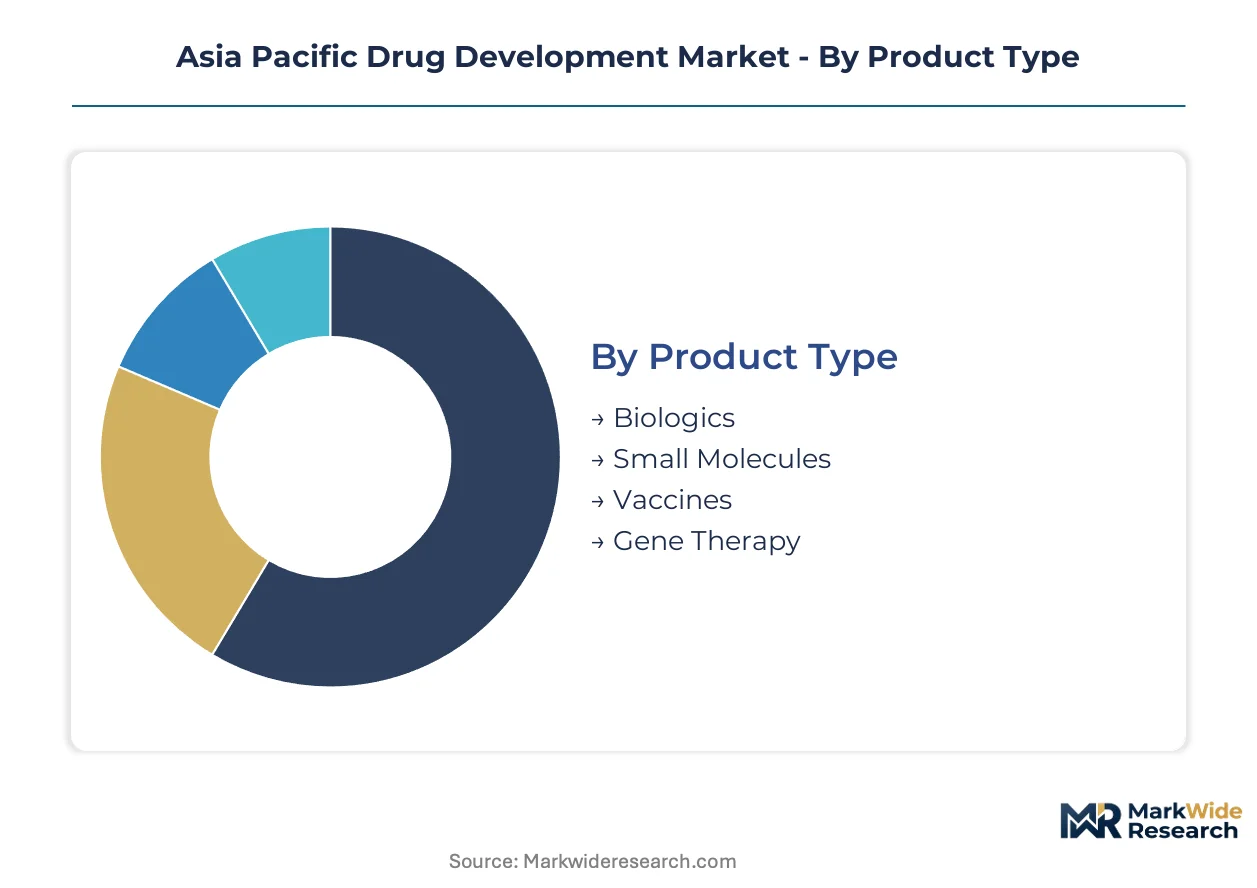
Segmentation reveals how modality complexity, delivery technology, and therapeutic focus reshape capability requirements across Asia Pacific drug development. Each dimension exposes distinct investment priorities and margin structures for contract service providers and pharmaceutical sponsors.
Product Type:
Upgrade cycles from legacy small-molecule platforms to living-system manufacturing are redefining facility capital allocation and technical workforce requirements across the region.
- Biologics:Protein therapeutics manufactured through mammalian or microbial cell culture demand precise control of temperature, pH, and dissolved oxygen parameters to maintain folding integrity. Demand concentrates in South Korea and Singapore manufacturing clusters, driven by antibody-drug conjugate programs requiring specialized bioconjugation expertise.
- Small Molecules:Synthetic chemistry-based APIs and finished dosage forms face margin compression from generic competition, though continuous manufacturing adoption offers quality consistency advantages for export-oriented Indian producers upgrading from batch processing.
- Vaccines:Adjuvanted and mRNA platforms require dedicated fill-finish lines and cold-chain infrastructure.
- Gene Therapy:Viral vector manufacturing faces binding capacity constraints from limited AAV and lentiviral production, creating queue bottlenecks for clinical programs across China and Japan.
Small molecules sit at the top of the volume ranking, with gene therapy climbing the fastest despite manufacturing complexity barriers.
Delivery Mode:
Patient compliance requirements and biologic stability constraints are shifting formulation investments toward alternative administration routes beyond traditional injection.
- Injectable:Parenteral delivery dominates biologics administration through prefilled syringes, autoinjectors, and vial formats requiring sterile manufacturing suites. Oncology and autoimmune applications in China and Australia drive demand for subcutaneous and intravenous formulations with extended shelf-life stability.
- Oral:Tablet and capsule formulations retain volume leadership for small molecules, though peptide oral delivery platforms are gaining structural attention from pharmaceutical companies seeking compliance advantages for chronic disease management.
- Transdermal:Patch and gel systems offer sustained release for pain management and hormone therapies.
- Intranasal:Mucosal delivery provides rapid systemic absorption for emergency medications and vaccine boosters.
Injectable formats command premium pricing, while oral peptide development represents the steepest expansion trajectory for formulation service providers.
End User:
Outsourcing depth varies by organization scale, with large pharmaceutical sponsors pursuing integrated partnerships while emerging biotechs seek flexible, milestone-based engagement structures.
- Pharmaceutical Companies:Multinational and domestic innovators drive integrated discovery-to-commercialization contracts, with WuXi AppTec and Samsung Biologics capturing long-term manufacturing agreements through dedicated capacity commitments and regulatory submission support.
- Contract Research Organizations:CDMOs and CROs themselves represent a growing client segment as platform companies subcontract specialized capabilities including viral vector production and CRISPR-edited cell line development.
- Academic Institutes:University spinouts and public research centers require early-phase manufacturing support for investigator-initiated trials.
- Hospitals:Health system sponsors concentrate in Japan and Australia for phase I oncology units and personalized medicine compounding.
Pharmaceutical companies anchor contract value, with academic institutes gaining share fastest through technology transfer partnerships.
Therapy Area:
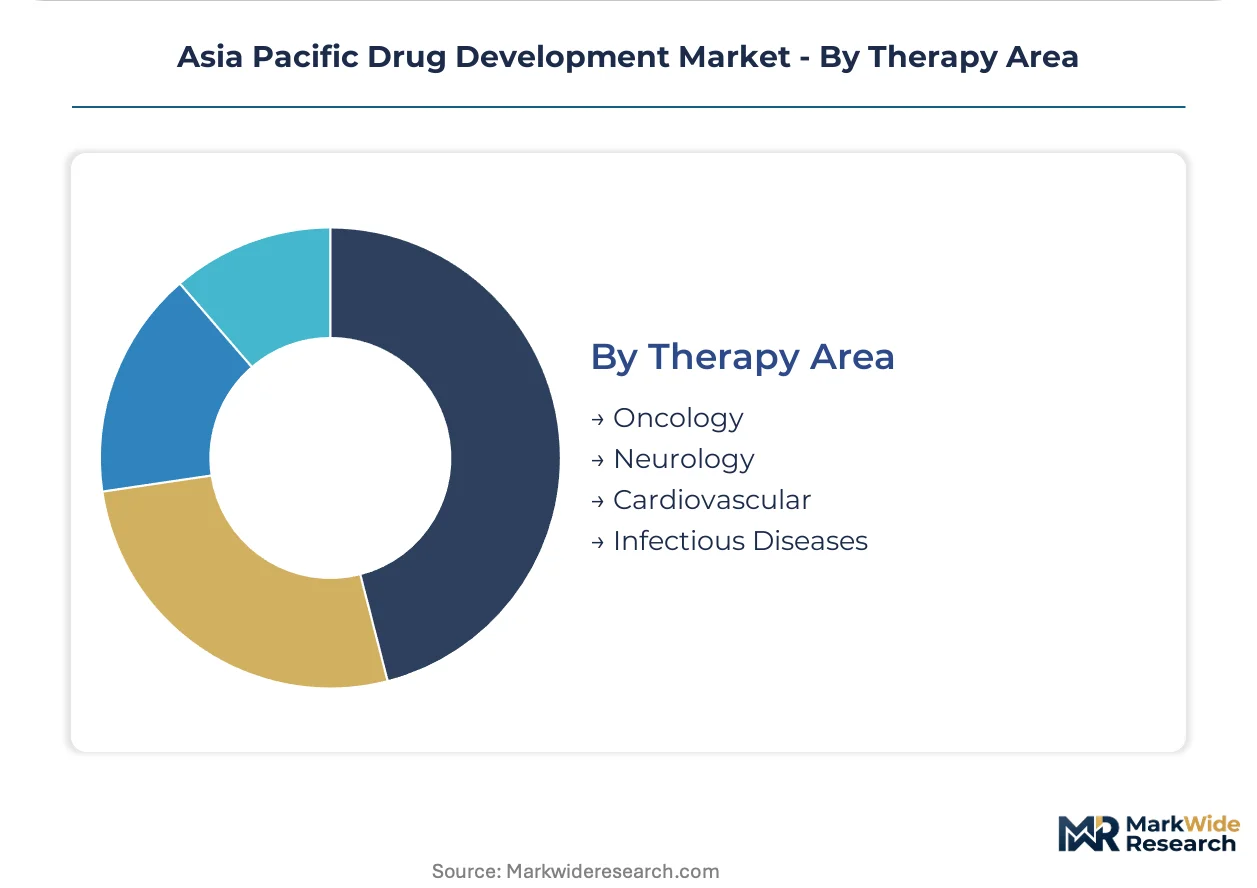
Clinical trial infrastructure and regulatory pathway design vary sharply by disease category, with oncology commanding accelerated review frameworks and specialized site networks.
- Oncology:Precision medicine applications including antibody-drug conjugates, bispecific antibodies, and cell therapies concentrate demand in China and South Korea, where NMPA and MFDS have implemented conditional approval pathways based on surrogate endpoints.
- Neurology:Blood-brain barrier penetration challenges and long trial durations constrain development velocity for Alzheimer's and Parkinson's programs.
- Cardiovascular:Large outcome trials require extensive site networks across India and Southeast Asia for patient recruitment.
- Infectious Diseases:Pandemic preparedness investments and antimicrobial resistance programs drive vaccine and novel antibiotic development, with India's CDSCO aligning bioequivalence standards with WHO prequalification to expand export access for generic antiretrovirals.
Oncology sits at the top of the volume ranking, with infectious disease applications climbing fastest through pandemic response infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bioprocessing talent concentrates in Singapore and South Korea, where mammalian cell culture expertise anchors large-scale antibody manufacturing. China's regulatory reformers and India's formulation chemists complete the regional capability matrix.
China
Oncology drug developers and gene therapy innovators drive NMPA submission volumes through conditional approval pathways for breakthrough therapies. The regulator's surrogate endpoint framework compresses commercialization timelines for domestic innovators. Shanghai and Suzhou biotech clusters host integrated discovery-to-manufacturing campuses serving multinational joint ventures.
India
API manufacturers and generic formulation exporters capitalize on PLI scheme incentives for greenfield active pharmaceutical ingredient investments. CDSCO's WHO prequalification alignment for bioequivalence standards unlocks institutional procurement access across Africa and Southeast Asia. Hyderabad and Ahmedabad chemistry hubs upgrade from batch processing to continuous manufacturing for export-oriented quality consistency.
South Korea
Antibody-drug conjugate specialists and large-scale biologics producers demand dedicated mammalian cell culture capacity for precision oncology programs. MFDS enforces GMP-Biosafety facility certification requirements that extend capital deployment timelines and raise barrier-to-entry thresholds. Incheon and Songdo bioclusters concentrate bioconjugation expertise and viral vector development capabilities.
Singapore
Multi-product contract manufacturers and sterile fill-finish operators serve Asia-Pacific distribution networks through advanced logistics infrastructure. The national pharmaceutical regulator maintains harmonized standards with US FDA and EMA for seamless technology transfer. Tuas Biomedical Park anchors regional biologics manufacturing with single-use bioreactor systems enabling rapid product changeovers.
Australia
Phase I oncology units and early-phase clinical trial infrastructure attract sponsor investment through streamlined TGA notification pathways and experienced investigator networks. The Therapeutic Goods Administration's priority review designation accelerates access schemes for innovative therapies. Melbourne and Sydney research precincts concentrate hospital-sponsored personalized medicine compounding and investigator-initiated trial manufacturing.
Asia Pacific Drug Development Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia Pacific drug development landscape. The market structure concentrates value capture among integrated contract organizations with mammalian cell culture expertise, while fragmented small-molecule chemistry providers face margin compression. Three archetypes dominate: full-service discovery-to-commercialization platforms, specialized biologics manufacturers, and regional generic formulation exporters. Capacity expansion and regulatory submission support represent the dominant competitive moves for securing long-term manufacturing agreements.
Within the integrated platform tier, WuXi AppTec exemplifies end-to-end service architecture spanning multiple therapeutic modalities. Samsung Biologics anchors the large-scale biologics manufacturing segment through dedicated mammalian cell culture infrastructure. WuXi Biologics occupies a specialized position in complex antibody formats including antibody-drug conjugates and bispecific constructs. CELLTRION INC represents the biosimilar-focused archetype with vertically controlled development and manufacturing capabilities.
| Leading Market Players |
|---|
| WuXi AppTec |
| Samsung Biologics |
| WuXi Biologics |
| CELLTRION INC |
| Takeda Pharmaceutical Company |
| Novartis AG |
| Pfizer Inc |
| PT Kalbe Farma Tbk. |
| Biocon |
| Others |
Pricing and Supply Chain Analysis
Vertical integration into mammalian cell culture infrastructure anchors premium pricing power for biologics contract manufacturers while exposing small-molecule chemistry providers to commodity margin compression. WuXi AppTec and Samsung Biologics leverage captive bioconjugation expertise to command project-based premiums, whereas Indian API exporters face transactional spot-market dynamics under PLI scheme competition.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated discovery-to-commercialization contracts from transactional small-molecule manufacturing engagements. Project-based pricing dominates biologics development, with antibody-drug conjugate programs commanding premiums tied to GMP-Biosafety certification tiers and dedicated capacity commitments. Cost compression in small-molecule APIs intensifies as continuous manufacturing adoption spreads among Hyderabad and Ahmedabad exporters. Emerging biotech sponsors exhibit highest price sensitivity, seeking milestone-based structures, while multinational pharmaceutical companies prioritize technical capability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from MFDS and NMPA-qualified sponsors mandate multi-supplier qualification for single-use bioprocessing bags and specialized polymer assemblies. Manufacturing inputs draw from China, South Korea, and Singapore for mammalian cell culture media, chromatography resins, and sterile fill-finish components. Single-source vulnerability concentrates in North American and European polymer supply chains for bioprocessing consumables. Distribution runs through Singapore's Tuas Biomedical Park and South Korea's Incheon bioclusters for Asia-Pacific regional fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
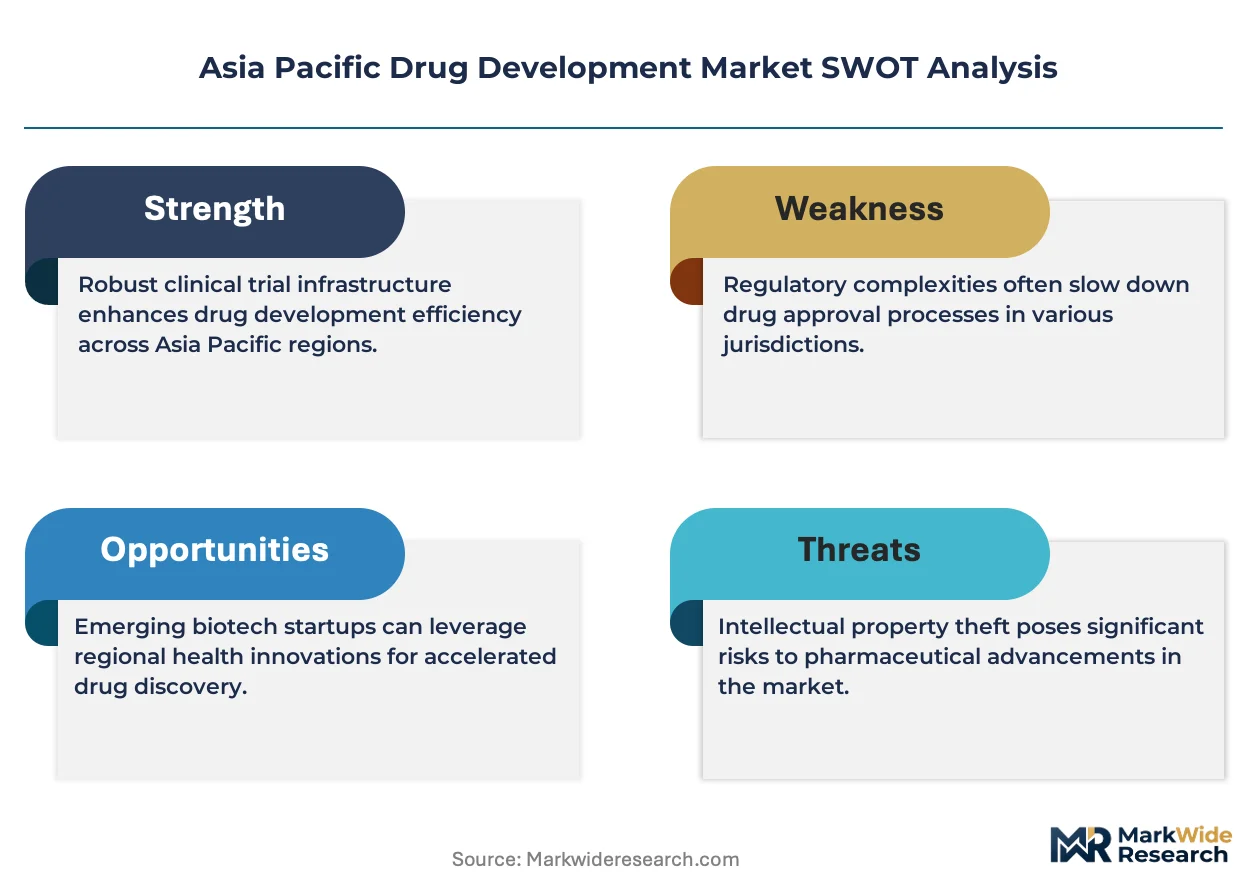
This market offers margin-expansion pathways through biologics capability premiums displacing commoditized small-molecule chemistry, with gene therapy viral vector scarcity supporting sustained pricing power.
For Market Incumbents: Deepen mammalian cell culture capacity in Songdo and Tuas Biomedical Park to defend against emerging bioconjugation specialists. Secure NMPA and MFDS dual-certification for facilities to capture multinational sponsor demand for accelerated oncology pathways. Lock in long-term viral vector supply agreements before AAV manufacturing scarcity intensifies queue bottlenecks. For New Entrants and Emerging Players: Enter via Vietnam's Phase II-III clinical trial expansion, where underserved oncology patient populations and improving ASEAN regulatory alignment attract sponsor investment previously concentrated in China. Target academic institute technology transfer partnerships as the fastest-growing client segment. Position around CRISPR-edited CHO cell line development expertise to address capability gaps at mid-tier contract research organizations. For Investors and Strategic Acquirers: Roll-up economics work for specialized bioconjugation and viral vector development platforms because MFDS GMP-Biosafety compliance extends capital deployment timelines and raises barrier-to-entry thresholds for new manufacturers. Target mid-cap CDMOs with differentiated antibody-drug conjugate capabilities over the medium-term horizon. Watch NMPA conditional approval pathway expansion as the signal indicating accelerated revenue realization timelines for domestic innovators and multinational joint ventures.| Strategic Initiative | Industry Significance |
|---|---|
| Mammalian Cell Culture Capacity Expansion | Samsung Biologics and WuXi Biologics anchor large-scale antibody manufacturing through dedicated facilities in Incheon and Suzhou. |
| NMPA Conditional Approval Pathway Utilization | Oncology developers compress commercialization timelines by front-loading China-specific clinical trial investments and localized regulatory affairs capabilities. |
| Continuous Manufacturing Adoption | Indian API exporters in Hyderabad upgrade from batch processing to flow chemistry for export-oriented quality consistency advantages. |
| Viral Vector Manufacturing Partnership | Gene therapy programs address AAV and lentiviral production bottlenecks through dedicated capacity commitments with specialized contract manufacturers. |
| CDSCO WHO Prequalification Alignment | Generic drug exporters unlock institutional procurement access across Africa and Southeast Asia through bioequivalence standard harmonization. |
Research Methodology
Coverage spans China, India, South Korea, Singapore, and Australia, with primary inputs from each market cluster combining interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and hospital formulary directors. Secondary validation draws from NMPA filings, MFDS GMP certifications, ClinicalTrials.gov records, and CDSCO bioequivalence submissions. Bottom-up facility capacity assessments and top-down therapeutic area demand projections enable triangulation across modeling approaches.
Granularity-level framing models biologics, small-molecule, and gene therapy modalities separately, with further disaggregation by delivery mode, end-user organization scale, and therapy area regulatory cluster across the projection horizon. CAGRs derive from segment-specific demand curves and capacity expansion schedules. Forecast inputs incorporate PLI scheme incentive trajectories, NMPA review timeline compression effects, and viral vector manufacturing queue dynamics.
Inputs from NMPA, MFDS, and CDSCO regulatory databases were available through the study window; gaps in real-time viral vector capacity utilization data introduce uncertainty bands around gene therapy segment projections. Deviation in AAV manufacturing yield improvements or NMPA conditional approval scope expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market