
 Polyp Trap Devices Market | 2026-2036
Polyp Trap Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Polyp Trap Devices Market Analytics
Chinese medical device manufacturers is expanding production capacity for disposable polyp traps to serve Asia-Pacific procurement networks. Boston Scientific leverages integrated endoscopy portfolios to anchor hospital system contracts across North American markets. Olympus sustains technology leadership in automated retrieval systems through proprietary channel designs. Exact Sciences competes in clinical research segments where pathology workflow integration commands premium positioning.
Polyp trap devices are containment accessories used during endoscopic procedures to capture and transport excised colorectal tissue specimens without contamination; most disposable variants employ medical-grade polycarbonate or polypropylene housings with 40-100 micron filtration mesh to preserve cellular architecture for histopathological analysis. The primary commercial purpose centers on reducing specimen loss rates during colonoscopy while standardizing chain-of-custody protocols between gastroenterology suites and pathology laboratories. Automated systems are capturing disproportionate investment as hospitals prioritize throughput optimization and nurse labor reduction. Disposable traps dominate volume while reusable metal designs retain footholds in cost-constrained European clinic settings. Silicone composite materials are gaining fastest in premium segments where thermal stability and repeated sterilization cycles justify higher per-unit expenditure.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and commercial launch sequencing for manufacturers targeting dual-continent distribution. The EPA regulates ethylene oxide sterilization residues that influence material selection and packaging design for disposable trap imports into the United States. ISO 13485 quality management certification functions as a baseline procurement qualifier for hospital group purchasing organizations across OECD markets. Stakeholders must monitor evolving single-use plastics legislation in Germany and France that could force material substitutions or extended producer responsibility schemes before the forecast horizon concludes.
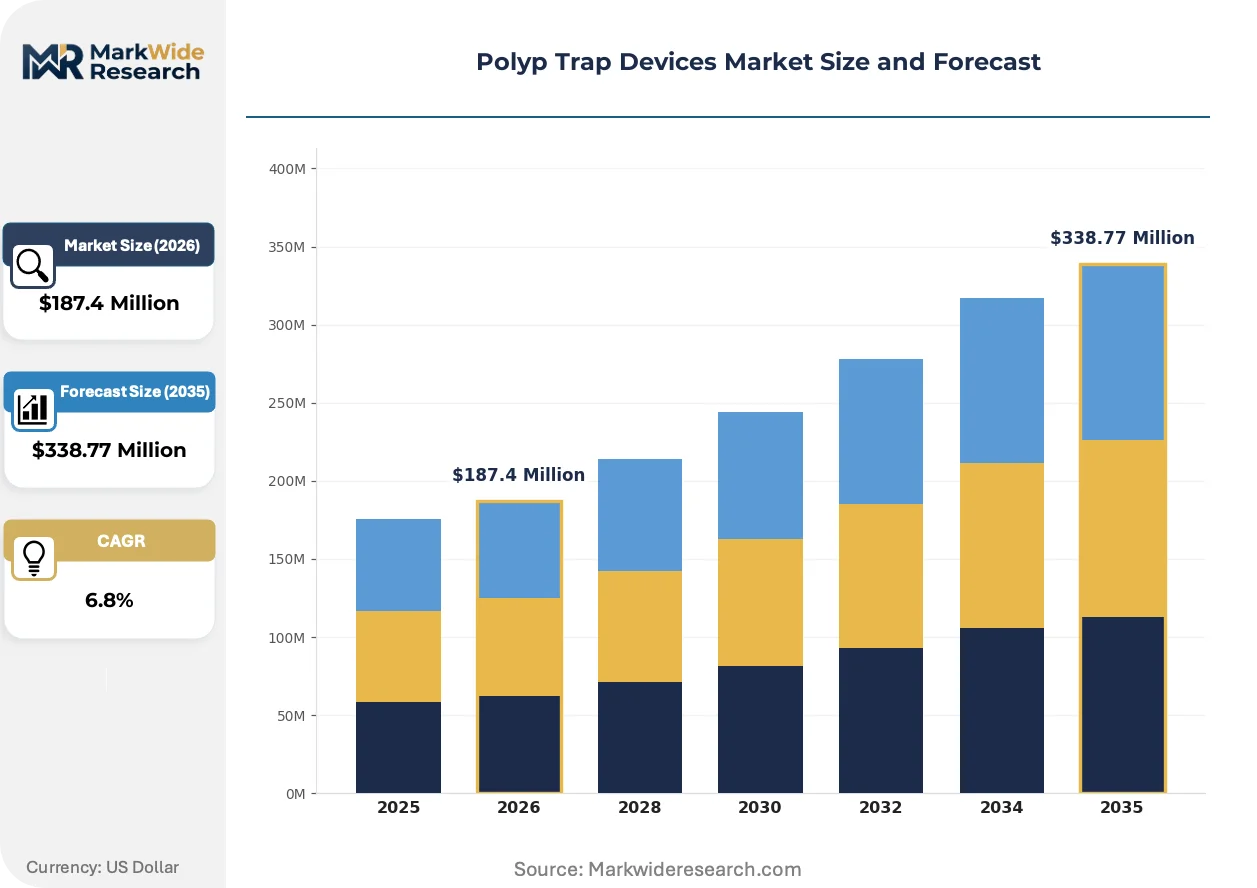
Market Dynamics
Automated polyp retrieval systems are capturing disproportionate capital allocation as hospitals prioritize throughput optimization and nurse labor reduction, fundamentally restructuring procurement criteria away from unit cost toward total cost of ownership metrics.
Growth Catalysts
- FDA 510(k) clearance streamlining:Accelerated regulatory pathways for predicate device submissions reduce commercial launch timelines for automated retrieval innovations targeting integrated endoscopy suites.
- Polycarbonate filtration mesh:Medical-grade polymer housings with 40-100 micron precision filtration preserve cellular architecture for histopathological analysis, elevating diagnostic reliability standards.
- United States colonoscopy volume concentration:Elevated screening compliance rates and pathology integration mandates drive replacement demand for legacy manual trap systems.
Market Restraints
- Ethylene oxide sterilization residue compliance:EPA regulatory thresholds for EtO residuals constrain material selection and packaging design for disposable trap imports into the United States.
- Single-use plastics legislation:Extended producer responsibility schemes advancing in Germany and France threaten polycarbonate and polypropylene demand before the forecast horizon concludes.
- Reusable metal system retention:Cost-constrained European clinic settings maintain installed bases of sterilizable stainless steel designs, compressing disposable penetration rates.
Strategic Opportunities
- Silicone composite thermal stability:Premium segments reward materials sustaining repeated sterilization cycles, justifying higher per-unit expenditure in academic medical centers.
- EMA Medical Device Regulation harmonization:Conformity assessment alignment with FDA pathways enables dual-continent distribution scale for manufacturers achieving ISO 13485 certification.
- Japan pathology workflow integration:PMDA-registered automated systems command premium positioning where histopathological throughput requirements exceed manual processing capacity.
Industry Challenges
- ISO 13485 quality management certification:Baseline procurement qualifiers for OECD hospital group purchasing organizations demand documented corrective action systems and supplier audit trails.
- Legacy endoscopy channel compatibility:Proprietary automated retrieval designs require integration with existing instrument portfolios, creating switching friction for non-integrated vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyp Trap Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Traps, Reusable Traps, Automated Systems, Manual Systems End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Laboratories Material: Plastic, Metal, Composite, Silicone Application: Gastroenterology, Surgical Procedures, Pathology, Clinical Research |
| Companies Covered | Boston Scientific, Olympus, Exact Sciences, Ruhof, Zhejiang Chuangxiang Medical Technology, GA Health, STERIS, Zutron Medical, Key Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyp Trap Devices Market Evolving Landscape
Material science advances and regulatory harmonization pressures are converging to reshape product development roadmaps, with automation and sustainability emerging as the dominant vectors of competitive differentiation.
Silicone composite trap housings are expanding into premium hospital segments where thermal stability during repeated autoclave cycles justifies 40-60% per-unit premiums over standard polycarbonate alternatives. Academic medical centers in Germany and Japan lead adoption, prioritizing total cost of ownership over acquisition price. This material migration is compressing addressable market share for conventional polymer suppliers while elevating certification requirements for biocompatibility documentation.
EMA Medical Device Regulation conformity assessments are extending product development timelines by 8-14 months for manufacturers pursuing dual-continent distribution, forcing sequential rather than parallel launch strategies. The regulation's emphasis on clinical evidence generation disproportionately burdens automated retrieval system innovators relative to predicate manual devices. German notified bodies report 30% application backlogs, delaying market access for second-tier manufacturers.
Hospital procurement committees are consolidating vendor relationships around integrated endoscopy portfolios, unbundling standalone polyp trap purchases from system-wide contracts. This concentration pattern disadvantages pure-play trap manufacturers while rewarding diversified suppliers offering channel-compatible automation. The shift is most visible in United States health system acquisitions, where standardization mandates override individual physician preference for disposable versus reusable formats.
Polyp Trap Devices Market Segmentation
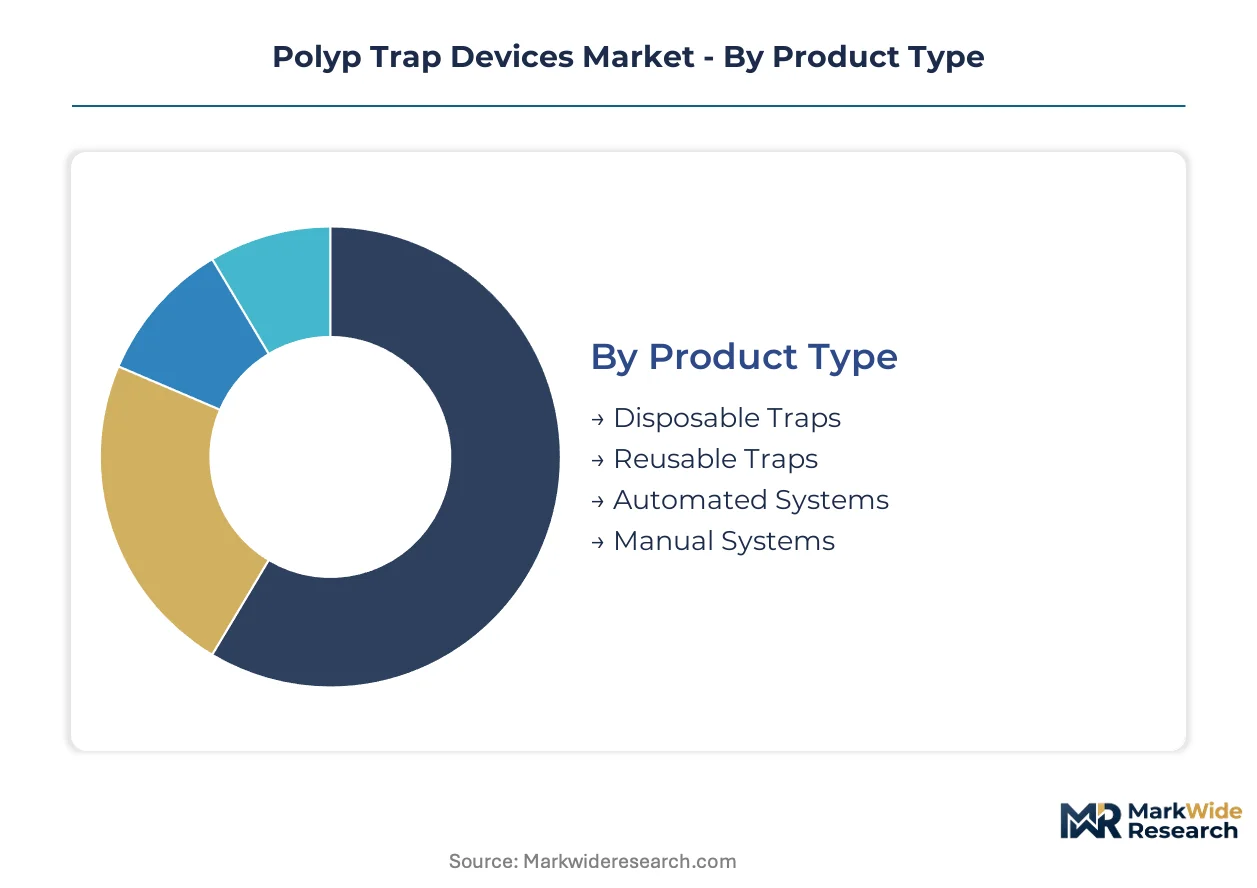
Polyp trap device segmentation reveals divergent capital requirements across manufacturing technologies and procurement channels. Automated systems demand substantial upfront R&D investment while disposable variants operate on high-volume, low-margin production economics.
Product Type:
Automated retrieval systems require the heaviest capital deployment for precision engineering and software integration, whereas manual disposable traps minimize fixed asset intensity through contract manufacturing networks.
- Disposable Traps:Medical-grade polycarbonate housings with 40-100 micron filtration mesh dominate procurement volumes in United States hospital systems where single-use protocols reduce cross-contamination liability. Gastroenterology suites in Germany and Japan prioritize these variants for throughput optimization despite higher per-procedure costs.
- Automated Systems:Proprietary channel designs integrate with endoscopy towers to capture excised tissue without nurse intervention, commanding premium positioning in academic medical centers. Demand concentrates in the United States where labor cost reduction justifies capital expenditure amid staffing shortages.
- Reusable Traps:Stainless steel designs retain footholds in European cost-constrained clinics with autoclave infrastructure.
- Manual Systems:Basic retrieval accessories serve pathology laboratories with limited procedure volumes.
Disposable traps absorb the bulk of installed capacity; automated systems are expanding most quickly.
End User:
Hospital procurement committees command the largest aggregate spending power, while ambulatory surgical centers represent the leanest operational model with minimal inventory carrying capacity.
- Hospitals:Integrated endoscopy suites drive replacement demand for legacy manual systems as FDA sterilization standards tighten and pathology integration mandates expand. United States health systems consolidate vendor relationships around automated retrieval portfolios that reduce nurse labor per colonoscopy.
- Ambulatory Surgical Centers:High-throughput outpatient facilities in Germany and Japan favor disposable traps for rapid turnover between procedures, prioritizing supply chain simplicity over total cost of ownership metrics.
- Clinics:Cost-constrained European settings maintain reusable metal trap bases.
- Research Laboratories:Clinical research segments demand precision specimen handling for histopathological studies.
Hospitals command the dominant revenue share; ambulatory surgical centers are climbing the fastest.
Material:
Silicone composite production requires specialized compounding equipment and biocompatibility certification, whereas commodity polymer processing operates on standardized injection molding assets.
- Silicone:Thermal stability during repeated autoclave cycles justifies 40-60% per-unit premiums in academic medical centers across Germany and Japan. These materials elevate certification requirements for biocompatibility documentation under EMA Medical Device Regulation.
- Plastic:Polycarbonate and polypropylene housings serve high-volume disposable segments where EPA ethylene oxide sterilization residue thresholds constrain import logistics into the United States.
- Metal:Stainless steel retains European clinic penetration amid sterilization infrastructure.
- Composite:Hybrid material formulations target niche thermal performance requirements.
Plastic materials dominate unit volume; silicone composites are gaining share fastest.
Application:
Gastroenterology procedures generate the most predictable recurring demand, while clinical research applications require the most specialized regulatory documentation.
- Gastroenterology:Colonoscopy volume concentration in the United States, Germany, and Japan drives replacement cycles for legacy trap systems. Screening compliance mandates and pathology integration requirements standardize chain-of-custody protocols between suites and laboratories.
- Pathology:Histopathological analysis demands 40-100 micron precision filtration to preserve cellular architecture for diagnostic reliability. Japanese laboratories lead automated system adoption where throughput requirements exceed manual processing capacity.
- Surgical Procedures:General endoscopic applications extend trap utility beyond colorectal specialization.
- Clinical Research:Exact Sciences competes in segments where workflow integration commands premium positioning.
Gastroenterology anchors the installed base; pathology applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polycarbonate feedstock concentration in the United States anchors procurement networks for disposable polyp trap manufacturing. Germany and Japan maintain parallel demand centers where pathology integration mandates reshape endoscopy suite capital allocation. Chinese manufacturers leverage regional polymer supply chains to serve Asia-Pacific distribution networks.
United States
FDA 510(k) clearance pathways accelerate commercial launch timelines for automated retrieval systems targeting integrated endoscopy suites. EPA ethylene oxide sterilization residue thresholds constrain material selection and packaging design for disposable trap imports. Boston Scientific anchors hospital system contracts across North American markets through integrated endoscopy portfolios.
Germany
EMA Medical Device Regulation conformity assessments extend product development timelines by 8-14 months for manufacturers pursuing dual-continent distribution. Single-use plastics legislation threatens polycarbonate and polypropylene demand before the forecast horizon concludes. Academic medical centers in Bavaria and North Rhine-Westphalia lead silicone composite adoption where thermal stability justifies 40-60% per-unit premiums.
Japan
PMDA-registered automated systems command premium positioning where histopathological throughput requirements exceed manual processing capacity. METI industrial standards shape quality management certification requirements for hospital group purchasing organization procurement. Olympus sustains technology leadership in automated retrieval systems through proprietary channel designs concentrated in Kanto and Kansai regions.
China
NMPA medical device registration requirements govern commercial launch sequencing for domestic and imported polyp trap systems. MIIT industrial policy supports medical-grade polymer production capacity expansion in Yangtze River Delta manufacturing clusters. Zhejiang Chuangxiang Medical Technology exemplifies regional fabricators scaling disposable trap output for Asia-Pacific procurement networks.
Polyp Trap Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automated retrieval specialization and silicone composite material differentiation. The vendor base stratifies across three tiers: diversified endoscopy system suppliers with integrated portfolios, pure-play disposable trap manufacturers serving high-volume contract channels, and regional fabricators leveraging proximity to polymer supply chains. Dominant competitive moves include portfolio diversification around automation capabilities and strategic partnerships with pathology workflow integrators.
Among diversified medical technology suppliers, Boston Scientific and Olympus exemplify integrated portfolio strategies that anchor hospital system contracts through endoscopy tower compatibility. Exact Sciences occupies a position within clinical research segments where pathology workflow integration commands premium positioning. These three entities represent distinct archetypes: the diversified system supplier, the technology-integrated endoscopy leader, and the precision diagnostics specialist.
| Leading Market Players |
|---|
| Boston Scientific |
| Olympus |
| Exact Sciences |
| Ruhof |
| Zhejiang Chuangxiang Medical Technology |
| GA Health |
| STERIS |
| Zutron Medical |
| Key Surgical |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between silicone composite and commodity polymer tiers manifests in both procurement premiums and raw material sourcing strategies, with EMA Medical Device Regulation compliance costs feeding directly into supplier qualification timelines and hospital GPO contract structures.
Pricing Analysis
Service-bundling separates automated retrieval system vendors from standalone disposable trap suppliers, with integrated endoscopy tower compatibility commanding inclusion of installation support and preventive maintenance in capital contracts. Price differentiation hinges on FDA 510(k) predicate pathway speed and ISO 13485 certification depth, with academic medical centers showing lowest sensitivity due to total cost of ownership framing while European clinics exhibit highest price elasticity amid reusable metal trap retention. Cost compression in polycarbonate disposable segments is intensifying as Chinese manufacturers expand Yangtze River Delta production capacity.
Supply Chain Analysis
Medical-grade polycarbonate feedstock rests on United States and German petrochemical complexes, with filtration mesh precision manufacturing anchored in Japanese specialty textile producers and silicone compounding concentrated among Bavarian and Kanto region suppliers. Raw material dependencies include ethylene oxide sterilization services, medical-grade polymer resins, and precision-woven filtration substrates. Single-source vulnerability permeates the 40-100 micron mesh segment where Japanese producers dominate technical specifications. Distribution runs through hospital group purchasing organization contracts in North America and tender-based procurement networks in European Union member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized silicone compounding capacity constraints prop pricing premiums for thermal-stable trap housings, with EMA notified body backlogs extending supplier qualification timelines and compressing available certified manufacturing base.
For Market Incumbents: Extend automated retrieval software development roadmaps to deepen endoscopy tower integration moats against emerging Asian hardware competitors. Anchor hospital system contracts through pathology workflow integration investments that raise switching costs. Prioritize backward integration into medical-grade polymer compounding to secure supply continuity amid German single-use plastics legislative uncertainty.
For New Entrants and Emerging Players: The 40-60% per-unit premium gap between silicone composite and standard polycarbonate tiers opens white-space targeting at mid-market ambulatory surgical centers in Japan and Germany seeking thermal stability without academic medical center procurement budgets. Unbundled disposable trap supply to Asia-Pacific distribution networks offers fastest penetration. Pursue NMPA registration pathways to leverage Chinese manufacturing scale for regional procurement network access.
For Investors and Strategic Acquirers: Re-rating potential sits with automated retrieval system specialists given FDA 510(k) clearance streamlining and hospital labor reduction mandates accelerating replacement cycles. Long-term viability favors vendors with dual-continent regulatory infrastructure and proprietary channel designs rather than commodity polymer trap fabricators. Watch EMA Medical Device Regulation application backlog resolution as inflection indicator for second-tier manufacturer market access timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened predicate device pathways reduce commercial launch timelines for automated retrieval innovations targeting integrated endoscopy suites. |
| EMA Medical Device Regulation Conformity Investment | Notified body relationship depth determines dual-continent distribution scale for manufacturers competing in German hospital procurement networks. |
| Hospital System Partnership Development | GPO contract consolidation around integrated portfolios disadvantages standalone trap vendors while rewarding diversified endoscopy suppliers. |
| Silicone Composite Material Certification | Biocompatibility documentation depth under EMA MDR elevates barriers for commodity polymer suppliers targeting premium academic medical center segments. |
| Pathology Workflow Integration Strategy | Software companion development for histopathological throughput optimization commands premium positioning in Japanese laboratory automation markets. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, and hospital group purchasing organization contract filings, complemented by interviews with biomedical engineers, gastroenterology suite managers, GPO contracts managers, and pathology laboratory directors. Secondary validation drew from EPA ethylene oxide sterilization compliance reports, ISO 13485 certification registries, and customs trade data for medical-grade polymer imports. Bottom-up and top-down triangulation reconciled manufacturer shipment data with hospital procurement expenditure patterns.
Segment-level projections across product type, end user, material, and application dimensions were generated through demand-side modeling of colonoscopy volume trends and supply-side capacity assessments of polycarbonate and silicone compounding infrastructure. CAGRs were derived from regression analysis of historical penetration rates and replacement cycle dynamics, with inputs including FDA regulatory pathway velocity, EMA notified body processing times, and Japanese PMDA registration timelines for automated retrieval systems.
Inputs from primary interviews and regulatory filing databases were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding screening compliance trajectories and pathology integration mandate adoption schedules. Supply chain disruption risks from German single-use plastics legislation and EPA ethylene oxide residue threshold adjustments warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Autosamplers Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Osteotomy Plates Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Suction Catheters Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Asia-Pacific Medical Suction Device Market