
 Chemotherapy Infusion Pumps Market | 2026-2036
Chemotherapy Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Infusion Pumps Market Analysis
Germany is reshaping European supply dynamics through expanded precision manufacturing capacity for infusion therapy devices. B. Braun Melsungen AG leverages its vertically integrated sterilization and polymer molding operations to sustain cost leadership across programmable pump lines. Fresenius Kabi AG anchors its position through hospital-centric distribution networks that dominate oncology ward procurement in Western Europe. Baxter International Inc. competes on ambulatory platform specialization, particularly in elastomeric pump formats for home chemotherapy administration.
Chemotherapy infusion pumps are electromechanical or pressure-driven devices that deliver cytotoxic agents, biologics, and supportive medications at controlled flow rates ranging from 0.1 mL/hour to 999 mL/hour, with occlusion pressure detection and air-in-line sensors as standard safety architecture. Their primary commercial purpose is to enable precise, repeatable drug delivery in oncology settings where dosing accuracy directly correlates with therapeutic efficacy and patient safety outcomes. Smart pump technology leads the technology segment through integrated dose error reduction software and wireless connectivity to electronic health records, while portable pumps represent the fastest-expanding category as home-based chemotherapy protocols gain clinical acceptance. The end-user landscape tilts toward oncology clinics, where margin pools concentrate due to higher reimbursement rates for supervised infusion services compared to general hospital wards.
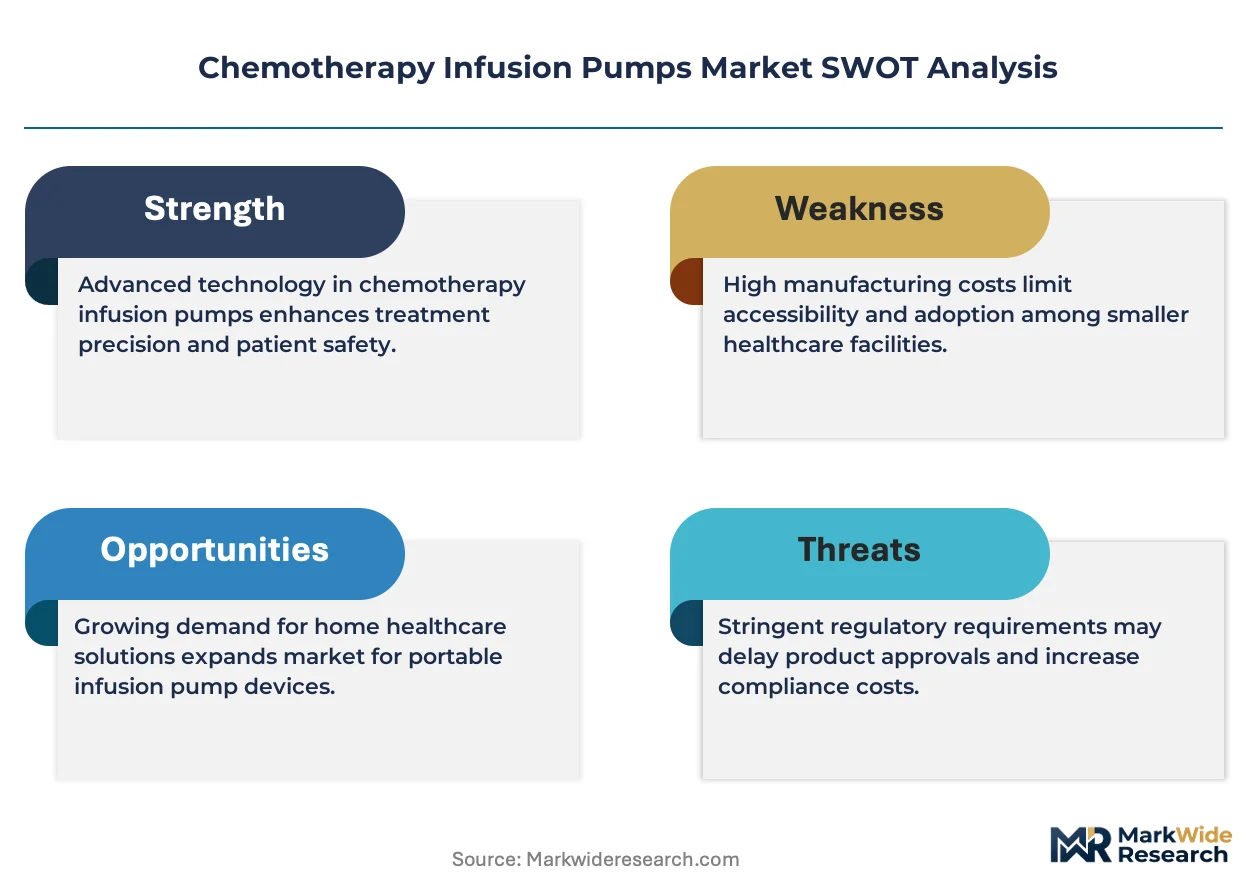
The FDA's infusion pump guidance documents and the EU MDR framework enforce escalating software validation and post-market surveillance requirements that elevate compliance costs for manufacturers. Japan's PMDA maintains distinct electromagnetic compatibility and biocompatibility testing protocols that create additional market access barriers for non-domestic suppliers. Stakeholders must monitor evolving cybersecurity standards for connected pump ecosystems as healthcare ransomware incidents intensify regulatory scrutiny of networked medical devices.
Market Dynamics
Smart pump ecosystems with dose error reduction software and wireless EHR connectivity are compressing replacement cycles and redrawing competitive boundaries between programmable and elastomeric device manufacturers.
Growth Catalysts
- Outpatient chemotherapy infrastructure:Oncology clinics in the United States, Germany, and Japan are expanding ambulatory infusion capacity to reduce hospital admission costs and improve patient throughput.
- FDA infusion pump guidance updates:Enhanced software validation requirements are accelerating obsolescence of legacy mechanical pumps and forcing upgrades to connected platforms with integrated safety architecture.
- Home-based chemotherapy protocols:Portable elastomeric pumps are gaining clinical acceptance for cytotoxic agent delivery outside supervised settings, extending addressable patient populations.
Market Restraints
- Polymer and electronic component cost volatility:Specialized biocompatible plastics and precision flow sensors face input price instability from concentrated Asian material suppliers.
- EU MDR recertification timelines:Extended conformity assessment procedures for Class IIb medical devices are freezing product launches and straining manufacturer cash flows.
- Technical limitation in occlusion detection:Current pressure sensing algorithms generate false alarms in low-flow chemotherapy applications, creating clinician workflow friction and device abandonment.
Strategic Opportunities
- Japan's PMDA electromagnetic compatibility pathway:Non-domestic manufacturers that invest in localized testing facilities can capture share in a market with distinct biocompatibility protocols and limited foreign penetration.
- Cybersecurity standards for connected pumps:Healthcare ransomware incidents are intensifying regulatory scrutiny of networked medical devices, creating first-mover advantage for vendors with hardened wireless architectures.
- Subscription-based device-as-a-service models:Hospital procurement departments are piloting operational expenditure structures that bundle hardware, maintenance, and software updates into per-infusion fees.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of fluid dynamics, embedded systems programming, and oncology clinical workflow expertise remains difficult to source for pump development teams.
- Legacy EHR integration complexity:Smart pump wireless connectivity requires costly customization to interface with heterogeneous hospital information systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Infusion Pumps Market |
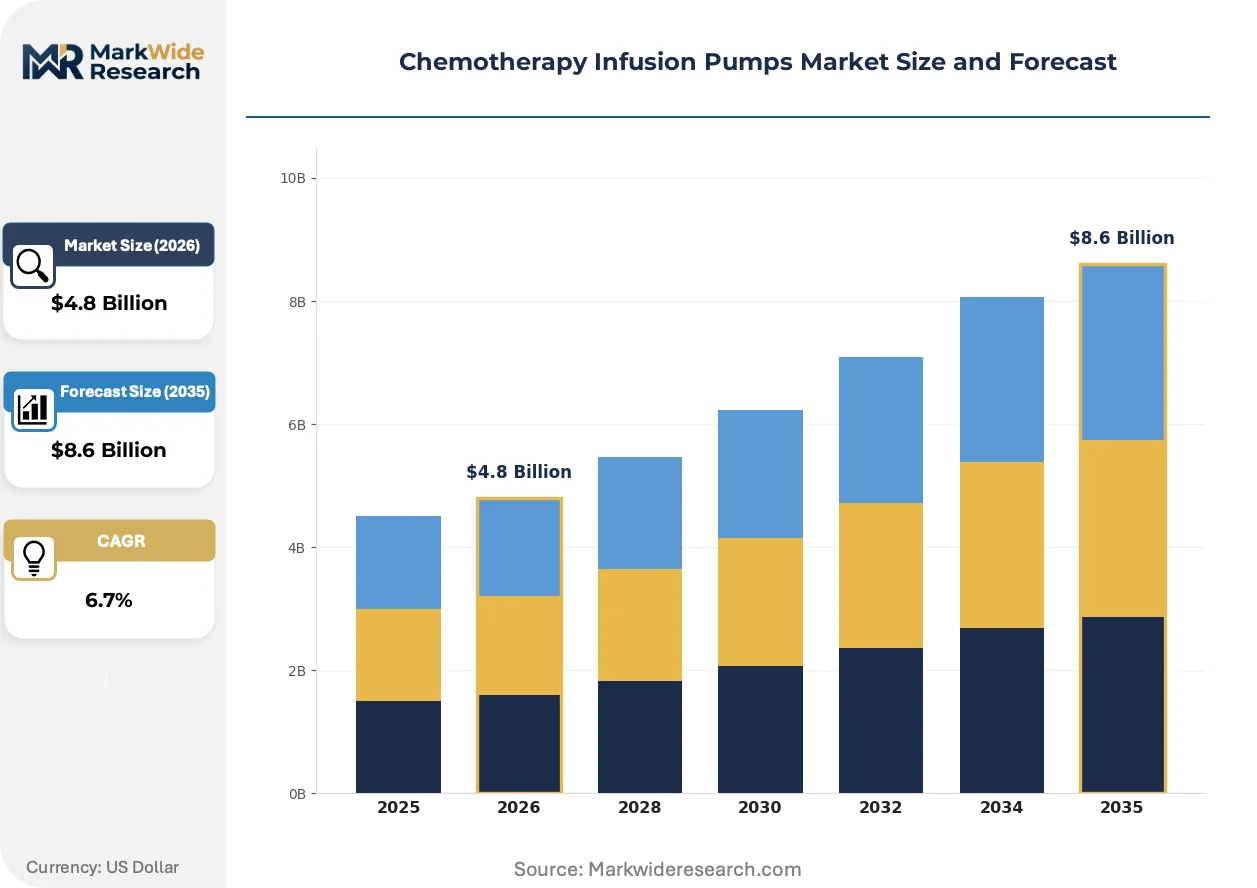
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Elastomeric Pumps, Disposable Pumps End User: Hospitals, Oncology Clinics, Home Care Settings, Ambulatory Surgical Centers Technology: Smart Pumps, Programmable Pumps, Portable Pumps, Gravity Pumps Application: Chemotherapy, Pain Management, Palliative Care, Nutritional Support |
| Companies Covered | B. Braun Melsungen AG, Baxter International Inc., ICU Medical, Inc., Medtronic Plc, Fresenius Kabi AG, BD, Terumo Corporation, Smiths Medical, IRadimed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Infusion Pumps Market Emerging Trajectories
Device intelligence and care setting migration are converging to redefine how cytotoxic therapy is delivered, monitored, and reimbursed across institutional and domestic environments.
Closed-loop infusion systems with real-time drug library verification and automated flow adjustment are rendering obsolete manual programming workflows in high-volume oncology wards. Academic medical centers in the United States are deploying these platforms to reduce medication error liability. The technology is compressing training requirements for infusion nursing staff while raising hardware replacement frequency.
EU MDR post-market surveillance mandates now require systematic collection of clinical evidence for legacy pump models still in commercial distribution. Manufacturers must maintain updated technical documentation and periodic safety reports for devices approved under previous directives. Small and mid-size European suppliers without dedicated regulatory affairs infrastructure are exiting product categories rather than absorbing compliance costs.
Hospital procurement departments are consolidating infusion pump purchasing through multi-year enterprise agreements that bundle devices, disposables, and service contracts. Group purchasing organizations are displacing individual ward-level vendor selection in the United States. This concentration is visible most acutely in integrated delivery networks seeking to standardize pump fleets across dozens of affiliated infusion centers.
Chemotherapy Infusion Pumps Market Segmentation
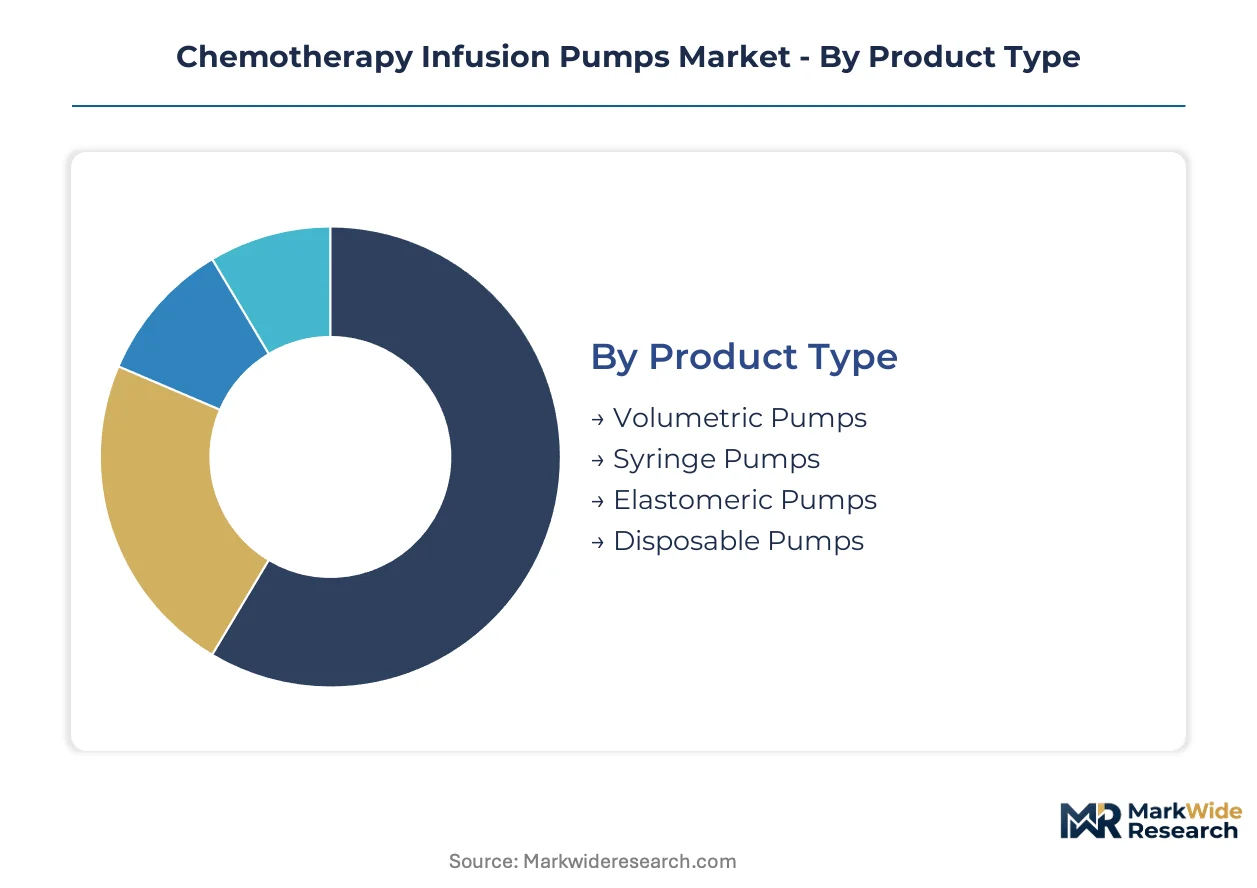
Segmentation in chemotherapy infusion pumps reveals how clinical requirements, care settings, and regulatory constraints fragment procurement patterns. Each dimension carries distinct margin profiles and replacement dynamics that shape vendor strategy.
Product Type:
Use-case spectrum spans high-accuracy institutional delivery to disposable home-based administration, with cost-per-infusion and sterilization burden driving selection.
- Volumetric Pumps:Electromechanical devices with peristaltic or cassette-based flow control deliver large-volume cytotoxic infusions at 1-999 mL/hour. Demand concentrates in United States academic medical centers where FDA-mandated dose error reduction software has become non-negotiable for liability protection. Replacement cycles compress as smart connectivity becomes standard.
- Elastomeric Pumps:Pressure-driven balloon reservoirs deliver medication through calibrated flow restrictors without electronic components. Oncology clinics in Germany and Japan are expanding ambulatory capacity with these devices to enable supervised same-day discharge protocols. Home chemotherapy programs favor this format for its portability and reduced infection risk.
- Syringe Pumps:Precision piston mechanisms handle low-volume, high-potency biologics requiring 0.1-99.9 mL delivery windows.
- Disposable Pumps:Single-use elastomeric or spring-powered units eliminate sterilization logistics for isolated treatment courses.
Established volume favors volumetric platforms; emerging adoption favors elastomeric formats.
End User:
Procurement authority and reimbursement structures create divergent purchasing behaviors across institutional hierarchies.
- Oncology Clinics:Dedicated infusion centers command premium reimbursement rates for supervised chemotherapy administration, justifying higher capital expenditure on connected pump fleets. United States integrated delivery networks are consolidating purchasing through multi-year enterprise agreements that bundle devices, disposables, and service contracts.
- Home Care Settings:Patients receiving cytotoxic therapy outside institutional walls require portable, patient-operable devices with simplified interfaces. Japan's aging demographic and hospital bed constraints are accelerating PMDA approvals for home-use elastomeric systems.
- Hospitals:General wards face capital budget pressure and longer replacement cycles compared to specialized oncology units.
- Ambulatory Surgical Centers:Same-day procedure volumes drive demand for compact, rapid-turnaround infusion platforms.
Margin concentration sits with oncology clinics; patient volume expansion sits with home care channels.
Technology:
Intelligence integration and connectivity architectures are redrawing competitive boundaries between programmable and mechanical platforms.
- Smart Pumps:Integrated dose error reduction software, drug library verification, and wireless EHR connectivity define this segment. FDA guidance on software validation and cybersecurity has elevated these systems to default specification in United States hospital procurement. Academic medical centers deploy closed-loop variants with automated flow adjustment.
- Portable Pumps:Battery-powered or elastomeric formats enable mobility across care settings. Germany's outpatient chemotherapy infrastructure investments are expanding addressable populations for these devices beyond traditional institutional boundaries.
- Programmable Pumps:Microprocessor-controlled flow rates without full drug library integration occupy mid-tier positioning.
- Gravity Pumps:Simple drip-rate controllers persist in cost-constrained environments and palliative care applications.
Regulatory tailwinds favor smart pump penetration; care setting migration favors portable formats.
Application:
Therapeutic intent and agent toxicity profiles dictate safety architecture and monitoring intensity requirements.
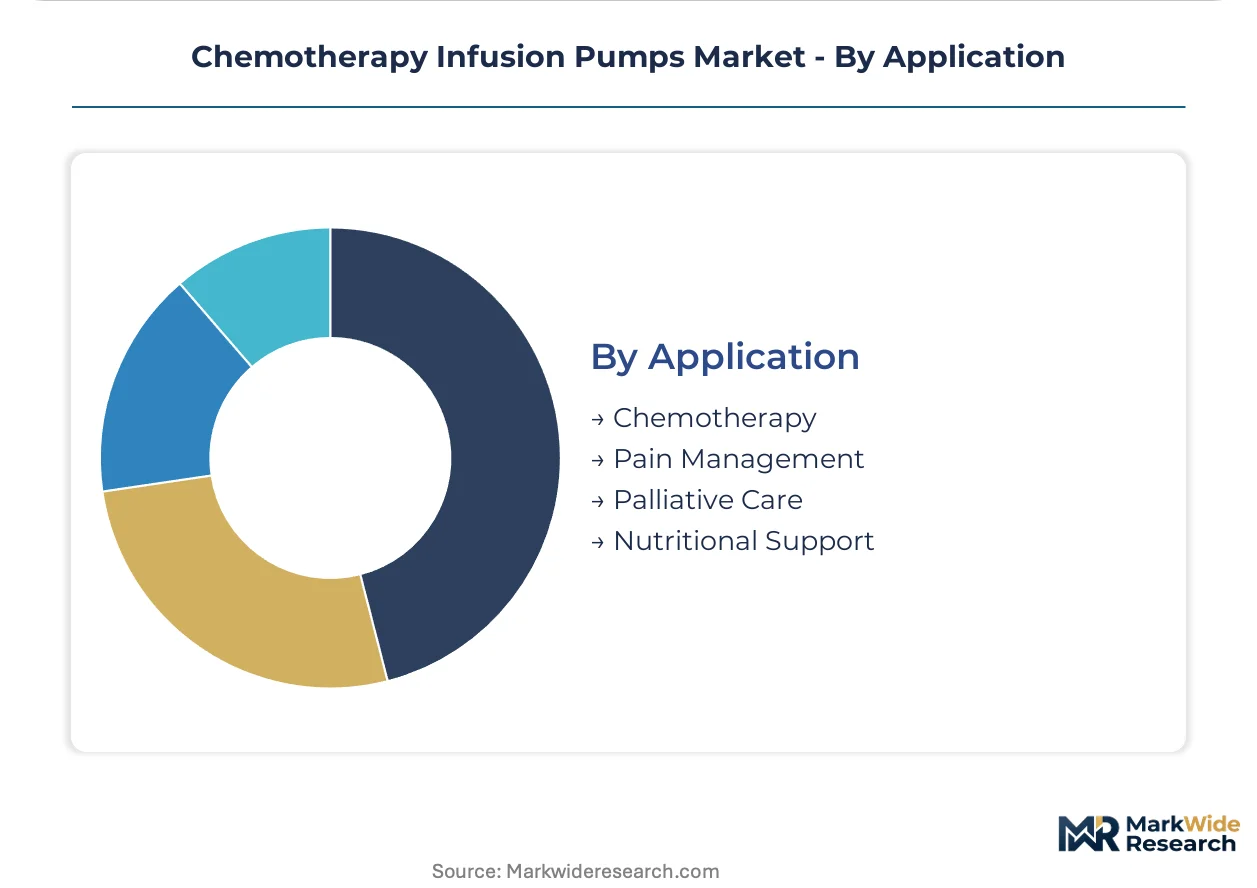
- Chemotherapy:Cytotoxic agent delivery demands occlusion detection, air-in-line sensors, and precise flow control to prevent extravasation and dosing errors. Smart pump ecosystems with wireless connectivity are compressing replacement cycles as FDA and EU MDR tighten software validation benchmarks.
- Pain Management:Patient-controlled analgesia applications require tamper-resistant locking mechanisms and programmable bolus limits.
- Palliative Care:Comfort-focused protocols prioritize simplicity and reliability over advanced connectivity features.
- Nutritional Support:Enteral feeding applications utilize distinct pump architectures with reduced precision requirements compared to intravenous chemotherapy.
Technical complexity peaks with chemotherapy; volume diversification spreads across supportive care applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing for infusion therapy devices clusters in Germany, while oncology infrastructure investments concentrate in the United States and Japan. Regulatory divergence across FDA, EU MDR, and PMDA frameworks fragments market access pathways and elevates compliance costs for multinational suppliers.
United States
Outpatient chemotherapy expansion and integrated delivery network consolidation drive demand for connected pump fleets. FDA's updated infusion pump guidance mandates dose error reduction software and cybersecurity validation for premarket submissions. Academic medical centers in Boston and the Research Triangle deploy closed-loop systems to reduce medication error liability.
Germany
Vertically integrated sterilization and polymer molding operations sustain cost leadership across programmable pump manufacturing. EU MDR recertification timelines strain manufacturer cash flows while tightening quality benchmarks for Class IIb devices. The Melsungen medical technology cluster anchors European supply capacity for precision infusion components.
Japan
Hospital bed constraints and aging demographics accelerate PMDA approvals for home-use elastomeric systems. Distinct electromagnetic compatibility and biocompatibility testing protocols create market access barriers for non-domestic suppliers. Tokyo and Osaka metropolitan areas concentrate oncology clinic infrastructure investments.
China
Domestic manufacturers expand production capacity for cost-competitive volumetric pumps serving tier-2 and tier-3 hospitals. NMPA medical device registration requirements intensify clinical evidence standards for imported infusion systems. The Yangtze River Delta medical device manufacturing corridor scales precision component output.
United Kingdom
NHS procurement consolidation favors multi-year enterprise agreements bundling devices, disposables, and service contracts. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment pathways for UK market access. London and Southeast England oncology centers prioritize smart pump connectivity for electronic health record integration.
Chemotherapy Infusion Pumps Market Vendor Landscape
Vertically integrated European manufacturers and North American platform specialists split the market between cost-engineered volume production and premium connected-device ecosystems. The vendor base concentrates around three strategic archetypes: precision polymer processors with captive sterilization infrastructure, hospital-centric distributors dominating oncology ward procurement, and ambulatory platform developers specializing in portable formats. Competitive intensity manifests through M&A activity targeting regulatory compliance capabilities and strategic partnerships securing elastomeric pump component supply.
Among German-based diversified medical technology groups, B. Braun Melsungen AG and Fresenius Kabi AG exemplify the vertically integrated archetype with in-house polymer molding and sterilization operations. Baxter International Inc. represents the North American ambulatory specialization vector, while BD and Terumo Corporation occupy positions spanning institutional and portable pump categories. ICU Medical, Inc. and Smiths Medical sit within the mid-tier programmable segment, with Medtronic Plc and IRadimed Corporation representing connectivity-focused and MRI-compatible niche positioning respectively.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Baxter International Inc. |
| ICU Medical, Inc. |
| Medtronic Plc |
| Fresenius Kabi AG |
| BD |
| Terumo Corporation |
| Smiths Medical |
| IRadimed Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized biocompatible polymer production concentrates in Germany's Melsungen medical technology cluster, feeding precision molding operations that capture margin pools in oncology clinic procurement channels. This upstream concentration shapes downstream pricing power, as captive sterilization infrastructure insulates integrated manufacturers from spot-market resin volatility while non-integrated competitors absorb cost pass-through pressure.
Pricing Analysis
FDA's updated infusion pump guidance dictates the pricing tier structure across the market, separating smart pump ecosystems with dose error reduction software from legacy mechanical platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and wireless connectivity integration, with academic medical centers least price-sensitive due to liability protection requirements. Cost compression in mid-tier programmable segments is intensifying because EU MDR recertification timelines strain manufacturer cash flows. General hospital wards exhibit highest price sensitivity, prioritizing capital expenditure minimization over connectivity features.
Supply Chain Analysis
Export controls on precision flow sensors and embedded wireless modules limit technology flows to non-domestic suppliers in Japan, fragmenting procurement pathways for connected pump architectures. Manufacturing gravity centers on Germany, China, and the United States, with specialized elastomeric balloon reservoirs drawing from Japanese silicone polymer suppliers and German precision molding equipment. Single-source vulnerability concentrates in Asian biocompatible plastic feedstock channels. Distribution runs through hospital-centric networks in Western Europe and group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemotherapy infusion pump market sits at an inflection where FDA cybersecurity validation requirements and EU MDR software benchmarks are compressing replacement cycles for legacy devices. This regulatory-technological convergence creates asymmetric returns for stakeholders positioned across connected platform development and compliance infrastructure.
For Market Incumbents: Entrench market position through backward integration into polymer sterilization capacity and accelerated FDA submission pathways for closed-loop infusion systems. The threat of non-domestic suppliers capturing Japan's home-use elastomeric segment demands localized PMDA testing facility investment. Certification leverage in wireless drug library verification represents the primary defensive moat.
For New Entrants and Emerging Players: Pursue white-space opportunity in subscription-based device-as-a-service models, where hospital procurement departments pilot operational expenditure structures bundling hardware and maintenance. Japan's aging demographic and hospital bed constraints create the most penetrable geography for portable elastomeric platforms. Go-to-market execution should anchor through oncology clinic partnerships rather than broad hospital system penetration.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale European manufacturers with dormant EU MDR technical documentation that strategic acquirers can activate through regulatory affairs infrastructure investment. Long-term viability across the analysis window hinges on cybersecurity-hardened wireless architectures as ransomware incidents intensify scrutiny of networked medical devices. The signal to watch is PMDA approval velocity for home-use elastomeric systems, indicating care setting migration momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket validation of wireless architectures addresses ransomware vulnerability concerns in hospital procurement. |
| EU MDR Technical Documentation | Systematic clinical evidence collection satisfies post-market surveillance mandates for legacy pump distribution. |
| Hospital System Partnership | Multi-year enterprise agreements with integrated delivery networks consolidate pump fleet standardization. |
| Software Companion Development | Dose error reduction algorithms with EHR integration compress training requirements for infusion nursing staff. |
| Reimbursement Strategy | Outpatient chemotherapy infrastructure investments in Germany and Japan expand ambulatory infusion capacity. |
Methodological Framework
The analysis maps smart pump ecosystems, elastomeric portable platforms, and legacy programmable devices, each validated through biomedical engineers, hospital purchasing committee members, oncology clinic operations directors, and group purchasing organization contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, PMDA approval registries, and hospital procurement contract disclosures. Bottom-up unit economics and top-down market sizing triangulate volume and value estimates.
Assumptions held fixed include regulatory enforcement intensity of FDA software validation guidance and EU MDR recertification timelines, while care setting migration velocity and polymer input cost trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, end-user channel, technology architecture, and application therapeutic intent. CAGRs were derived from installed base replacement dynamics and ambulatory capacity expansion rates, with infusion nursing workforce constraints and EHR integration complexity serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles and medical device reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and supply chain input cost stability. Material shifts in FDA cybersecurity guidance stringency or EU MDR conformity assessment duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Memory Implants Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Human Enhancement Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Global Capnography Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Global Ureteral Stent Market