
 Towing Software Market | 2026-2036
Towing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Towing Software Market Analytics
The fleet management channel is rewriting how towing operators source operational technology. Towbook Management Software leverages cloud-native dispatch architectures to anchor its position among mid-market fleets. ProTow sustains competitive pressure through specialized billing workflows that integrate with insurance claims systems. Beacon Software controls a narrow but defensible niche in municipal contract towing across the southeastern United States.
Towing software encompasses dispatch automation, GPS-enabled fleet tracking, digital impound management, and integrated payment processing designed to coordinate vehicle recovery operations in real time. Cloud-based deployment leads segment momentum as operators abandon legacy on-premises installations to reduce IT overhead and enable mobile driver applications. Tow Management product categories capture the largest current revenue pool, while Fleet Tracking exhibits the fastest structural expansion due to telematics integration and predictive maintenance demand from commercial motor clubs.
The Federal Motor Carrier Safety Administration and state-level public utility commissions shape operational compliance requirements for electronic logging and driver hour tracking across the United States. European operators face CE marking obligations and GDPR constraints on location data retention that elevate platform security standards. Stakeholders must monitor how API interoperability specifications evolve between insurers and roadside assistance networks to preserve integration investments.
Market Dynamics
Cloud-native dispatch architectures are compressing deployment cycles from months to weeks, forcing legacy on-premises vendors to accelerate SaaS migrations or exit mid-market contracts entirely. This technological discontinuity rewrites vendor selection criteria across fleet operators and municipal procurement offices.
Growth Catalysts
- FMCSA ELD Mandate:Federal Motor Carrier Safety Administration electronic logging requirements for commercial towing fleets create baseline demand for integrated telematics platforms that automate driver hour tracking and roadside inspection reporting.
- API-First Insurance Integration:Property-casualty carriers are mandating real-time claims data exchange, pulling dispatch software vendors toward standardized interoperability protocols that reduce manual billing friction.
- Telematics Convergence:Predictive maintenance algorithms from commercial motor clubs are embedding directly into fleet management dashboards, expanding software utility beyond dispatch into asset lifecycle management.
Market Restraints
- Input Cost Volatility:Semiconductor shortages for GPS modules and cellular modems inflate hardware costs for hybrid cloud-edge deployments, squeezing margins for operators serving price-sensitive municipal contracts.
- GDPR Location Retention:European operators face structural compliance costs from GDPR constraints on geolocation data storage periods, limiting cross-border service standardization.
- Mobile-First Substitution:Lightweight driver apps from adjacent fleet management sectors threaten to displace full-featured towing platforms for small independent operators with sub-ten-truck fleets.
Strategic Opportunities
- Underpenetrated Canada:Provincial roadside assistance networks outside Ontario and Quebec operate on fragmented legacy systems, creating whitespace for unified dispatch platforms with bilingual compliance.
- EV Recovery Specialization:Electric vehicle towing protocols require battery state monitoring and flatbed-only dispatch rules, opening premium software tiers for certified EV-capable fleets.
- Municipal RFP Digitization:State procurement offices are shifting from paper-based bidding to centralized e-procurement portals, lowering customer acquisition costs for vendors with pre-approved contract vehicles.
Industry Challenges
- Legacy System Integration:Decades-old impound lot management databases with proprietary data formats resist API connectivity, forcing expensive middleware development for unified workflows.
- Certification Timeline Compression:State-level public utility commission licensing for towing software vendors is lengthening in California and New York, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Towing Software Market |
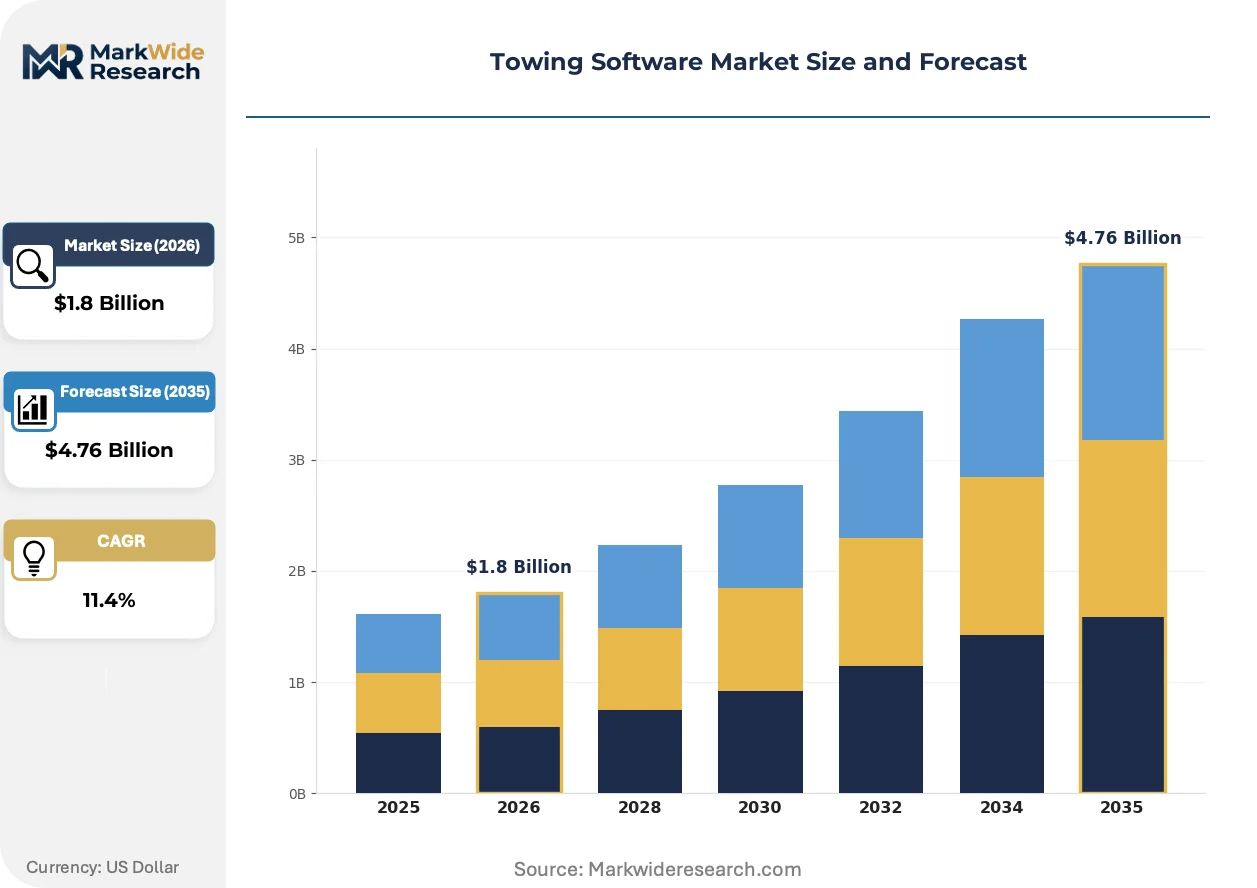
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tow Management, Fleet Tracking, Dispatch Software, Billing Solutions Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Applications End User: Towing Companies, Roadside Assistance Providers, Insurance Firms, Municipal Agencies Service Type: Technical Support, Software Customization, Training Services, Maintenance |
| Companies Covered | Towbook Management Software, ProTow, TXI Systems, Omadi, Relay Towing Software, Beacon Software, VTS Systems, Swoop, Route4Me, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Towing Software Market Evolving Landscape
Digital twin technology is virtualizing fleet coordination, compressing the gap between physical dispatch operations and software-mediated optimization. Three convergent developments are accelerating this transformation.
Edge-computing dispatch nodes are virtualizing route optimization by processing GPS telemetry and traffic data locally within vehicle-mounted hardware. Large fleet operators in Texas and Florida are deploying these systems to maintain dispatch continuity during cellular network outages. This virtualization is eliminating the latency penalties that previously constrained real-time decision-making in rural coverage zones.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated dispatch prioritization systems used by European roadside assistance networks. Vendors must now document training data provenance and decision logic for predictive ETA models. German motor clubs are responding by segregating AI-driven recommendations from mandatory human dispatch confirmations, creating dual-path workflow architectures.
Subscription pricing for software access is displacing perpetual license purchases among mid-market fleet operators who prefer operational expenditure treatment. United States-based commercial motor clubs are consolidating vendor relationships through multi-year platform agreements that bundle dispatch, tracking, and billing modules. This preference shift is most visible in the southeastern United States, where private equity-backed fleet rollups are standardizing technology stacks across acquired operators.
Towing Software Market Segmentation
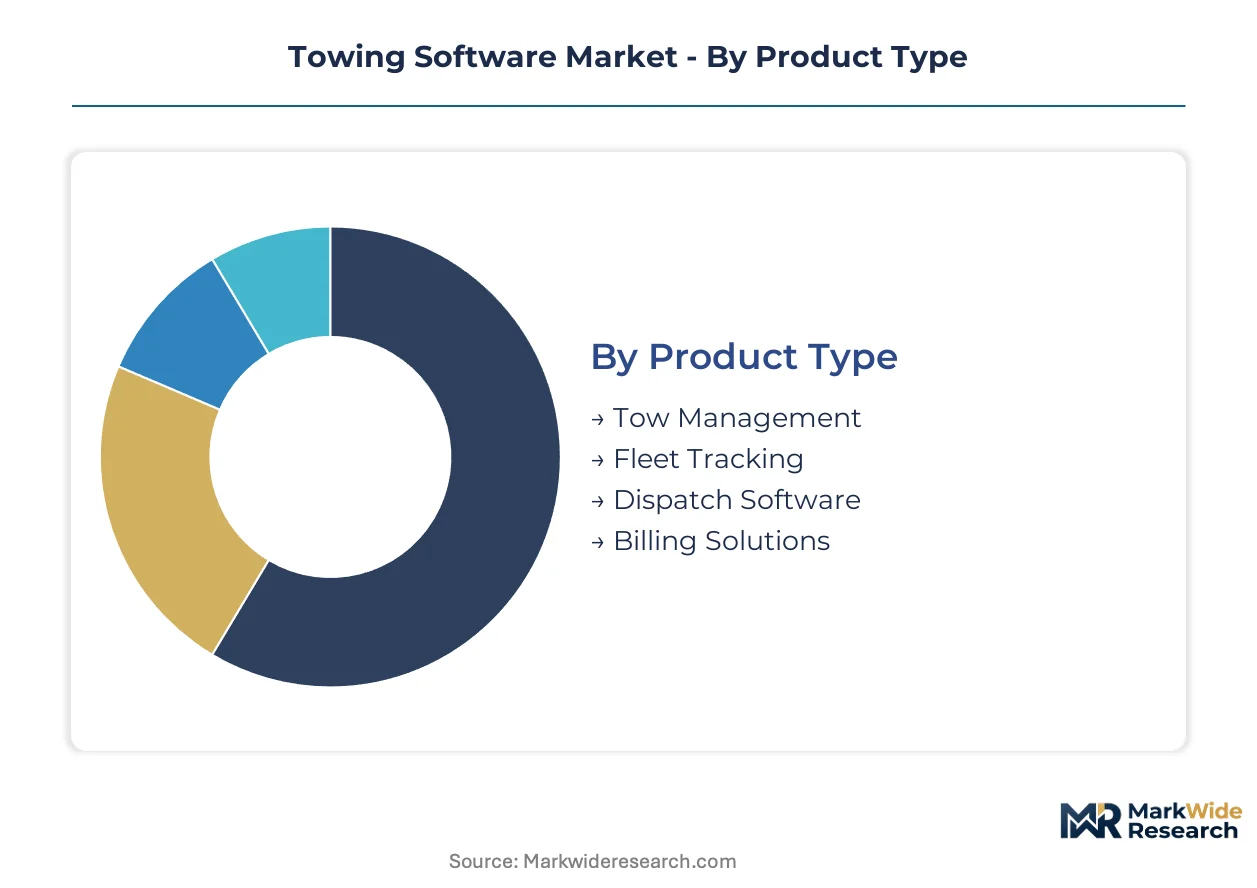
Towing software segmentation reveals how operational complexity drives purchasing patterns. Fleet operators select platforms based on integration depth, deployment constraints, and regulatory exposure rather than feature checklists alone.
Product Type:
Use-case spectrum spans single-truck dispatch optimization to multi-state fleet orchestration with predictive maintenance layers.
- Tow Management:Core dispatch coordination, impound lot tracking, and driver workflow automation anchor operational control for mid-market fleets. Municipal contract holders in Texas and Florida prioritize these systems for compliance documentation with state public utility commissions.
- Fleet Tracking:GPS telemetry with real-time route optimization and geofencing alerts. Commercial motor clubs across Germany embed predictive maintenance algorithms, expanding utility into asset lifecycle management.
- Dispatch Software:Cloud-native job allocation with mobile driver interfaces.
- Billing Solutions:Insurance claims integration and automated invoicing workflows.
Established volume favors Tow Management; emerging adoption favors Fleet Tracking.
Deployment:
Cost tier separation runs from capital-intensive on-premises installations to operational-expenditure cloud subscriptions.
- Cloud-Based:SaaS delivery eliminates server maintenance and enables instant mobile driver updates. United States roadside assistance networks are consolidating onto these platforms to reduce IT overhead.
- Hybrid Solutions:Edge-computing nodes process GPS data locally during cellular outages, then sync to central clouds. Large Texas operators deploy these for rural coverage continuity.
- On-Premises:Legacy server installations with full data custody.
- Mobile Applications:Lightweight driver-facing tools for sub-ten-truck independents.
Procurement momentum concentrates in Cloud-Based; Hybrid Solutions gain share fastest among rural coverage operators.
End User:
Customer type determines integration depth requirements and contract complexity.
- Towing Companies:Independent operators and fleet rollups need dispatch-billing-tracking unification. Private equity-backed consolidators in the southeastern United States standardize stacks across acquired operators.
- Roadside Assistance Providers:Motor clubs require API-first architectures for insurer data exchange. GDPR compliance costs elevate platform security standards for European networks.
- Insurance Firms:Property-casualty carriers mandate real-time claims data feeds.
- Municipal Agencies:State procurement offices shift to e-procurement portals.
Revenue concentration sits with Towing Companies; steepest expansion trajectory belongs to Roadside Assistance Providers.
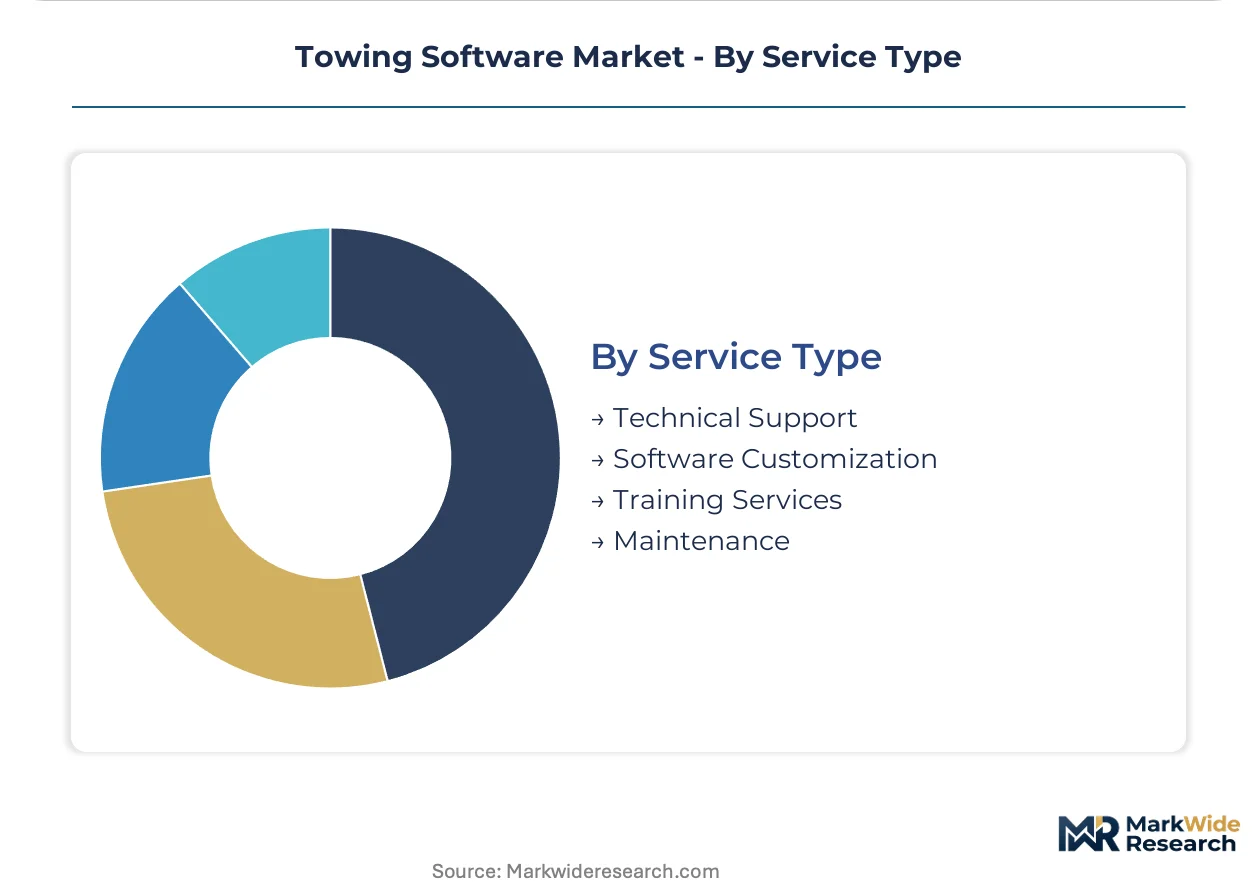
Service Type:
Margin structure differentiates high-touch customization from scalable subscription support.
- Software Customization:API middleware development for legacy impound database integration commands premium pricing. California and New York vendors face lengthening certification timelines that delay revenue recognition.
- Training Services:Bilingual compliance instruction for Canadian provincial networks outside Ontario and Quebec.
- Technical Support:Tiered response commitments with uptime guarantees.
- Maintenance:Security patch delivery and feature update scheduling.
Margin protection depends on Software Customization; volume scaling favors Training Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Motor Carrier Safety Administration anchors regulatory gravity in the United States, where commercial towing fleets face mandatory electronic logging compliance. This regulatory anchor shapes procurement patterns across North American roadside assistance networks and establishes baseline telematics requirements that ripple through adjacent markets.
United States
Commercial motor clubs in Texas and Florida are deploying edge-computing dispatch nodes to maintain rural coverage continuity during cellular outages. The FMCSA ELD mandate creates baseline demand for integrated telematics platforms that automate driver hour tracking. Private equity-backed fleet rollups across the southeastern United States are standardizing technology stacks through multi-year platform agreements.
Canada
Provincial roadside assistance networks outside Ontario and Quebec operate on fragmented legacy systems, creating whitespace for unified dispatch platforms. Bilingual compliance requirements elevate platform security standards for vendors entering Quebec and New Brunswick markets. Municipal procurement offices in Alberta and British Columbia are shifting toward centralized e-procurement portals.
Germany
The EU AI Act imposes algorithmic transparency requirements on automated dispatch prioritization systems used by German motor clubs. CE marking obligations and GDPR constraints on location data retention elevate platform security standards for European operators. Munich and Stuttgart clusters are segregating AI-driven recommendations from mandatory human dispatch confirmations.
United Kingdom
Post-Brexit regulatory divergence is creating compliance complexity for cross-border roadside assistance networks serving Ireland and continental Europe. London-based motor clubs are mandating API-first architectures for real-time claims data exchange with property-casualty carriers. The Midlands and northern England host growing concentrations of mid-market fleet operators consolidating onto cloud-native platforms.
France
ANSM and CNIL enforcement of GDPR location retention constraints is limiting cross-border service standardization for operators serving Belgium and Luxembourg. Paris-based roadside assistance networks are embedding predictive maintenance algorithms from commercial motor clubs into fleet management dashboards. Lyon and Marseille clusters are responding to EU AI Act requirements with dual-path workflow architectures.
Towing Software Market Competitive Landscape
Cloud-native specialists and legacy on-premises vendors split the market along deployment architecture lines. The vendor base compresses toward SaaS delivery as municipal procurement offices and fleet operators abandon capital-intensive server installations. Three archetypes dominate: established dispatch platforms with insurance integration depth, telematics-first entrants with predictive maintenance layers, and municipal contract specialists with compliance documentation expertise. Consolidation through private equity-backed fleet rollups and API interoperability partnerships represent the dominant competitive vectors.
Within the cloud-native tier, Towbook Management Software and ProTow anchor distinct positioning vectors. Towbook exemplifies the mid-market fleet consolidation play through cloud-native dispatch architectures. ProTow occupies a specialized niche in billing workflow integration with insurance claims systems. Beacon Software represents the municipal contract specialist archetype, with defensible positioning across southeastern United States procurement networks.
| Leading Market Players |
|---|
| Towbook Management Software |
| ProTow |
| TXI Systems |
| Omadi |
| Relay Towing Software |
| Beacon Software |
| VTS Systems |
| Swoop |
| Route4Me |
| Others |
Value Network & Pricing Analysis
Semiconductor fabrication concentration in Taiwan and South Korea for GPS modules and cellular modems feeds directly into margin compression for hybrid cloud-edge deployments, with downstream software vendors absorbing hardware cost volatility through tiered subscription structures.
Pricing Analysis
North American municipal contracts trade at 15-25 percent premiums over comparable commercial fleet deployments due to compliance documentation burdens and extended payment terms. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with API-first insurance connectivity commanding top-tier rates. Cost compression in economy-tier mobile-first offerings is intensifying because lightweight driver apps from adjacent fleet management sectors erode feature-complete platform value. Small independent operators with sub-ten-truck fleets exhibit highest price sensitivity; private equity-backed fleet rollups absorb premium pricing for unified stack standardization.
Supply Chain Analysis
US export controls on advanced semiconductors and position-fixing technologies constrain hardware sourcing for edge-computing dispatch nodes, forcing vendors toward qualified supplier lists. Component manufacturing concentrates in China, Taiwan, and Vietnam for GPS chipsets, cellular modems, and vehicle-mounted processing units. Raw material dependencies span lithium for battery-backed edge devices, rare earth elements for antenna assemblies, and high-purity silicon for telemetry processors. Single-source vulnerability runs through TSMC-adjacent fabrication for precision positioning chipsets. Distribution runs through Tier 1 hardware integrators who bundle white-label devices with software subscriptions for fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from lightweight driver apps and adjacent fleet management platforms that strip towing-specific functionality for cost-sensitive independents.
For Market Incumbents: Entrench API-first insurance integration as a switching-cost moat against mobile-app substitution, while consolidating vertical control over edge-computing hardware supply through captive relationships with Taiwan-based chipset distributors. Certification investment in California and New York public utility commission licensing creates regulatory barriers for SaaS entrants. For New Entrants and Emerging Players: Establish a beachhead in Canadian provincial networks outside Ontario and Quebec, where fragmented legacy systems and bilingual compliance requirements deter incumbent expansion. Target EV recovery specialization with battery-state monitoring modules, leveraging flatbed-only dispatch protocols as a premium tier entry point. Go-to-market through municipal e-procurement portal pre-approval accelerates contract velocity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures, reducing barrier-to-entry advantages for legacy on-premises vendors. Long-term viability favors platforms with embedded telematics and predictive maintenance layers that expand addressable spend per truck. Acquisition target archetype: mid-market SaaS vendors with FMCSA ELD compliance certification and existing insurance API partnerships. Signal to watch: state-level procurement office consolidation onto centralized e-procurement portals as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures reduce manual billing friction with property-casualty carriers. |
| Geographic Expansion | Canadian provincial networks outside Ontario and Quebec offer whitespace for unified dispatch platforms. |
| Acquisition of Specialist Firm | EV recovery certification capabilities command premium software tiers from certified fleets. |
| Product Launch | Edge-computing dispatch nodes maintain rural coverage continuity during cellular outages. |
| Strategic Partnership | Multi-year platform agreements with private equity-backed fleet rollups standardize technology stacks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet dispatch managers, roadside assistance network CTOs, municipal procurement officers, and insurance claims integration specialists. Secondary validation drew from FMCSA regulatory filings, state public utility commission licensing databases, SEC 10-K disclosures from listed fleet operators, and customs data on GPS module imports. Bottom-up sizing of installed base and top-down cross-check against roadside assistance contract values established volume anchors.
Calibration against historical adoption curves for cloud-native dispatch platforms anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, fleet size tier, integration complexity level, and regional regulatory cluster. CAGRs derived from S-curve penetration modeling for telematics convergence and predictive maintenance algorithm adoption. Forecast inputs incorporated ELD mandate compliance deadlines and municipal RFP digitization timelines.
Stress conditions across semiconductor availability, GDPR enforcement intensity, and mobile-app substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on API interoperability standardization and insurance carrier data exchange requirements. Material shifts in FMCSA regulatory interpretation or EU AI Act algorithmic transparency enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Dental Practice Management Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Business Rules Management System Market
Software & Services
Europe CMMS Software Market
Software & Services
Application Virtualization Market
Software & Services
Global Vendor Management Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global HVAC Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Global Directory Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Global Cloud Enterprise Resource Planning Market
Software & Services
Global IVR Software Market
Software & Services
Coaching Management Software Market