
 Global Testing Software Market | 2026-2036
Global Testing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Testing Software Market Foresight
Open-source containerization frameworks are realigning enterprise testing economics as organizations replace legacy virtualization stacks with Kubernetes-native validation pipelines. IBM leverages its hybrid cloud portfolio to anchor large-scale government testing contracts across federal agencies. Tricentis specializes in model-based test automation for SAP environments, sustaining premium positioning in European manufacturing verticals.
Testing software comprises code-level validation engines, synthetic data generators, and continuous integration orchestrators that execute functional, performance, and security assertions against software artifacts under specified load conditions and compliance baselines. Cloud-based deployment leads solution type distribution as enterprises migrate quality assurance workloads from fixed-capacity data centers to elastic consumption models; security testing registers the fastest structural expansion due to mandatory breach-disclosure statutes and zero-trust architecture mandates across BFSI and telecommunications end users. Embedded systems application testing commands elevated margins given hardware-software co-validation complexity and safety-critical certification requirements in automotive and aerospace supply chains.
The EU AI Act imposes conformity assessment obligations on automated decision systems, compelling European enterprises to procure validated testing toolchains with auditable traceability matrices. FDA software validation guidance for medical device manufacturers and NIST cybersecurity framework requirements for federal contractors similarly shape procurement specifications and vendor qualification criteria in the United States. Stakeholders must monitor evolving algorithmic accountability legislation across multiple jurisdictions to anticipate compliance-driven replacement cycles and certification premium capture opportunities.
Market Dynamics
Container-native validation pipelines are compressing testing cycles as enterprises abandon fixed-capacity data center licensing for Kubernetes-orchestrated elastic consumption models.
Growth Catalysts
- EU AI Act conformity mandates:Automated decision systems in European banking and insurance now require auditable traceability matrices, compelling procurement of certified testing toolchains with embedded compliance documentation.
- FDA software validation guidance:Medical device manufacturers in the United States face expanded premarket submission requirements for software-as-a-medical-device, driving demand for validated test automation platforms.
- Synthetic data generators:Privacy-preserving test data fabrication is displacing production data copies in German automotive supply chains, accelerating validation throughput without GDPR exposure.
Market Restraints
- Specialized hardware-software co-validation:Safety-critical embedded systems in aerospace require proprietary emulation rigs, locking mid-market vendors out of margin-rich certification workflows.
- Open-source toolchain fragmentation:Unmaintained plugins and version drift in community-driven testing frameworks create integration debt that enterprise procurement committees increasingly reject.
- Cloud egress cost volatility:Multi-terabyte test artifact transfer between hyperscale regions unpredictably inflates total cost of ownership for distributed quality assurance teams.
Strategic Opportunities
- India's digital infrastructure mandates:Central government PLI scheme incentives for semiconductor and electronics manufacturing are creating localized demand for indigenous testing certification laboratories.
- Zero-trust architecture mandates:United States federal contractor requirements under NIST cybersecurity framework specifications are opening adjacent security testing revenue streams adjacent to functional validation.
- Quantum-resistant cryptography validation:Post-quantum algorithm testing represents unclaimed white space as standards bodies finalize NIST-selected encryption schemes.
Industry Challenges
- ISO 26262 functional safety engineer scarcity:Automotive OEMs in Stuttgart and Wolfsburg compete for the same limited pool of certified hardware-in-the-loop validation specialists.
- Legacy SAP environment test data provisioning:European manufacturing enterprises struggle to generate consistent synthetic master data for S/4HANA migration validation without production system disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Testing Software Market |
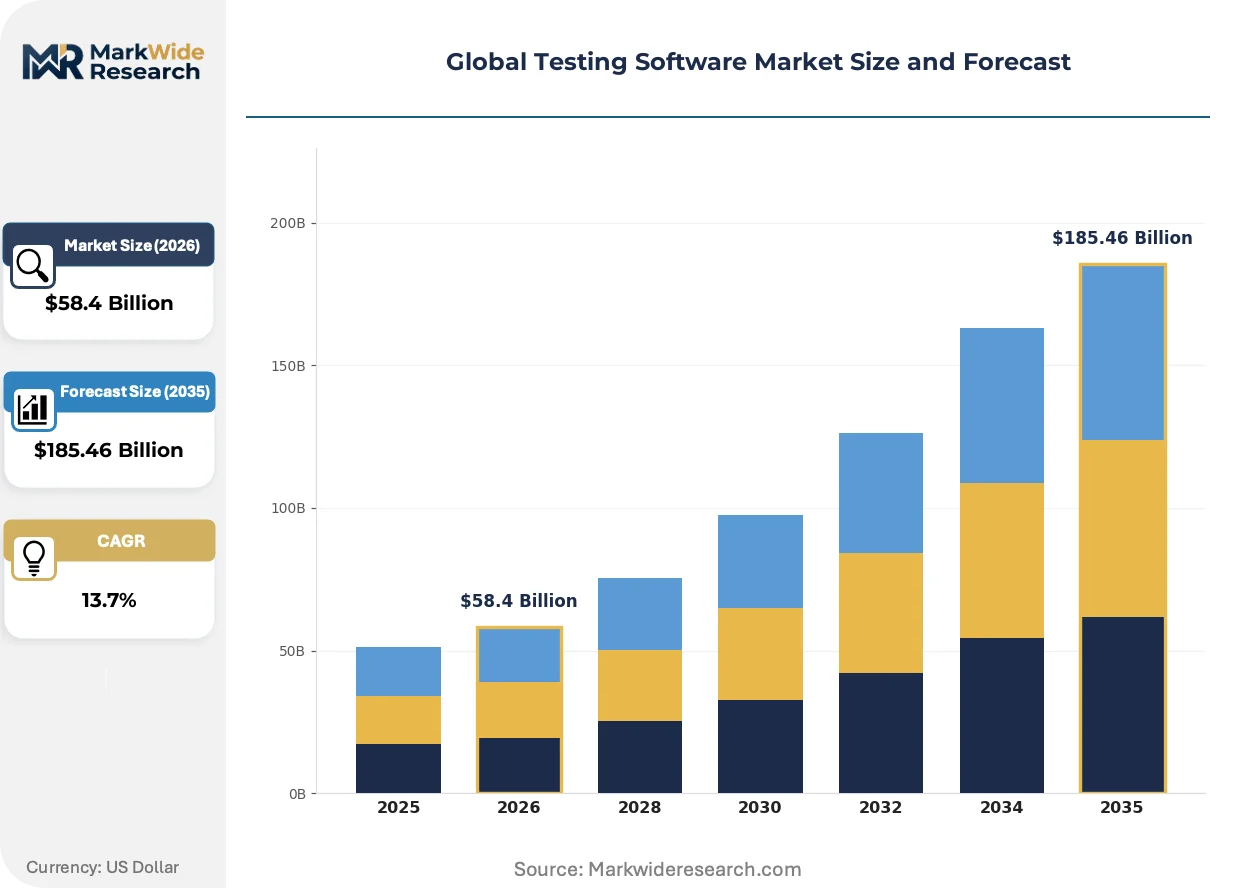
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $185.46 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS, Virtualized Solution Type: Functional Testing, Performance Testing, Security Testing, Compatibility Testing, Usability Testing Application: Web Applications, Mobile Applications, Embedded Systems, Enterprise Software, Middleware Platforms End User Industry: Telecommunications, BFSI, IT Services, Manufacturing, Government Agencies |
| Companies Covered | Accenture, Cognizant, IBM, TCS, Capgemini, NTT Data, Wipro, Tricentis, Qualitest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Testing Software Market Shifts & Advancements
Shift-left security validation is collapsing traditional sequential development handoffs as developers assume direct responsibility for vulnerability detection before code commit.
Model-based test automation is modularizing SAP environment validation by decomposing monolithic regression suites into reusable component libraries. German automotive suppliers now assemble test scenarios from standardized blocks rather than scripting end-to-end flows. This compression is halving validation cycle times for ECU software releases while reducing maintenance overhead.
REACH chemical substance traceability requirements are extending into software supply chain documentation. European medical device manufacturers must now map testing tool dependencies against restricted substance declarations. This regulatory extension is forcing validation platform vendors to restructure procurement contracts with full material disclosure clauses.
Consumption-based pricing is displacing perpetual licensing in enterprise quality assurance procurement. United Kingdom financial services firms now meter test execution minutes through cloud marketplaces rather than provisioning fixed agent pools. This behavioral shift concentrates vendor relationships with hyperscale platform operators and compresses standalone testing software margins.
Global Testing Software Market Segmentation
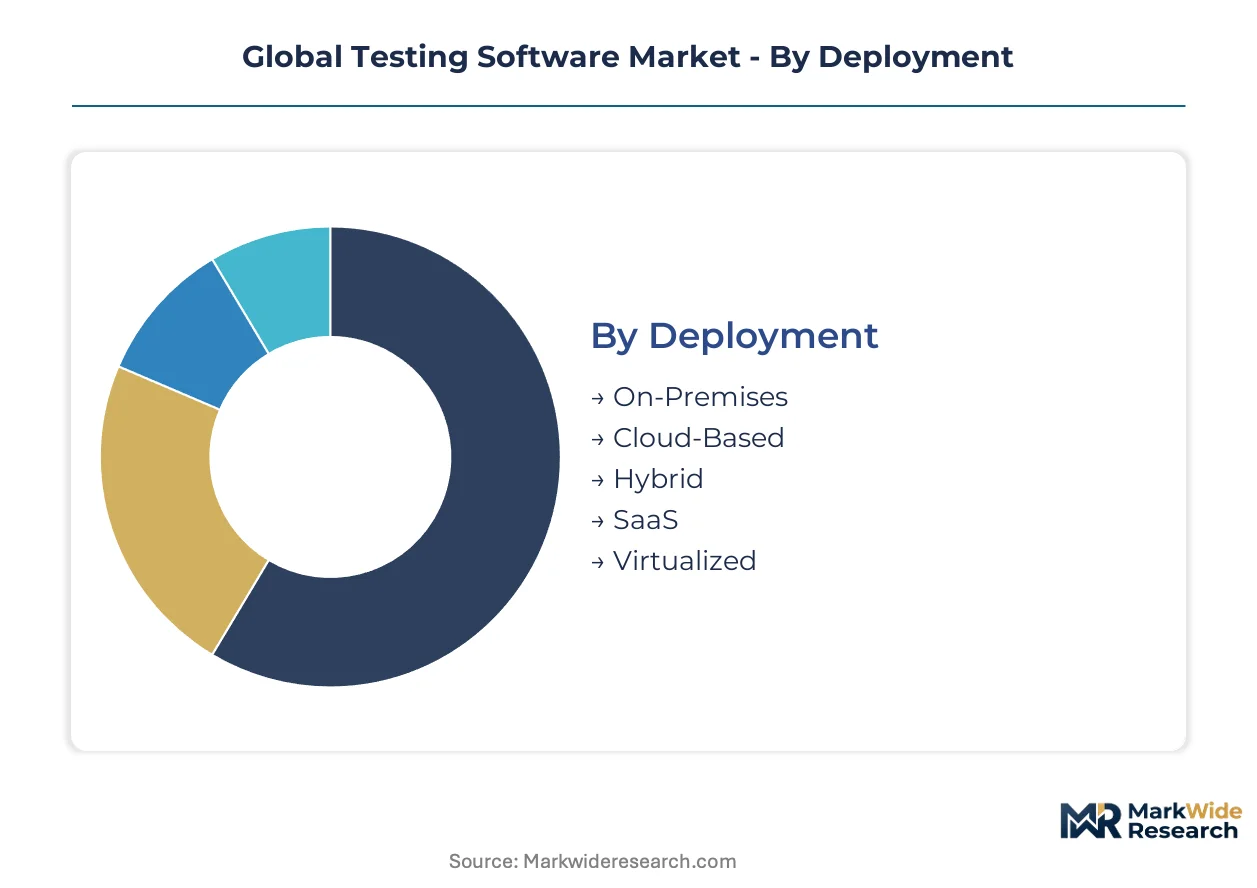
Testing software procurement patterns diverge sharply between standalone validation tools and deeply embedded CI/CD pipelines. Deployment architecture determines integration complexity, licensing economics, and vendor lock-in exposure across enterprise quality assurance functions.
Deployment:
Standalone installations persist in regulated environments where data sovereignty overrides cloud elasticity, while Kubernetes-native pipelines dominate greenfield DevOps transformations.
- On-Premises:Fixed-capacity licensing with perpetual ownership models suits German automotive suppliers subject to ISO 26262 audit trail requirements. Stuttgart-based ECU manufacturers maintain captive data centers to prevent test artifact egress outside national boundaries.
- Cloud-Based:Elastic consumption metering aligns with United Kingdom financial services procurement patterns, where Barclays and HSBC meter test execution minutes through AWS Marketplace integrations. Cloud egress cost volatility remains the primary constraint for distributed QA teams.
- Hybrid:Split workloads keep sensitive test data on-premises while bursting compute-intensive regression suites to hyperscale regions. Indian IT services exporters deploy this architecture to satisfy RBI data localization mandates for BFSI clients.
- SaaS:Browser-based validation portals eliminate agent provisioning overhead for mid-market enterprises. Subscription pricing compresses upfront capital requirements.
- Virtualized:Legacy VMware stacks persist in federal contractor environments where NIST cybersecurity framework compliance predates containerization adoption.
Cloud-Based leads volumes today; Hybrid is gaining share fastest.
Solution Type:
Functional validation commands baseline procurement budgets, while security testing captures premium pricing from mandatory breach-disclosure statutes.
- Functional Testing:Code-level assertion engines verify business logic against specification documents. SAP S/4HANA migration projects in Wolfsburg manufacturing clusters consume substantial regression automation capacity.
- Performance Testing:Load generation tools simulate concurrent user volumes to identify latency bottlenecks before production deployment. Indian telecommunications operators stress-test 5G network functions prior to commercial launch.
- Security Testing:Penetration testing suites and static application security testing (SAST) tools command elevated margins under United States federal zero-trust architecture mandates. NIST framework compliance drives adjacent security validation revenue.
- Compatibility Testing:Cross-browser and cross-device validation ensures consistent rendering across fragmented endpoint ecosystems. Mobile device fragmentation in emerging markets sustains demand.
- Usability Testing:Session recording and heatmap analytics validate user experience hypotheses prior to feature release. A/B testing integration differentiates premium offerings.
Functional Testing anchors procurement volumes; Security Testing climbs the fastest.
Application:
Hardware-software co-validation complexity stratifies margins, with embedded systems commanding certification premiums and web applications driving volume scale.
- Web Applications:Browser-based validation pipelines leverage Selenium and Playwright frameworks for cross-platform functional coverage. United Kingdom fintech startups prioritize continuous deployment velocity.
- Mobile Applications:Device cloud services provide access to fragmented Android and iOS hardware configurations without captive device farms. Indian consumer app developers represent high-volume adopters.
- Embedded Systems:Hardware-in-the-loop validation requires proprietary emulation rigs for automotive ECU and aerospace avionics certification. Stuttgart OEMs compete for scarce ISO 26262 functional safety engineers.
- Enterprise Software:Monolithic ERP regression suites demand model-based test automation to compress validation cycles. SAP environment testing sustains premium vendor positioning.
- Middleware Platforms:API and message queue validation ensures interoperability across distributed microservices architectures. Kubernetes-native service mesh testing represents emerging demand.
Web Applications dominate transaction volumes; Embedded Systems capture the steepest margin expansion.
End User Industry:
Regulatory intensity varies dramatically across verticals, with BFSI and government agencies mandating auditable traceability while manufacturing prioritizes throughput velocity.
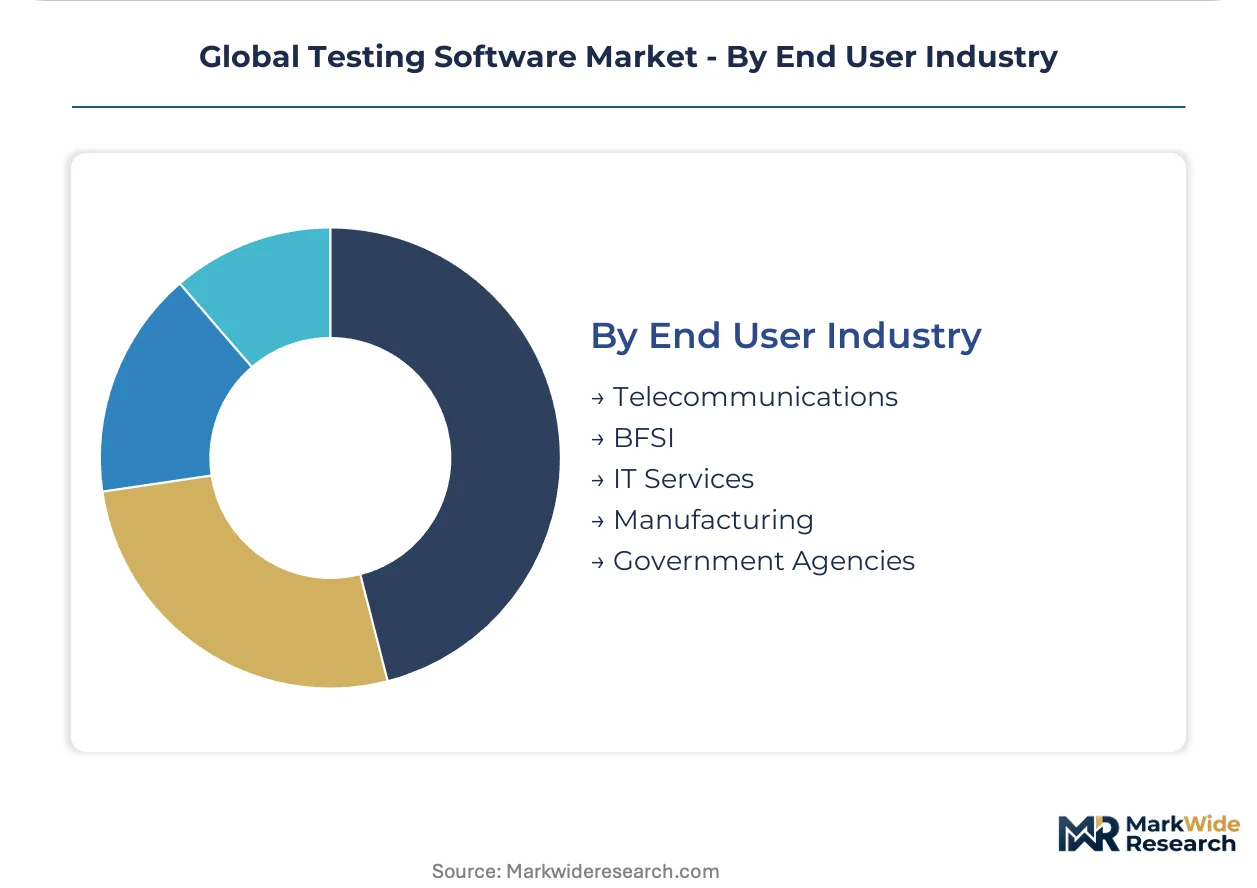
- Telecommunications:5G network function virtualization demands continuous validation of cloud-native infrastructure. Indian operators under TRAI quality-of-service mandates invest heavily in automated test coverage.
- BFSI:EU AI Act conformity assessments and GDPR data protection requirements compel European banks to procure certified testing toolchains with embedded compliance documentation. Automated compliance validation suites represent the fastest-growing procurement category.
- IT Services:Outsourced QA functions from global system integrators concentrate demand in Indian technology corridors. PLI scheme incentives for semiconductor manufacturing extend testing requirements to indigenous certification laboratories.
- Manufacturing:German automotive suppliers apply model-based test automation to ECU software releases, halving validation cycle times through reusable component libraries.
- Government Agencies:United States federal contracts under NIST cybersecurity framework specifications require validated test automation platforms with FedRAMP authorization. IBM anchors large-scale procurement through hybrid cloud portfolio alignment.
BFSI leads absolute spending; Government Agencies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors embedded systems validation demand as German automotive OEMs compete for scarce ISO 26262 functional safety engineers. The EU AI Act and GDPR requirements reshape procurement across European banking clusters. India's PLI scheme incentives for semiconductor manufacturing create localized certification laboratory demand.
United States
Federal contractor requirements under NIST cybersecurity framework specifications drive validated test automation platform procurement. FDA software validation guidance for medical device manufacturers expands premarket submission requirements. Greater Boston medical device clusters consume substantial security testing capacity for SaMD releases.
Germany
REACH chemical substance traceability requirements extend into software supply chain documentation for medical device manufacturers. The EU AI Act imposes conformity assessment obligations on automated decision systems in banking and insurance. Stuttgart and Wolfsburg automotive suppliers apply model-based test automation to halve ECU validation cycle times.
United Kingdom
Financial services firms meter test execution minutes through cloud marketplaces rather than provisioning fixed agent pools. Barclays and HSBC drive consumption-based pricing adoption across elastic quality assurance workloads. London fintech startups prioritize continuous deployment velocity through browser-based validation pipelines.
India
Central government PLI scheme incentives for semiconductor and electronics manufacturing create indigenous testing certification laboratory demand. RBI data localization mandates for BFSI clients push hybrid deployment architectures among IT services exporters. Bangalore and Hyderabad technology corridors concentrate outsourced QA functions from global system integrators.
Japan
METI industrial standards shape enterprise software procurement specifications for manufacturing verticals. Automotive and electronics supply chains demand hardware-software co-validation complexity for safety-critical certification. Tokyo and Nagoya industrial clusters sustain premium positioning for embedded systems testing margins.
Global Testing Software Market Competitive Landscape
Global majors compete with regional champions across deployment architecture and compliance specialization. The vendor base stratifies between hyperscale platform operators, legacy system integrators, and vertical-specific testing specialists. Three archetypes dominate: cloud-native pipeline providers, SAP environment specialists, and federal contract anchors. M&A activity concentrates on containerization capabilities while strategic partnerships target zero-trust security validation adjacencies.
Within the federal contract anchor tier, IBM occupies a position exemplifying hybrid cloud portfolio alignment for large-scale government testing contracts. Tricentis represents the SAP environment specialist archetype through model-based test automation for European manufacturing verticals. Among global system integrators, TCS and Wipro exemplify scale-driven delivery models for outsourced QA functions concentrated in Indian technology corridors.
| Leading Market Players |
|---|
| Accenture |
| Cognizant |
| IBM |
| TCS |
| Capgemini |
| NTT Data |
| Wipro |
| Tricentis |
| Qualitest |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FedRAMP-authorized federal contractors and mid-market SaaS providers manifests in both pricing premiums and supply chain localization requirements. Premium toolchains command three-to-five-year enterprise agreements with embedded compliance documentation, while economy-tier offerings compete on per-execution metering through hyperscale marketplaces.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers intensifies pricing pressure on SaaS-native testing vendors. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized federal contractors from GDPR-compliant European specialists and unlicensed open-source alternatives. Price differentiation hinges on certification level—ISO 27001, SOC 2 Type II, and EU AI Act conformity assessment—and vertical integration into synthetic data generation capabilities. Cost compression in the economy tier accelerates as hyperscale operators bundle testing minutes with compute commitments. Mid-market enterprises exhibit highest price sensitivity, while BFSI procurement committees prioritize audit trail completeness over unit economics.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for semiconductor validation laboratories. Supply concentration centers on the United States for federal contract tooling, Germany for automotive hardware-in-the-loop rigs, and India for outsourced QA labor pools. Raw material dependencies include proprietary emulation hardware from Stuttgart suppliers, GPU clusters from hyperscale operators, and certified functional safety engineers. Single-source vulnerability in ISO 26262 specialist talent pools constrains capacity expansion. Distribution runs through direct enterprise sales for regulated verticals and cloud marketplaces for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement committees elevate compliance documentation above feature velocity in vendor selection criteria. The demand shift toward EU AI Act conformity assessment obligations justifies premium positioning for auditable traceability matrices.
For Market Incumbents: Extend certification coverage into emerging regulatory domains before specialized entrants capture quantum-resistant cryptography validation white space. Anchor federal contract relationships through FedRAMP authorization investments that lock out mid-market competitors lacking compliance infrastructure. Deepen synthetic data generation capabilities to defend against open-source toolchain commoditization in GDPR-sensitive European banking clusters. For New Entrants and Emerging Players: The price-point gap between SAP-certified model-based automation suites and Selenium-based open-source alternatives creates entry opportunity for container-native pipeline providers. Target India's indigenous certification laboratory demand under PLI scheme incentives as the most penetrable geography. Pursue channel partnerships with hyperscale operators rather than direct enterprise sales to minimize customer acquisition costs. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 26262 functional safety engineer scarcity constrains organic growth for automotive testing specialists. Long-term viability favors vendors with embedded compliance documentation capabilities spanning multiple regulatory jurisdictions. Acquisition target archetype: vertical-specific testing specialists with dormant federal contract relationships. Watch NIST post-quantum cryptography standard finalization as inflection indicator for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Container-native pipelines displace VMware stacks in federal contractor environments seeking NIST compliance. |
| Acquisition of Specialist Firm | Synthetic data generators eliminate GDPR exposure for German automotive supply chains validating ECU releases. |
| Strategic Partnership | Hyperscale marketplace integrations enable consumption-based pricing for United Kingdom financial services firms. |
| Geographic Expansion | Indigenous certification laboratories capture PLI scheme demand from Indian semiconductor manufacturing incentives. |
| Product Launch | Quantum-resistant cryptography validation tools address unclaimed white space as NIST finalizes encryption standards. |
Research Methodology
Direct dialogue with CTOs, IT procurement officers, platform engineers, and compliance auditors grounded the qualitative foundation. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FedRAMP authorization databases, and EU AI Act implementation guidance. Bottom-up and top-down triangulation reconciled vendor-reported deployment metrics with enterprise IT spending patterns.
Bottom-up segmentation modeling across deployment architecture, solution type, application complexity, and end-user industry generated volume and value outputs. The analytical framework projected adoption curves across the analysis window using derived CAGRs from historical penetration rates and regulatory mandate timelines. Industry-specific inputs included FDA software validation guidance revision schedules and ISO 26262 certification velocity in Stuttgart automotive clusters.
Caveats apply where NIST post-quantum cryptography standard delays or EU AI Act enforcement variations could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance cost pass-through and hyperscale bundling strategies. A small set of named triggers—quantum-resistant algorithm finalization, PLI scheme incentive adjustments, and ISO 26262 engineer pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
RIP Software Market
Software & Services
Creative Software Market
Software & Services
Global Localization Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Saas-Based SCM Market
Software & Services
Reporter Systems Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Online Donation Software Market
Software & Services
Global Product Management Software Market
Software & Services
Background Removal Software Market
Software & Services
Website Builder Tool Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Australia HR Payroll Software Market