
 Packaged Software Market | 2026-2036
Packaged Software Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Software Market Outlook
Subscription-based financing and asset-light SaaS leasing is rewriting competitive entry barriers for mid-tier vendors. Microsoft Corporation leverages its Azure infrastructure to sustain hybrid deployment dominance across enterprise accounts. Oracle Corporation anchors its position through in-house database-to-application stack control. Salesforce Inc competes aggressively via vertical-specific CRM modules tailored to healthcare and financial services workflows.
Packaged software denotes pre-built, commercially licensed applications delivered through physical media, downloadable installers, or cloud-hosted instances, typically incorporating compiled codebases, configuration databases, and API endpoints designed for immediate deployment without custom engineering. These solutions automate enterprise workflows, manage customer relationships, process financial transactions, and secure digital infrastructure across organizational scales. ERP Solutions and CRM Software occupy the largest installed bases and renewal pools, while Cloud-Based and Software as a Service deployment models capture the fastest expansion trajectories as organizations retire on-premise data centers. Project Management Tools represent a maturing segment with consolidation pressure, whereas hybrid deployments in regulated verticals retain premium pricing power due to data sovereignty requirements.
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that shape product architecture decisions for vendors serving European enterprises. The US SEC cybersecurity disclosure rules and HIPAA requirements for healthcare software create compliance-driven demand for audit-ready, pre-certified packaged solutions. Stakeholders must monitor how fragmented regulatory timelines across jurisdictions will force modular certification strategies rather than unified global product releases.
Market Dynamics
Cloud migration mandates from enterprise buyers are compressing on-premise maintenance revenue pools while forcing vendors to rearchitect licensing frameworks around consumption-based metering.
Growth Catalysts
- EU AI Act compliance deadlines:European enterprises must deploy auditable algorithmic decision-making tools by fixed regulatory timelines, accelerating replacement of legacy black-box systems with certified packaged alternatives.
- Financial services cloud ERP expansion:Banks and insurers are retiring mainframe cores for modular cloud suites to satisfy real-time reporting requirements and reduce data center operating overhead.
- API-first architecture adoption:Pre-built integration marketplaces are shortening implementation cycles for mid-market buyers who lack internal development resources.
Market Restraints
- Hyperscaler concentration risk:Three cloud infrastructure providers control the underlying compute layer for most SaaS deployments, creating single-point-of-failure exposure and pricing leverage.
- Data residency compliance costs:Fragmented national data localization laws force vendors to maintain redundant hosting footprints, elevating operational expenditure without corresponding revenue expansion.
- Open-source substitution pressure:Enterprise-grade alternatives to proprietary CRM and ERP modules are maturing, eroding pricing power in commoditized workflow categories.
Strategic Opportunities
- Healthcare vertical specialization:HIPAA-compliant workflow automation for US hospital systems remains underserved by generic cross-industry platforms, creating margin-rich niche expansion potential.
- Edge deployment architectures:Manufacturing and logistics buyers require low-latency processing at distributed sites, opening hybrid delivery models that blend cloud control planes with local instance execution.
- SEC cybersecurity disclosure alignment:Public company audit requirements for incident reporting are driving demand for pre-certified security modules with embedded compliance documentation.
Industry Challenges
- Legacy system integration complexity:Decades-old custom codebases in enterprise accounts resist standard API connectivity, forcing costly professional services engagements that compress product gross margins.
- Multi-jurisdiction certification lag:Sequential approval processes across national regulators delay product launches and fragment development roadmaps.
- Specialized cloud architecture talent scarcity:Shortages of engineers skilled in Kubernetes orchestration and zero-trust security design are inflating compensation costs and slowing delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Software Market |
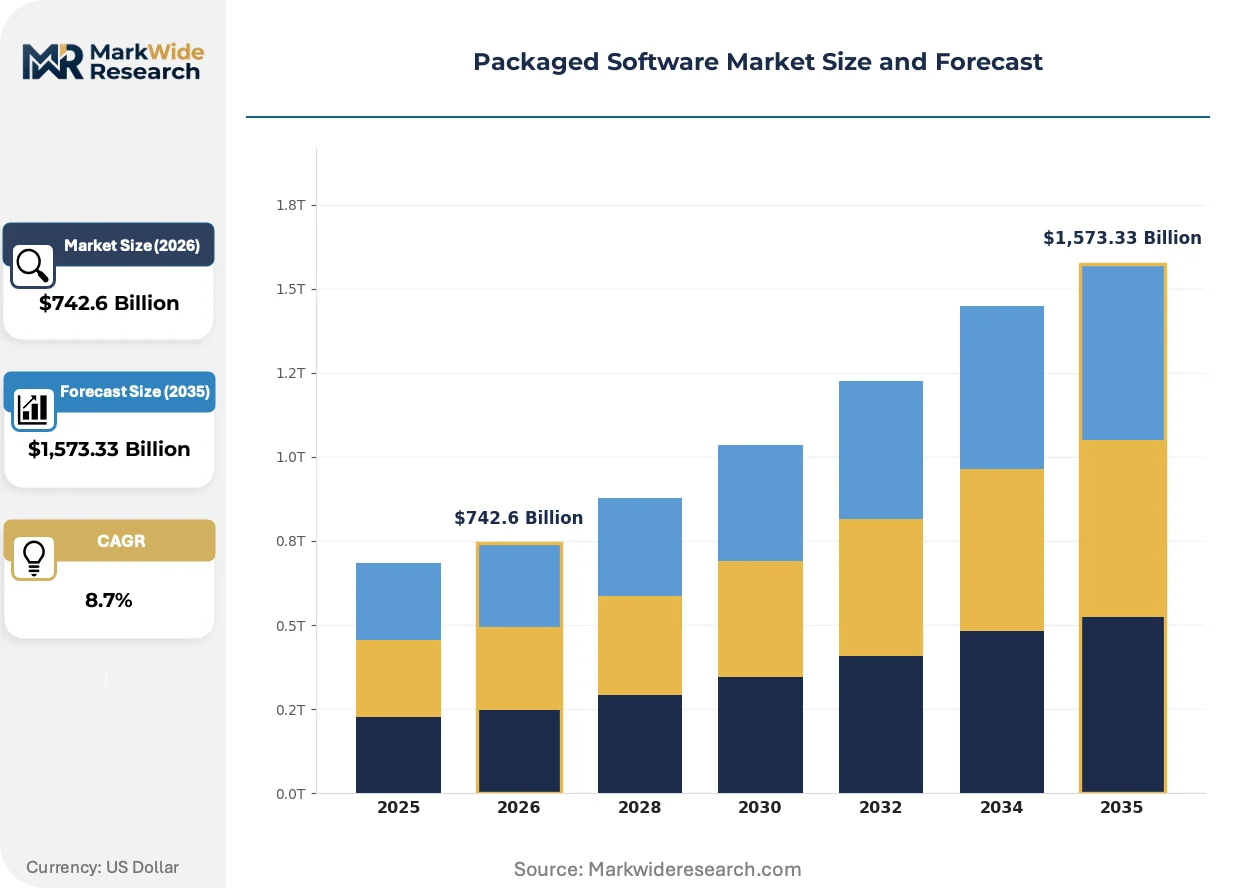
| Market Size in 2026 | $742.6 Billion |
| Market Size in 2035 | $1,573.33 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM Software, ERP Solutions, Accounting Software, Project Management Tools Deployment Model: On-Premise, Cloud-Based, Hybrid, Software as a Service End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Retail, Financial Services, Manufacturing |
| Companies Covered | ServiceNow Inc, Intuit Inc, Microsoft Corporation, Atlassian Corporation, CrowdStrike Holdings Inc, Oracle Corporation, Adobe Inc, Palantir Technologies Inc, Salesforce Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Software Market Strategic Shifts
Containerized deployment and AI-embedded automation are restructuring how packaged software is built, sold, and consumed across enterprise technology stacks.
Container orchestration technology is virtualizing the traditional boundary between infrastructure and application layers. DevOps teams in financial services and healthcare verticals are adopting Kubernetes-native packaging at accelerating rates. This shift is virtualizing vendor lock-in dynamics by enabling portable workloads across competing cloud substrates.
GDPR algorithmic accountability requirements are mandating explainability features in automated decision systems. Vendors must now embed audit trails and bias detection modules into core product architectures. European enterprise buyers are prioritizing pre-certified solutions to avoid regulatory exposure and implementation delays.
Enterprise buying committees are consolidating vendor relationships around integrated platform suites rather than best-of-breed point solutions. Procurement functions are demanding consolidated billing and unified support structures that reduce supplier management overhead. This concentration pattern is most pronounced among US mid-market manufacturers seeking to rationalize fragmented software estates.
Packaged Software Market Segmentation
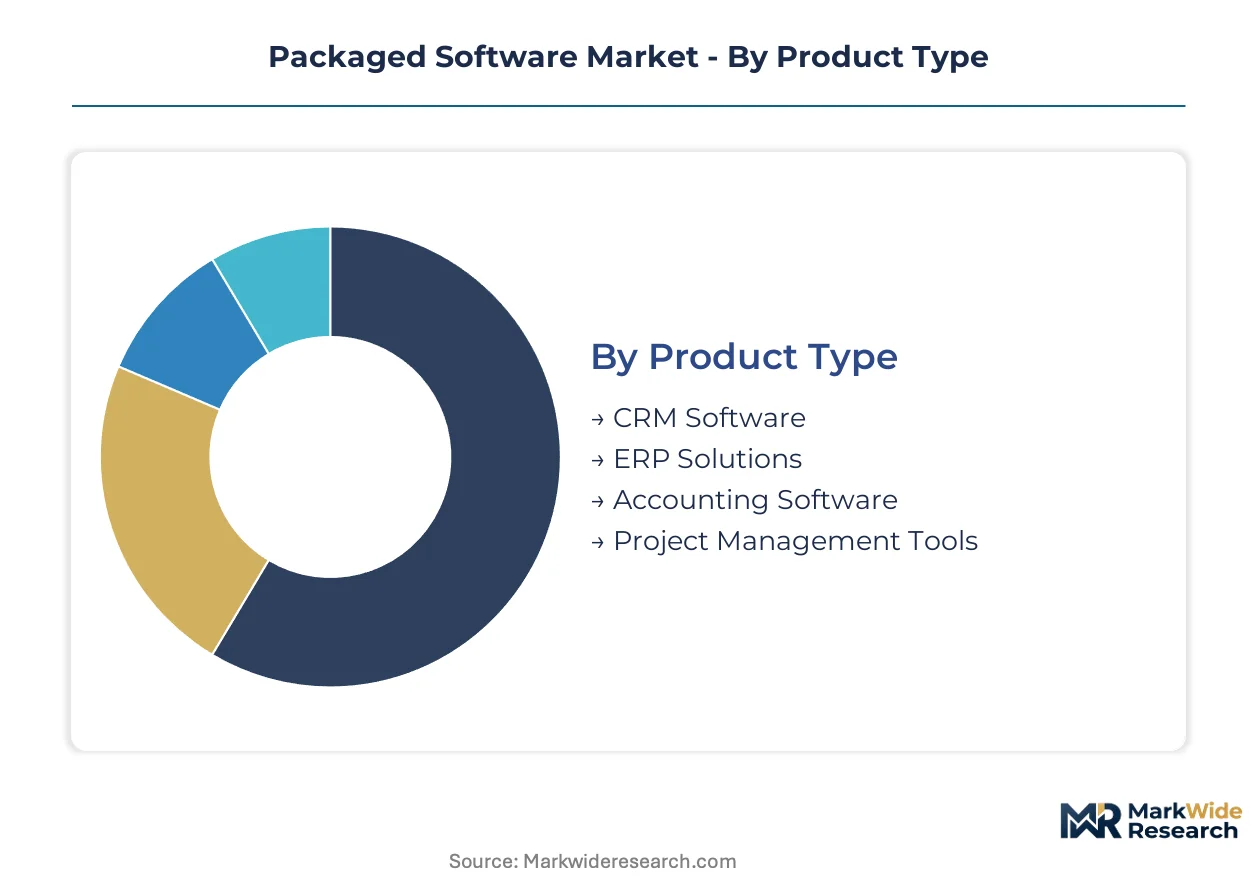
Segmentation in packaged software reveals divergent replacement cycles that reshape vendor resource allocation. ERP and CRM systems lock enterprises into multi-year contracts with steep switching costs, while project management tools churn faster as teams test alternatives. Deployment models and end-user scale further stratify renewal predictability and pricing power.
Product Type:
Replacement velocity varies dramatically across functional categories, with transactional systems turning over slowly and collaborative tools cycling rapidly as user preferences shift.
- ERP Solutions:Integrated suites spanning finance, HR, and supply chain operations bind organizations through data migration complexity and process reengineering investments. Manufacturing conglomerates in Germany and financial services holding companies in the United States anchor the longest average contract tenures, driven by regulatory audit trail requirements and multi-entity consolidation needs.
- CRM Software:Customer data platforms with embedded workflow automation manage prospect pipelines, service tickets, and marketing attribution across sales organizations. Healthcare provider networks and retail banking divisions concentrate demand for HIPAA-compliant and PCI-DSS-certified deployments, with renewal rates bolstered by proprietary data model entrenchment.
- Accounting Software:General ledger, accounts payable, and tax compliance modules serve statutory reporting obligations with jurisdiction-specific regulatory templates.
- Project Management Tools:Task coordination and resource scheduling applications face compressed evaluation cycles as distributed teams pilot competing collaboration interfaces.
ERP Solutions anchors the volume base while Project Management Tools gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models, with hybrid architectures commanding premium positioning for sovereignty-sensitive workloads.
- Cloud-Based:Multi-tenant architectures with shared infrastructure pools deliver elastic compute and storage without facility ownership burdens. United States technology firms and United Kingdom professional services clusters drive consumption growth, attracted by consumption-based metering that aligns spending with actual utilization rather than peak provisioning.
- Software as a Service:Vendor-managed application layers with automatic update cycles eliminate patch management overhead for resource-constrained buyers. Mid-market manufacturers in Japan and healthcare clinics in Australia prioritize SaaS subscriptions to redirect technical staff toward core operations rather than infrastructure maintenance.
- On-Premise:Perpetually licensed software executing on customer-controlled hardware persists in classified environments and legacy compliance scenarios.
- Hybrid:Split architectures placing sensitive data on local instances while leveraging cloud control planes satisfy data residency mandates without sacrificing scalability.
On-Premise retains the largest installed base though Cloud-Based expands most quickly.
End User:
Customer scale determines implementation complexity and support intensity, with procurement sophistication varying across organizational maturity levels.
- Large Enterprises:Complex governance structures with distributed business units demand configurable role hierarchies and multi-currency consolidation. German automotive suppliers and United States pharmaceutical conglomerates anchor the highest average contract values, driven by global template standardization requirements and integration with proprietary manufacturing execution systems.
- SMEs:Resource-constrained organizations prioritize rapid deployment and minimal customization, accepting narrower feature sets for reduced total cost of ownership. Professional services firms in France and specialty retailers in Canada concentrate demand for pre-configured industry templates that accelerate time-to-value without dedicated implementation teams.
- Government Agencies:Public sector procurement with mandated competitive bidding and security certification requirements extends sales cycles.
- Educational Institutions:Budget-capped universities and school districts favor volume-discounted licensing with simplified administrative controls.
Large Enterprises dominate current revenue contribution while SMEs climb the fastest.
Industry Vertical:
Application-specific requirements fragment product development roadmaps, with compliance mandates and workflow patterns diverging sharply across sectors.
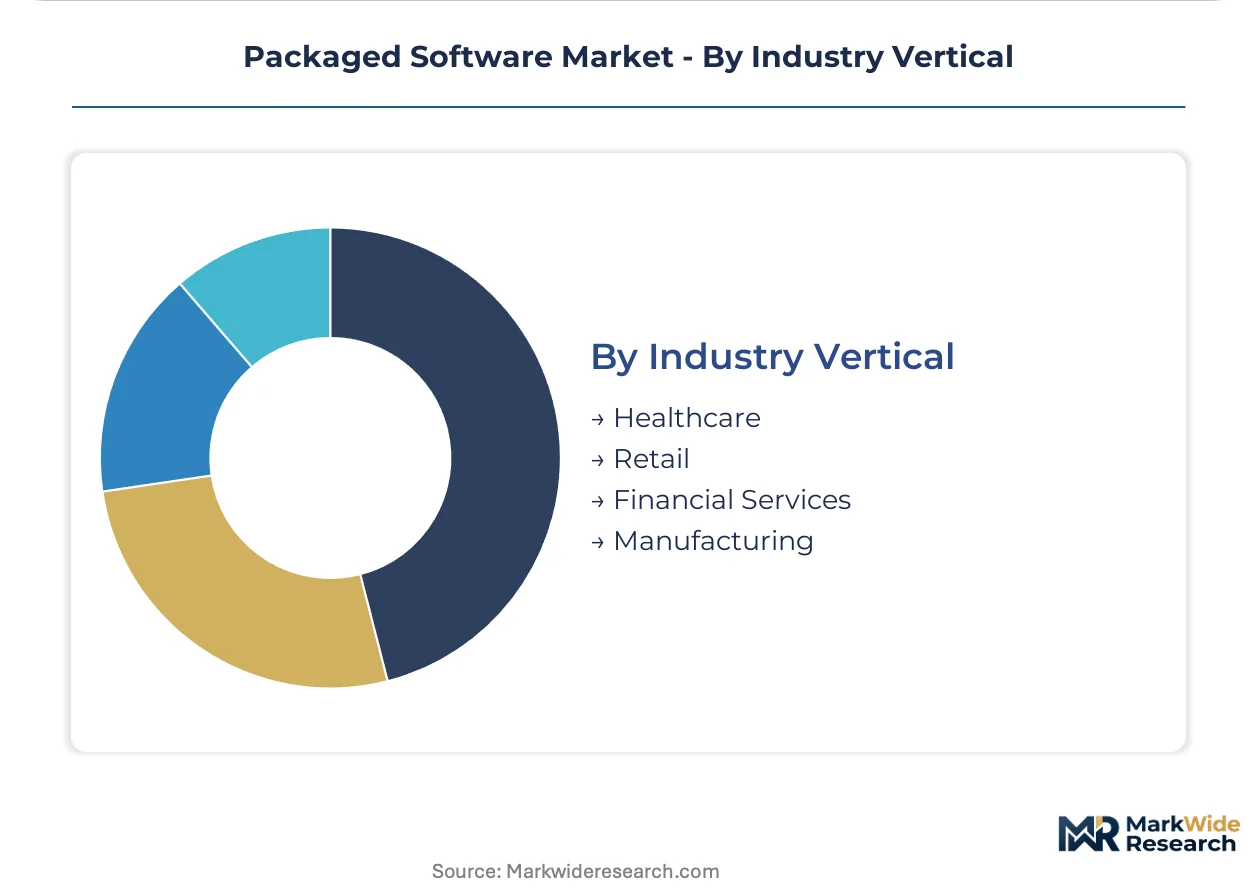
- Financial Services:Real-time transaction processing, anti-money laundering surveillance, and regulatory reporting automation dominate functional requirements. United Kingdom banking groups and Singaporean wealth management firms concentrate investment in cloud-native core banking replacements, driven by open banking API mandates and Basel liquidity calculation demands.
- Healthcare:Electronic health record integration, clinical workflow orchestration, and patient privacy protection shape procurement criteria. United States hospital systems and German university medical centers prioritize HIPAA and GDPR-aligned solutions with embedded consent management and audit logging capabilities.
- Retail:Omnichannel inventory visibility and customer identity resolution drive demand for unified commerce platforms.
- Manufacturing:Shop floor connectivity and supply chain traceability requirements favor industrial IoT-integrated application suites.
Financial Services anchors the volume base while Healthcare gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software trade flows favor export-heavy economies with deep enterprise technology bases. Import-dependent markets rely on foreign-hosted cloud infrastructure, creating data sovereignty friction. Regulatory fragmentation across jurisdictions forces vendors to architect redundant compliance layers.
United States
Enterprise technology corridors in California and Washington concentrate cloud infrastructure investment and SaaS development. SEC cybersecurity disclosure rules and HIPAA requirements shape product certification priorities for healthcare and financial software. The Boston-Washington corridor anchors financial services ERP replacement cycles.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg drive demand for manufacturing-integrated ERP suites. The EU AI Act and GDPR impose algorithmic transparency mandates that reshape product roadmaps. Frankfurt's financial services cluster accelerates core banking system modernization.
United Kingdom
Open banking API mandates and regulatory reporting requirements concentrate fintech software procurement in London. The Financial Conduct Authority's operational resilience rules elevate demand for audit-ready packaged solutions. Edinburgh and Manchester host expanding insurance technology development centers.
Japan
Mid-market manufacturers in Osaka and Nagoya prioritize SaaS subscriptions to redirect technical staff from infrastructure maintenance. METI's digital transformation incentives accelerate legacy system retirement. Tokyo's financial district anchors demand for real-time transaction processing platforms.
India
IT services hubs in Bengaluru and Hyderabad generate demand for project management and collaboration tools. RBI's data localization guidelines for financial services create hosting architecture constraints. Mumbai's banking sector drives CRM and customer data platform investment.
Packaged Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in narrow functional domains. The vendor base clusters around three structural tiers: hyperscale cloud platforms with integrated application stacks, vertical-focused SaaS providers with industry-specific workflows, and security-centric vendors with embedded compliance modules. Dominant competitive moves include strategic acquisitions to fill portfolio gaps and API-first partnership ecosystems to accelerate integration velocity.
Among hyperscale platform providers, Microsoft Corporation and Oracle Corporation occupy positions spanning infrastructure through application layers. Salesforce Inc exemplifies the vertical-specialist archetype with healthcare and financial services workflow modules. These three entities represent contrasting strategic postures: infrastructure-led bundling, database-to-application stack control, and industry-specific CRM configuration.
| Leading Market Players |
|---|
| ServiceNow Inc |
| Intuit Inc |
| Microsoft Corporation |
| Atlassian Corporation |
| CrowdStrike Holdings Inc |
| Oracle Corporation |
| Adobe Inc |
| Palantir Technologies Inc |
| Salesforce Inc |
| Others |
Value Chain & Pricing Dynamics
Hyperscaler infrastructure concentration in the United States and Ireland concentrates compute cost leverage at the base layer, forcing application vendors to absorb margin compression or pass through consumption volatility to enterprise buyers downstream. This upstream bottleneck reshapes where SaaS providers can extract pricing power versus where they must compete on operational efficiency.
Pricing Analysis
Large enterprise buyers anchor subscription-based pricing structures across the packaged software landscape. Three-tier pricing stratification separates premium compliance-certified suites from standard multi-tenant offerings and economy single-function modules, with differentiation resting on audit trail depth and API throughput guarantees. Pricing pressure stems from open-source ERP and CRM alternatives maturing in commoditized workflow categories, compressing margins for undifferentiated feature sets. SMEs exhibit acute price sensitivity, while financial services conglomerates prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Export control regimes restricting advanced GPU and AI accelerator flows to Chinese entities are fragmenting cloud infrastructure deployment patterns across vendor roadmaps. Supply concentration rests on United States hyperscalers, Irish data center clusters, and Singaporean interconnection hubs for Asia-Pacific routing. Dependencies center on NVIDIA accelerators, custom ARM-based server chips, and specialized networking silicon from Broadcom and Marvell. Single-source vulnerability in AI training hardware creates procurement risk for vendors building embedded automation features. Distribution runs through direct enterprise sales teams with certified implementation partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source substitution threatens incumbent pricing power across commoditized ERP and CRM modules, forcing proprietary vendors to defend through compliance certification moats and vertical workflow depth.
For Market Incumbents: Harden platform stickiness by embedding EU AI Act audit trails and HIPAA consent management directly into core architectures, not as add-on modules. Deepen vertical integration into healthcare and financial services workflow layers to escape open-source feature parity. Prioritize certification investment over raw feature expansion as the primary defensive lever against emerging API-first competitors. For New Entrants and Emerging Players: Establish a beachhead in mid-market healthcare clinics and specialty manufacturers seeking HIPAA-compliant project management tools without enterprise-suite complexity. Target Japanese and Australian SMEs with SaaS-native accounting modules that bypass legacy on-premise migration burdens. Lead with consumption-based metering and pre-configured industry templates to accelerate time-to-value against incumbent professional services dependencies. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertical SaaS providers holding concentrated hospital system or regional banking relationships but lacking platform breadth. Long-term viability hinges on whether target architectures can absorb AI compliance mandates without fundamental rewrites. Watch for inflection signals in EU AI Act certification timelines, as sequential national approvals will separate acquirable compliance-ready assets from stranded legacy codebases.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure and Oracle Cloud infrastructure bundling locks enterprise accounts into unified billing and support structures. |
| Acquisition of Specialist Firm | Healthcare workflow automation targets with embedded HIPAA audit trails command premium multiples from platform consolidators. |
| Product Launch | EU AI Act-certified algorithmic decision modules accelerate replacement cycles for black-box legacy systems in European banks. |
| Strategic Partnership | API-first integration marketplaces with Salesforce and ServiceNow reduce implementation friction for resource-constrained mid-market buyers. |
| Geographic Expansion | Frankfurt and Singapore data center footprints satisfy GDPR and RBI data localization mandates without sacrificing global template standardization. |
Study Parameters
A spread of perspectives from enterprise CTOs, IT procurement officers, platform integration specialists, and channel partners converged on the working assumptions driving segmentation splits and growth trajectory estimates. Primary fieldwork across financial services holding companies in New York, automotive suppliers in Stuttgart, and healthcare networks in Dallas supplied implementation timeline and renewal pattern intelligence. Secondary validation drew from SEC 10-K infrastructure disclosures, hyperscaler capex reporting, EU AI Act regulatory filings, and Gartner enterprise software spending surveys. Bottom-up account-level sizing and top-down macroeconomic anchoring were reconciled through iterative triangulation.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity tier, and regional regulatory cluster. CAGRs emerged from installed base turnover velocity analysis and new account acquisition run rates, cross-checked against cloud infrastructure consumption growth curves and professional services headcount expansion at major vendors. Forecast inputs incorporated EU AI Act compliance deadline phasing, HIPAA audit frequency changes, and open-source ERP feature maturity timelines.
Sensitivities concentrate around regulatory timeline delays, hyperscaler pricing actions, and open-source substitution acceleration in commoditized categories. Forecasts reflect documented assumptions about enterprise cloud migration persistence and compliance-driven replacement cycles. Material shifts in EU AI Act enforcement intensity, SEC cybersecurity disclosure scope expansion, or major open-source foundation governance changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Subscription Management Software Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Logistics Services Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Workflow Management Software (WMS) Market
Software & Services
Time and Attendance Software Market
Software & Services
Production Optimization Software Market
Software & Services
Petcare Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Talent Management Software Market
Software & Services
Mining Simulation Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Global Printing Software Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Visitor Identification Software Market