
 Construction and Design Software Market | 2026-2036
Construction and Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction and Design Software Market Intelligence
Recurring platform licensing revenue is tilting from perpetual desktop licenses toward cloud-based subscription models across the construction software stack. Autodesk anchors its position through deep R&D investment in generative design and AI-assisted BIM workflows. Bentley Systems differentiates by dominating infrastructure-scale digital twin deployments for transportation and utility megaprojects. Trimble competes through its precision hardware-software integration, controlling field-to-office data pipelines for contractors and surveyors.
Construction and design software encompasses digital tools for architectural drafting, structural engineering simulation, construction sequencing, and facility lifecycle management, typically supporting file formats such as IFC for interoperability and parametric modeling for design iteration. Its primary commercial purpose is reducing material waste, compressing project schedules, and enabling multi-stakeholder coordination across distributed teams. BIM and project management segments lead current revenue contribution, reflecting their centrality to compliance documentation and capital project controls. Cloud-based and SaaS deployment modes represent the fastest-expanding structural category, as enterprise buyers shift capital expenditure to operational expenditure models and demand mobile accessibility for field personnel.
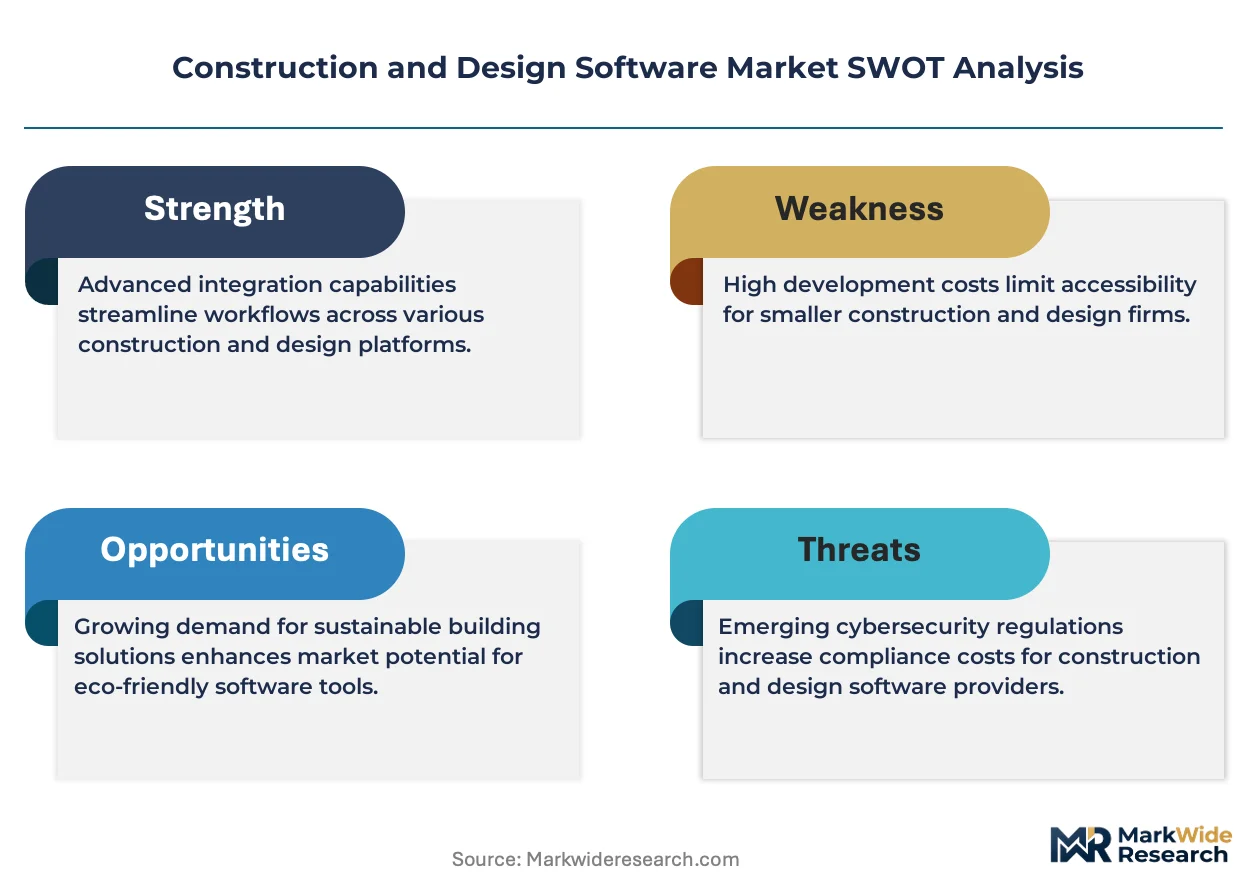
EMA's MDR framework and the EU AI Act shape algorithmic transparency requirements for automated design suggestion engines, while REACH and F-Gas Regulation indirectly drive software demand through material tracking and environmental reporting mandates. In the US, OSHA safety reporting standards and the SEC's climate disclosure rules push contractors toward integrated platforms that unify compliance documentation. Stakeholders must monitor how divergent transatlantic regulatory timelines for AI governance and embodied carbon accounting reshape platform certification requirements and buyer procurement criteria.
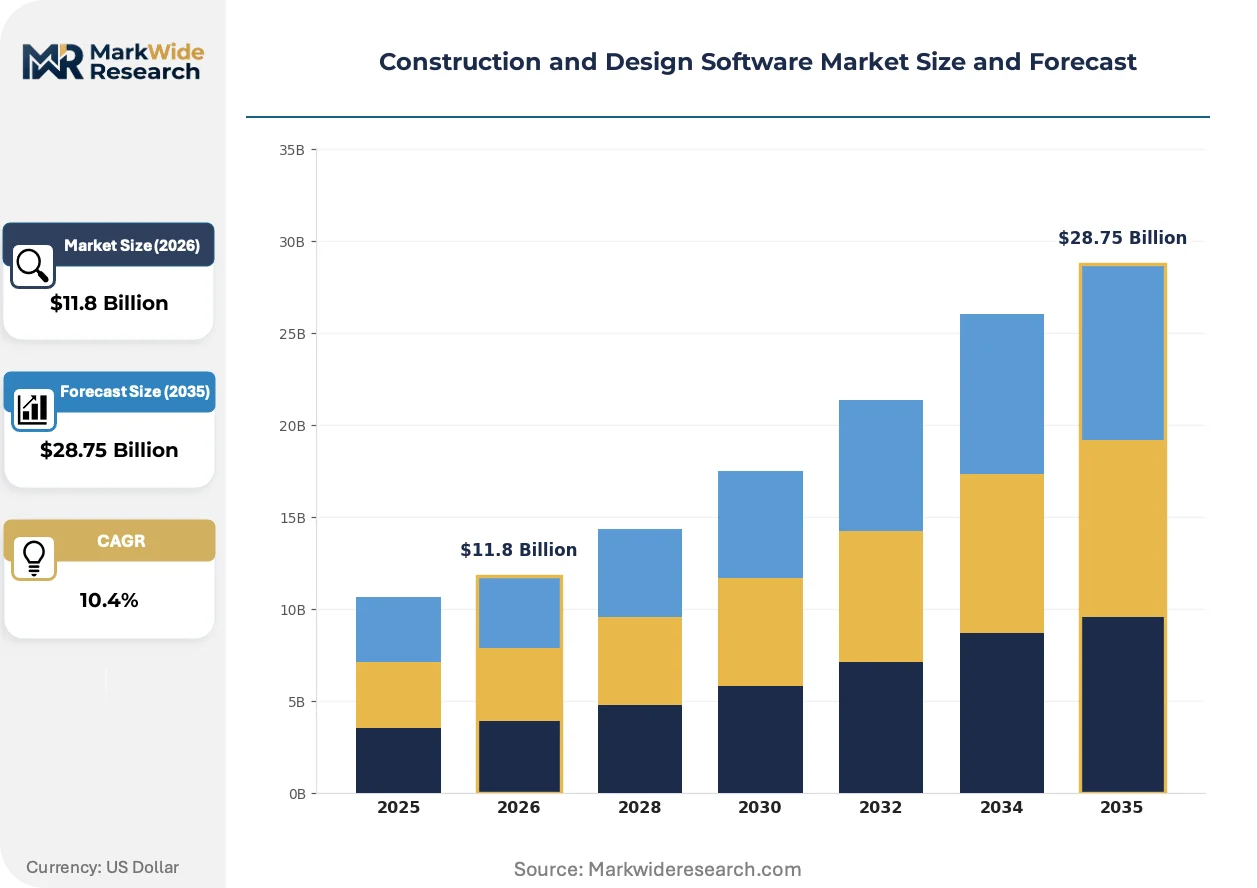
Market Dynamics
Cloud migration is collapsing the perpetual licensing model across construction software, forcing vendors to rebuild revenue architectures around recurring subscriptions while field personnel demand mobile-first workflows.
Growth Catalysts
- EU Green Deal retrofit mandates:National building energy codes in Germany, France, and the Netherlands require BIM-compliant documentation for public procurement, accelerating platform upgrades among engineering consultancies.
- Generative design algorithms:AI-assisted parametric modeling reduces material waste in early-stage structural optimization, pulling architects toward integrated design-to-fabrication workflows.
- Federal infrastructure renewal:Germany's transport ministry digital twin requirements for rail and highway megaprojects are expanding Bentley Systems' infrastructure software deployments.
Market Restraints
- Interoperability friction:Proprietary file formats from Autodesk and Trimble create data lock-in, raising switching costs for multi-vendor environments and delaying IFC standard adoption.
- Cloud dependency risks:Concentrated hyperscaler infrastructure in US East and West Coast regions exposes European contractors to data sovereignty conflicts under GDPR cross-border transfer rules.
- Skill scarcity:Shortages of BIM coordinators and computational designers in France and the UK constrain deployment velocity for midsize architectural practices.
Strategic Opportunities
- India's smart cities mission:Urban development authorities in Mumbai and Bangalore are piloting digital twin platforms for water distribution and transit planning, opening greenfield procurement channels.
- Embodied carbon tracking:Integration of material databases with structural simulation tools addresses France's RE2020 environmental regulation and emerging SEC climate disclosure requirements.
- Edge-to-cloud field pipelines:Convergence of Trimble's precision GNSS hardware with real-time model synchronization enables surveyors to bypass traditional batch upload workflows.
Industry Challenges
- Legacy ERP integration:Construction firms running SAP or Oracle on-premise face 18-24 month timelines to synchronize financial project controls with cloud-based design platforms.
- Algorithmic transparency compliance:EMA's MDR framework and EU AI Act require documentation of automated design suggestion logic, forcing vendors to reengineer black-box optimization engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction and Design Software Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $28.75 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BIM, CAD, Project Management, 3D Modeling End User: Architects, Engineers, Contractors, Developers Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Technology: AI-Driven, VR, AR, Automation |
| Companies Covered | Autodesk, Bentley Systems, Trimble, Nemetschek Group, Procore Technologies, Oracle Corporation, Microsoft Corporation, SAP SE, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction and Design Software Market Strategic Shifts & Innovations
Generative AI and regulatory pressure on embodied carbon are compressing design iteration cycles while fragmenting procurement authority across project stakeholders.
Digital twin platforms are collapsing the separation between design-phase simulation and operational asset management. Infrastructure owners in Germany and the UK are mandating handover of as-built models with embedded sensor specifications, forcing designers to extend liability into facility operations. This convergence is eroding traditional boundaries between architectural practices and facilities management vendors.
REACH and F-Gas Regulation amendments are tightening material tracking requirements across EU construction supply chains. Software vendors must now integrate substance databases with BIM objects to automate hazardous material reporting, particularly for insulation and HVAC components. French engineering consultancies are prioritizing platforms with pre-validated environmental product declaration libraries.
Subscription fatigue among midsize contractors is fragmenting procurement decisions away from centralized IT departments. German commercial builders are unbundling project management licenses by trade specialty, with steel fabricators and MEP installers selecting niche SaaS tools over enterprise suites. This shift pressures Autodesk and Trimble to modularize pricing or risk disintermediation by vertical-specific challengers.
Construction and Design Software Market Segmentation
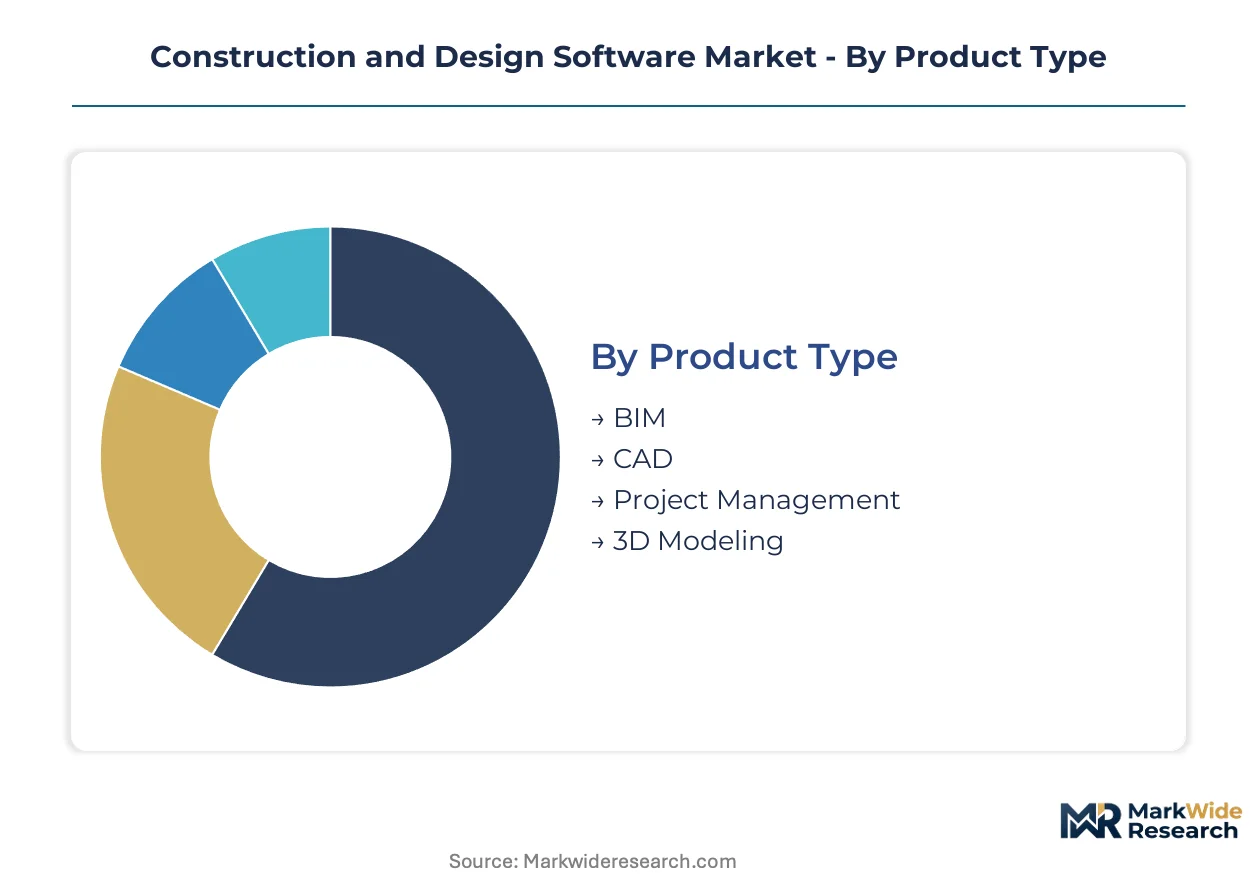
Segmentation in construction and design software reveals how procurement authority fragments across technical specializations and deployment preferences. Understanding these divisions exposes where platform vendors must modularize offerings to capture spend from distinct buyer cohorts.
Product Type:
Mature architectural drafting tools coexist with emerging generative design engines, creating a bifurcated procurement landscape where legacy upgrade cycles run parallel to experimental AI deployments.
- BIM:Building Information Modeling platforms integrate parametric 3D geometry with embedded data attributes for structural, MEP, and clash detection workflows. German federal retrofit mandates and France's RE2020 environmental compliance rules are pulling engineering consultancies toward BIM-compliant documentation systems. BIM retains volume leadership; Project Management holds the steepest expansion curve.
- CAD:Computer-aided drafting software provides 2D technical documentation and precision geometry for manufacturing and construction detailing. Midsize architectural practices in the UK and Netherlands maintain CAD licenses for legacy drawing archives while piloting BIM transitions. CAD retains volume leadership; 3D Modeling holds the steepest expansion curve.
- Project Management:Cloud-based scheduling, cost control, and resource allocation platforms unify field-to-office coordination for commercial contractors.
- 3D Modeling:Mesh-based visualization and rendering tools support conceptual design exploration and client presentation workflows.
Project Management platforms are climbing the fastest as subscription models displace perpetual licenses across contractor procurement.
End User:
Cost tier stratification separates enterprise engineering conglomerates from solo architectural practitioners, with procurement authority increasingly decentralizing to trade-specific subcontractors.
- Architects:Design-focused practitioners prioritize visualization fidelity and generative iteration speed for early-stage concept development. French and UK studios face skill scarcity in computational design, constraining deployment of advanced parametric tools. Architects retain volume leadership; Contractors hold the steepest expansion curve.
- Engineers:Structural and MEP specialists demand simulation accuracy and code compliance automation for safety-critical calculations. German transport ministry digital twin requirements for rail megaprojects are expanding infrastructure-scale engineering software deployments. Engineers retain volume leadership; Developers hold the steepest expansion curve.
- Contractors:Commercial builders and specialty trades coordinate procurement, scheduling, and field execution through integrated project controls.
- Developers:Real estate owners and asset managers leverage software for feasibility modeling, pro forma integration, and lifecycle cost analysis.
Contractor segment adoption is expanding most quickly as field personnel demand mobile-first workflows and real-time model synchronization.
Deployment:
Application criticality drives divergence between security-sensitive on-premise financial systems and collaboration-dependent cloud design environments.
- Cloud-Based:Browser-accessible platforms with automatic updates and multi-tenant infrastructure eliminate local server maintenance for distributed teams. GDPR cross-border transfer uncertainties and concentrated US hyperscaler exposure create data sovereignty friction for European contractors evaluating cloud migration. Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
- On-Premises:Locally installed software with perpetual licensing maintains air-gapped security for classified infrastructure and defense projects. German and French government procurement rules for sensitive transport and utility data sustain on-premise demand despite cloud pressure. On-Premises retains volume leadership; Hybrid holds the steepest expansion curve.
- Hybrid:Split architectures keep sensitive financial and HR data on-premise while design collaboration shifts to cloud instances.
- SaaS:Subscription-native platforms with API-first architectures enable modular integration with vertical-specific field tools.
SaaS deployment is gaining share fastest as operational expenditure models displace capital-intensive license purchases across midsize practices.
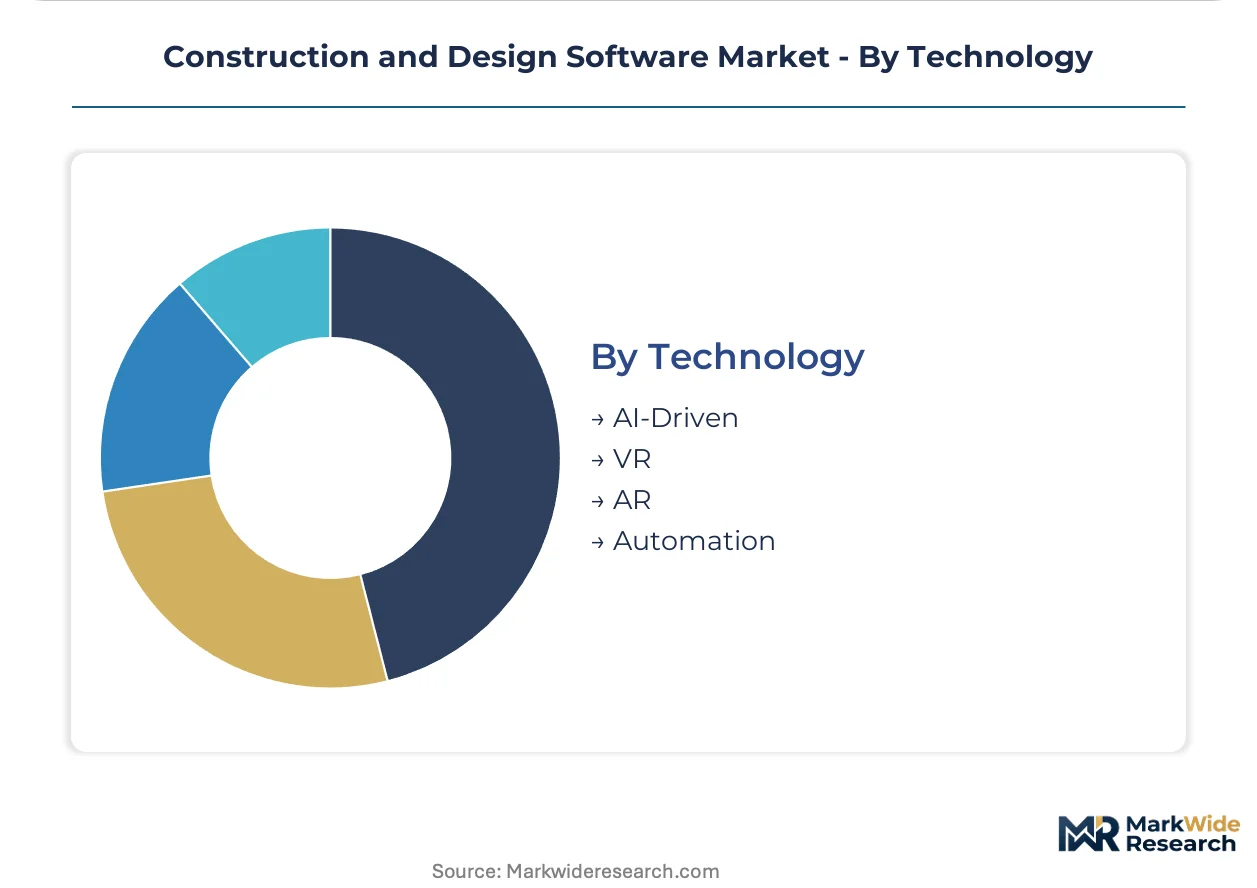
Technology:
Customer type separates early-adopter enterprises piloting immersive visualization from risk-averse institutions awaiting regulatory clarity on automated decision systems.
- AI-Driven:Machine learning algorithms automate design optimization, code compliance checking, and predictive cost forecasting from historical project data. EMA's MDR framework and EU AI Act transparency requirements are forcing vendors to reengineer black-box suggestion engines for documented audit trails. AI-Driven retains volume leadership; AR holds the steepest expansion curve.
- VR:Headset-based immersive environments enable spatial walkthroughs and stakeholder design reviews before construction commencement.
- AR:Overlay visualization aligns digital models with physical site conditions through tablet and wearable displays for field crews.
- Automation:Robotic process automation streamlines repetitive documentation tasks including specification generation and submittal package assembly.
AR technology is expanding most quickly as hardware costs decline and construction superintendents adopt tablet-based model alignment for quality assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German engineering consultancies absorb premium licensing costs to meet federal compliance mandates, while midsize UK architectural practices defer cloud migrations amid subscription fatigue and uncertain ROI timelines.
Germany
Federal retrofit mandates and transport ministry digital twin requirements for rail megaprojects dominate software procurement. The EU Green Deal's building energy codes force BIM-compliant documentation across public infrastructure tenders. Engineering clusters in Munich and Stuttgart drive enterprise platform deployments for structural simulation and clash detection workflows.
United States
OSHA safety reporting standards and SEC climate disclosure rules push contractors toward integrated compliance platforms. Commercial builders in Texas and Florida unbundle project management licenses by trade specialty, favoring niche SaaS tools over enterprise suites. The Pacific Northwest hosts early pilots of edge-to-cloud field pipelines linking precision hardware with real-time model synchronization.
United Kingdom
Skill scarcity in BIM coordination and computational design constrains deployment velocity for midsize London and Manchester studios. GDPR cross-border transfer uncertainties create data sovereignty friction for cloud migration decisions. Infrastructure owners mandate as-built model handovers with embedded sensor specifications, extending designer liability into facility operations.
France
RE2020 environmental regulation drives demand for embodied carbon tracking integrated with structural simulation tools. Engineering consultancies in Paris and Lyon prioritize platforms with pre-validated environmental product declaration libraries. ANSM and CNIL oversight shapes algorithmic transparency requirements for automated design suggestion engines.
India
Urban development authorities in Mumbai and Bangalore pilot digital twin platforms for water distribution and transit planning, opening greenfield procurement channels. National smart cities mission funding accelerates digital infrastructure investment. Maharashtra and Karnataka state governments compete to attract software vendor partnerships for megaproject delivery.
Construction and Design Software Market Key Industry Players
Capability concentration sits with specialized engineering software developers; scale advantage sits with diversified enterprise technology conglomerates. The market structure tiers between infrastructure-focused digital twin specialists and horizontal project management platform providers. Strategic archetypes include precision hardware-software integrators, generative design algorithm developers, and compliance-native documentation platforms. Dominant competitive moves encompass modular pricing unbundling to counter subscription fatigue and strategic partnerships bridging legacy ERP systems with cloud-native design environments.
Within the infrastructure-scale engineering tier, Bentley Systems and Autodesk exemplify divergent specialization strategies. Bentley Systems anchors digital twin deployments for transportation and utility megaprojects through deep vertical integration with government procurement channels. Autodesk occupies a position spanning architectural drafting through AI-assisted BIM workflows, representing the breadth-first archetype against narrower infrastructure specialists. Nemetschek Group sits within the European compliance-native tier, leveraging geographic proximity to EU regulatory bodies for platform certification advantages.
| Leading Market Players |
|---|
| Autodesk |
| Bentley Systems |
| Trimble |
| Nemetschek Group |
| Procore Technologies |
| Oracle Corporation |
| Microsoft Corporation |
| SAP SE |
| Hexagon AB |
| Others |
Cost & Logistics Intelligence
Munich's engineering software cluster anchors European platform development capacity, concentrating R&D talent and localization expertise that downstream vendors leverage for premium pricing power in federal compliance segments. Cloud infrastructure hyperscalers in Frankfurt and Amsterdam create regional cost baselines that shape SaaS subscription tiers across the continent.
Pricing Analysis
After-sales service revenue from implementation support and training contracts drives lifetime value for enterprise platform vendors. The dominant pricing structure is subscription-tiered SaaS, with premium tiers bundling generative design modules and compliance-native documentation tools. Price differentiation rests on certification level for EU AI Act transparency and vertical integration with precision hardware. Pricing pressure stems from subscription fatigue among midsize contractors unbundling licenses by trade specialty. Solo architectural practitioners exhibit highest price sensitivity; German engineering conglomerates absorbing premium costs for federal retrofit mandate compliance show lowest.
Supply Chain Analysis
Supplier-financing facilities extended by hyperscaler infrastructure providers ease cash flow for SaaS vendors scaling multi-tenant deployments. Software development capacity concentrates in Germany, the United States, and India, with Bangalore hosting specialized AI/ML engineering teams for parametric modeling tools. Raw material dependencies include GPU compute instances, open-source geometry kernels, and environmental product declaration databases. Single-source vulnerability in concentrated US East and West Coast hyperscaler regions exposes European contractors to GDPR cross-border transfer friction. Distribution runs through direct enterprise sales teams and systems integrators serving defense and transport sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity permeates this market as procurement authority decentralizes from centralized IT departments to trade-specific subcontractors, creating vertical niches for specialized challengers.
For Market Incumbents: Pre-empt disintermediation by modularizing pricing architectures to match unbundled procurement patterns among German steel fabricators and MEP installers. Invest in certification engineering for EU AI Act algorithmic transparency requirements before enforcement timelines harden. Vertical integration into precision hardware-software stacks, following Trimble's field-to-office data pipeline model, defends against niche SaaS challengers eroding enterprise suite dominance.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with urban development authorities in Mumbai and Bangalore piloting digital twin platforms for greenfield procurement. Embodied carbon tracking modules integrated with structural simulation tools address France's RE2020 compliance gaps left by incumbent platforms. Go-to-market through engineering consultancy partnerships leverages existing client relationships and bypasses direct enterprise sales barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-native documentation platforms with pre-validated environmental product declaration libraries and EU regulatory certification advantages. Long-term viability over the next decade hinges on AI-assisted BIM workflow integration and digital twin handover capabilities extending designer liability into facility operations. Watch algorithmic transparency enforcement timelines as the inflection indicator for platform reengineering costs and competitive consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies legacy ERP systems with cloud-native design environments for SAP and Oracle users. |
| Acquisition of Specialist Firm | Captures niche SaaS tools serving unbundled trade procurement in German commercial construction. |
| Geographic Expansion | Establishes localized development capacity in Bangalore for India's smart cities mission pilots. |
| Product Launch | Introduces embodied carbon tracking modules addressing France's RE2020 environmental regulation. |
| Strategic Partnership | Bridges precision GNSS hardware with real-time model synchronization for surveyor workflows. |
Research Approach
The analysis maps BIM platforms, CAD tools, project management suites, and generative design engines, each validated through primary interviews with CTOs at engineering consultancies, IT procurement officers at commercial contractors, platform engineers at SaaS vendors, and integration specialists at systems integrators. Secondary validation draws from SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and construction industry trade association reports. Bottom-up sizing of deployment instances and top-down revenue triangulation across vendor disclosures ensure cross-verified outputs.
Assumptions held fixed include current EU AI Act enforcement timelines, GDPR cross-border transfer rule interpretations, and federal infrastructure renewal funding levels in Germany; varied assumptions include cloud migration velocity among midsize practices and embodied carbon tracking mandate expansion. The analytical framework models deployment mode, organization size, vertical specialization, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include BIM coordinator skill scarcity constraints and digital twin handover requirement adoption curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting construction capital expenditure, or infrastructure stimulus program continuity, would shift the trajectory. Forecasts reflect documented assumptions; regulatory enforcement acceleration, AI governance divergence between EU and US frameworks, or hyperscaler concentration policy intervention would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Enterprise Content Management Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Newsroom Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Global Dance Studio Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Consignment Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Tenant Billing Software Market
Software & Services
App Building Software Market
Software & Services
Global Handyman Software Market
Software & Services
Software Repository Market