
 Client Virtualization Software Market | 2026-2036
Client Virtualization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Client Virtualization Software Market Analysis
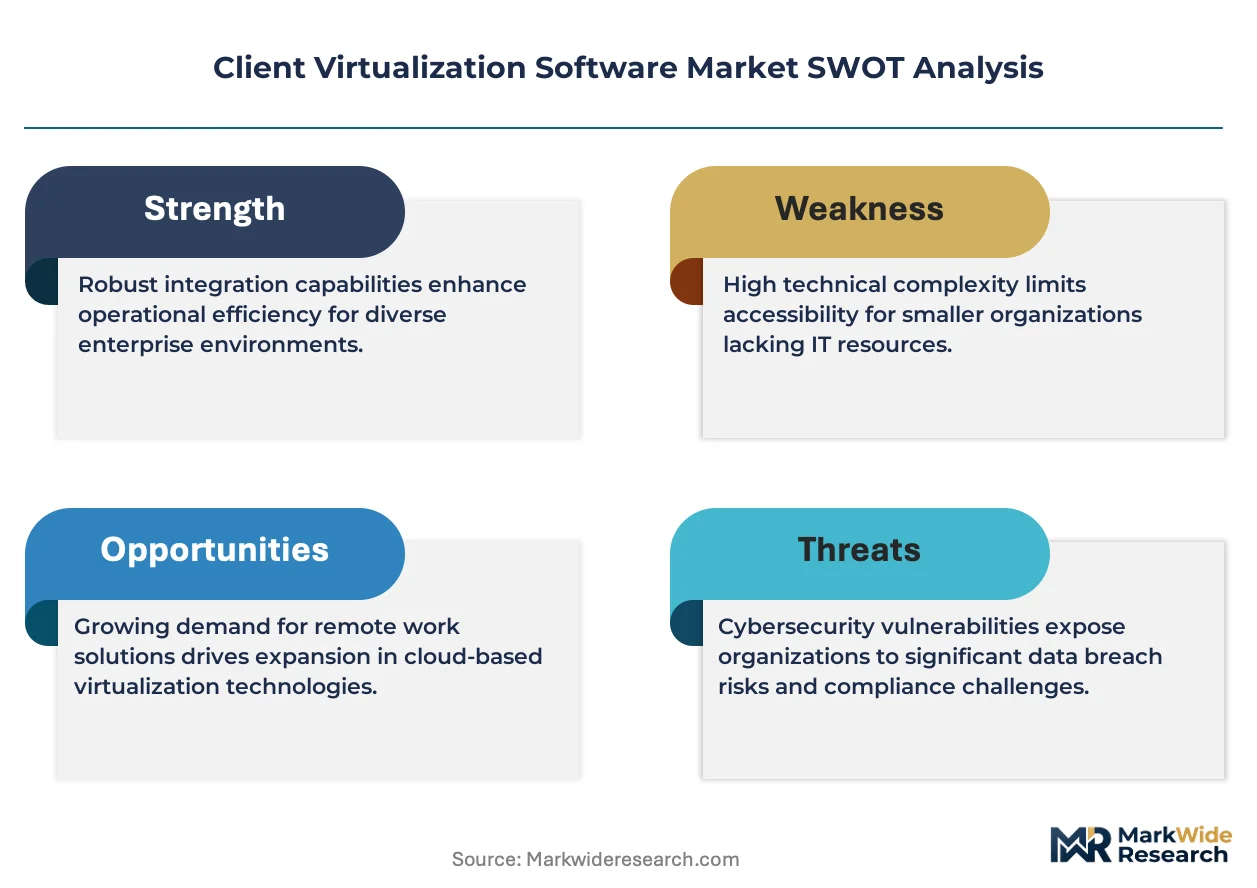
Container-based delivery is tilting the client virtualization stack away from monolithic VDI instances toward lighter, more elastic workload orchestration. Microsoft leverages its Azure Virtual Desktop integration to anchor enterprise hybrid deployments across regulated industries. Citrix competes through specialized application layering technologies that streamline patch management for complex software estates. Amazon extends its position via AppStream 2.0 streaming protocols that reduce client-side compute requirements for graphics-intensive workloads.
Client virtualization software decouples desktop environments, applications, and user profiles from physical endpoint hardware through hypervisor abstraction or container isolation, typically delivering operating system images via centralized servers to thin clients, browsers, or mobile devices. The technology serves commercial and industrial purposes by enabling secure remote access, simplifying IT administration, and reducing endpoint capital expenditure through centralized patch governance and data residency controls. Cloud-based deployment now captures the fastest expansion as organizations retire on-premise data center commitments, while application virtualization commands concentrated margin pools where software vendors bundle licensing with streaming delivery. Desktop virtualization retains volume leadership among enterprises with legacy Windows application dependencies, though container-based technology is displacing hypervisor architectures in DevOps-aligned environments.
The EU AI Act and NIS2 Directive impose stringent endpoint security and incident reporting obligations on virtualization platforms processing sensitive data across European member states. The US FDA and HIPAA frameworks shape healthcare adoption by mandating audit trails and access controls for clinical workstations delivered through virtual infrastructure. Stakeholders must monitor how zero-trust architecture mandates from national cybersecurity agencies are rewriting procurement specifications for endpoint virtualization before committing to multi-year platform contracts.
Market Dynamics
Container-based workload isolation is compressing the traditional hypervisor-dominated stack as DevOps teams demand elastic, API-driven desktop delivery that integrates with CI/CD pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare networks across France, Germany, and Italy are accelerating virtual desktop deployments to satisfy audit trail and data residency requirements for AI-assisted diagnostics.
- Thin client hardware refresh cycles:Industrial manufacturers in Germany are consolidating legacy terminal services onto modern application virtualization stacks to reduce endpoint capital expenditure.
- Hybrid cloud orchestration:Financial services firms are adopting Azure Virtual Desktop integration to anchor regulated workloads across on-premise and cloud infrastructure without re-architecting applications.
Market Restraints
- Specialized talent scarcity:Enterprise IT departments face acute shortages of engineers certified in Citrix and VMware virtualization stack administration, inflating implementation timelines.
- Graphics protocol licensing costs:Streaming delivery of GPU-intensive workloads through proprietary remote display protocols imposes per-user fees that compound at scale.
- Legacy application binding:Windows 7 and 32-bit application dependencies trap manufacturing and healthcare buyers on aging VDI platforms with limited vendor support.
Strategic Opportunities
- Edge computing convergence:Kubernetes-based container orchestration at branch locations enables low-latency virtual desktop delivery for retail and logistics operations without central data center dependency.
- India's digital workplace expansion:IT services exporters and banking shared services centers in Bangalore and Hyderabad represent underpenetrated demand for cloud-hosted desktop virtualization.
- Zero-trust architecture mandates:National cybersecurity agencies in the US and UK are rewriting procurement specifications to require continuous endpoint verification, favoring vendors with integrated identity and access management.
Industry Challenges
- Multi-vendor integration complexity:Enterprises stitching together identity providers, endpoint detection tools, and virtualization brokers face protracted deployment cycles and interoperability failures.
- Patch velocity mismatches:Operating system image update cycles lag behind security vulnerability disclosure timelines, exposing virtual desktop fleets to exploit windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Client Virtualization Software Market |
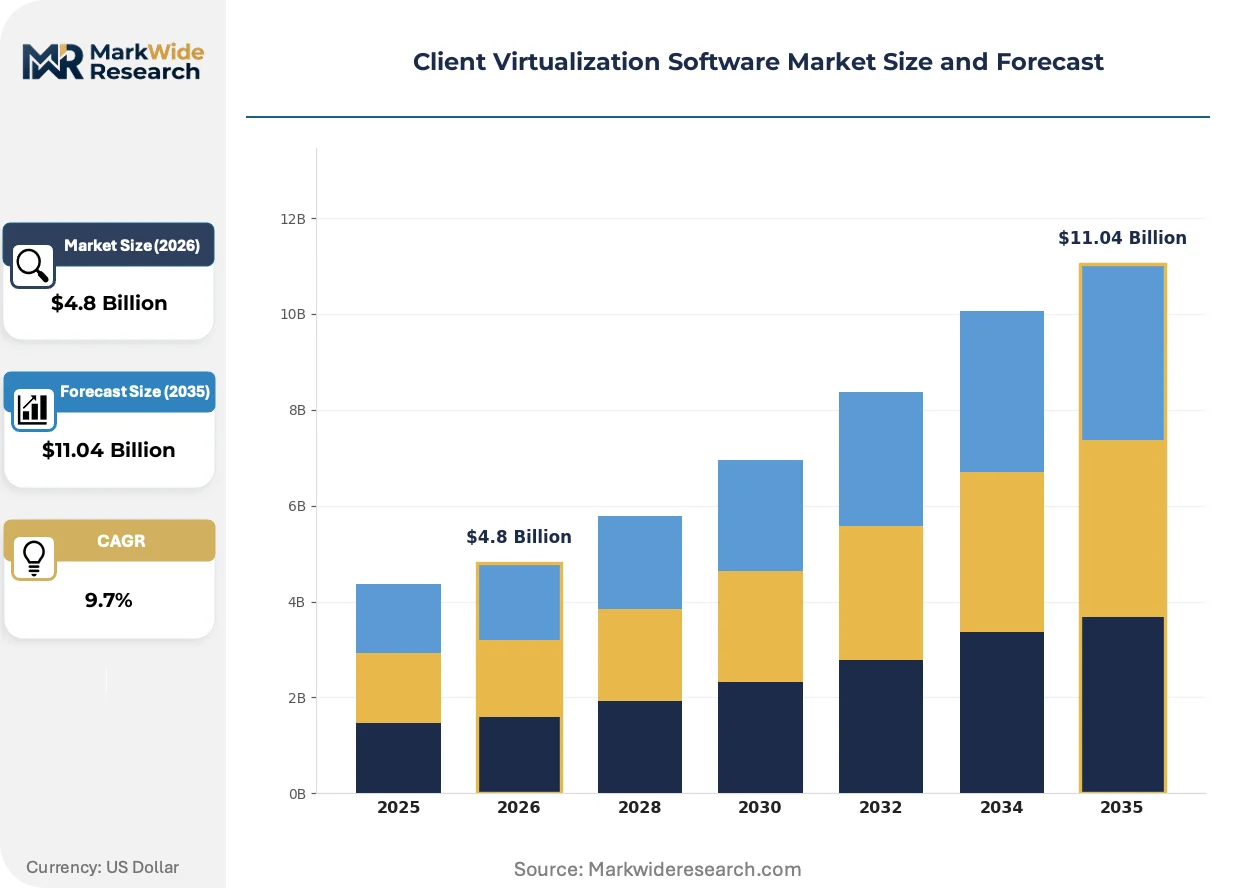
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Virtual Desktop Infrastructure End User: SMBs, Enterprises, Government, Educational Institutions Solution: Desktop Virtualization, Application Virtualization, User Virtualization, Device Virtualization Technology: Hypervisor-Based, Container-Based, VDI, Streaming |
| Companies Covered | Microsoft, Ericom, Citrix, TSplus, V2 Cloud, Inuvika, Parallels, Amazon, Omnissa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Client Virtualization Software Market Emerging Trajectories
Workload abstraction technologies are fragmenting the monolithic virtual desktop category into specialized delivery modes optimized for specific latency, security, and compute requirements.
Docker and Podman container runtimes are rendering obsolete traditional persistent VDI instances for development and analytics use cases. Software engineering teams at pharmaceutical and financial services firms are adopting containerized desktop environments that spin up in seconds rather than minutes. This shift is compressing infrastructure costs by eliminating the need for dedicated virtual machine overhead per user.
The EU NIS2 Directive imposes mandatory incident reporting and supply chain security obligations on virtualization platforms processing critical infrastructure data. Managed service providers operating across member states must now document endpoint isolation architectures and breach response protocols to national regulators. Healthcare delivery networks in Spain and the Netherlands are prioritizing vendors with pre-certified compliance frameworks to accelerate procurement.
Subscription-based consumption models are displacing perpetual licensing for on-premise virtualization stacks. Enterprise buyers in manufacturing and professional services are negotiating term contracts that bundle compute, storage, and software fees into predictable monthly expenditures. This preference is most visible in Germany, where industrial mid-caps seek to convert capital expenditure into operational expenditure for balance sheet optimization.
Client Virtualization Software Market Segmentation
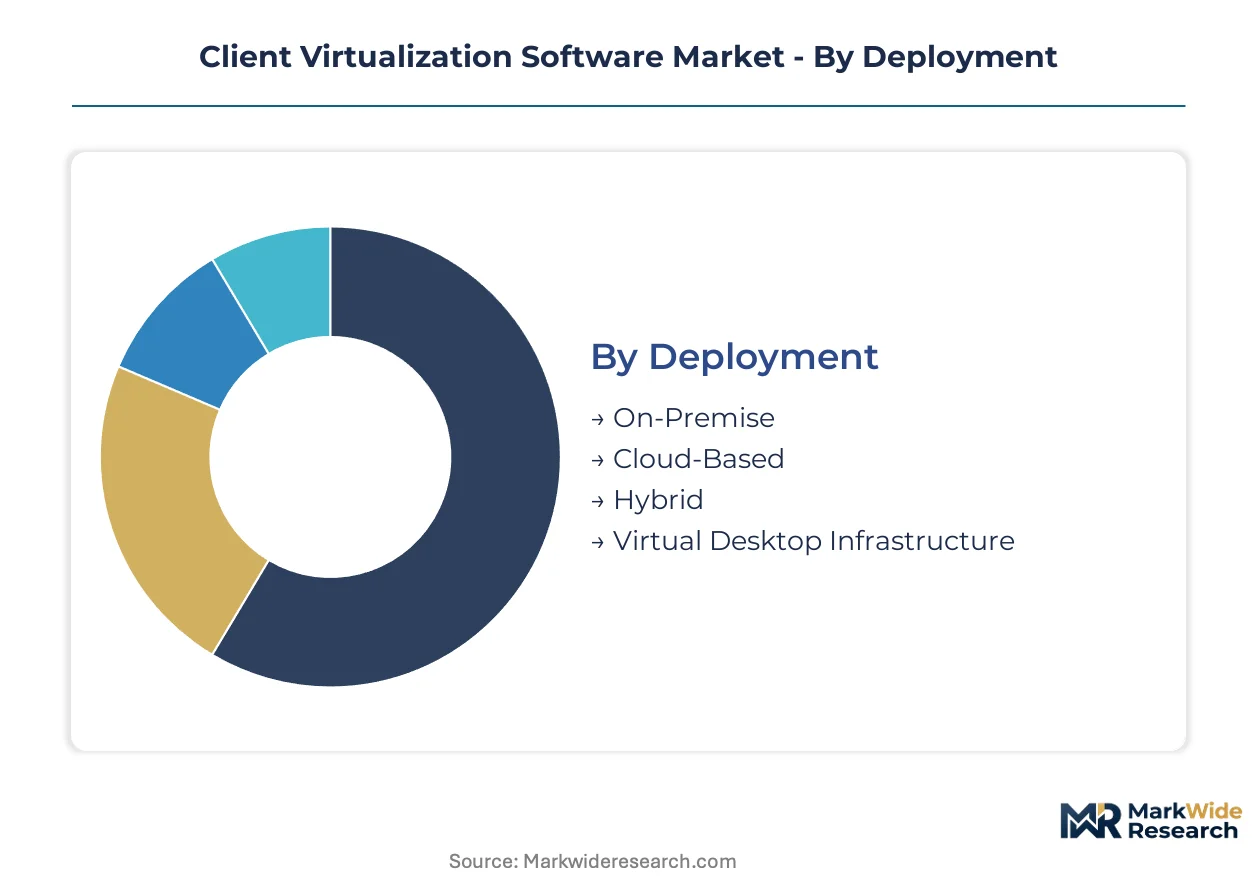
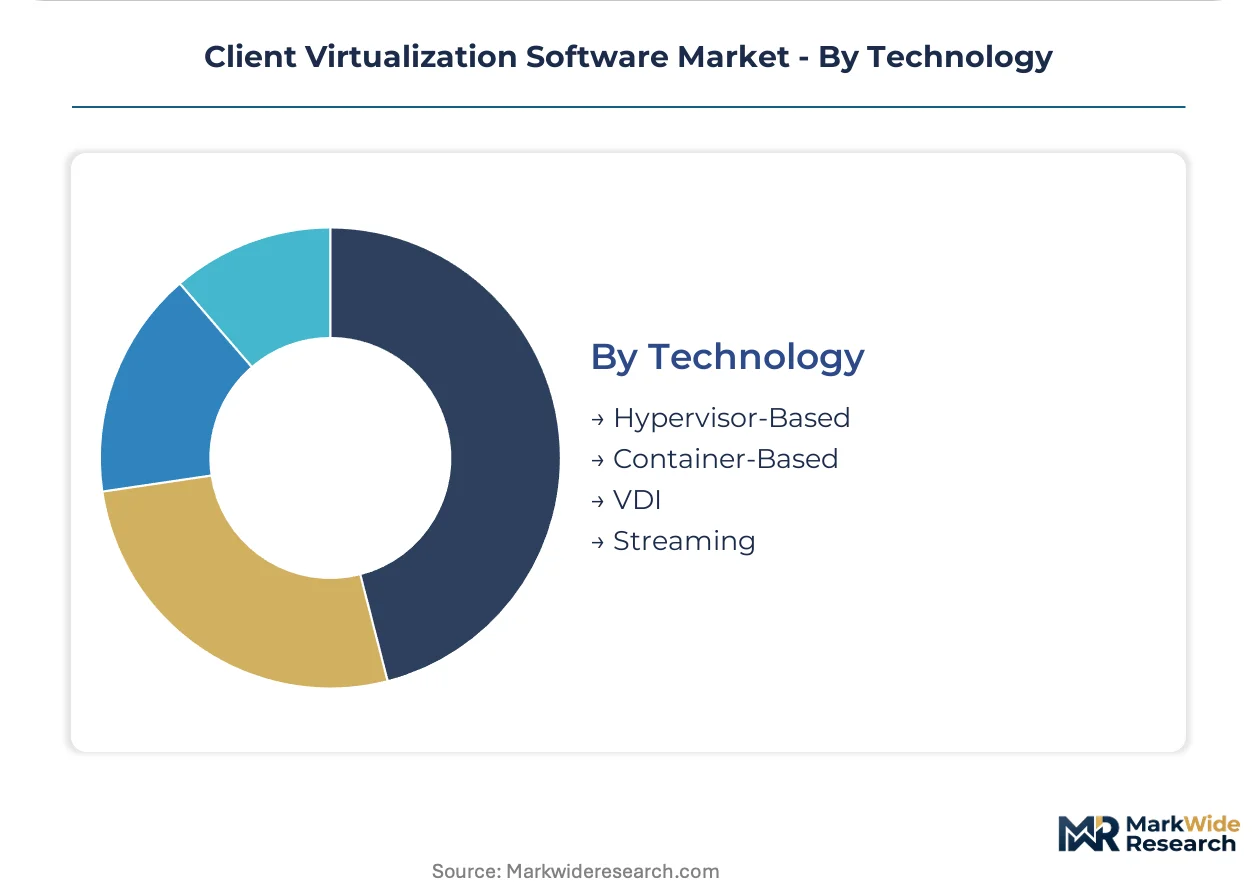
Client virtualization software procurement varies sharply across deployment models, end-user scale, solution architecture, and underlying technology. Buyers optimize for capital efficiency, compliance posture, or developer velocity depending on organizational maturity and workload characteristics.
Deployment:
Cost tier determines infrastructure ownership obligations and operational expenditure predictability for virtualization buyers.
- On-Premise:Organizations retain full hardware and data center responsibility for hypervisor clusters and storage arrays. German industrial manufacturers favor this model for air-gapped production environments where cloud connectivity violates operational technology security protocols.
- Cloud-Based:Third-party providers host virtual desktop and application workloads across distributed availability zones. Financial services firms in France and the Netherlands are migrating here to satisfy EU AI Act data residency requirements without building sovereign data centers.
- Hybrid:Workloads split between owned infrastructure and public cloud based on sensitivity and latency requirements. Healthcare networks use this architecture to keep patient imaging data on-premise while bursting administrative desktops to cloud during seasonal demand spikes.
- Virtual Desktop Infrastructure:Purpose-built VDI platforms deliver persistent or non-persistent desktop sessions from centralized server farms. This deployment mode retains dominance in regulated industries with legacy Windows application dependencies.
On-Premise retains the installed base across manufacturing and defense sectors. Cloud-Based is climbing the fastest as regulated industries retire data center commitments.
End User:
Customer type shapes procurement complexity, integration requirements, and vendor support expectations.
- SMBs:Mid-sized organizations prioritize turnkey managed services with predictable per-user monthly fees. These buyers lack dedicated virtualization engineering staff and favor bundled endpoint management.
- Enterprises:Large organizations operate multi-thousand seat deployments across heterogeneous identity providers and security stacks. Demand concentrates in banking and pharmaceuticals where Citrix and VMware certifications command salary premiums.
- Government:Public sector buyers mandate FedRAMP, DISA STIG, or national sovereign cloud certifications before procurement. Defense and civilian agencies in the US and EU member states drive specialized compliance roadmaps.
- Educational Institutions:Universities and K-12 districts seek semester-scale elasticity for student lab environments. Budget constraints favor open-source hypervisors and thin client hardware refresh cycles aligned with fiscal year funding.
Enterprises anchor current revenue concentration. Educational Institutions are expanding most quickly as remote learning infrastructure becomes permanent.
Solution:
Application focus determines whether buyers virtualize full desktops, individual applications, user profiles, or endpoint hardware abstraction layers.
- Desktop Virtualization:Complete operating system environments stream to endpoint devices from centralized data centers or cloud regions. Healthcare delivery networks deploy this solution to secure clinical workstation access across distributed hospital campuses.
- Application Virtualization:Individual software packages execute on servers while rendering interfaces to local devices. Manufacturing engineers in Germany use this to isolate legacy CAD tools from modern endpoint operating systems.
- User Virtualization:Profile and personalization data separate from underlying desktop images for rapid session portability. This architecture accelerates IT helpdesk resolution times in call center and shared services environments.
- Device Virtualization:Peripheral hardware abstraction enables USB, printer, and scanner redirection across network boundaries. Logistics and retail operations depend on this capability for warehouse workstation standardization.
Desktop Virtualization holds the dominant share. Application Virtualization is gaining share fastest as container runtimes displace monolithic VDI for specific workloads.
Technology:
Underlying isolation mechanism determines resource efficiency, startup latency, and compatibility with modern DevOps workflows.
- Hypervisor-Based:Type 1 or Type 2 hypervisors partition physical server resources into isolated virtual machines. This mature technology powers the majority of production VDI fleets in enterprise data centers.
- Container-Based:OS-level isolation via Docker or Podman runtimes delivers lighter, faster-provisioning desktop environments. Pharmaceutical and financial services development teams are adopting this for CI/CD-integrated workstation delivery.
- VDI:Purpose-built virtual desktop infrastructure protocols optimize for graphics rendering and peripheral redirection. Brokering and connection management software from specialized vendors dominates this segment.
- Streaming:Application execution occurs entirely on servers with pixel-level display transmission to clients. Amazon AppStream 2.0 and comparable protocols reduce client-side compute requirements for GPU-intensive engineering and media workloads.
Hypervisor-Based technology commands the established deployment base. Container-Based approaches are expanding most quickly as development organizations reject virtual machine overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software virtualization exports flow predominantly from US and German vendors toward healthcare and industrial buyers in import-dependent European and Asia-Pacific markets. Trade balances favor net exporters with established cloud infrastructure and compliance certification pipelines. Currency volatility and data localization mandates are reshaping cross-border licensing terms.
United States
Federal agencies and defense contractors drive demand for FedRAMP-authorized virtual desktop platforms with zero-trust architecture integration. The FDA and HIPAA frameworks mandate audit trails for clinical workstations delivered through virtual infrastructure. Healthcare delivery networks in Boston and the Research Triangle are consolidating legacy terminal services onto cloud-native stacks to satisfy cybersecurity executive orders.
Germany
Industrial manufacturers in Baden-Württemberg and North Rhine-Westphalia are retiring on-premise data center commitments in favor of hybrid cloud orchestration for engineering workstations. The EU AI Act and NIS2 Directive impose mandatory incident reporting on virtualization platforms processing operational technology data. Munich-based automotive suppliers are bundling application virtualization with subscription-based consumption models to optimize balance sheet structures.
France
Banking shared services centers in Paris and Lyon are adopting Azure Virtual Desktop integration to anchor regulated workloads across sovereign and cloud infrastructure. The CNIL enforces GDPR-aligned data residency controls on endpoint virtualization processing personal data. Pharmaceutical firms in the Île-de-France region are deploying container-based development environments to accelerate CI/CD pipelines for AI-assisted diagnostics.
India
IT services exporters and banking shared services centers in Bangalore and Hyderabad represent expanding demand for cloud-hosted desktop virtualization with predictable per-user economics. The RBI mandates multi-factor authentication and transaction logging for virtual workstations accessing core banking systems. Telangana's government cloud initiative is pre-certifying domestic virtualization vendors to reduce import dependency for public sector deployments.
United Kingdom
Financial services firms in London and Edinburgh are rewriting procurement specifications to require continuous endpoint verification under national cybersecurity agency guidance. The UK National Cyber Security Centre mandates supply chain security documentation for virtualization platforms processing critical infrastructure data. Manchester-based logistics operations are deploying edge-computing converged stacks for low-latency warehouse workstation delivery.
Client Virtualization Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: hyperscale cloud platforms with native virtualization services, specialized broker vendors with application layering expertise, and emerging container-native challengers displacing hypervisor architectures. Strategic archetypes include subscription revenue optimizers, compliance certification specialists, and DevOps-integrated workstation providers. Dominant competitive moves encompass strategic partnerships with identity management vendors and geographic expansion through managed service provider channels.
Within the hyperscale tier, Microsoft and Amazon anchor enterprise hybrid deployments with integrated cloud infrastructure and streaming protocol portfolios. Citrix occupies a position exemplifying the specialized broker archetype, with application layering technologies targeting complex software estates in regulated industries. Ericom represents the security-centric specialization vector, serving government and defense buyers with zero-trust-aligned remote access architectures.
| Leading Market Players |
|---|
| Microsoft |
| Ericom |
| Citrix |
| TSplus |
| V2 Cloud |
| Inuvika |
| Parallels |
| Amazon |
| Omnissa |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on hyperscale cloud infrastructure providers determines both tiered pricing spreads and supply chain configuration across the client virtualization software market. Regulatory chokepoints in data residency certification compress margins for non-compliant vendors while concentrating procurement power among FedRAMP and EU sovereign cloud authorized suppliers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the client virtualization software market. Premium tiers bundle managed security operations and zero-trust architecture integration, while economy tiers strip professional services to bare per-user licensing. Price differentiation hinges on certification grade—FedRAMP High and EU sovereign cloud authorizations command substantial premiums over standard commercial deployments. Cost compression in mid-market segments is intensifying because container-native challengers are undercutting legacy hypervisor vendors with consumption-based models. SMB buyers exhibit acute price sensitivity, whereas defense contractors and pharmaceutical firms prioritize compliance posture over per-seat economics.
Supply Chain Analysis
Extended payment terms from hyperscale cloud providers reshape working capital requirements for virtualization software vendors competing on infrastructure resale. Software development concentrates in the United States, Germany, and India, with engineering talent pools in Bangalore and Berlin feeding product innovation cycles. Raw material dependencies center on GPU silicon from Taiwan, enterprise storage arrays from South Korea, and identity management middleware from domestic European vendors. Single-source vulnerability in graphics protocol licensing—particularly for GPU-intensive streaming workloads—creates margin exposure when per-user fees reset annually. Distribution runs through managed service provider channels in regulated verticals, with direct enterprise sales dominating government and healthcare accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT refresh cycles are accelerating after deferred modernization during macroeconomic uncertainty, positioning client virtualization software for cyclical recovery as organizations resume infrastructure commitments.
For Market Incumbents: Pre-empt container-native displacement by embedding Kubernetes orchestration into existing broker platforms before DevOps-aligned buyers complete stack replacements. Acquire specialized compliance certification capabilities—particularly EU sovereign cloud and FedRAMP High authorizations—to defend against emerging security-centric challengers eroding margin in government verticals. Expand professional services capacity in Germany and France where NIS2 Directive implementation is compressing deployment timelines for under-staffed enterprise IT departments. For New Entrants and Emerging Players: Mid-market healthcare delivery networks in Spain and the Netherlands represent the most penetrable entry point, as these buyers prioritize pre-certified compliance frameworks over incumbent brand recognition. Container-based development environments for pharmaceutical R&D teams in Basel and Cambridge offer specialized wedge opportunities where legacy VDI performance frustrates CI/CD integration. Pursue managed service provider co-sell arrangements rather than direct field sales to bypass entrenched channel relationships. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape by elevating vendors with documented audit trail architectures above commodity broker providers. Target firms holding dual FedRAMP and EU sovereign cloud certifications with established healthcare and defense revenue concentration. Monitor zero-trust architecture mandate adoption curves across UK and US national cybersecurity agencies as the primary inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Integration | NCSC and CISA mandates are rewriting procurement specifications for endpoint verification. |
| Container-Native Platform Development | Docker and Podman runtimes displace hypervisor overhead in DevOps-aligned pharmaceutical environments. |
| EU Sovereign Cloud Certification | CNIL enforcement of GDPR-aligned data residency controls blocks non-compliant vendors from French banking. |
| Managed Service Provider Channel Expansion | German industrial mid-caps seek turnkey consumption models converting capital expenditure to operational expenditure. |
| GPU Streaming Protocol Licensing | Amazon AppStream 2.0 and comparable protocols reduce client-side compute requirements for engineering workloads. |
Methodological Framework
Cross-validation between primary interviews with virtualization architects and secondary analysis of hyperscaler capex disclosures anchors the qualitative findings in this study. Conversations with CTOs, IT procurement officers at healthcare delivery networks, platform engineers in financial services, channel partners distributing Citrix and VMware stacks, and integration specialists implementing Azure Virtual Desktop deployments informed demand-side assumptions. Secondary validation drew from SEC 10-K filings of publicly traded software vendors, EMA and FDA guidance documents on clinical workstation security, EU NIS2 Directive implementation timelines, and cloud infrastructure spending reports. Bottom-up seat-count modeling triangulated against top-down addressable market sizing from national healthcare and banking employment statistics.
Calibration against historical virtualization adoption curves in regulated verticals shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture (on-premise, cloud-based, hybrid), organization scale (SMB, enterprise, government), solution type (desktop, application, user, device virtualization), and underlying isolation technology (hypervisor-based, container-based, streaming). CAGRs were derived from elasticity-adjusted seat growth rates applied to per-user pricing trajectories observed in subscription contract renewals. Industry-specific inputs incorporated EU AI Act compliance deadline impacts on healthcare procurement cycles and thin client hardware refresh patterns in German manufacturing.
Practitioners should monitor regulatory enforcement intensity, hyperscaler pricing resets, and container runtime standardization for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Audio Editing Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Resonator Design Software Market
Software & Services
Laser Engraving Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Business Analytics Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
LTFS Copy Software Market
Software & Services
Global License Management Market
Software & Services
Sales Intelligence Software Market