
 Electronic Design Automation Software Market | 2026-2036
Electronic Design Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Design Automation Software Market Intelligence
REACH is rebalancing the cost-of-entry calculus for EDA vendors serving European semiconductor customers, forcing compliance investments in material traceability modules. Synopsys leverages its analog-digital co-design platform to anchor advanced node workflows for European automotive chip designers. Cadence Design Systems sustains R&D intensity in RF simulation tools that compete directly with Keysight Technologies' physical test instrumentation. Siemens EDA differentiates through tight integration with its manufacturing execution systems, occupying a unique position in fab-to-design feedback loops.
Electronic Design Automation Software comprises computer-aided tools for designing, verifying, and manufacturing electronic systems, with functional parameters spanning transistor-level simulation at sub-3nm geometries through system-level thermal and electromagnetic analysis. Its primary commercial purpose is compressing design cycle time while ensuring first-pass silicon success for integrated circuits and printed circuit boards. Simulation tools command the deepest margin pools as physical verification complexity explodes at each process node shrink. Cloud-based deployment is gaining fastest among fabless startups that lack capital for on-premise server farms, though hybrid architectures dominate among established semiconductor companies with existing data center investments. Mixed-signal design technology is accelerating as automotive radar and lidar systems proliferate, bridging the gap between mature analog expertise and digital automation.
The EU Chips Act, alongside FDA scrutiny of medical device electronics and China's GB standards for semiconductor equipment, is fragmenting compliance requirements across jurisdictional boundaries. EDA vendors must now embed region-specific verification rule decks directly into their tool chains, raising switching costs for multinational chip designers. Stakeholders should monitor how export control lists from the US Department of Commerce and EU dual-use regulations reshape which simulation algorithms can be deployed across foundry locations.
Market Dynamics
Advanced node migration below 3nm geometries is forcing EDA vendors to rebuild physical verification engines from first principles, as traditional rule-based checking collapses under quantum tunneling effects and parasitic extraction complexity.
Growth Catalysts
- Automotive radar proliferation:Lidar and millimeter-wave sensor deployment in German and Japanese vehicle platforms is accelerating mixed-signal design tool procurement.
- REACH compliance mandates:European material traceability requirements are embedding verification rule decks directly into EDA workflows, raising switching costs for multinational designers.
- Cloud-native startups:Fabless semiconductor ventures without captive data centers are adopting SaaS simulation licenses fastest among all buyer segments.
Market Restraints
- Foundry concentration:Taiwan's Hsinchu corridor controls over 90% of leading-edge capacity, creating single-point vulnerability for EDA tool roadmapping.
- Algorithm export controls:US Department of Commerce dual-use restrictions limit electromagnetic simulation deployment across certain foundry locations.
- Legacy code entrenchment:Decades-old SPICE kernel architectures resist parallelization for GPU acceleration, capping performance gains.
Strategic Opportunities
- EU Chips Act incentives:Dresden and Leuven fab investments are creating captive demand for sovereign EDA capability independent of US and Asian vendors.
- Photonics-electronics convergence:Silicon photonics design automation remains underserved, with co-simulation between optical and electrical domains nascent.
- India PLI scheme:Semiconductor manufacturing subsidies in Gujarat and Karnataka are seeding first domestic EDA procurement outside traditional design services.
Industry Challenges
- Quantum device modeling expertise:Fewer than two hundred engineers worldwide possess combined expertise in condensed matter physics and commercial EDA tool development.
- Multi-physics integration:Thermal, electromagnetic, and mechanical co-simulation workflows require manual handoffs that break automation chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Design Automation Software Market |
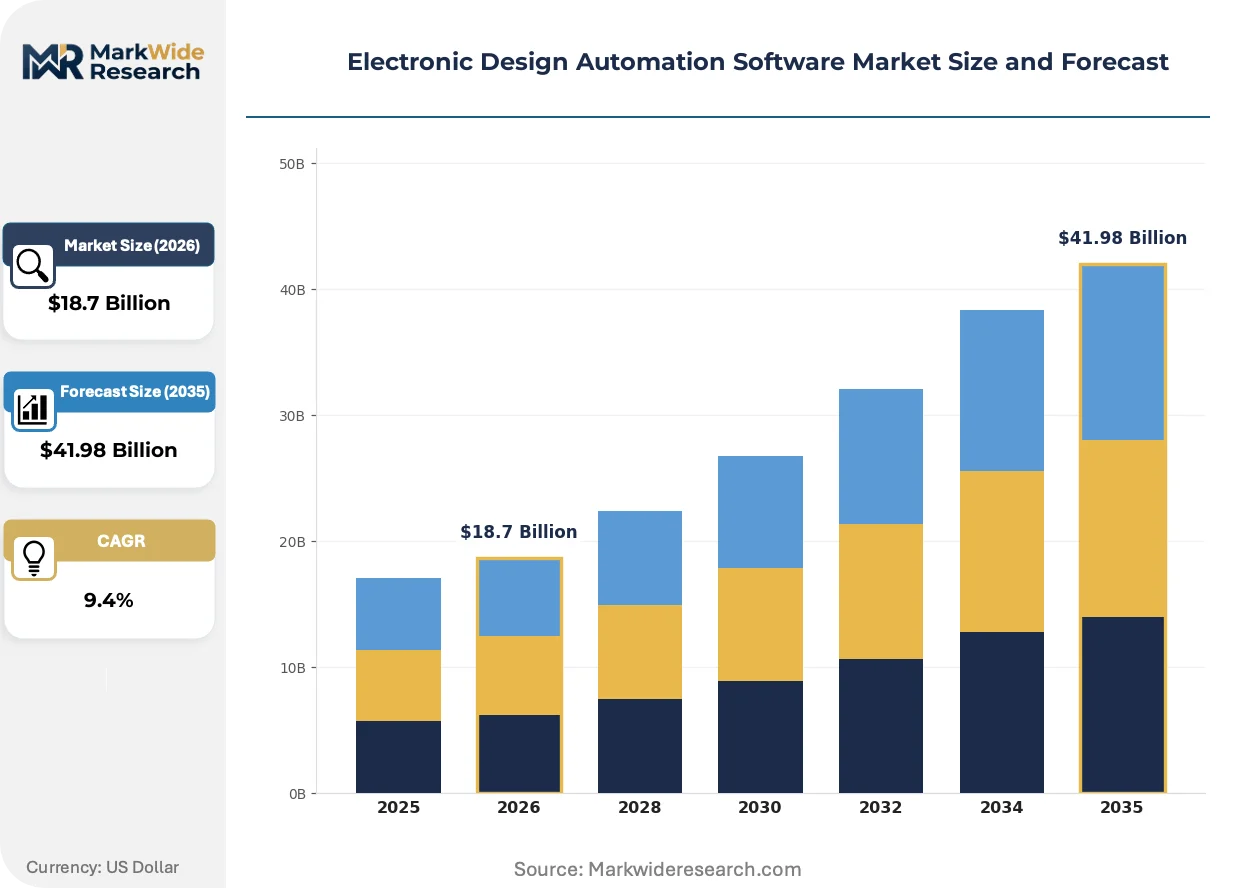
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schematic Capture, PCB Design, Simulation, Layout End User: Semiconductor Companies, Automotive Manufacturers, Consumer Electronics, Aerospace Technology: Analog, Digital, Mixed-Signal, RF Deployment: Cloud-Based, On-Premise, Hybrid, Open Source |
| Companies Covered | Ansys, Zuken, Synopsys, Silvaco, Altium, Cadence Design Systems, Keysight Technologies, Aldec, Siemens EDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Design Automation Software Market Strategic Shifts & Innovations
Generative AI is penetrating EDA workflows at three distinct layers: architecture exploration, layout synthesis, and test pattern generation. This transformation is compressing design cycles while raising fundamental questions about verification completeness and tool trustworthiness.
Machine learning-accelerated place-and-route is rewriting physical design economics. Cadence and Synopsys have deployed reinforcement learning agents that optimize floorplans against multi-objective constraints. Fabless AI chip designers in Taiwan and Israel are adopting these tools fastest, cutting iteration cycles from weeks to days. The technology is rewriting staffing ratios between physical designers and verification engineers.
REACH and RoHS material restrictions are forcing chemical substance databases into IC design environments. ECHA's Substance of Very High Concern list now propagates through semiconductor bill-of-materials tracking. European automotive chip designers face the tightest compliance deadlines, with OEMs demanding full material disclosure down to the die-attach epoxy level.
Subscription pricing is displacing perpetual license models across mid-market accounts. Fabless startups in Austin, Tel Aviv, and Shenzhen prefer OpEx-based tool access that scales with tapeout volume. This shift is most visible among Series B and C funded ventures that prioritize cash preservation over long-term TCO optimization.
Electronic Design Automation Software Market Segmentation
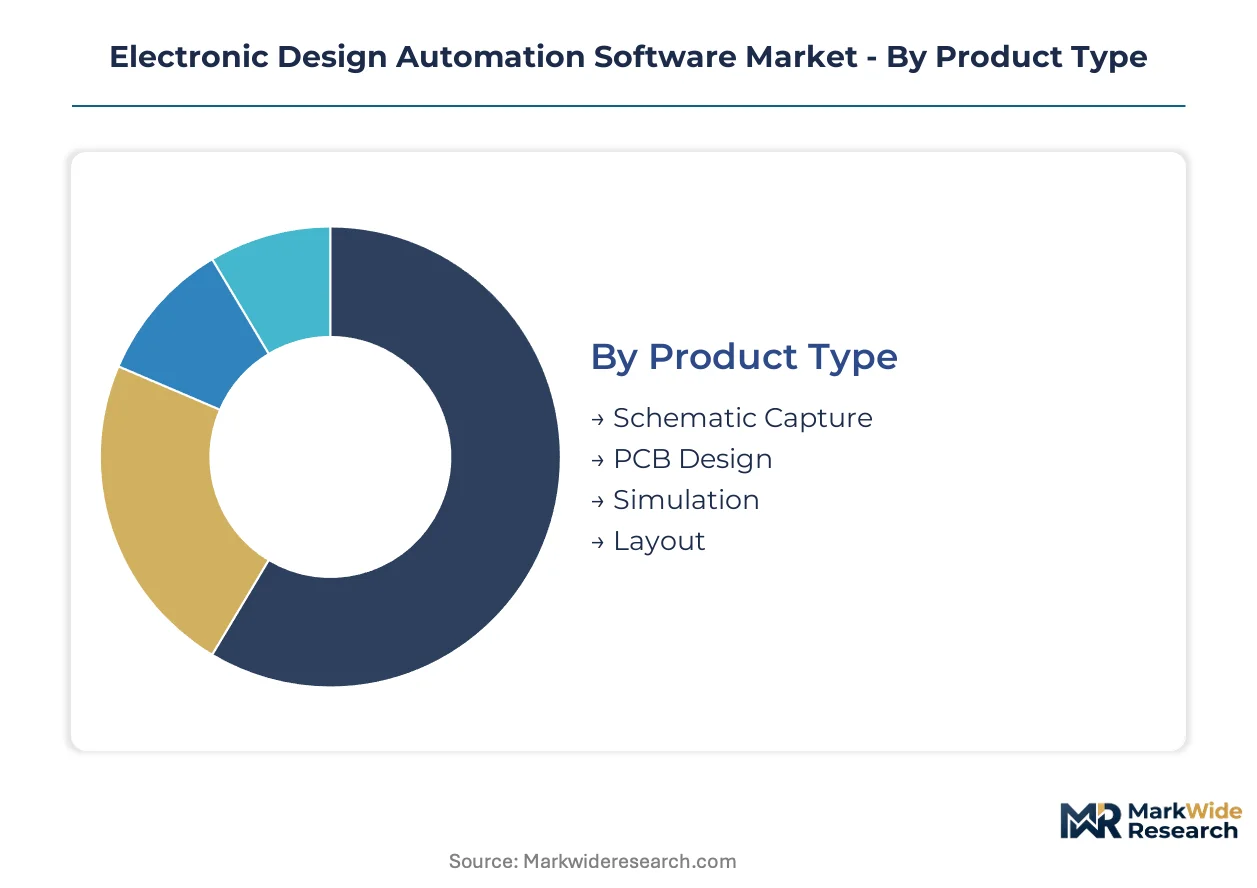
EDA software segmentation reveals how tool complexity maps to customer capability and procurement economics. Product architecture, end-user vertical, signal domain, and infrastructure deployment each create distinct margin pools and competitive dynamics.
Product Type:
Simulation commands premium pricing while schematic capture drives volume proliferation across mid-market accounts.
- Simulation:Transistor-level analysis tools handle sub-3nm quantum effects and parasitic extraction. TSMC's N2 node qualification requirements in Hsinchu are accelerating electromagnetic and thermal co-simulation procurement among leading-edge designers.
- Layout:Physical design automation encompasses place-and-route engines and design rule checking. Fabless AI chip ventures in Israel and Taiwan are adopting machine-learning-accelerated floorplanning to compress iteration cycles from weeks to days.
- PCB Design:Multi-layer board routing tools integrate with mechanical CAD systems for system-in-package workflows.
- Schematic Capture:Entry-level diagramming and netlist generation tools serve education markets and small engineering teams.
Mature deployment sits with schematic capture in established electronics manufacturing. Newer deployment is concentrated in simulation as advanced node complexity demands first-pass silicon success.
End User:
Semiconductor companies anchor R&D intensity while automotive verticals are expanding procurement fastest.
- Semiconductor Companies:Integrated device manufacturers and fabless designers require full-flow tool suites spanning architecture to sign-off. Samsung's Pyeongtaek and TSMC's Hsinchu campuses are driving the most sophisticated physical verification requirements globally.
- Automotive Manufacturers:Tier-1 suppliers and OEM captive chip teams need mixed-signal tools for radar and lidar integration. German and Japanese vehicle platforms under KBA and METI functional safety mandates are accelerating millimeter-wave design tool adoption.
- Consumer Electronics:Smartphone and wearable designers prioritize power optimization and form-factor constraints.
- Aerospace:Satellite and avionics systems demand radiation-hardened design methodologies and extended temperature verification.
Volume concentration rests with semiconductor companies. Procurement expansion is climbing the fastest among automotive manufacturers as electrification multiplies chip content per vehicle.
Technology:
Digital automation dominates license revenue while mixed-signal bridges analog expertise gaps.
- Mixed-Signal:Co-design environments bridge analog circuit precision with digital automation scale. Automotive radar proliferation across German and Japanese supply chains is accelerating tool procurement for sensor fusion architectures.
- Digital:RTL-to-GDSII flows encompass synthesis, place-and-route, and static timing analysis. Hyperscaler AI chip designers in Taiwan and the United States are driving the most aggressive adoption of generative layout agents.
- Analog:Custom IC design for power management and sensor interfaces retains craft-intensive workflows resistant to full automation.
- RF:High-frequency electromagnetic simulation for wireless communications and radar systems competes with physical test instrumentation from Keysight.
Margin depth pools with digital flows at advanced nodes. Technical complexity is expanding most acutely in mixed-signal as automotive and industrial applications proliferate.
Deployment:
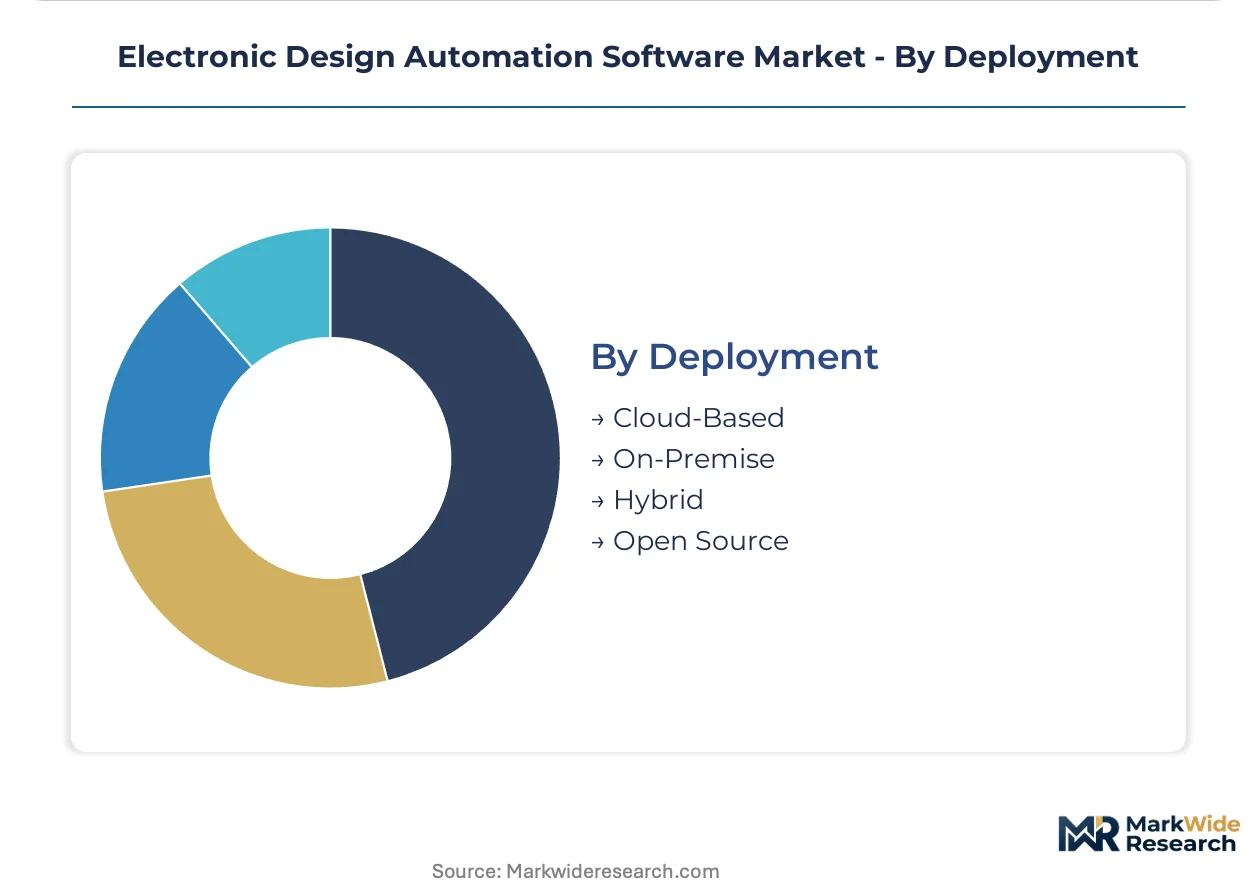
Hybrid architectures dominate established semiconductor companies while cloud-native adoption concentrates among capital-constrained entrants.
- Hybrid:Mixed on-premise and cloud infrastructure preserves data center investments while enabling burst capacity for physical verification. Intel and AMD maintain this architecture for IP security and legacy workflow integration.
- Cloud-Based:SaaS simulation licenses eliminate server farm capital requirements. Series B and C funded fabless startups in Austin, Tel Aviv, and Shenzhen prefer OpEx-based tool access that scales with tapeout volume.
- On-Premise:Fully captive infrastructure persists among defense contractors and memory manufacturers with stringent data sovereignty requirements.
- Open Source:Community-developed tools like Magic and KLayout serve academic research and cost-sensitive small design teams.
Established workflows remain with on-premise and hybrid configurations. Cloud-based deployment is gaining share fastest among new market entrants lacking legacy infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors global EDA procurement intensity through TSMC's advanced node roadmap and its captive supplier ecosystem. Taiwan's foundry corridor generates the most sophisticated physical verification requirements as sub-3nm geometries demand rebuilt simulation engines.
United States
Hyperscaler AI chip designers in Austin and Silicon Valley drive generative layout agent adoption fastest among all customer segments. FDA scrutiny of medical device electronics and Department of Commerce dual-use restrictions fragment compliance requirements for multinational tool deployment. Intel's Hillsboro campus and AMD's Austin operations maintain hybrid cloud-on-premise architectures for IP security.
Germany
Automotive radar and lidar sensor deployment across BMW and Mercedes supply chains accelerates mixed-signal design tool procurement. KBA functional safety mandates under UN ECE regulations embed verification rule decks directly into EDA workflows. Dresden's emerging fab investments under EU Chips Act incentives create captive demand for sovereign EDA capability independent of US vendors.
South Korea
Samsung's Pyeongtaek memory complex and SK Hynix's Icheon operations sustain the most aggressive physical verification R&D intensity outside Taiwan. METI-aligned export control frameworks limit electromagnetic simulation deployment across certain foundry locations. Seoul Capital Area fabless ventures are adopting SaaS simulation licenses faster than established chaebol captive design teams.
Japan
Automotive tier-1 suppliers under METI automotive semiconductor revitalization plans need RF simulation tools for millimeter-wave sensor integration. Sony and Renesas design centers in Tokyo and Osaka prefectures retain craft-intensive analog workflows resistant to full automation. Kyushu's silicon photonics research clusters represent nascent demand for optical-electrical co-simulation.
India
PLI scheme subsidies in Gujarat and Karnataka seed first domestic EDA procurement outside traditional design services. BIS semiconductor equipment standards and DGFT import licensing create region-specific verification requirements. Bangalore's fabless startup ecosystem prefers OpEx-based cloud tool access that scales with tapeout volume.
Electronic Design Automation Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the EDA software landscape, creating a tiered structure where full-flow suite vendors anchor high-value relationships while point-tool specialists capture niche margin pools. The market consolidates around three strategic archetypes: integrated design-to-manufacturing platform providers, simulation-centric specialists, and cloud-native entrants attacking mid-market accounts. Dominant competitive moves include reinforcement learning technology licensing for place-and-route acceleration and strategic partnerships with foundries for early node qualification access.
Within the integrated platform tier, Synopsys and Cadence Design Systems exemplify archetypes combining digital and analog capabilities through acquisition-driven portfolio breadth. Siemens EDA occupies a distinct position linking design automation with manufacturing execution systems. Among simulation-centric specialists, Ansys and Keysight Technologies represent physics-based analysis depth competing with EDA-native electromagnetic tools.
| Leading Market Players |
|---|
| Ansys |
| Zuken |
| Synopsys |
| Silvaco |
| Altium |
| Cadence Design Systems |
| Keysight Technologies |
| Aldec |
| Siemens EDA |
| Others |
Cost & Logistics Intelligence
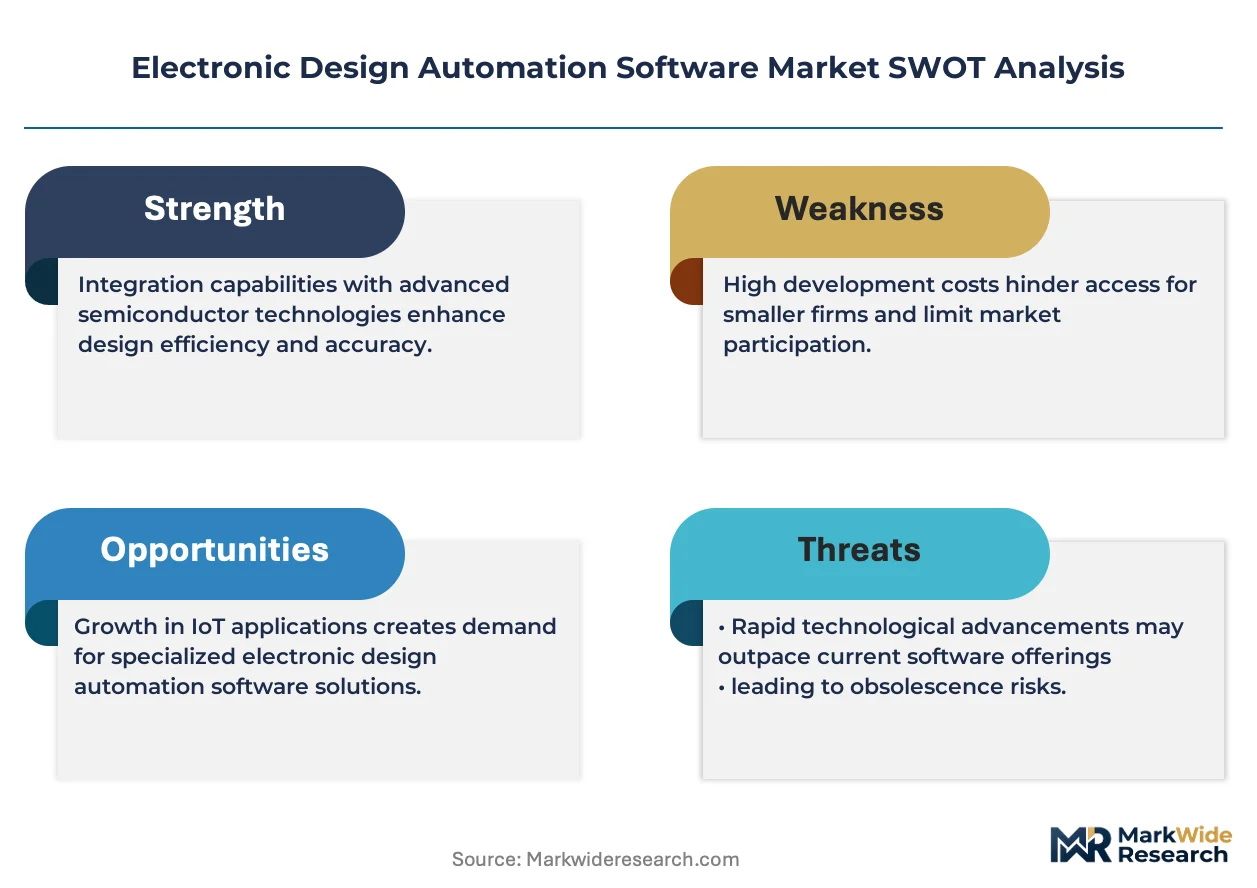
Silicon wafer spot prices from the Taiwan spot market cascade through foundry cost structures into EDA software pricing tiers, with advanced node design tool premiums reflecting the concentrated supply of leading-edge manufacturing capacity.
Pricing Analysis
Lead-time compression commands premium pricing for EDA licenses tied to TSMC N2 node qualification schedules, while surplus inventory of mature-node tool suites trades at spot discounts. Three-tier pricing structure across premium, standard, and economy levels segments by verification engine sophistication and foundry partnership depth. Pricing pressure stems from cloud-native entrants undercutting perpetual license models with SaaS-based simulation access. Fabless startups in Austin and Tel Aviv exhibit highest price sensitivity; captive design teams at Samsung and Intel demonstrate lowest.
Supply Chain Analysis
PhD-level quantum device modeling expertise concentrates in Taiwan's Hsinchu corridor, South Korea's Seoul Capital Area, and California's Silicon Valley, creating workforce bottlenecks for physical verification engine development. EDA tool production draws from specialized computational physics talent pools, GPU accelerator supply chains, and foundry process design kit partnerships. Single-source vulnerability runs through Taiwan's 90% share of leading-edge foundry capacity. Distribution runs through direct enterprise sales for semiconductor majors and channel partners for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leading-edge foundry capacity scarcity in Taiwan props pricing power for EDA vendors with validated advanced node tool chains, creating durable margin pools for incumbents with foundry-qualified verification engines.
For Market Incumbents: Anchor advanced node roadmaps through exclusive TSMC and Samsung process design kit partnerships, locking out cloud-native challengers from early node access. Deepen backward integration into GPU-accelerated simulation hardware to escape legacy SPICE kernel performance ceilings. Defensive priority: monitor generative AI layout agents threatening physical designer staffing ratios. For New Entrants and Emerging Players: The mid-market gap between Synopsys-Cadence premium suites and open-source Magic-KLayout tools offers white-space for SaaS-native simulation targeting Series B fabless ventures. Target India's PLI-subsidized Gujarat and Karnataka design centers before established vendors build channel presence. Go-to-market angle: OpEx-scaling licenses tied to tapeout volume rather than perpetual seat commitments. For Investors and Strategic Acquirers: The window for entry favors photonics-electronics co-simulation specialists with silicon photonics domain expertise, ahead of optical-electrical integration inflection. Long-term viability rests on captive foundry relationships rather than algorithmic differentiation alone. Signal to watch: EU Chips Act sovereign EDA procurement awards to non-US vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Process Design Kit Partnership | Early N2 node access at TSMC Hsinchu locks in leading-edge designers for verification tool suites. |
| GPU-Accelerated Simulation Engine Launch | Cadence and Synopsys reinforcement learning agents cut physical design iteration cycles from weeks to days. |
| Cloud-Native SaaS Platform Expansion | OpEx-based licensing captures fabless startups in Austin, Tel Aviv, and Shenzhen lacking data center capital. |
| Sovereign EDA Capability Investment | Dresden and Leuven fab investments under EU Chips Act create captive demand independent of US vendors. |
| Photonics-Electronics Co-Simulation Development | Kyushu silicon photonics clusters represent underserved demand for optical-electrical domain integration. |
Research Approach
SEC 10-K filings, foundry capex disclosures, and EDA vendor revenue segment reports formed the secondary backbone, cross-referenced with primary interviews spanning physical design engineers at TSMC and Samsung, EDA product managers at Synopsys and Cadence, fabless startup CTOs in Israel and Taiwan, and semiconductor procurement leads at German automotive tier-1 suppliers. Bottom-up tool license volume estimates triangulated against top-down foundry capacity expansion projections.
Historical trendline analysis of license revenue growth against foundry node migration timelines established baseline trajectory patterns across the projection horizon. Segmentation modeling incorporated product type, end-user vertical, signal domain technology, and deployment infrastructure dimensions. CAGRs derived from regression-weighted capacity expansion schedules and design complexity elasticity factors, with specific inputs from advanced node yield learning curves and cloud adoption penetration rates.
Inputs from foundry process roadmaps and EDA vendor R&D disclosures were available through the study window; gaps in proprietary algorithm performance benchmarks introduce uncertainty bands around simulation tool adoption velocity. Forecasts reflect documented assumptions regarding node migration pacing and export control evolution. Material deviation in TSMC capacity allocation or US Department of Commerce dual-use list expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Construction Software Market
Software & Services
Compositing Software Market
Software & Services
Global Business Software Market
Software & Services
Marketing Automation Software Market
Software & Services
Global Backup Restore Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Global IVR Software Market
Software & Services
Global Vendor Management Software Market
Software & Services
Global Diagram Software Market
Software & Services
Mobile Application Development Market
Software & Services
Lead Scoring Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Time Series Databases Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Multiphysics Software Market