
 Braking Systems Software Market | 2026-2036
Braking Systems Software Market Size, Share, and Industry Trends Forecast 2026-2036
Braking Systems Software Market Outlook
ISO 26262 functional safety certification is reorganizing competitive access in braking systems software, elevating compliance costs that favor incumbents with established ASIL-D processes. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain integrated software-hardware development for ESC and ABS modules across multiple OEM platforms. Continental AG anchors its position through dedicated braking software divisions supplying electronic systems to German and North American vehicle manufacturers. ZF Friedrichshafen AG differentiates via simulation-intensive validation pipelines that compress homologation cycles for hybrid braking architectures.
Braking systems software comprises the embedded control algorithms, sensor fusion logic, and actuator command layers that modulate hydraulic, pneumatic, or electromechanical force distribution to individual wheels. The software executes real-time wheel-slip calculations at sub-millisecond intervals, enabling anti-lock braking, stability intervention, and regenerative blending in electrified powertrains. Electronic systems command the fastest expansion within the technology dimension, driven by brake-by-wire proliferation and the displacement of hydraulic backups in premium platforms. ESC software retains the largest installed base across passenger and commercial applications, though TCS modules for electric two-wheelers represent the most concentrated growth vector in Asian supply contracts. OEM end users capture the dominant value share through pre-installed software licensing, while aftermarket providers face narrowing access as encrypted control units restrict independent recalibration.
NHTSA automatic emergency braking mandates and EU Green Deal-aligned vehicle safety standards are accelerating software validation requirements for suppliers seeking North American and European market access. UN ECE R79 and R152 protocols are reshaping testing documentation burdens, compelling Tier-1 developers to expand in-house proving grounds and simulation assets. Stakeholders must monitor divergence between U.S. FMVSS interpretation and EU type-approval frameworks, as regulatory misalignment threatens platform standardization strategies for multinational braking software portfolios.
Market Dynamics
The brake-by-wire transition is collapsing traditional hydraulic architectures and forcing Tier-1 suppliers to rebuild software validation pipelines around real-time actuator control without mechanical fallback systems.
Growth Catalysts
- NHTSA AEB Mandate:United States automatic emergency braking requirements for light vehicles are compelling OEMs to source integrated perception-braking software stacks from qualified Tier-1 developers.
- EU Green Deal Safety Alignment:European Commission vehicle safety standards are accelerating regenerative braking software procurement for electrified platforms seeking type approval.
- German Engineering Clusters:Stuttgart and Munich metropolitan regions concentrate ESC and ABS software development talent serving export programs to North American and Asian vehicle manufacturers.
Market Restraints
- ISO 26262 ASIL-D Certification Costs:Functional safety compliance expenses for braking software exceed thresholds accessible to mid-tier developers, consolidating supply around incumbent verification infrastructures.
- Rare Earth Magnet Dependence:Electromechanical brake actuators require neodymium-dysprosium permanent magnets concentrated in Chinese processing facilities, exposing cost volatility to export control fluctuations.
- Hydraulic Legacy Integration:Brake-by-wire architectures must maintain redundant hydraulic backups for regulatory acceptance, duplicating software validation effort without eliminating mechanical component costs.
Strategic Opportunities
- India Two-Wheeler Electrification:TCS software for electric scooters and motorcycles represents underpenetrated demand as domestic OEMs expand production for Southeast Asian export markets.
- Over-the-Air Update Monetization:Braking performance calibration delivered through cellular connectivity creates recurring revenue streams from feature activation and seasonal parameter adjustments.
- Simulation-First Validation:Virtual homologation pipelines compress development cycles by replacing physical proving ground mileage with hardware-in-the-loop testing for regulatory documentation.
Industry Challenges
- Embedded Cybersecurity Engineering:UN ECE R155 requirements for braking system intrusion detection are forcing suppliers to recruit automotive security architects from scarce talent pools.
- Multi-Standard Documentation Burden:Divergent FMVSS interpretation in the United States and EU type-approval frameworks compels parallel validation tracks for identical software builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braking Systems Software Market |
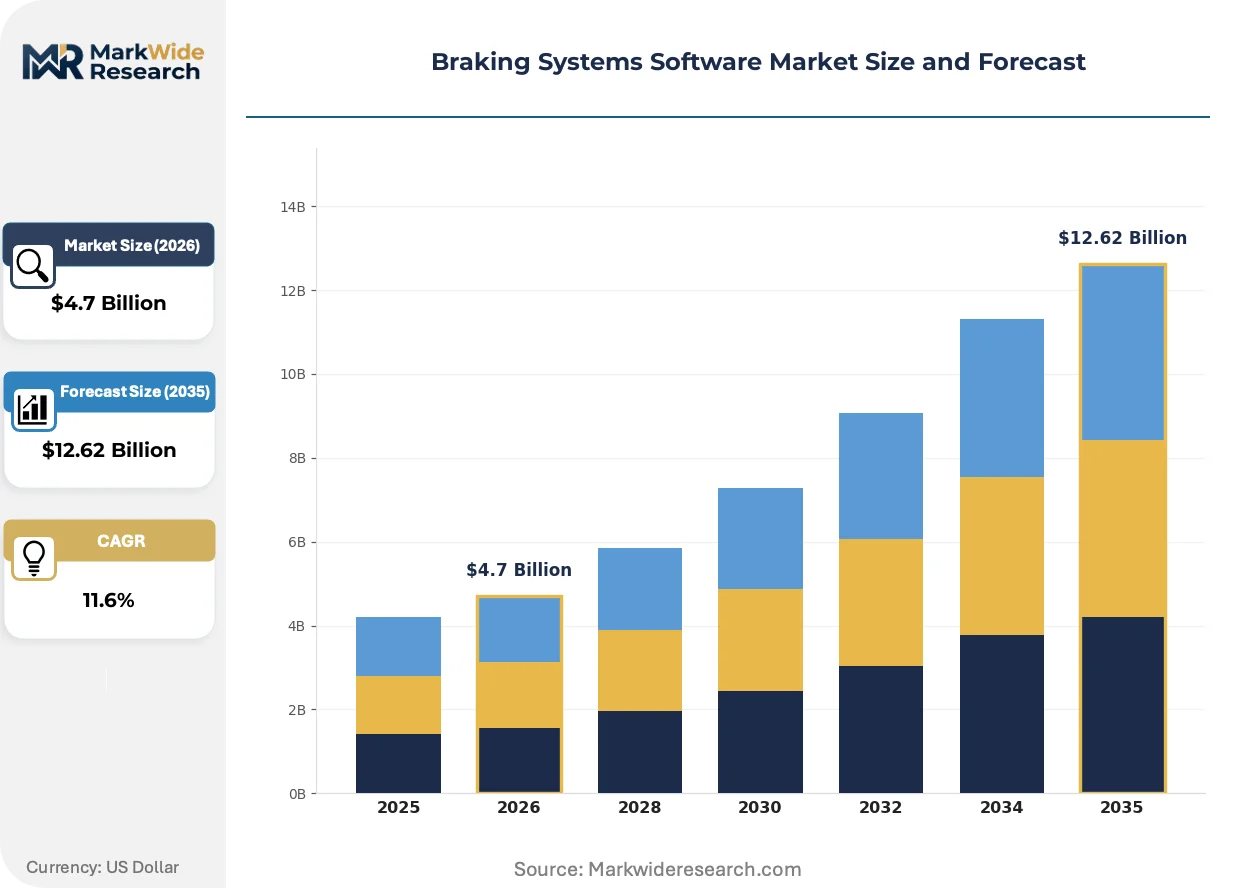
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, EBD, ESC, TCS Technology: Hydraulic Systems, Pneumatic Systems, Electronic Systems, Hybrid Systems End User: OEMs, Aftermarket Providers, Fleet Managers, Repair Shops Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Hitachi Astemo Ltd., Mando Corporation, Knorr-Bremse AG, Akebono Brake Industry Co. Ltd., Brembo S.p.A, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braking Systems Software Market Strategic Shifts
Software-defined braking architectures are separating control logic from hydraulic hardware, enabling modular procurement and forcing suppliers to defend value capture at the algorithm layer.
Brake-by-wire actuation is bifurcating development roadmaps between centralized domain controllers and distributed wheel-end modules. Premium passenger vehicle platforms are adopting centralized architectures to reduce wiring mass and enable cross-axle torque vectoring. This technology is bifurcating supplier relationships into software-only licensing versus integrated actuator-software bundles.
UN ECE R152 automatic emergency braking protocols are expanding test scenario requirements to include vulnerable road user detection in low-light conditions. European type-approval authorities are rejecting submissions lacking documented sensor fusion performance across camera-radar-lidar combinations. Commercial vehicle segments in Germany are absorbing the highest compliance burden as multi-axle braking coordination adds validation complexity.
Fleet operators are unbundling brake maintenance from vehicle procurement through predictive wear algorithms. Leasing companies in the United States are subscribing to friction material degradation monitoring rather than scheduled replacement intervals. This shift concentrates software purchasing authority with fleet management platforms rather than individual vehicle owners.
Braking Systems Software Market Segmentation
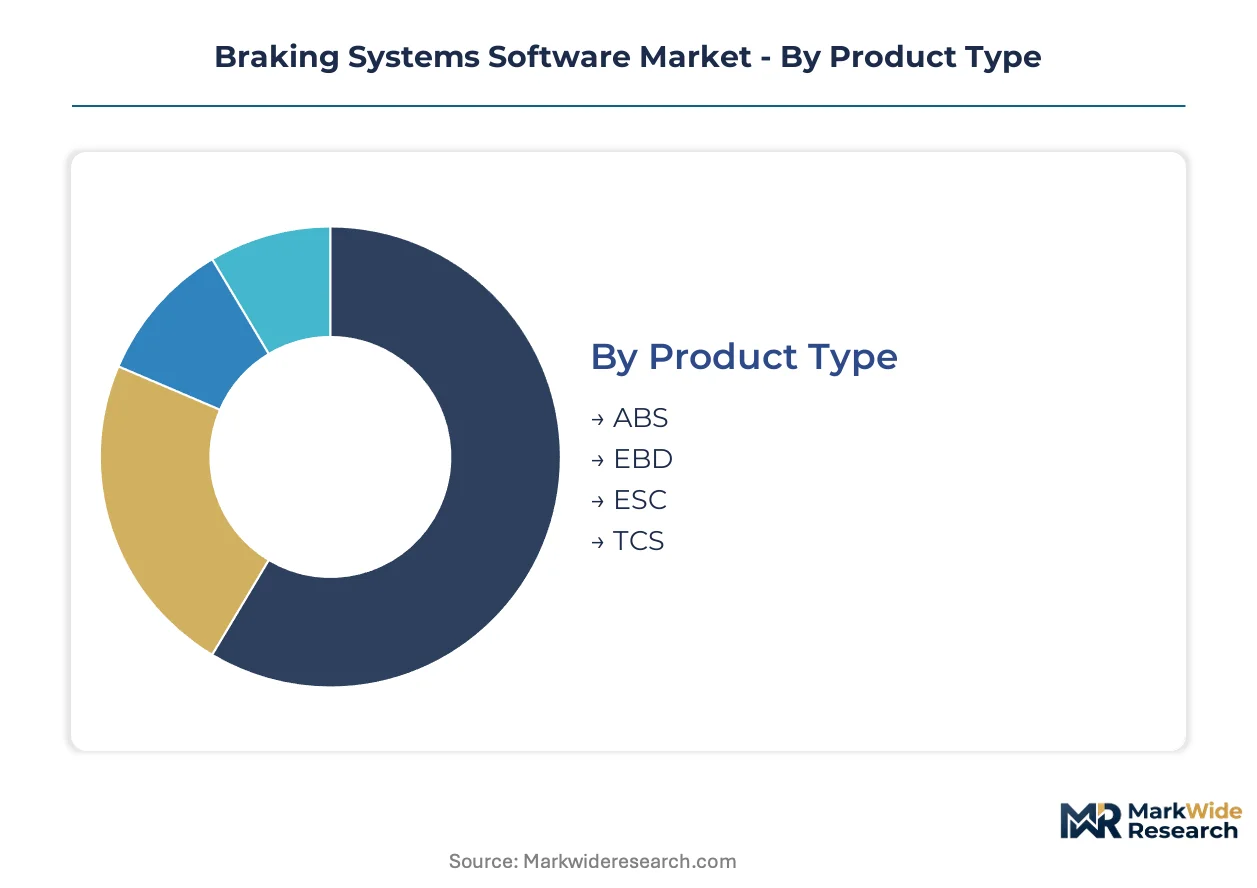
Segmentation in braking systems software reveals how control algorithms, actuator interfaces, and validation requirements vary across vehicle architectures. Suppliers must align development roadmaps with distinct certification burdens and update protocols that differ materially by product type and end user.
Product Type:
Electronic substitutes for mechanical braking functions are displacing legacy hydraulic modules fastest in premium vehicle platforms, forcing suppliers to defend algorithmic value capture.
- ABS:Anti-lock braking software modulates hydraulic pressure at individual wheels to prevent lock-up during emergency stops. Demand concentrates in emerging markets where cost-sensitive OEMs retain hydraulic backups rather than migrating to full brake-by-wire. Regulatory mandates in India and Brazil sustain procurement volumes despite technology obsolescence pressure.
- EBD:Electronic brakeforce distribution algorithms apportion hydraulic pressure between axles based on real-time load sensing. German and Japanese passenger vehicle programs drive specification refinement as these platforms integrate EBD with regenerative blending for electrified powertrains.
- ESC:Electronic stability control software commands the largest installed base across passenger and commercial applications, with UN ECE R13-H mandates compelling fitment in heavy-duty trucks.
- TCS:Traction control modules for electric two-wheelers represent concentrated growth in Indian and Southeast Asian supply contracts as domestic OEMs expand production.
ESC anchors the volume base while TCS gains share at the steepest rate.
Technology:
Cost tier stratification separates validation-intensive electronic architectures from legacy hydraulic systems that dominate price-sensitive procurement.
- Hydraulic Systems:Conventional fluid-pressure architectures retain dominance in commercial vehicle and budget passenger segments where mechanical redundancy satisfies regulatory requirements without software certification burdens.
- Pneumatic Systems:Air-brake control software serves heavy-duty trucking applications with specialized compressor management algorithms. North American and European fleet specifications drive demand concentration.
- Electronic Systems:Brake-by-wire platforms eliminate hydraulic backups in premium passenger vehicles, requiring ASIL-D functional safety certification and real-time actuator control without mechanical fallback. German engineering clusters anchor development.
- Hybrid Systems:Blended architectures combine regenerative braking software with friction-based backup for electrified platforms seeking type approval under EU Green Deal safety alignment.
Electronic systems command margin expansion while hybrid systems expand most quickly as electrification accelerates.
End User:
Customer type determines software update authority and recurring revenue potential across the ownership lifecycle.
- OEMs:Vehicle manufacturers capture dominant value share through pre-installed software licensing and encrypted control units that restrict independent recalibration. Over-the-air update capabilities are becoming standard in premium platforms.
- Aftermarket Providers:Independent service channels face narrowing access as encrypted control units and cybersecurity requirements under UN ECE R155 limit recalibration permissions.
- Fleet Managers:Leasing and logistics operators are unbundling brake maintenance from vehicle procurement through predictive wear algorithms and friction material degradation monitoring subscriptions.
- Repair Shops:Authorized service networks retain software access through Tier-1 diagnostic tools, while independent shops confront declining revenue from brake system servicing.
OEMs dominate current procurement while fleet managers represent the fastest-expanding customer type.
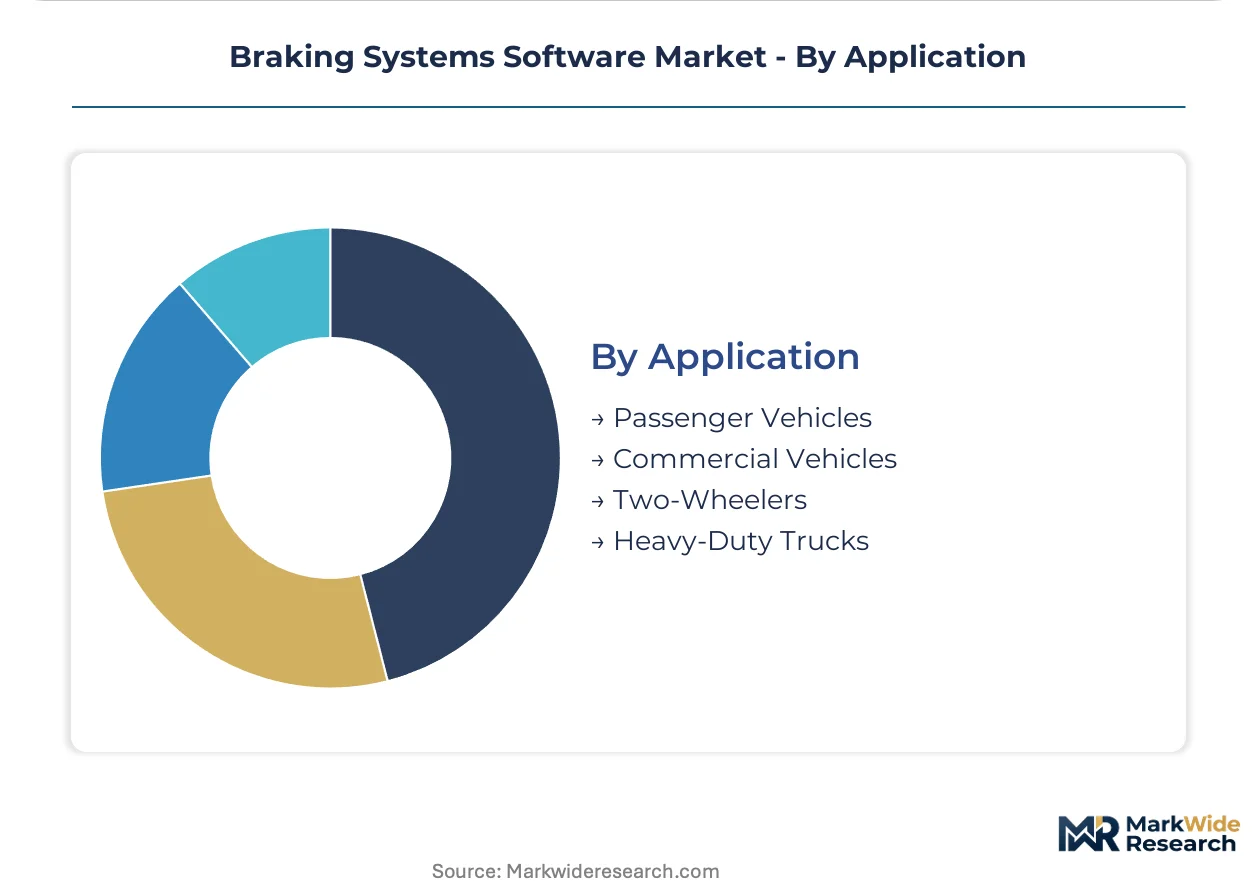
Application:
Vehicle category dictates coordination complexity and validation documentation burden for multi-axle or two-wheel architectures.
- Passenger Vehicles:Light-duty platforms drive brake-by-wire adoption with centralized domain controllers enabling cross-axle torque vectoring and reduced wiring mass.
- Commercial Vehicles:Multi-axle braking coordination adds validation complexity under UN ECE R152 protocols, with German commercial segments absorbing the highest compliance burden.
- Two-Wheelers:Electric scooters and motorcycles require compact TCS modules as domestic OEMs in India expand production for Southeast Asian export markets.
- Heavy-Duty Trucks:Long-haul applications combine pneumatic foundation brakes with electronic control for trailer synchronization and stability intervention.
Passenger vehicles anchor the installed base while two-wheelers climb the fastest as electrification penetrates Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Tier-1 suppliers anchor procurement relationships with premium passenger vehicle manufacturers seeking brake-by-wire integration. Japanese and South Korean electronics conglomerates supply ESC and ABS modules to Asian OEM electrification programs. Indian domestic manufacturers source TCS software for two-wheeler export markets into Southeast Asia.
United States
NHTSA automatic emergency braking mandates compel light vehicle OEMs to source integrated perception-braking software stacks from qualified developers. FMVSS interpretation frameworks govern validation documentation for braking system type approval. Michigan and Ohio engineering centers concentrate ESC calibration work for Detroit-based vehicle manufacturers.
Germany
EU Green Deal safety alignment accelerates regenerative braking software procurement for electrified platforms seeking type approval. UN ECE R79 and R152 protocols reshape testing documentation burdens for Tier-1 developers. Stuttgart and Munich metropolitan regions concentrate ABS and ESC software engineering talent serving export programs.
China
Domestic OEM electrification drives demand for hybrid braking architectures blending regenerative and friction-based systems. MIIT vehicle safety standards govern software certification requirements for new energy vehicle platforms. Yangtze River Delta automotive clusters anchor brake-by-wire development for local passenger vehicle programs.
Japan
Electronics conglomerates supply sensor fusion algorithms for camera-radar-lidar combinations in premium braking systems. METI industrial policy supports autonomous driving technology development including AEB software validation. Kanto region engineering bases serve both domestic OEMs and technology licensing to Southeast Asian assemblers.
India
Electric two-wheeler OEMs expand TCS module procurement for scooters and motorcycles targeting Southeast Asian export markets. BIS automotive safety standards govern braking system certification for domestic production. Tamil Nadu and Karnataka manufacturing corridors concentrate software integration work for domestic electrification programs.
Braking Systems Software Market Competitive Environment
Player mix skews toward diversified automotive electronics conglomerates with established functional safety certification infrastructure. Consolidation pressure favors incumbents bearing ASIL-D compliance costs that exceed mid-tier developer thresholds. Strategic archetypes separate integrated hardware-software bundlers from software-only licensors and simulation-intensive validation specialists. Dominant competitive moves include strategic partnerships for brake-by-wire platform development and geographic expansion into Indian two-wheeler electrification corridors.
Within the integrated systems tier, Robert Bosch GmbH and Continental AG exemplify Stuttgart-based engineering conglomerates with captive software-hardware development pipelines. ZF Friedrichshafen AG occupies a position among simulation-intensive validation specialists compressing homologation cycles for hybrid architectures. These three German entities anchor the supplier base serving European and North American OEM platform programs.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Hitachi Astemo Ltd. |
| Mando Corporation |
| Knorr-Bremse AG |
| Akebono Brake Industry Co. Ltd. |
| Brembo S.p.A |
| Aisin Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with rare earth magnet suppliers lock in both neodymium-dysprosium access and cost predictability for electromechanical brake actuator developers serving brake-by-wire platforms. These arrangements shield Tier-1 suppliers from Chinese export control volatility while embedding indexation clauses to raw material benchmarks.
Pricing Analysis
Cost-plus contracts with rare earth price indexation dominate procurement for electromechanical braking components. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-certified software tiers separates premium brake-by-wire stacks from legacy ABS modules. Pricing pressure stems from OEM consolidation around integrated hardware-software bundles that compress standalone licensing margins. Fleet operators exhibit lowest price sensitivity due to predictive maintenance subscription value, while Indian two-wheeler OEMs face acute cost compression in TCS module procurement.
Supply Chain Analysis
Strategic stockpiling of neodymium-dysprosium magnets supersedes just-in-time preferences as Chinese processing concentration intensifies supply vulnerability. Manufacturing concentrates in Germany, China, and Japan for brake-by-wire controllers, with rare earth refining anchored in Chinese facilities. Semiconductor content for sensor fusion modules draws from Taiwanese and South Korean foundries. Single-source vulnerability in permanent magnet supply creates structural risk. Distribution runs through Tier-1 direct OEM supply contracts with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as brake-by-wire proliferation splinters demand across centralized domain controllers, distributed wheel-end modules, and hybrid architectures for electrified platforms. This demand-side shift creates specialized niches for simulation-intensive validation specialists and cybersecurity-certified software licensors.
For Market Incumbents: Compound ASIL-D certification infrastructure advantages by acquiring simulation asset platforms that compress homologation cycles for hybrid braking architectures. Deepen backward integration into rare earth magnet supply through offtake agreements with Australian and Canadian mining ventures to neutralize Chinese export control exposure. ISO 26262 compliance cost escalation threatens margin compression from emerging software-only entrants. For New Entrants and Emerging Players: Lead with cybersecurity engineering capabilities targeting UN ECE R155 intrusion detection requirements as established suppliers confront talent scarcity in automotive security architecture. Indian electric two-wheeler TCS modules represent the most penetrable segment given domestic OEM expansion into Southeast Asian export markets. Partner with fleet management platforms for predictive brake wear algorithm deployment rather than competing for encrypted OEM control unit access. For Investors and Strategic Acquirers: Capital is best deployed toward simulation-intensive validation specialists with hardware-in-the-loop testing infrastructure that reduces physical proving ground dependency for regulatory documentation. Long-term viability hinges on differentiation at the algorithm layer as hardware commoditization accelerates through brake-by-wire standardization. Watch for NHTSA rulemaking expansion into heavy-duty truck AEB mandates as inflection indicator for commercial vehicle software procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Reduces wiring mass and enables cross-axle torque vectoring for premium passenger vehicle OEMs. |
| Software-Defined Vehicle Investment | Separates control logic from hydraulic hardware, forcing algorithmic value capture defense. |
| Geographic Manufacturing Footprint | Tamil Nadu and Karnataka corridors capture Indian two-wheeler electrification export demand. |
| Strategic Partnership | Fleet operator alliances unlock predictive maintenance subscription revenue streams. |
| Acquisition of Specialist Firm | Automotive cybersecurity boutiques address UN ECE R155 intrusion detection requirements. |
Study Parameters
Cross-validation between Tier-1 supplier procurement directors and OEM platform engineering leads anchors the qualitative findings in operational reality. Primary interviews encompassed braking software development heads, functional safety certification auditors, fleet management technology officers, and aftermarket diagnostic tool distributors. Secondary validation drew from NHTSA FMVSS interpretation bulletins, UN ECE R79 and R152 protocol documentation, EU Green Deal vehicle safety alignment communications, and vehicle production registration databases. Bottom-up segment sizing triangulated against top-down OEM platform software content estimates.
Sensitivity analysis tested forecast outputs against brake-by-wire adoption velocity, rare earth magnet price volatility, and regulatory mandate expansion scenarios. The analytical framework modeled segmentation across vehicle class, propulsion architecture, software certification tier, and regional production cluster throughout the projection horizon. CAGRs derived from installed base turnover rates, content-per-vehicle escalation curves, and electrification penetration pathways. Industry-specific inputs included ESC fitment mandate compliance schedules and over-the-air update capability deployment trajectories.
The analysis sits within stated boundaries; outcomes outside sustained NHTSA and EU regulatory enforcement, stable rare earth supply access, and brake-by-wire technical validation success would require recalibration. Forecasts reflect documented assumptions regarding OEM platform consolidation and cybersecurity certification burden evolution. Revision becomes warranted when AEB mandate scope expansion crosses thresholds into commercial vehicle segments or when Chinese rare earth export licensing tightens materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Event Management Software Market
Software & Services
Global Accounts Receivable Software Market
Software & Services
Global Audit Software Market
Software & Services
Home Fitness App Market
Software & Services
Mainframe Software Market
Software & Services
Global Data Mining Software Market
Software & Services
Digital Painting Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
B2B Gateway Software Market
Software & Services
Global Municipal Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global HVAC Software Market
Software & Services
Global Digital Experience Management Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market