
 Global Order Management Software Market | 2026-2036
Global Order Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Order Management Software Market Foresight
North America is fragmenting as cloud infrastructure investments multiply across the United States and Canada. Oracle Corporation leverages its ERP integration depth to anchor enterprise deployments. Manhattan Associates competes through warehouse management convergence. SAP SE dominates in manufacturing verticals with embedded supply chain modules.
Order management software orchestrates the capture, processing, and fulfillment of customer orders across multiple sales channels through API-driven workflow engines and real-time inventory visibility layers. The system executes allocation logic, payment validation, and carrier selection to synchronize demand signals with warehouse and transportation assets. Cloud-based deployment leads in new implementations as retailers prioritize elastic scaling during peak demand periods. ERP integration captures the deepest margin pools because unified data architecture reduces reconciliation overhead. Third-party logistics application segments are expanding fastest as fulfillment networks outsource orchestration complexity.
The EU AI Act imposes transparency obligations on automated order-routing decisions, compelling vendors to document algorithmic logic for European deployments. The United States FDA and FCC frameworks indirectly shape requirements for pharmaceutical and telecommunications order tracking through traceability mandates. Stakeholders must monitor how ISO supply chain standards evolve to incorporate machine-learning auditability before selecting platform architectures.
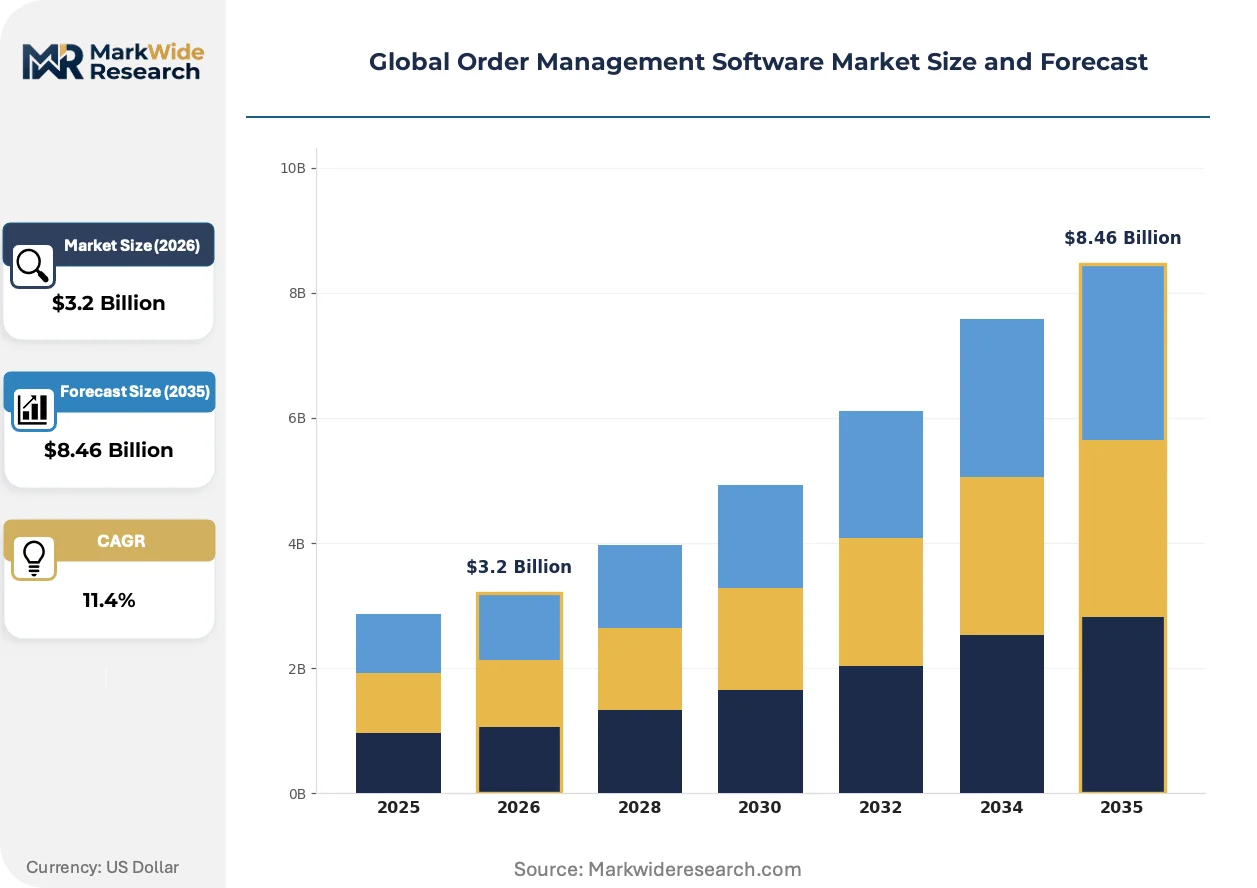
Market Dynamics
Cloud-native architecture is hybridizing with legacy ERP systems as retailers demand elastic orchestration without forklift upgrades, forcing vendors to bridge containerized microservices with monolithic inventory databases.
Growth Catalysts
- EU AI Act transparency mandates:Automated order-routing algorithms now require documented logic trails, accelerating demand for explainable AI modules in European deployments.
- Third-party logistics outsourcing:Fulfillment networks are offloading orchestration complexity to specialized platforms as SKU proliferation strains in-house capabilities.
- API-driven inventory unification:Real-time visibility layers synchronize warehouse and transportation assets, compressing order-to-delivery windows for omnichannel retailers.
Market Restraints
- Legacy system integration costs:Custom middleware development for SAP and Oracle ERP connectors consumes implementation budgets and extends deployment timelines.
- Cloud infrastructure concentration:Dependence on hyperscaler availability zones in Virginia, Frankfurt, and Singapore creates single-point-of-failure exposure during peak demand periods.
- Algorithmic auditability gaps:ISO supply chain standards lack machine-learning audit frameworks, forcing vendors to maintain parallel compliance documentation.
Strategic Opportunities
- India's PLI scheme for logistics technology:Domestic manufacturing incentives are attracting order management vendors to establish local cloud regions and compliance engineering.
- Pharmaceutical serialization convergence:FDA traceability mandates are creating demand for order platforms with embedded lot-tracking and cold-chain verification.
- Headless commerce architecture:Decoupled frontend-backend systems enable API-first order orchestration across emerging social commerce and live-streaming channels.
Industry Challenges
- Multicloud Kubernetes orchestration expertise:Shortage of platform engineers capable of managing distributed order workflows across AWS, Azure, and GCP environments.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical order systems require extensive electronic records compliance testing, delaying go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Order Management Software Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, SaaS, Managed Services Application: E-commerce, Wholesale Distribution, Manufacturing, Telecommunications, Third-party Logistics End User Industry: Retailers, Food & Beverage Chains, Electronics Distributors, Apparel Brands, Consumer Goods Suppliers Integration Level: ERP Integration, CRM Integration, Warehouse Management System, Payment Gateway, Shipping Carrier |
| Companies Covered | IBM Corporation, Manhattan Associates, Oracle Corporation, Netsuite Inc., Zoho Inventory, SAP SE, Blue Yonder, Inc., Brightpearl, Salesforce.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Order Management Software Market Shifts & Advancements
Order management platforms are absorbing adjacent supply chain functions as buyers consolidate vendor relationships, compressing the traditional boundaries between OMS, WMS, and TMS categories.
Event-driven architecture is hybridizing batch and real-time processing to handle flash-sale traffic spikes without over-provisioning baseline infrastructure. Mid-market retailers are adopting serverless compute models for peak elasticity. This convergence is compressing the pricing premium between enterprise and mid-tier deployment tiers.
EU AI Act algorithmic transparency requirements are mandating decision-log documentation for automated order allocation and carrier selection. Vendors must now maintain technical files explaining routing logic for regulatory inspection. Pharmaceutical and telecommunications verticals face the steepest compliance engineering burdens.
Subscription commerce models are displacing transactional order patterns in consumer goods and industrial supply. Buyers now expect flexible fulfillment cadences, pause-skip functionality, and consolidated billing. This shift is most visible in United States direct-to-consumer brands and European B2B industrial distributors.
Global Order Management Software Market Segmentation
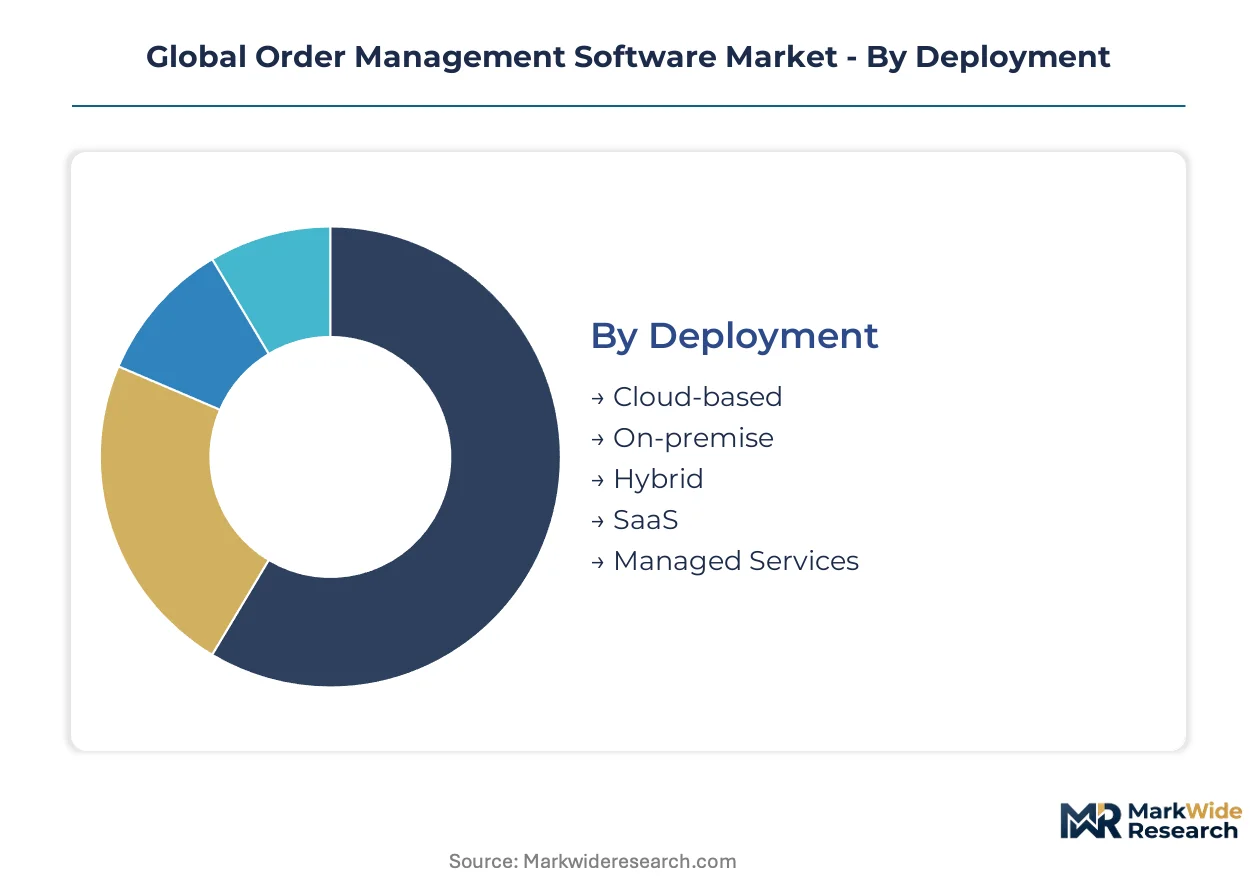
Order management software segments reveal divergent refresh cycles across deployment modes and integration depths. Cloud-native implementations turn over every 18-24 months as vendors release API updates, while on-premise ERP-integrated systems persist for 7-10 years. Understanding these velocity differences shapes platform selection and vendor relationship planning.
Deployment:
Cycle times compress from multi-year enterprise lock-in to elastic monthly scaling across deployment modes.
- Cloud-based:Containerized microservices architecture enables elastic scaling during demand spikes. United States retailers prioritize this model for omnichannel peak traffic management, though EU AI Act documentation requirements add compliance overhead to European rollouts.
- SaaS:Multi-tenant platforms deliver quarterly feature releases without client-side maintenance. Mid-market food and beverage chains in Germany and France favor this model for rapid deployment without capital expenditure approval cycles.
- On-premise:Monolithic installations persist in regulated pharmaceutical environments requiring FDA 21 CFR Part 11 validation.
- Hybrid:Split architectures synchronize sensitive payment data on-premise with fulfillment orchestration in cloud regions.
- Managed Services:Third-party operated infrastructure appeals to Japanese electronics distributors lacking internal DevOps capacity.
On-premise deployments anchor the volume base while SaaS implementations gain share at the steepest rate.
Application:
Margin profiles diverge sharply between transaction-heavy consumer channels and contract-driven industrial workflows.
- E-commerce:Real-time inventory unification across marketplaces, direct sites, and social commerce platforms. United States direct-to-consumer brands drive demand for headless commerce APIs enabling live-streaming checkout integration.
- Third-party Logistics:Multi-tenant orchestration platforms manage fulfillment complexity for outsourced networks. India's PLI scheme for logistics technology is attracting vendors to establish local cloud regions serving this segment.
- Wholesale Distribution:Bulk order processing with negotiated pricing tiers and credit validation workflows.
- Manufacturing:Embedded supply chain modules synchronize production schedules with component procurement.
- Telecommunications:FCC traceability mandates shape device order tracking and activation sequencing requirements.
E-commerce captures the deepest revenue concentration while third-party logistics demonstrates the most rapid expansion trajectory.
End User Industry:
Customer concentration patterns separate fragmented long-tail markets from consolidated enterprise procurement.
- Retailers:Omnichannel order orchestration spanning physical stores, online marketplaces, and curbside pickup. United States department store chains and Canadian grocery networks dominate implementation volumes.
- Electronics Distributors:Serial number tracking and warranty validation across complex global supply chains. Japan's METI standards and China's GB certification requirements shape platform specifications.
- Food & Beverage Chains:Cold-chain verification and expiration-date allocation logic for perishable fulfillment.
- Apparel Brands:Size-color matrix complexity and seasonal demand forecasting integration.
- Consumer Goods Suppliers:Subscription commerce models with pause-skip functionality and consolidated billing cadences.
Retailers anchor the volume base while electronics distributors expand most quickly amid semiconductor supply chain restructuring.
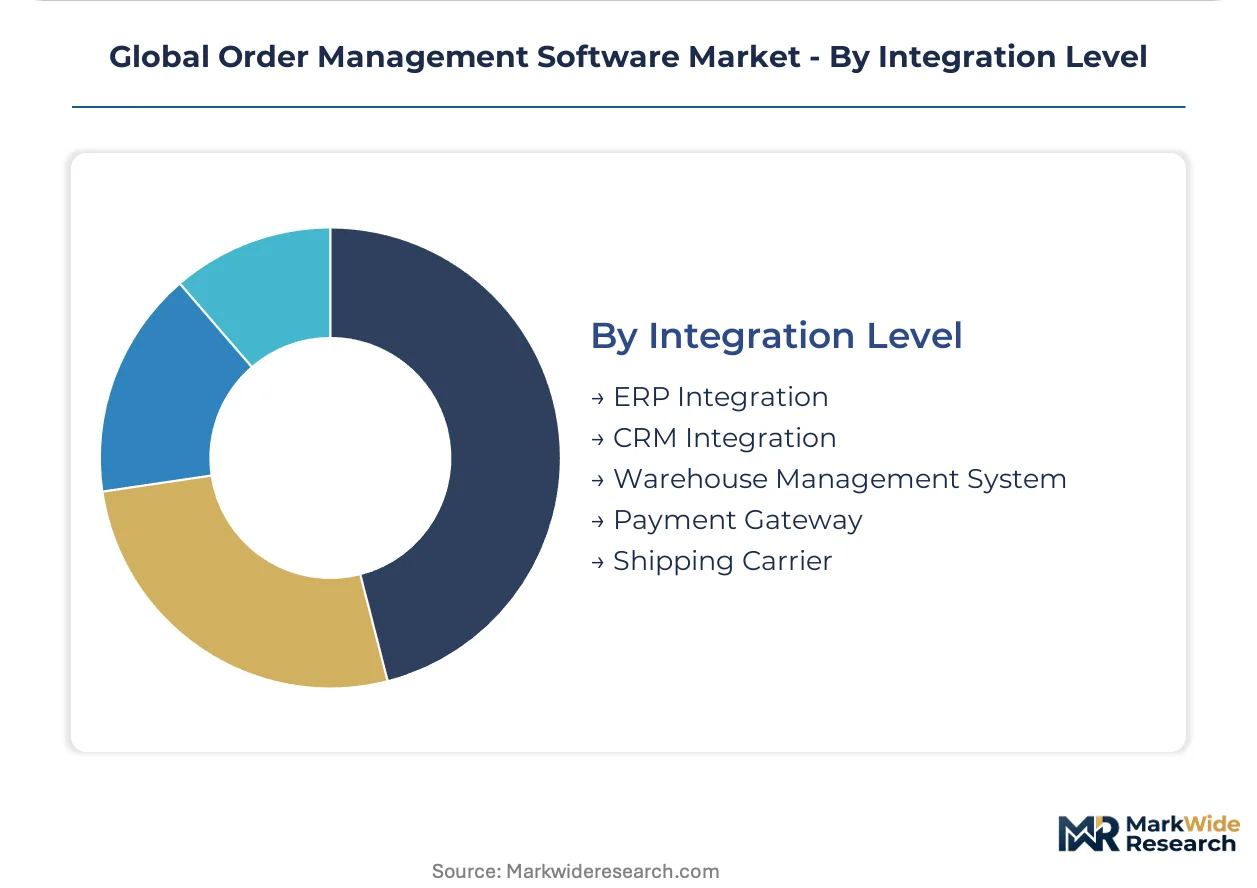
Integration Level:
Technical debt accumulates at interface boundaries between order platforms and legacy enterprise systems.
- ERP Integration:Unified data architecture eliminates reconciliation between order capture and financial settlement. Oracle and SAP connector development consumes the largest implementation budgets in German manufacturing verticals.
- Warehouse Management System:Real-time inventory allocation against physical location and labor capacity. United States 3PL providers demand this convergence to optimize last-mile fulfillment density.
- CRM Integration:Customer lifetime value scoring influences order prioritization and service level commitments.
- Payment Gateway:PCI-DSS compliance and fraud scoring embedded within checkout workflows.
- Shipping Carrier:Rate shopping and label generation across multi-carrier networks with delivery promise calculation.
ERP integration anchors the volume base while WMS convergence gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure for order management software concentrates in hyperscaler availability zones across five countries. Vendor engineering teams cluster near these data centers to minimize latency for enterprise clients. Regulatory fragmentation across these jurisdictions shapes platform architecture decisions.
United States
E-commerce fulfillment complexity and omnichannel integration investments drive demand for elastic orchestration platforms. FDA traceability mandates for pharmaceutical order tracking shape compliance engineering requirements. Seattle and Northern Virginia host the densest concentrations of cloud-native order management engineering teams.
Germany
Manufacturing verticals prioritize embedded supply chain modules with ERP integration depth. The EU AI Act imposes transparency obligations on automated order-routing decisions, compelling documentation of algorithmic logic. Stuttgart and Munich anchor automotive and industrial machinery order management implementation volumes.
India
The PLI scheme for logistics technology attracts vendors to establish local cloud regions and compliance engineering capabilities. BIS standards and RBI payment regulations shape platform specifications for domestic deployments. Bangalore and Hyderabad concentrate software engineering talent for order orchestration platform development.
Japan
Electronics distributors require serial number tracking and warranty validation across complex global supply chains. METI standards influence platform specifications for domestic and export-oriented implementations. Tokyo and Osaka host the primary concentrations of enterprise order management procurement decision-makers.
United Kingdom
Mid-market food and beverage chains favor SaaS deployment models for rapid implementation without capital expenditure approval cycles. GDPR compliance requirements shape data residency and processing architecture decisions. London concentrates financial services and retail order management software demand.
Global Order Management Software Market Competitive Landscape
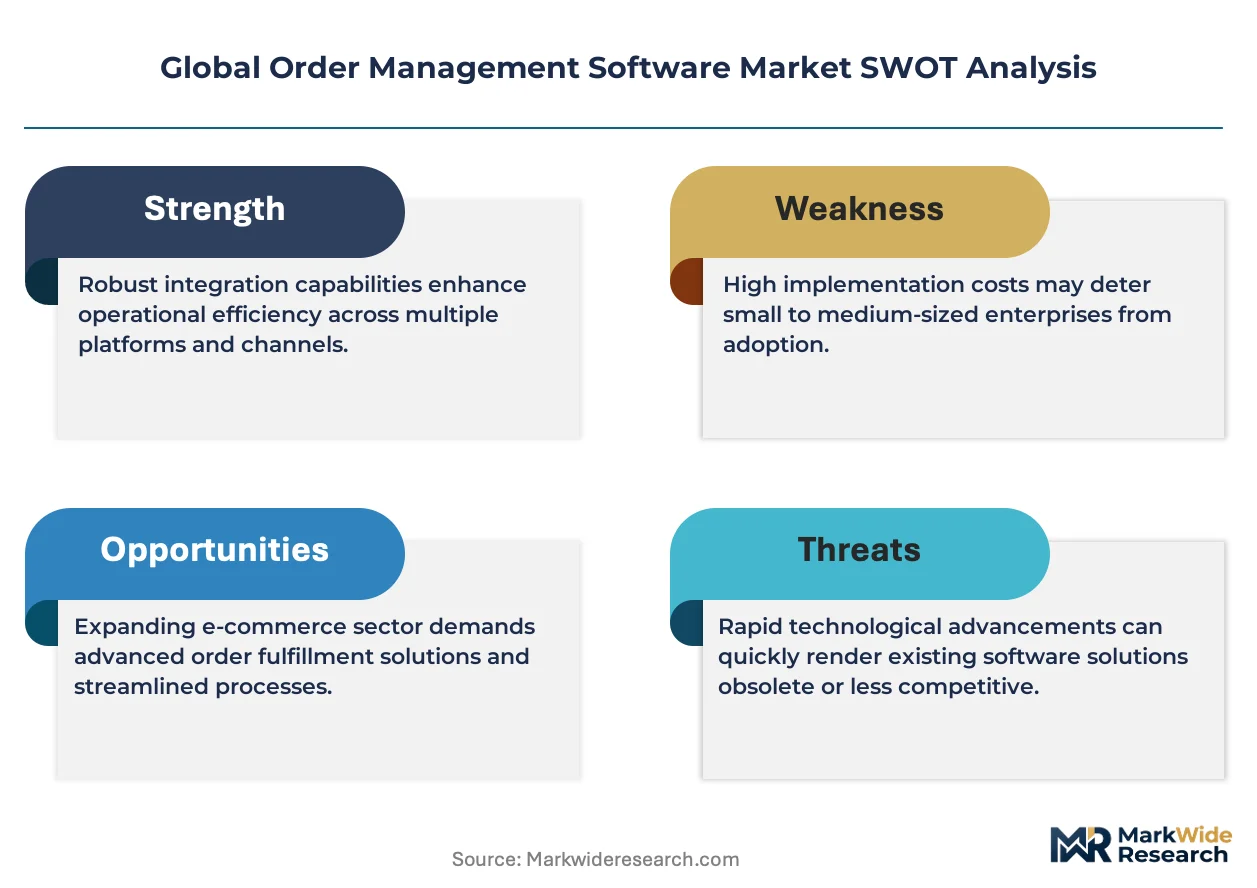
ERP-anchored incumbents and cloud-native specialists split the market between integration depth and deployment velocity. The vendor base organizes around three strategic archetypes: legacy ERP extenders, best-of-breed warehouse convergence players, and API-first SaaS platforms. Dominant competitive moves include hybrid architecture bridging and vertical-specific compliance module development.
Within the ERP-anchored tier, Oracle Corporation and SAP SE represent integration-heavy deployment models. Manhattan Associates exemplifies warehouse management convergence strategy. Salesforce.com, Inc. occupies a position in the CRM-integrated order orchestration segment. These three anchors illustrate the structural tension between unified data architecture and modular best-of-breed flexibility.
| Leading Market Players |
|---|
| IBM Corporation |
| Manhattan Associates |
| Oracle Corporation |
| Netsuite Inc. |
| Zoho Inventory |
| SAP SE |
| Blue Yonder, Inc. |
| Brightpearl |
| Salesforce.com, Inc. |
| Others |
Supply & Pricing Matrix
Elastic overcapacity in United States cloud regions is compressing implementation margins while simultaneously expanding vendor pricing power through value-added compliance modules. Order management software suppliers respond by anchoring premium tiers to EU AI Act documentation capabilities and FDA validation workflows.
Pricing Analysis
The EU AI Act dictates the pricing tier structure by mandating explainable AI documentation for automated order-routing decisions in European deployments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance complexity and integration depth. Price differentiation centers on ISO auditability certification and vertical-specific validation bundles. Cost compression in the economy tier is intensifying because hyperscaler infrastructure commoditizes baseline orchestration features. Mid-market retailers in Germany and France exhibit highest price sensitivity, while pharmaceutical enterprises in the United States demonstrate lowest sensitivity due to FDA 21 CFR Part 11 validation requirements.
Supply Chain Analysis
Export-control restrictions on advanced GPU clusters and AI training hardware are constraining vendor capacity expansion in certain cloud regions. Engineering talent concentrates in the United States, India, and Germany, with Bangalore and Hyderabad feeding platform development pipelines. Raw material dependencies center on hyperscaler data center infrastructure, open-source middleware libraries, and proprietary ERP connector IP. Single-source vulnerability persists for Oracle and SAP integration modules, where certified developer scarcity creates bottleneck conditions. Distribution runs through direct enterprise sales teams for large implementations and channel partners for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent order management vendors face substitution pressure from adjacent supply chain platforms absorbing OMS functionality into unified suites. Defense requires preemptive consolidation of integration touchpoints before buyers rationalize vendor relationships.
For Market Incumbents: Pre-empt API-first competitors by embedding warehouse management convergence deeper into core orchestration engines. Oracle and SAP must accelerate containerized microservices deployment to match cloud-native elasticity. Vertical integration into cold-chain verification modules for pharmaceutical clients anchors retention against best-of-breed specialists.
For New Entrants and Emerging Players: Establish a beachhead in India's third-party logistics segment where PLI scheme incentives are attracting fulfillment network modernization budgets. Target mid-market food and beverage chains in the United Kingdom seeking rapid SaaS deployment without capital expenditure cycles. Lead with headless commerce APIs enabling live-streaming checkout integration for United States direct-to-consumer brands.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment tiers as serverless compute models reduce baseline infrastructure requirements. Acquisition targets should display vertical-specific compliance engineering depth rather than horizontal feature breadth. Watch hyperscaler partnership certification velocity as the signal indicating platform scalability and enterprise readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Absorbing WMS and TMS functions into unified orchestration layers reduces buyer vendor counts. |
| Acquisition of Specialist Firm | Cold-chain verification capabilities from pharmaceutical-focused developers anchor regulated vertical retention. |
| Geographic Expansion | Local cloud regions in India satisfy BIS standards and RBI payment regulations for domestic deployments. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, and GCP enable multicloud Kubernetes orchestration for enterprise clients. |
| Product Launch | Explainable AI modules addressing EU AI Act transparency mandates capture premium pricing in European markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Secondary validation drew from SEC filings, hyperscaler capex disclosures, ERP vendor documentation, and customs records on software services trade. Bottom-up deployment estimates across cloud, SaaS, on-premise, and hybrid models were triangulated against top-down market sizing from vendor revenue disclosures and analyst briefings.
Calibration against historical refresh cycles and regulatory implementation timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment expansion and pharmaceutical serialization mandates as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure investment cycles or cross-border data localization policies would shift the trajectory. Forecasts reflect documented assumptions regarding ERP migration velocities and compliance deadline adherence. Cross-checking against hyperscaler earnings call commentary on enterprise software attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Home Fitness App Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
E-Invoicing Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Employee Wellness Software Market
Software & Services
Global Polling Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
App Development Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Category Management Software Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Inventory Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Transient Analysis Software Market
Software & Services
House Cleaning App Market
Software & Services
Account Reconciliation Software Market