
 North America Equity Management Software Market | 2026-2036
North America Equity Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Equity Management Software Market Analytics
The SEC's climate disclosure rules and emerging ESG reporting mandates for private companies is broadening the compliance burden that equity management platforms must address. Carta leverages its extensive cap table network to embed governance and sustainability tracking into core workflows. Eqvista specializes in streamlined 409A valuation and equity plan services for early-stage ventures. Computershare anchors institutional-grade transfer agency capabilities that extend into private market registry functions.
North America Equity Management Software encompasses digital platforms that automate equity plan administration, cap table tracking, valuation modeling, and stakeholder reporting for privately held and publicly traded enterprises. These systems integrate with ERP and HRIS architectures through standardized APIs, enabling real-time equity data synchronization across finance, legal, and human capital functions. Cloud-based deployment models dominate new implementations, though hybrid configurations persist among asset managers with stringent data residency requirements. Portfolio management functionality captures the largest revenue pool, while risk analytics modules represent the fastest-expanding segment as fiduciary scrutiny intensifies.
The SEC, FINRA, and IRS shape product development through disclosure timelines, broker-dealer custody rules, and equity compensation tax treatment respectively. Firms must architect audit trails that satisfy the SEC's private fund adviser requirements while maintaining IRS compliance for incentive stock option programs. Stakeholders should monitor how state-level privacy legislation in California and New York intersects with shareholder data handling protocols.
Market Dynamics
Venture capital portfolio density in California and New York is forcing equity management platforms to automate cap table reconciliation for complex waterfall scenarios. The SEC's private fund adviser rules now mandate granular fee and expense disclosure, compressing compliance timelines for general partners.
Growth Catalysts
- SEC Private Fund Adviser Rules:The SEC's enhanced disclosure mandates require institutional-grade audit trails, driving replacement of spreadsheet-based cap table management among mid-market private equity firms.
- Cloud ERP Integration:Native API connectivity with Workday and SAP SuccessFactors is pulling equity data into real-time compensation workflows for technology sector HR teams.
- Startup Ecosystem Concentration:Dense clusters of venture-backed companies in Austin and Boston are creating network effects that accelerate platform adoption across portfolio companies.
Market Restraints
- Data Residency Requirements:Asset managers with sovereign wealth limited partners face architectural constraints that block pure cloud deployment in certain fund structures.
- 409A Valuation Cost Volatility:Independent appraisal fees for early-stage companies fluctuate with audit complexity, creating procurement friction for bootstrapped ventures.
- Substitution by In-House Legal Teams:Large corporate law departments at Fortune 500 companies maintain proprietary equity tracking systems that resist external software migration.
Strategic Opportunities
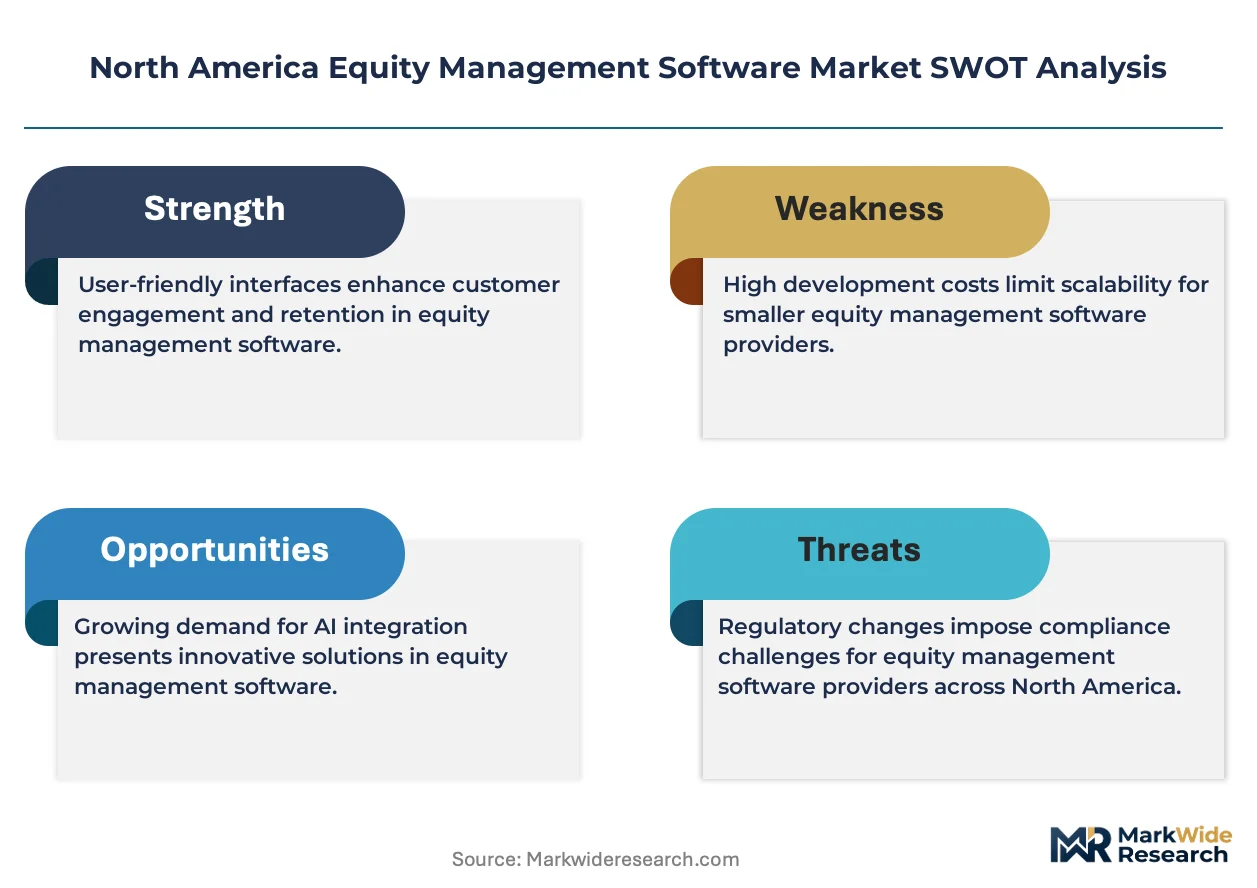
- Canadian Market Expansion:Toronto and Vancouver's emerging technology corridors show underpenetrated demand for automated equity plan administration relative to US saturation levels.
- ESG Disclosure Convergence:The EU's CSRD and anticipated SEC climate rules create a regulatory tailwind for platforms embedding sustainability metrics into governance workflows.
- AI-Enhanced Document Parsing:Machine learning extraction of vesting schedules from legal agreements is converging with natural language processing for stakeholder communications automation.
Industry Challenges
- Cross-Border Tax Expertise Scarcity:Platforms struggle to hire professionals fluent in both US IRC Section 409A and Canadian tax treatment of stock options.
- Legacy System Integration Complexity:Mainframe-based transfer agency systems at established financial institutions resist API modernization, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Equity Management Software Market |
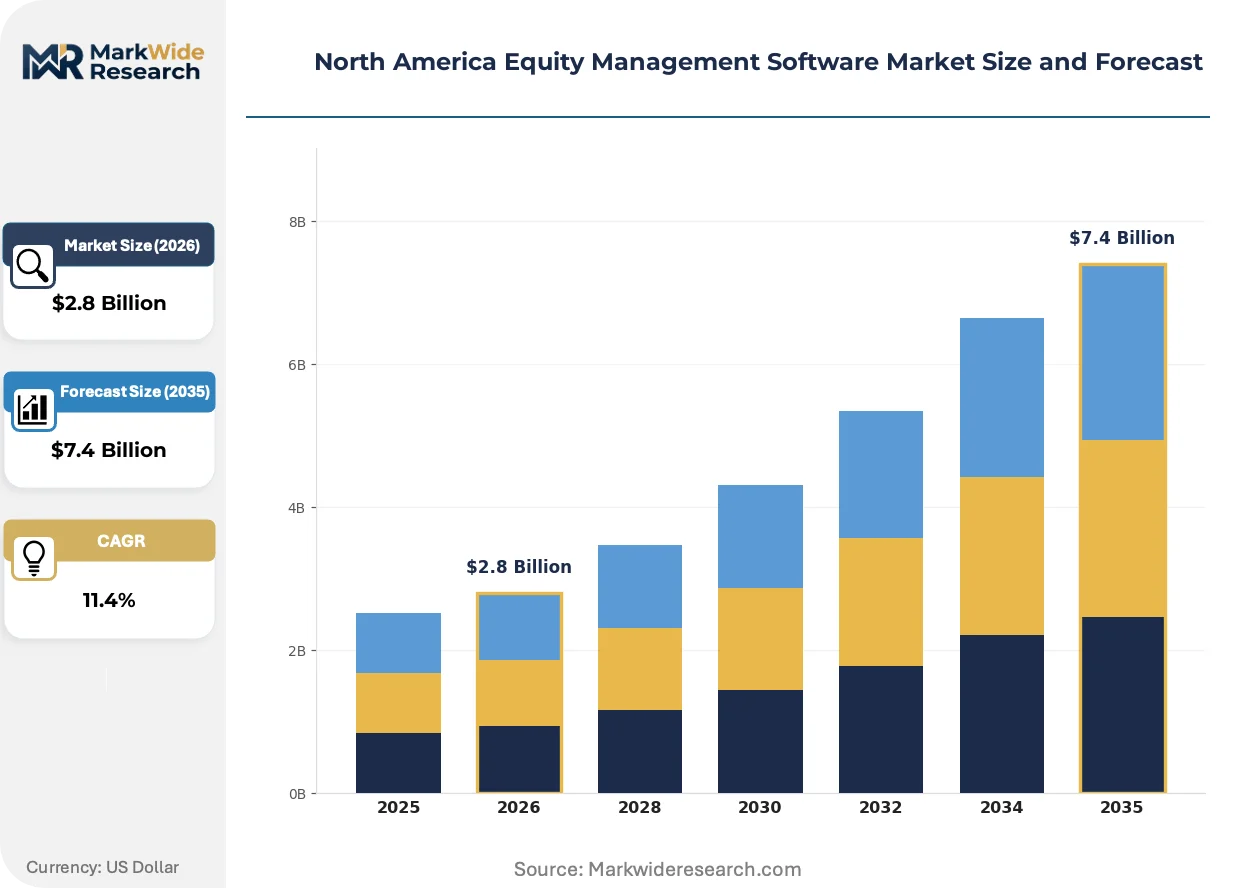
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Institutional Investors, Hedge Funds, Asset Managers, Family Offices Functionality: Portfolio Management, Risk Analytics, Reporting Tools, Transaction Management Service Type: Support Services, Consultation, Implementation, Training |
| Companies Covered | Carta, Eqvista, Gust Equity Management, Global Shares, Computershare, Certent, Morgan Stanley, Pulley, Ledgy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Equity Management Software Market Evolving Landscape
Platform architecture is pivoting from standalone cap table tools toward embedded finance infrastructure that sits within broader ERP and HRIS workflows. This convergence is compressing vendor margins while expanding addressable use cases.
Blockchain-based cap table infrastructure is consolidating shareholder registry functions across multiple jurisdictions into immutable distributed ledgers. Early-stage companies in Delaware and Cayman-domiciled fund structures are piloting tokenized equity instruments for cap table transparency. The technology is consolidating transfer agency costs that previously required separate legal opinions for each funding round.
The SEC's climate disclosure rules for private fund advisers are reshaping data collection workflows across North American equity platforms. General partners must now track and report portfolio company emissions alongside traditional financial metrics. Real estate and infrastructure-focused funds face the steepest compliance burden as they retrofit legacy assets for energy efficiency benchmarking.
Subscription pricing models are displacing perpetual license arrangements among mid-market private equity sponsors. Buyers now expect usage-based billing tied to portfolio company count rather than upfront implementation fees. This shift is most visible among emerging managers in Texas and Florida who prioritize cash flow flexibility over long-term cost optimization.
North America Equity Management Software Market Segmentation
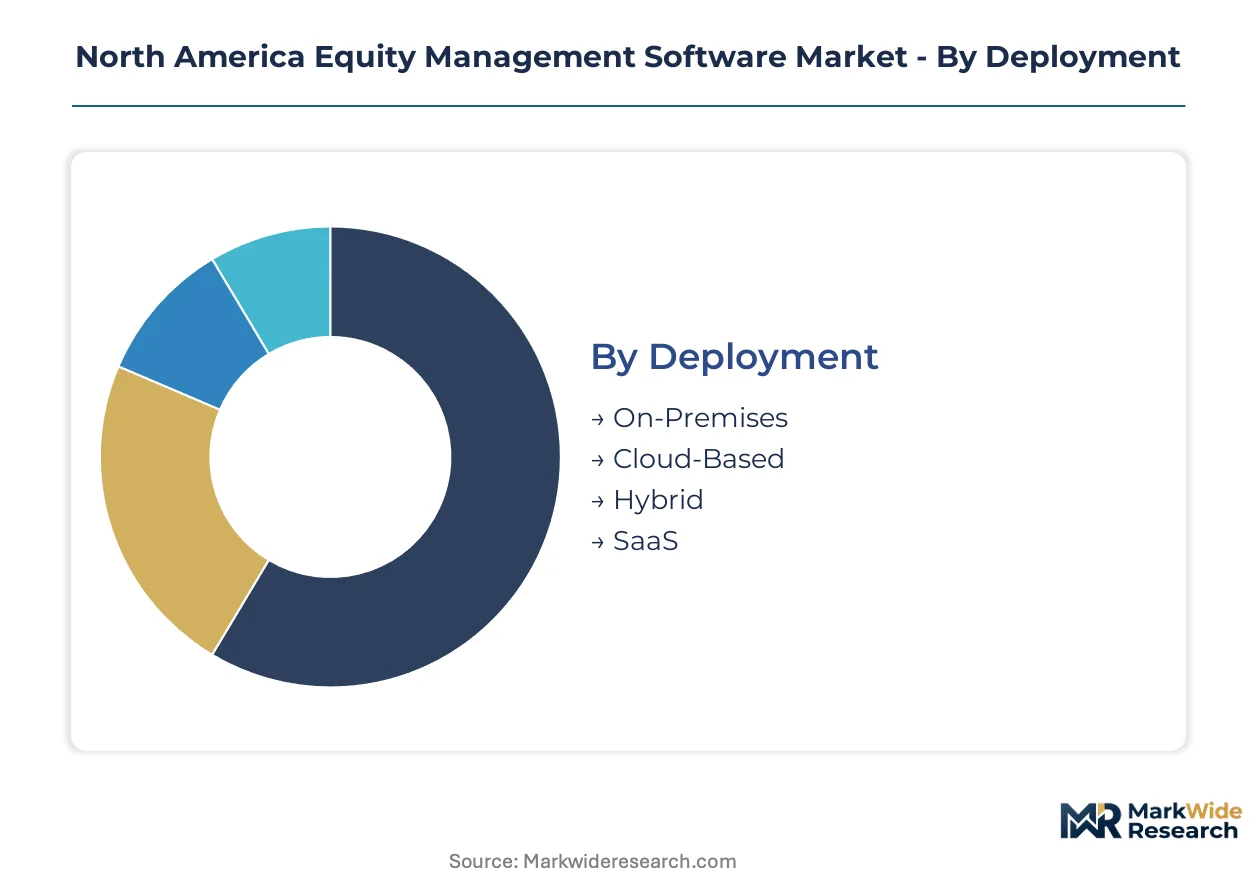
Equity management software purchasing decisions hinge on compliance architecture, integration requirements, and fund complexity tiers. Buyers evaluate deployment models against data residency obligations while matching functionality depth to portfolio sophistication.
Deployment:
Regulatory scrutiny over audit trail accessibility drives infrastructure procurement priorities.
- On-Premises:Dedicated hardware installations within client data centers satisfy sovereign wealth limited partner requirements for physical asset control. Asset managers in Texas and Florida favor this model for private equity funds with stringent custody rules.
- Cloud-Based:Multi-tenant SaaS architectures enable real-time cap table synchronization across distributed venture portfolios. California's Bay Area technology clusters are accelerating migration to pure cloud configurations for portfolio company network effects.
- Hybrid:Split architectures isolate sensitive shareholder data on-premises while pushing analytics workloads to public cloud infrastructure. Mid-market private equity sponsors in New York deploy this model to balance SEC audit requirements with computational flexibility.
- SaaS:Subscription-native platforms embed equity plan administration directly into Workday and SAP SuccessFactors workflows through standardized APIs. Emerging managers prioritize this model for cash flow flexibility over long-term cost optimization.
Volume sits with Cloud-Based deployments; growth tilts toward SaaS as ERP integration deepens.
End User:
Entity sophistication determines feature requirements from basic cap table tracking to multi-jurisdictional waterfall modeling.
- Institutional Investors:Pension funds and endowments require institutional-grade transfer agency capabilities with granular fee disclosure audit trails. The SEC's private fund adviser rules mandate enhanced transparency that spreadsheet-based systems cannot satisfy.
- Hedge Funds:Multi-strategy vehicles demand real-time risk analytics modules for derivatives overlay positions and complex fund-of-funds structures. Prime brokerage integration requirements favor platforms with robust API architectures.
- Asset Managers:Traditional long-only managers prioritize reporting tools for regulatory filings and client statements. Legacy mainframe integration challenges extend implementation timelines for established financial institutions.
- Family Offices:Single-family and multi-family offices seek streamlined 409A valuation services for direct venture investments. Cost volatility in independent appraisal fees creates procurement friction for smaller entities.
Asset Managers command the largest deployment base; Family Offices are expanding most quickly as wealth transitions accelerate.
Functionality:
Workflow automation depth separates basic record-keeping tools from strategic decision-support platforms.
- Portfolio Management:Comprehensive position tracking, waterfall modeling, and carried interest calculation engines form the revenue core. General partners rely on these modules for fund-level performance attribution across vintage years.
- Risk Analytics:Scenario modeling and stress testing capabilities address intensifying fiduciary scrutiny from limited partner advisory committees. Real estate and infrastructure funds face the steepest compliance burden for climate risk integration.
- Reporting Tools:Automated stakeholder communications and regulatory filing generation reduce legal team overhead. Machine learning extraction of vesting schedules is converging with natural language processing for document automation.
- Transaction Management:Secondary market trade execution and custody reconciliation streamline liquidity events for private company shareholders. Tokenized equity pilots in Delaware-domiciled structures are reshaping registry functions.
Portfolio Management captures current spending; Risk Analytics shows the steepest expansion trajectory as ESG disclosure mandates broaden.
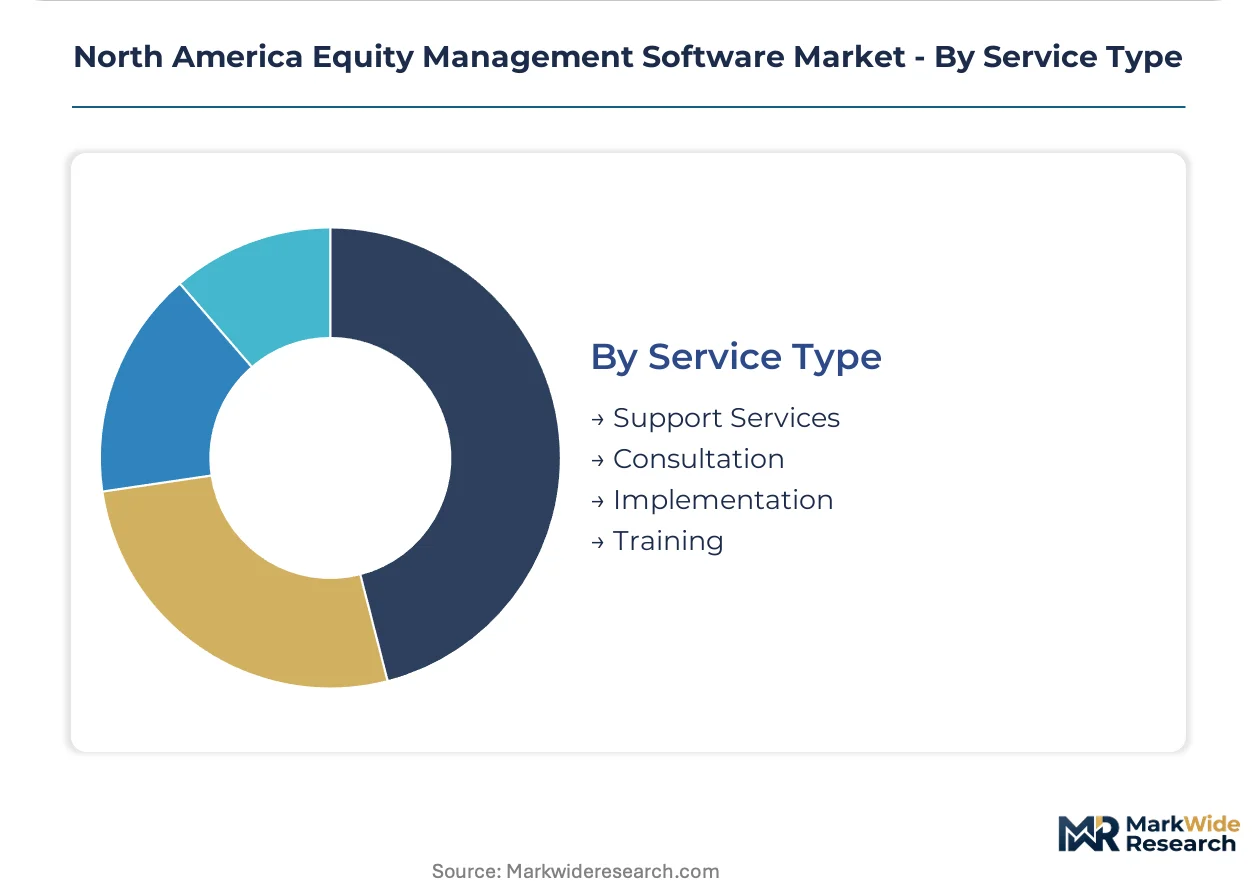
Service Type:
Implementation complexity and ongoing operational support requirements shape service bundling decisions.
- Support Services:Tiered help desk and technical maintenance contracts ensure platform uptime for mission-critical equity data. Response time guarantees differentiate vendor offerings for time-sensitive compliance deadlines.
- Consultation:Strategic advisory on equity plan design and regulatory navigation addresses cross-border tax expertise scarcity. Professionals fluent in both US IRC Section 409A and Canadian stock option treatment command premium engagement rates.
- Implementation:Data migration, system integration, and workflow configuration services bridge legacy transfer agency infrastructure to modern platforms. Mainframe-based systems at established institutions resist API modernization.
- Training:Administrator certification and end-user education programs accelerate platform adoption across finance, legal, and human capital functions. Dense venture clusters in Austin and Boston create network effects that amplify training ROI.
Support Services anchor recurring revenue; Consultation is gaining share fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Bay Area anchors North American demand for equity management platforms, with dense venture capital portfolios forcing automation of complex cap table waterfalls and stakeholder reporting workflows.
United States
The SEC's private fund adviser rules mandate granular fee disclosure audit trails that spreadsheet-based systems cannot satisfy. General partners in New York and Boston face compressed compliance timelines as institutional limited partners demand real-time transparency. Austin's emerging technology corridor creates network effects that accelerate platform adoption across venture-backed portfolio companies.
Canada
Toronto and Vancouver's technology corridors show underpenetrated demand relative to US saturation levels. The country's national securities regulator has aligned disclosure requirements with US standards, creating procurement tailwinds for platforms with cross-border tax expertise. Ontario-based pension funds and family offices are migrating from manual equity tracking to automated 409A valuation services.
Mexico
Nuevo León's manufacturing and technology hub is attracting venture capital that requires equity plan administration for cross-border employee compensation. The central bank's fintech licensing framework is formalizing custody requirements for private market securities. Mexico City Metro's startup ecosystem is piloting cloud-based cap table tools for early-stage venture structures.
North America Equity Management Software Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with transfer agency heritage. Platform providers cluster into three tiers: venture-focused SaaS native tools, institutional-grade legacy processors, and hybrid consultancies with valuation expertise. M&A activity concentrates on cap table automation startups absorbing 409A appraisal boutiques. Strategic partnerships between equity platforms and major cloud ERP vendors are reshaping distribution economics.
Among venture-native specialists, Carta and Pulley exemplify the SaaS-first archetype with API-centric architectures designed for distributed portfolio company networks. Eqvista occupies a position within the streamlined valuation services tier, targeting early-stage ventures with bundled 409A and equity plan administration. Computershare anchors the institutional-grade segment, leveraging transfer agency infrastructure to extend into private market registry functions.
| Leading Market Players |
|---|
| Carta |
| Eqvista |
| Gust Equity Management |
| Global Shares |
| Computershare |
| Certent |
| Morgan Stanley |
| Pulley |
| Ledgy |
| Others |
Value Network & Pricing Analysis
SaaS-native platform incumbents and legacy transfer agency processors occupy divergent pricing strata, with the former commanding recurring revenue premiums through API-embedded workflows while the latter defend contract values via custody compliance bundling. This bifurcation concentrates procurement decision-making among California venture capital firms and New York institutional limited partners who weight data residency guarantees against cash flow flexibility.
Pricing Analysis
Outcome-based pricing anchored to portfolio company count and audit trail granularity dominates procurement negotiations. Subscription tiers stratify across enterprise-grade compliance bundles, mid-market SaaS configurations, and startup-focused valuation-plus-cap table packages. Pricing pressure stems from emerging managers in Texas and Florida prioritizing usage-based billing over upfront implementation fees. Family offices exhibit highest price sensitivity due to 409A appraisal cost volatility, while sovereign wealth limited partners accept premium pricing for on-premises data control.
Supply Chain Analysis
Domestic-content mandates from the SEC's private fund adviser rules and state-level privacy legislation in California and New York are reshaping vendor infrastructure deployment. Cloud computing capacity concentrates in US-based hyperscaler regions, with secondary dependencies on Canadian data centers for cross-border fund structures. API middleware and machine learning document parsing modules draw from specialized development shops in Austin and Boston. Single-source vulnerability sits with legacy mainframe transfer agency systems resisting modernization. Distribution runs through direct enterprise sales teams and strategic partnerships with Workday and SAP SuccessFactors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cross-border tax expertise fluent in both US IRC Section 409A and Canadian stock option treatment props vendor pricing power across the North American equity management software market.
For Market Incumbents: To counter API-native challengers eroding mid-market share, incumbents should deepen ERP integration partnerships with Workday and SAP SuccessFactors while acquiring 409A valuation boutiques to consolidate bundled service offerings. Custody compliance bundling remains the priority defensive lever against pure-play SaaS disintermediation. For New Entrants and Emerging Players: Begin with Toronto and Vancouver's underpenetrated technology corridors where automated equity plan administration lags US saturation levels. Target single-family offices managing direct venture investments through streamlined 409A and cap table bundles. A channel partnership route through Canadian pension fund consultants accelerates referenceability. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid consultancies possessing valuation expertise given the SEC's climate disclosure convergence with ESG reporting mandates. Long-term viability hinges on platforms embedding sustainability metrics into governance workflows. Watch for tokenized equity pilot scale in Delaware-domiciled structures as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native API connectivity with Workday pulls equity data into real-time HR compensation workflows. |
| Acquisition of Specialist Firm | Cap table automation startups absorbing 409A boutiques consolidate bundled valuation services. |
| Geographic Expansion | Toronto and Vancouver corridors show procurement tailwinds from Ontario pension fund migration. |
| Strategic Partnership | Cloud ERP vendor alliances reshape distribution economics for mid-market private equity sponsors. |
| Product Launch | Blockchain-based shareholder registry pilots in Cayman-domiciled funds reduce transfer agency costs. |
Research Methodology
Independent corroboration across cap table administrators, venture capital operating partners, and compliance officers at private fund advisers underwrites the qualitative findings. Primary fieldwork engaged CFOs at technology sector portfolio companies, SEC regulatory counsel, and HRIS integration specialists. Secondary validation drew from SEC private fund adviser rule filings, FINRA custody guidance, and hyperscaler capex disclosures for cloud infrastructure deployment. Bottom-up platform adoption modeling triangulates against top-down venture capital deployment data.
Rate-of-change decomposition across deployment models, end user sophistication tiers, and functionality depth modules structures the analytical framework. Segmentation dimensions span cloud versus on-premises versus hybrid architectures, institutional investor versus family office versus asset manager profiles, and portfolio management versus risk analytics versus transaction management capabilities. CAGRs derive from vendor revenue run-rates, customer count expansion, and average contract value trajectories. Forecast inputs incorporate ERP integration penetration rates and 409A appraisal volume elasticity.
Regulatory timeline delays, sovereign wealth data residency requirement tightening, and machine learning document parsing accuracy thresholds are the dominant revision risks. Forecasts reflect assumptions around SEC climate disclosure implementation pacing and cross-border tax expertise pipeline development. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Multiphysics Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Laser Engraving Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Aviation Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Europe Database Management Software Market
Software & Services
HACCP Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
OCR Scanning Software Market