
 Global Inside Sales Software Market | 2026-2036
Global Inside Sales Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inside Sales Software Market Foresight
Multi-source vendor strategies is decoupling from traditional single-platform commitments as enterprises hedge against integration lock-in. Salesforce Sales Cloud anchors its position through deep CRM ecosystem control, while Outreach competes through specialized sales engagement workflow automation. Apollo.io differentiates by embedding proprietary buyer-intent data directly into prospecting sequences.
Inside sales software denotes cloud-native and on-premise platforms that orchestrate remote selling workflows through predictive dialers, conversation intelligence, and pipeline analytics with API-driven CRM synchronization. Cloud-based deployment leads solution architecture as organizations prioritize elastic infrastructure over fixed-capacity on-premise installations. Lead management and sales engagement categories capture concentrated margin pools, while analytics and reporting functions mature into table-stakes requirements rather than premium differentiators.
The EU AI Act and GDPR framework in Europe, alongside HIPAA obligations in US healthcare-adjacent sales operations, shape product roadmaps toward auditable automation and consent-managed outreach. India's Digital Personal Data Protection Act and China's PIPL standards further fragment compliance requirements for multinational vendors. Stakeholders must evaluate whether their architecture supports jurisdiction-specific data residency without fragmenting the unified rep experience.
Market Dynamics
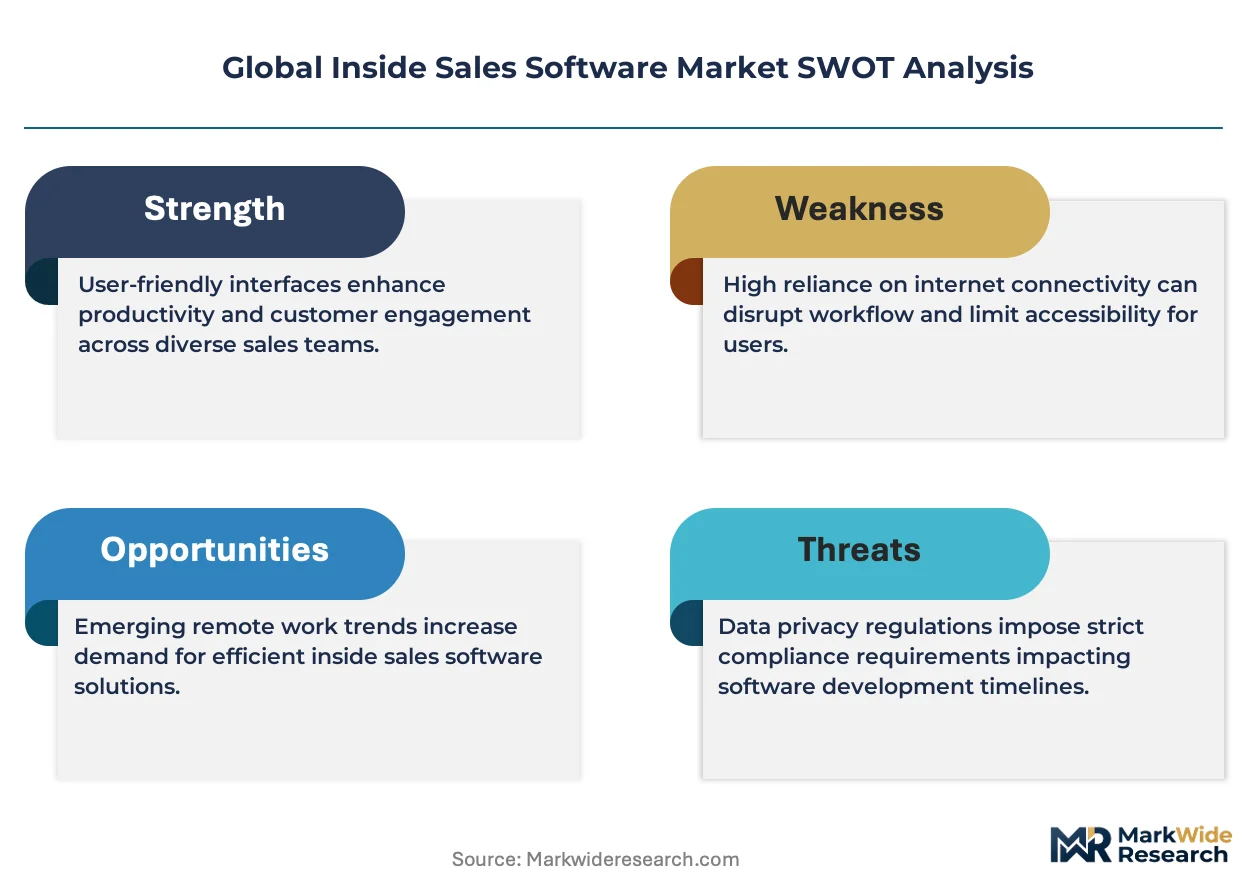
Enterprise procurement teams are decoupling from single-vendor CRM ecosystems, forcing sales engagement platforms to interoperate through open APIs rather than proprietary data models.
Growth Catalysts
- EU AI Act compliance requirements:European enterprises are accelerating procurement of auditable automation tools with built-in consent management and explainable AI documentation for sales outreach sequences.
- Remote sales infrastructure buildouts in India:IT services and BPO clusters in Bangalore and Hyderabad are deploying cloud-native dialer systems to support distributed inside sales teams serving North American and European clients.
- HIPAA-aligned healthcare sales operations:US-based medical device and pharmaceutical vendors are investing in conversation intelligence platforms with encrypted call recording and automated PHI redaction capabilities.
Market Restraints
- Data residency fragmentation:India's Digital Personal Data Protection Act and China's PIPL impose conflicting localization requirements that fragment unified rep experiences across multinational deployments.
- Legacy CRM switching costs:Deep Salesforce ecosystem entrenchment creates integration friction for alternative sales engagement platforms seeking enterprise adoption.
- API rate limiting by incumbent platforms:Established CRM vendors are constraining third-party data synchronization throughput, degrading real-time pipeline visibility for competing engagement tools.
Strategic Opportunities
- German Mittelstand segment:Mid-market manufacturers with export-oriented sales teams remain underpenetrated by specialized inside sales platforms, presenting white space for localized deployment.
- Revenue operations (RevOps) convergence:Integration of sales engagement data with marketing automation and customer success platforms creates cross-functional workflow orchestration demand.
- ISO 27001 and SOC 2 Type II certification:Enterprise procurement mandates for security attestations are creating competitive separation for vendors with completed audits versus those in process.
Industry Challenges
- Conversation intelligence model training:Scarcity of multilingual audio datasets with proper licensing for commercial AI training constrains non-English product capabilities.
- Telecommunications carrier integration:Maintaining reliable VoIP connectivity across disparate regional carriers requires ongoing engineering investment and partnership management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inside Sales Software Market |
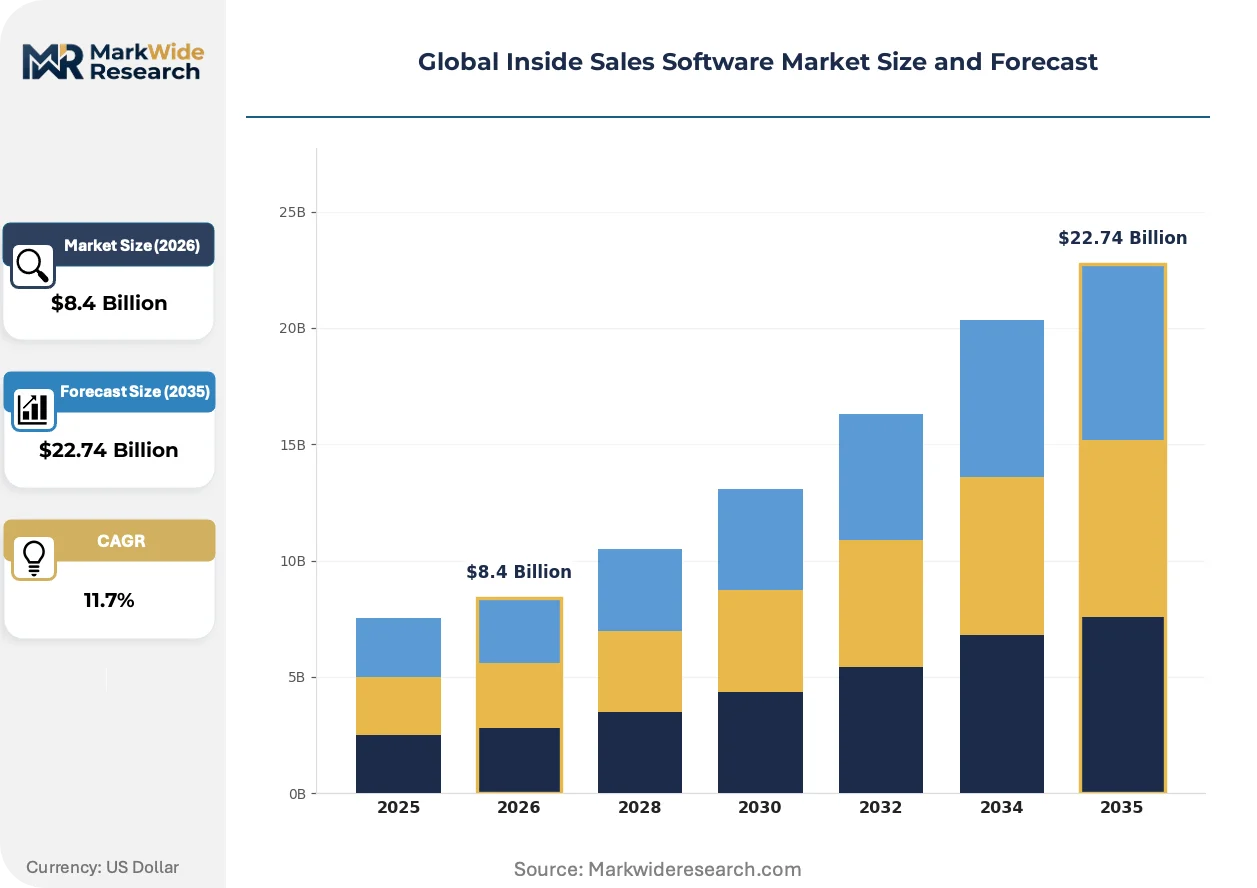
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Virtual Private Cloud Solution Type: Lead Management, Predictive Dialer, Sales Engagement, Analytics & Reporting, Customer Relationship Management End User Industry: BFSI, Telecommunication, Information Technology, Manufacturing, Education Sales Channel: Direct Sales, Partner Sales, Online Sales, Inside Sales Teams |
| Companies Covered | Salesloft, ZoomInfo Sales OS, Salesforce Sales Cloud, Freshsales, Apollo.io, HubSpot Sales Hub, Outreach, Close, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inside Sales Software Market Shifts & Advancements
Workflow automation architectures are fragmenting from monolithic platforms toward composable stacks, with buyers assembling best-of-breed components through middleware layers rather than accepting bundled functionality.
Real-time buyer intent signal aggregation is decentralizing prospecting workflows across the inside sales stack. Revenue teams at B2B software vendors and financial services firms are ingesting third-party data streams—funding announcements, technographic changes, and hiring velocity—directly into sequence triggers without CRM intermediary steps. This compression of the data-to-action pipeline is reducing lead response latency from hours to minutes.
GDPR Article 22 and the EU AI Act's automated decision-making provisions are forcing architectural changes in predictive lead scoring and next-best-action engines. Vendors serving European enterprises must now implement human-in-the-loop overrides and algorithmic impact assessments for AI-driven outreach prioritization. German and French data protection authorities are actively auditing sales automation deployments for compliance depth.
Subscription fatigue among mid-market buyers is compressing vendor consolidation cycles. Procurement teams in US technology and professional services verticals are unbundling point solutions—separating dialer infrastructure from conversation analytics from engagement sequencing—to reduce redundant per-seat licensing. This disaggregation favors vendors with transparent API pricing and modular feature activation over all-in-one platform positioning.
Global Inside Sales Software Market Segmentation
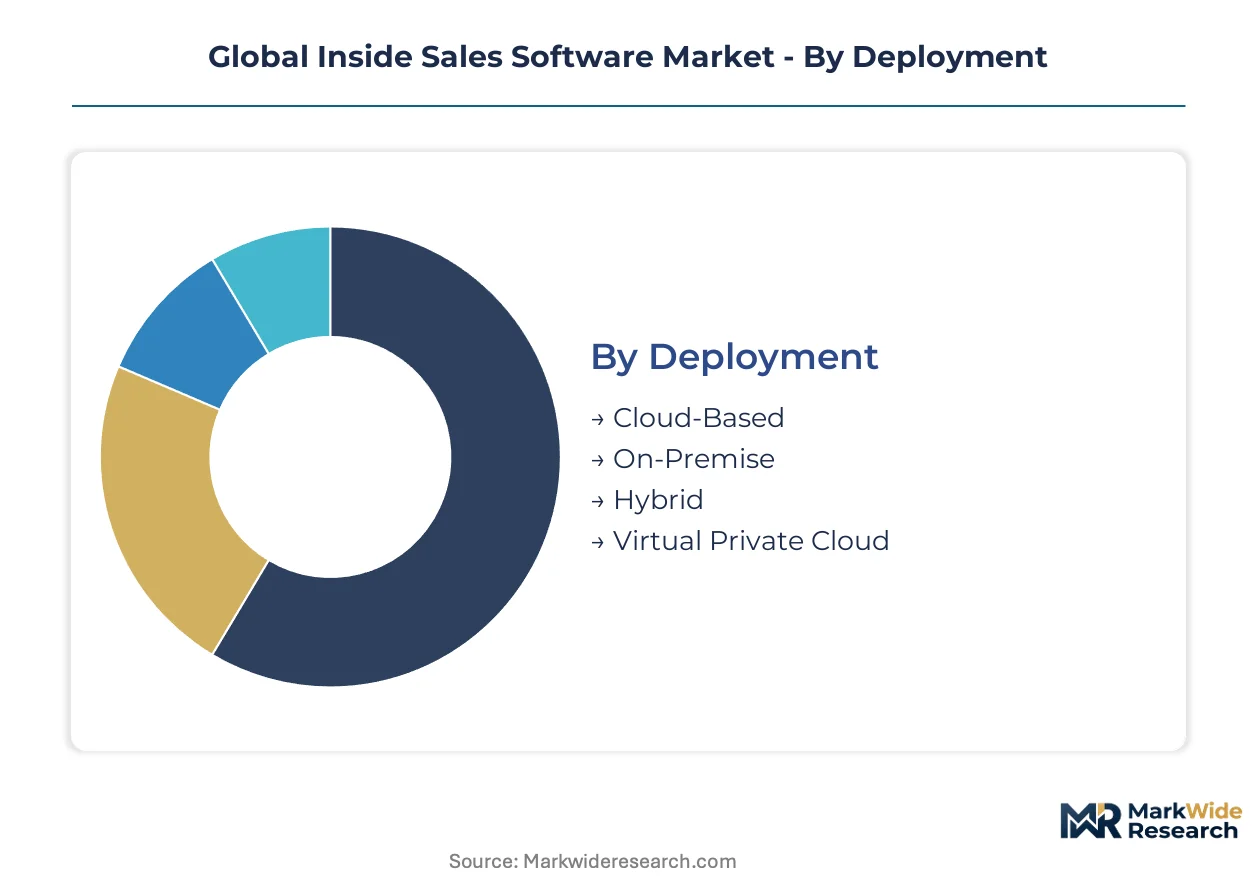
Inside sales software procurement varies sharply by deployment architecture and regulatory exposure. Buyers segment solutions by data sovereignty requirements, integration complexity, and end-use compliance obligations rather than feature checklists alone.
Deployment:
ISO 27001 and SOC 2 Type II certifications dominate procurement mandates for cloud-based solutions, while on-premise and hybrid architectures face heightened scrutiny under GDPR Article 44 data transfer mechanisms and India's Digital Personal Data Protection Act localization rules.
- Cloud-Based:Elastic infrastructure with multi-tenant architecture supports rapid scaling for distributed sales teams. Demand concentrates among US SaaS vendors and Indian IT services clusters in Bangalore and Hyderabad serving North American clients, driven by subscription flexibility and reduced capital expenditure.
- On-Premise:Fixed-capacity installations with direct hardware control appeal to defense contractors and EU financial institutions under strict data residency requirements. German Mittelstand manufacturers with export-oriented sales teams favor this architecture for GDPR Article 22 auditability in automated decision-making systems.
- Hybrid:Split workloads between private infrastructure and public cloud tiers balance latency-sensitive dialer operations with centralized analytics storage.
- Virtual Private Cloud:Isolated network segments within hyperscaler environments address HIPAA-aligned healthcare sales operations requiring encrypted PHI processing without full on-premise burden.
Leading the category by volume: Cloud-Based. Growing fastest: Virtual Private Cloud.
Solution Type:
Margin concentration follows workflow automation depth, with sales engagement and lead management commanding premium pricing against commoditizing analytics layers.
- Lead Management:Pipeline prioritization engines with AI-driven scoring and routing. BFSI institutions in the United States and telecommunication carriers in Germany deploy these systems for high-velocity prospect qualification, constrained by EU AI Act explainability requirements for automated ranking algorithms.
- Sales Engagement:Multi-channel sequence orchestration across email, voice, and social touchpoints. Information technology vendors and financial services firms ingest real-time buyer intent signals directly into trigger workflows, compressing lead response latency from hours to minutes.
- Predictive Dialer:Algorithmic call pacing with abandonment rate optimization and compliance recording.
- Analytics & Reporting:Dashboard visualization and pipeline forecasting with API-driven CRM synchronization.
- Customer Relationship Management:Core contact management with opportunity tracking and account hierarchy mapping.
Highest margin capture: Sales Engagement. Steepest expansion trajectory: Lead Management.
End User Industry:
Compliance burden varies by vertical, with healthcare-adjacent manufacturing and BFSI facing HIPAA and GDPR dual obligations that shape feature prioritization.
- BFSI:Conversation intelligence with real-time regulatory scripting and automated disclosure tracking. US banks and EU insurers under ECB and national financial authority oversight require auditable automation with human-in-the-loop overrides for high-value product recommendations.
- Telecommunication:High-volume outbound infrastructure with carrier-grade VoIP reliability and TCPA consent management. Indian BPO clusters serving European and North American markets prioritize multilingual conversation intelligence capabilities constrained by scarce licensed audio datasets.
- Information Technology:Agile integration with product usage data and customer success platforms.
- Manufacturing:Long-cycle opportunity management with distributor portal integration and configure-price-quote alignment.
- Education:Enrollment pipeline tracking with federal financial aid compliance and student privacy protections.
Deepest technology penetration: Information Technology. Fastest emerging demand: Manufacturing.
Sales Channel:
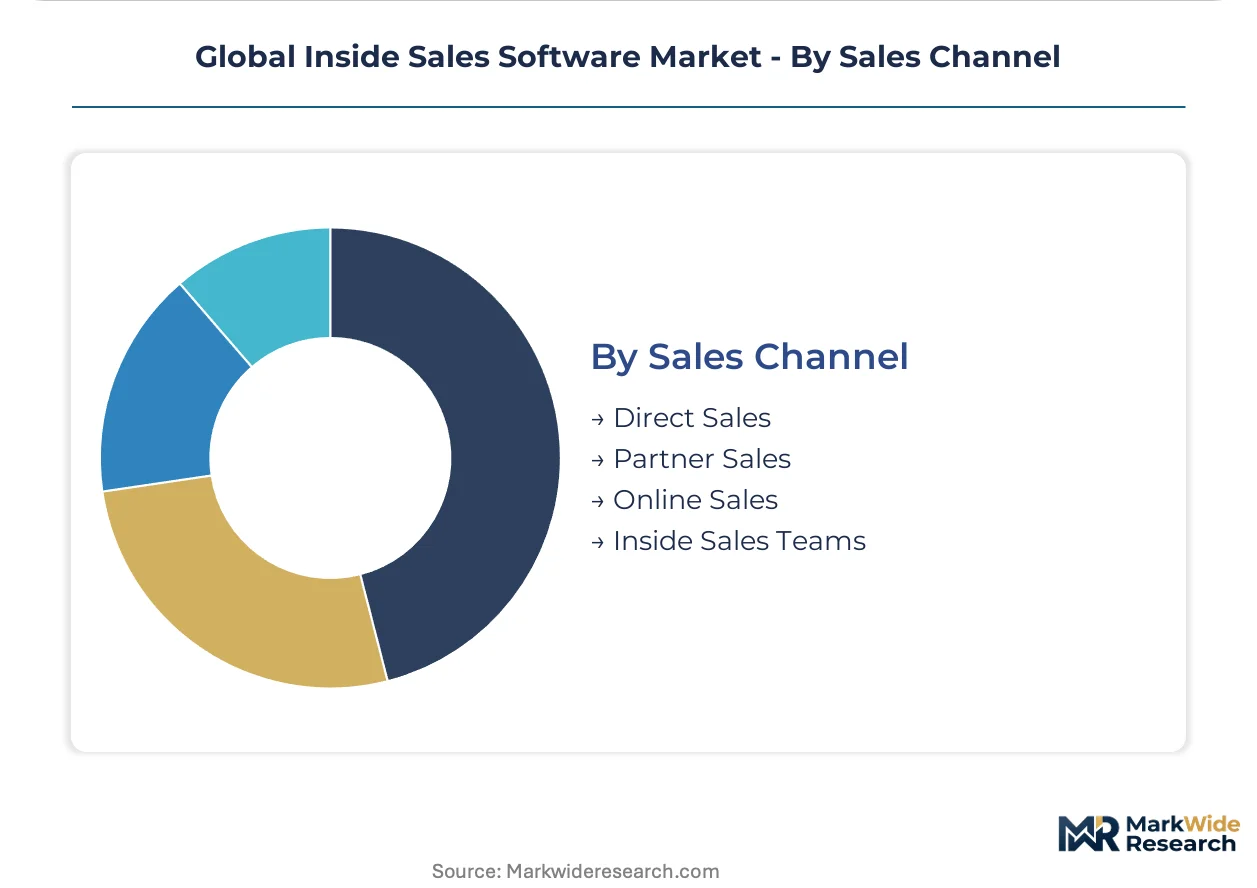
Channel selection reflects buyer sophistication and integration complexity, with direct relationships dominating enterprise deployments and partner networks capturing mid-market scale.
- Direct Sales:Vendor field teams with dedicated solution architects and custom implementation services. Large enterprises in the United States and Germany procure through this channel for complex CRM ecosystem integration and GDPR Article 22 compliance consulting.
- Partner Sales:Systems integrators and value-added resellers with vertical specialization. Indian IT services firms and European consultancies bundle inside sales platforms with broader digital transformation engagements, accelerating deployment in underpenetrated Mittelstand segments.
- Online Sales:Self-service procurement with transparent API pricing and modular feature activation.
- Inside Sales Teams:Vendor's own remote sales operations demonstrating platform capabilities through live usage.
Dominant revenue contribution: Direct Sales. Gaining share fastest: Partner Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments in Virginia, Oregon, and Frankfurt anchor the geographic distribution of inside sales software demand. Enterprise procurement concentrates where data center density meets regulatory clarity.
United States
HIPAA-aligned healthcare sales operations drive specialized conversation intelligence procurement among medical device vendors. The FTC and SEC enforce disclosure requirements on automated outreach systems. Seattle and San Francisco Bay Area clusters host the highest density of sales engagement platform engineering talent.
Germany
Export-oriented Mittelstand manufacturers deploy on-premise architectures for GDPR Article 22 auditability in automated decision-making. The EU AI Act mandates explainable AI documentation for predictive lead scoring engines. Bavarian industrial automation firms in Munich and Nuremberg represent the fastest-growing regional adoption segment.
India
IT services and BPO clusters in Bangalore and Hyderabad scale cloud-native dialer systems for North American and European client service. The Digital Personal Data Protection Act imposes localization requirements that complicate unified rep experiences. Telangana's HITEC City corridor concentrates the highest deployment velocity for multilingual conversation intelligence.
United Kingdom
Financial services firms in London integrate sales engagement data with regulatory reporting infrastructure under FCA oversight. GDPR compliance shapes procurement toward auditable automation with consent-managed outreach. The Thames Valley technology corridor hosts emerging RevOps convergence deployments linking marketing automation with customer success platforms.
Japan
Enterprise software vendors in Tokyo prioritize integration with existing keiretsu CRM ecosystems over greenfield platform replacement. METI guidelines on AI governance influence product roadmap prioritization for algorithmic transparency. Osaka-based manufacturing exporters represent underpenetrated demand for long-cycle opportunity management with distributor portal alignment.
Global Inside Sales Software Market Competitive Landscape
Global majors compete with regional champions across integration depth and compliance specialization. The vendor base stratifies into three tiers: full-stack CRM incumbents with ecosystem lock-in, specialized sales engagement pure-plays with workflow automation depth, and emerging intent-data aggregators with proprietary signal networks. Dominant competitive moves include API-first interoperability investments and jurisdiction-specific data residency certifications.
Within the specialized engagement tier, Outreach and Apollo.io occupy positions emphasizing workflow automation and buyer-intent integration respectively. Salesforce Sales Cloud anchors the full-stack category through deep CRM ecosystem control. Salesloft exemplifies the revenue operations convergence archetype linking sales engagement with customer success orchestration.
| Leading Market Players |
|---|
| Salesloft |
| ZoomInfo Sales OS |
| Salesforce Sales Cloud |
| Freshsales |
| Apollo.io |
| HubSpot Sales Hub |
| Outreach |
| Close |
| Pipedrive |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates are forcing procurement teams toward auditable automation platforms with built-in consent management, compelling vendors to absorb certification costs and restructure subscription tiers around jurisdictional deployment requirements. This demand-side pressure concentrates pricing power with ISO 27001-certified providers while fragmenting supply chain coordination across regional cloud infrastructure clusters.
Pricing Analysis
Implementation services and ongoing compliance support are increasingly unbundled from base platform subscriptions, with German Mittelstand manufacturers and US healthcare-adjacent vendors paying premiums for GDPR Article 22 auditability and HIPAA-aligned encryption modules. Three-tier pricing structure across premium, standard, and economy levels reflects deployment architecture complexity, with Virtual Private Cloud configurations commanding substantial uplifts over multi-tenant cloud baselines. Cost compression in mid-market SaaS tiers is intensifying because procurement teams are consolidating redundant per-seat licenses across engagement, dialer, and analytics point solutions. Indian IT services clusters demonstrate highest price sensitivity due to volume-scaled BPO procurement, while EU financial institutions under ECB oversight show lowest elasticity given regulatory non-negotiability.
Supply Chain Analysis
Engineering talent scarcity in Bangalore and Hyderabad is constraining platform development velocity for cloud-native dialer systems, while Seattle and San Francisco Bay Area clusters anchor conversation intelligence R&D. Hyperscaler infrastructure in Virginia, Oregon, and Frankfurt supplies elastic compute for distributed sales teams, with API middleware development drawing from Telangana's HITEC City corridor and Bavaria's Munich-Nuremberg automation cluster. Single-source vulnerability concentrates in telecommunications carrier integrations for VoIP connectivity across regional networks. Distribution runs through direct vendor field teams for enterprise deployments, partner networks for Mittelstand segments, and self-service portals for mid-market SaaS procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Inside Sales Software Market operates as a cost-of-compliance story where GDPR Article 22 and EU AI Act documentation requirements create durable barrier-to-entry moats for vendors with completed security attestations. This regulatory scaffolding favors incumbents with established certification depth while raising capital requirements for new platform development.
For Market Incumbents: Cement ecosystem lock-in through deeper CRM integration investments and jurisdiction-specific data residency architectures that fragment competitor access to multinational deployments. Prioritize ISO 27001 and SOC 2 Type II certification maintenance as defense against emerging pure-plays with workflow automation depth. Vertical integration into proprietary buyer-intent data networks reduces substitution risk from Apollo.io-style signal aggregators. For New Entrants and Emerging Players: Launch via partner sales channels targeting underpenetrated German Mittelstand manufacturers with export-oriented inside sales teams lacking specialized platform support. White space concentrates in HIPAA-aligned healthcare conversation intelligence with automated PHI redaction, where incumbent API rate limiting degrades competing engagement tools. Modular feature activation with transparent API pricing addresses subscription fatigue among US technology vertical procurement teams. For Investors and Strategic Acquirers: Re-rating potential sits with revenue operations convergence platforms given RevOps integration demand linking sales engagement with customer success orchestration. Long-term viability favors vendors with multilingual conversation intelligence capabilities and licensed audio dataset moats for non-English market expansion. Monitor EU AI Act enforcement depth by German and French data protection authorities as inflection indicator for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep CRM ecosystem control anchors retention against API-first competitors. |
| Acquisition of Specialist Firm | Buyer-intent data networks reduce lead response latency from hours to minutes. |
| Geographic Expansion | Indian BPO clusters in Bangalore demand cloud-native dialer infrastructure scale. |
| Product Launch | Human-in-the-loop overrides address EU AI Act automated decision-making provisions. |
| Strategic Partnership | Telecommunications carrier alliances secure VoIP reliability across fragmented networks. |
Research Methodology
Document review covered SEC filings from sales engagement vendors, hyperscaler capex disclosures, and EU regulatory guidance documents, complemented by interviews with CTOs at BFSI institutions, IT procurement officers at German manufacturers, platform engineers at Indian IT services clusters, and integration specialists at systems integrators. Secondary validation drew from GDPR implementation case studies, HIPAA compliance frameworks, and cloud infrastructure deployment databases. Bottom-up and top-down triangulation reconciled vendor-reported seat counts with enterprise procurement survey data.
Market size outputs calibrated against deployment architecture splits and solution type margin pools across the projection horizon, with segmentation modeling spanning cloud-based, on-premise, hybrid, and Virtual Private Cloud deployment models alongside lead management, sales engagement, and predictive dialer solution categories. CAGRs derived from elasticity-adjusted adoption curves and compliance-driven replacement cycles. Forecast inputs incorporated EU AI Act implementation timelines and India's Digital Personal Data Protection Act localization requirements.
The model assumes a particular technology adoption path; alternative pathways for composable workflow stacks would alter the outlook if middleware abstraction layers accelerate unbundling beyond projected rates. Forecasts reflect assumptions around regulatory enforcement consistency and carrier integration reliability. Material deviation in EU AI Act audit frequency or telecommunications partnership stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Brain Training Software Market
Software & Services
Packaged Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Channel Management Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Strategy Management Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Live Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Computer Backup Software Market
Software & Services
United States Contract Lifecycle Management Software Market
Software & Services
Automotive Design Software Market
Software & Services
India Sports Management Software Market
Software & Services
Combat Management Systems Software Market