
 Global Manufacturing Operations Management (MOM) Software Market | 2026-2036
Global Manufacturing Operations Management (MOM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manufacturing Operations Management (MOM) Software Market Intelligence
The direct-to-enterprise sales channel is tilting towards a hybrid model that incorporates cloud marketplaces and system integrator partnerships. Siemens leverages its extensive industrial automation portfolio to embed MOM solutions within larger digital factory frameworks. Rockwell Automation competes with its FactoryTalk suite, targeting complex process manufacturing environments. SAP integrates its MOM capabilities directly with its core ERP systems, offering a unified data model for enterprise clients.
Manufacturing Operations Management software provides a digital framework for managing end-to-end production processes on the factory floor. It integrates real-time machine data with higher-level enterprise systems, creating a unified view of production scheduling, inventory, and quality control. Cloud-based deployment is becoming the standard for new installations, offering greater flexibility than on-premise solutions. Within solution offerings, modules for performance analytics and compliance management are critical for regulated sectors like aerospace components and food processing.
Compliance with standards such as the US FDA's 21 CFR Part 11 for electronic records and the EU's Medical Device Regulation (MDR) for traceability are key adoption drivers. Global quality benchmarks like ISO 9001 further necessitate robust quality management modules within MOM platforms. Vendor selection increasingly hinges on a platform's ability to support multi-site operations under disparate, evolving regulatory regimes.
Market Dynamics
The central force shaping the market is the convergence of operational technology (OT) on the factory floor with enterprise-level information technology (IT). This integration is driven by demands for multi-site production visibility and stringent regulatory mandates for data integrity.
Growth Catalysts
- Regulatory Mandates:Stringent regulations, including the US FDA's 21 CFR Part 11 and the EU's Medical Device Regulation (MDR), compel life sciences manufacturers to adopt MOM software for validated electronic records and end-to-end traceability.
- Industry 4.0 Initiatives:National industrial strategies, particularly in advanced manufacturing hubs like Germany, promote the adoption of digital factory frameworks, where MOM software is a foundational component for real-time production monitoring and control.
- Quality Management Standards:The need to comply with global quality benchmarks such as ISO 9001 pushes sectors like aerospace and automotive to implement MOM solutions with integrated quality and performance analytics modules.
Market Restraints
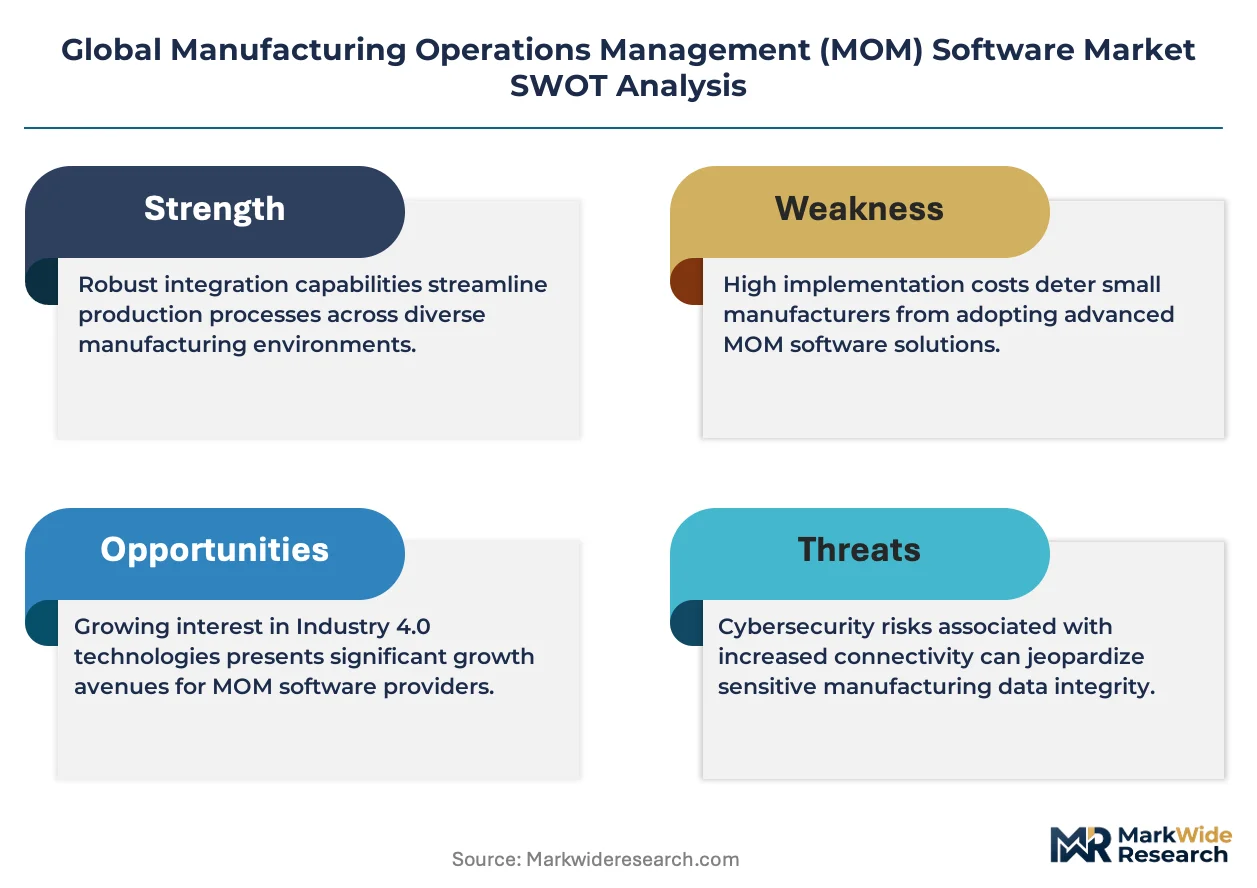
- High Implementation Costs:The significant upfront investment required for software licensing, system integration, and employee training presents a substantial barrier, especially for small and medium-sized manufacturers.
- Legacy System Integration:Integrating modern MOM software with a heterogeneous landscape of aging, proprietary factory equipment and existing enterprise resource planning (ERP) systems is complex and resource-intensive.
- Vendor Lock-In:The high cost and operational disruption associated with switching comprehensive MOM platforms create a risk of vendor lock-in, limiting an enterprise's future flexibility and negotiating power.
Strategic Opportunities
- SaaS for SMEs:Developing scalable, subscription-based cloud MOM solutions tailored for small and medium-sized enterprises (SMEs) opens a largely underpenetrated segment of the industrial market.
- AI-Powered Analytics:Embedding artificial intelligence and machine learning algorithms into MOM platforms to offer predictive maintenance and prescriptive quality control represents a significant value-add opportunity beyond basic data visualization.
- Cloud Marketplace Channels:Leveraging major cloud marketplaces for distribution simplifies procurement and deployment for enterprise IT departments, creating a new and efficient sales channel that complements direct sales.
Industry Challenges
- IT and OT Skills Gap:A persistent shortage of professionals with hybrid expertise in both information technology and operational technology hinders the effective implementation and maintenance of integrated MOM systems.
- Data Security Risks:Connecting factory floor systems to enterprise networks and the cloud through MOM software introduces new cybersecurity vulnerabilities that require specialized security protocols to mitigate.
- Standardization Gaps:The lack of universal communication standards between different generations of industrial machinery and software platforms complicates efforts to achieve seamless, plug-and-play interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manufacturing Operations Management (MOM) Software Market |
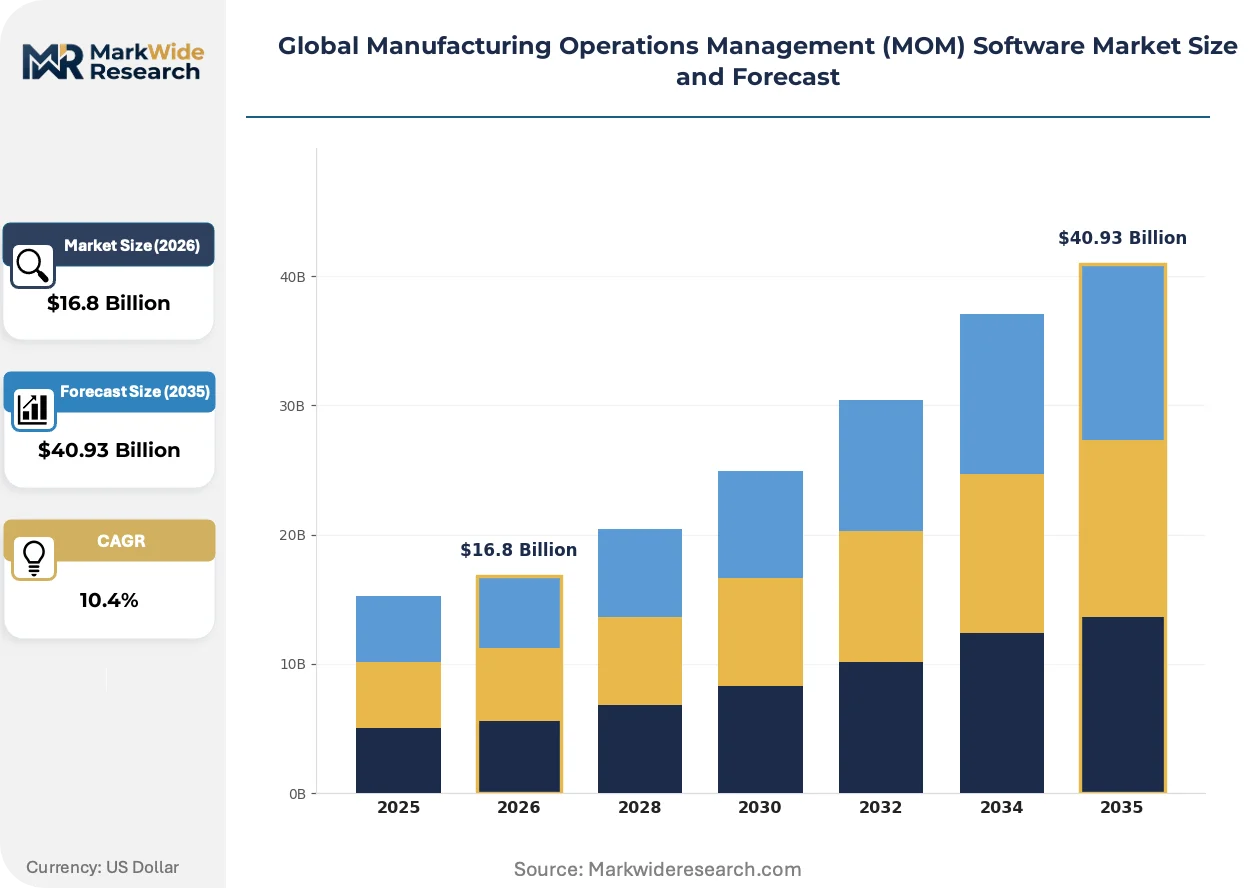
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $40.93 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing, Multi-Cloud Solution Offering: Production Scheduling, Quality Management, Inventory Control, Performance Analytics, Compliance Management Use Case: Discrete Manufacturing, Process Manufacturing, Continuous Manufacturing, Batch Production, Custom Manufacturing End User Industry: Electronics Assembly, Aerospace Components, Pharmaceutical Production, Food Processing, Consumer Durables |
| Companies Covered | Siemens, Rockwell Automation, Honeywell, SAP, Oracle, Dassault Systèmes, ABB, Microsoft, Fabrico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manufacturing Operations Management (MOM) Software Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from monolithic, on-premise systems toward modular, cloud-native platforms. This transition enables greater agility and facilitates the integration of advanced analytics directly into production workflows across global manufacturing networks.
Edge computing provides a critical function by processing machine-level data locally before sending it to a central cloud platform. Process manufacturing sectors, including food processing and chemicals, are adopting this model to enable immediate control actions on the production line. This architecture is hybridizing the deployment model, combining the low-latency benefits of on-premise processing with the analytical power and scalability of the cloud.
The European Union's Medical Device Regulation (MDR) establishes rigorous requirements for unique device identification (UDI) and electronic traceability throughout the product lifecycle. This regulation compels medical device manufacturers to implement or upgrade MOM systems with validated electronic device history record (eDHR) capabilities. Consequently, the European medtech industry is prioritizing platforms with proven compliance and validation modules to ensure uninterrupted market access.
Enterprise procurement behavior is pivoting from large, single-vendor perpetual license agreements toward more flexible, modular software subscriptions. This allows manufacturers to select and pay for specific functionalities, such as scheduling or quality management, on an as-needed basis. This trend is particularly pronounced in the electronics assembly industry, where production lines must rapidly adapt to frequent product changes and shifting consumer demand.
Global Manufacturing Operations Management (MOM) Software Market Segmentation
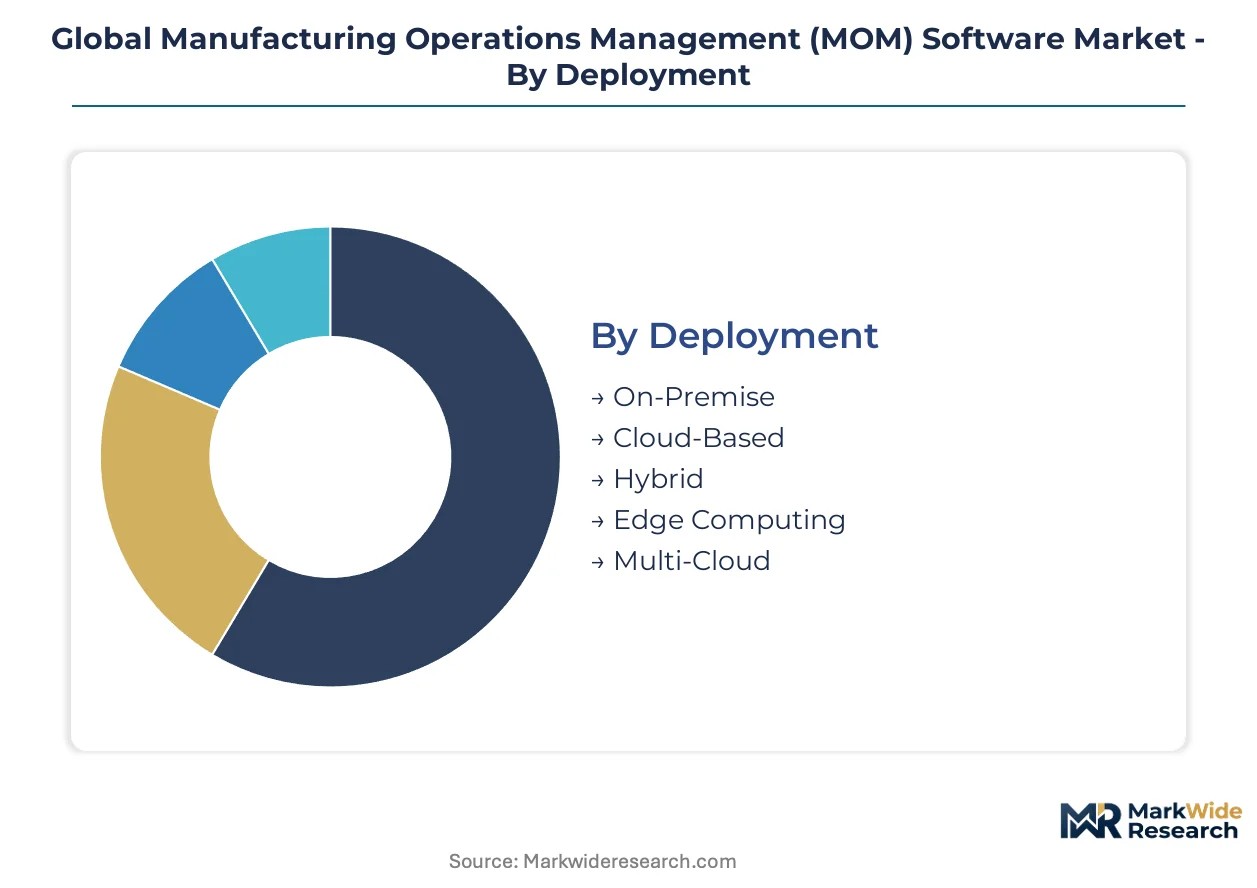
The segmentation of the Global Manufacturing Operations Management (MOM) Software Market illuminates how varied operational requirements and industry-specific demands shape technology adoption. Understanding these distinct segments helps manufacturers select solutions that precisely align with their production processes and regulatory landscapes. This granular view reveals critical areas of investment and innovation across the industrial sector.
Deployment:
The deployment models for MOM software span a spectrum of operational needs, from isolated factory floors to globally interconnected production networks.
- On-Premise:Traditional deployment where software and infrastructure reside on-site, offering maximum control and data sovereignty.
- Cloud-Based:Provides scalable, subscription-based access to MOM functionalities, eliminating significant upfront infrastructure investments for manufacturers. Its flexibility supports multi-site operations and facilitates rapid feature updates across global networks.
- Hybrid:Combines on-premise components for critical, low-latency factory operations with cloud services for data analytics and enterprise-level integration. This model balances real-time control with scalable data processing capabilities.
- Edge Computing:Processes machine-level data locally, enabling immediate control actions and reducing latency before sending aggregated data.
- Multi-Cloud:Utilizes services from multiple cloud providers, enhancing resilience and optimizing for specific regional compliance.
The dominant share belongs to Cloud-Based solutions, while Hybrid deployment is closing the gap fastest.
Solution Offering:
MOM software delivers a comprehensive functional scope, addressing critical aspects of production management from initial planning through execution and analysis.
- Production Scheduling:Optimizes manufacturing sequences and resource allocation to meet delivery targets and minimize bottlenecks.
- Quality Management:Monitors product quality throughout manufacturing, identifies defects, and implements corrective actions for standards.
- Inventory Control:Manages raw materials, work-in-progress, and finished goods, optimizing stock levels to prevent shortages or excess.
- Performance Analytics:Leverages real-time operational data to provide insights into production efficiency, asset utilization, and overall equipment effectiveness (OEE). This module supports data-driven decision-making for continuous process improvement.
- Compliance Management:Ensures adherence to industry regulations and quality standards, including electronic record-keeping and traceability requirements for sectors like pharmaceutical production. This module automates audit trails and documentation.
Performance Analytics capabilities are rapidly gaining traction, reflecting the industry's push for data-driven operational excellence.
Use Case:
MOM software caters to distinct production types, each requiring tailored functionalities to manage specific operational complexities and material flows.
- Discrete Manufacturing:Focuses on the production of individual, distinct items, often involving assembly lines and bill-of-materials management. This segment requires precise tracking of components and sub-assemblies.
- Process Manufacturing:Involves transforming raw materials through a series of chemical or physical processes to create bulk products, common in chemicals or food processing. This necessitates recipe management and batch control.
- Continuous Manufacturing:Characterized by uninterrupted production flows, often for high-volume, standardized products like refined oil.
- Batch Production:Produces goods in specific quantities or lots, allowing flexibility in product variations, common in pharmaceuticals.
- Custom Manufacturing:Caters to unique, one-off product designs, requiring flexible planning and detailed project management.
Process Manufacturing environments increasingly adopt MOM solutions to manage complex recipes and stringent quality parameters.
End User Industry:
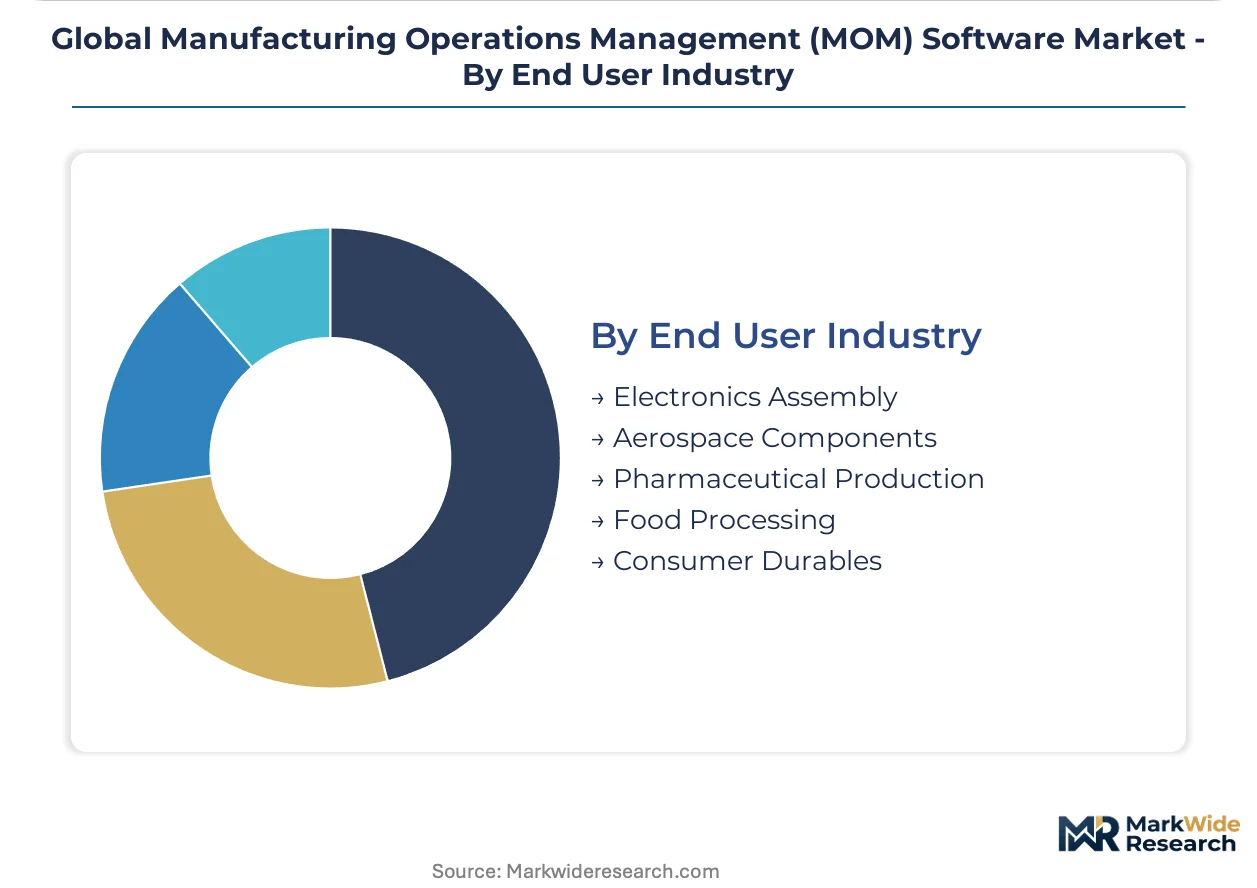
The end-user industries for MOM software vary significantly, driven by differing regulatory intensities and the complexity of their manufactured products.
- Electronics Assembly:Requires MOM platforms that can manage rapid product changes, high-volume production, and intricate supply chains. Solutions support precise component tracking and quality control for complex devices.
- Aerospace Components:Demands meticulous quality control and traceability for critical parts, driven by safety regulations.
- Pharmaceutical Production:Mandates stringent traceability and electronic record-keeping to comply with regulations like the US FDA's 21 CFR Part 11 and the EU's MDR. MOM solutions here ensure validated processes and audit readiness.
- Food Processing:Focuses on batch traceability, allergen management, and hygiene compliance for food safety standards.
- Consumer Durables:Benefits from MOM for optimizing high-volume production, managing variants, and improving supply chain responsiveness.
Pharmaceutical Production represents a significant and growing segment, propelled by non-negotiable regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National industrial strategies, particularly those promoting digital factory frameworks, significantly influence the adoption of Manufacturing Operations Management (MOM) software across various regions. These governmental initiatives often provide incentives and set standards that accelerate the integration of IT and OT systems on factory floors. Regulatory compliance also drives significant investment in MOM solutions, especially in highly controlled industries.
United States
Pharmaceutical production and aerospace components demand stringent traceability and quality control, driving MOM software adoption. The US FDA's 21 CFR Part 11 mandates validated electronic records, compelling manufacturers to upgrade their systems. Biopharmaceutical hubs in the Boston and San Francisco Bay Areas actively integrate MOM platforms to ensure data integrity and compliance.
Germany
German manufacturers in industrial equipment and automotive sectors are rapidly implementing MOM software for advanced manufacturing and Industry 4.0 initiatives. National strategies promote the adoption of digital factory frameworks, making MOM a foundational component. Automotive clusters in Bavaria and machinery manufacturers in North Rhine-Westphalia lead in deploying integrated MOM solutions.
China
Electronics assembly and high-volume manufacturing sectors in China require MOM solutions for efficient production scaling and quality management. Policies from the Ministry of Industry and Information Technology (MIIT) encourage smart manufacturing adoption. Electronics manufacturing hubs in Shenzhen and the Yangtze River Delta actively deploy MOM systems to optimize complex supply chains.
Japan
Japanese precision manufacturing and automotive industries prioritize MOM software for optimizing production lines and ensuring consistent quality. The Ministry of Economy, Trade and Industry (METI) supports smart factory initiatives to enhance industrial competitiveness. Automotive and robotics manufacturers in Aichi Prefecture utilize MOM for real-time monitoring and control.
India
India's pharmaceutical production and automotive sectors are increasingly adopting MOM software to meet rising quality standards and production targets. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing, stimulating MOM investment. Pharmaceutical manufacturing centers in Hyderabad and automotive clusters in Chennai are key areas for MOM implementation.
Global Manufacturing Operations Management (MOM) Software Market Key Industry Players
On the supply side, the industry is consolidated at the top tier with a broader fragmentation among specialized providers addressing niche requirements. Strategic archetypes include large enterprise resource planning (ERP) vendors, industrial automation giants, and specialized cloud-native MOM solution providers. Dominant competitive moves involve portfolio diversification, embedding MOM capabilities within broader digital factory frameworks, and forming strategic partnerships with cloud marketplaces and system integrators.
Large-scale industrial technology providers such as Siemens AG and Rockwell Automation Inc. exemplify comprehensive industrial automation and MOM integration. Siemens leverages its extensive industrial automation portfolio to embed MOM solutions within larger digital factory frameworks, offering end-to-end operational visibility. Rockwell Automation competes with its FactoryTalk suite, targeting complex process manufacturing environments with specialized control and information systems. SAP SE integrates its MOM capabilities directly with its core ERP systems, offering a unified data model for enterprise clients seeking seamless data flow between business and operational layers.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Honeywell |
| SAP |
| Oracle |
| Dassault Systèmes |
| ABB |
| Microsoft |
| Fabrico |
| Others |
Cost & Logistics Intelligence
Regulatory compliance complexity, particularly for validated systems, dictates pricing tier differentiation and influences the geographic concentration of specialized MOM software providers. This shapes the market's overall supply and demand dynamics.
Pricing Analysis
Certification level, specifically adherence to US FDA 21 CFR Part 11 and EU MDR, creates the primary pricing spread for MOM solutions. SaaS-tiered subscriptions dominate the market, with pricing differentiated by compliance modules and the depth of integration services. Customization for specific factory floor layouts also commands a premium. Pricing softness emerges in basic MOM functionalities for small and medium-sized enterprises due to a proliferation of entry-level offerings. Large enterprises in pharmaceutical production exhibit the least price sensitivity, prioritizing regulatory adherence and validated systems over cost.
Supply Chain Analysis
Intellectual property protection regimes, particularly for specialized industrial software, influence the geographic availability of advanced MOM solutions. Supply concentrates in Germany for industrial automation solutions and the US for software innovation, with India providing significant development talent. The MOM software supply chain relies on a skilled workforce of IT/OT engineers and robust cloud infrastructure services. Vendor lock-in presents a structural risk, given the complex integration required for these platforms. Distribution runs through direct-to-enterprise sales, cloud marketplaces, and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Manufacturing Operations Management (MOM) Software market represents a high-growth disruption, driven by the convergence of operational technology and IT. This integration, accelerated by Industry 4.0 initiatives, reshapes manufacturing processes.
For Market Incumbents:Insulate core market share by embedding MOM solutions deeper within existing digital factory frameworks. This counters the threat from agile cloud-native providers offering specialized modules. Leverage extensive industrial automation portfolios to offer end-to-end solutions, making switching costs prohibitive for clients. Invest in R&D for AI-powered analytics to maintain a technological edge and address the IT/OT skills gap.
For New Entrants and Emerging Players:Build out scalable, subscription-based cloud MOM solutions tailored for small and medium-sized enterprises. This targets the underpenetrated SME segment within discrete manufacturing. Focus on AI-powered analytics for predictive maintenance and prescriptive quality control, offering immediate value beyond basic data visualization. Leverage cloud marketplace channels for simplified procurement and rapid deployment, bypassing traditional direct sales cycles.
For Investors and Strategic Acquirers:The EU Medical Device Regulation (MDR) reshapes the acquisition landscape, emphasizing compliance capabilities. Over the next five to ten years, MOM software will remain a critical investment for manufacturing digitalization. Target niche cloud-native providers specializing in specific regulated sectors like pharmaceutical production or aerospace components, particularly those with validated electronic record-keeping modules. Consolidation of smaller, specialized players by larger industrial automation firms serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cloud Marketplace Presence | Simplifies procurement for enterprise IT departments, expanding reach beyond traditional sales channels. |
| Develop AI/ML Predictive Modules | Offers advanced analytics for prescriptive quality control, enhancing operational efficiency for process manufacturing. |
| Acquire Compliance Software Specialists | Strengthens offerings for regulated sectors, particularly pharmaceutical production requiring FDA 21 CFR Part 11. |
| Partner with System Integrators | Accelerates complex MOM system deployments, crucial for multi-site operations and legacy system integration. |
| Focus on SaaS for SMEs | Addresses the largely underpenetrated small and medium-sized enterprise segment with flexible, scalable solutions. |
Research Approach
A standing panel of manufacturing operations managers, IT directors, and regulatory compliance officers provided ongoing calibration. This primary insight was validated against extensive secondary research, including industry association reports, patent filings, and government manufacturing statistics. The analysis employed both bottom-up and top-down triangulation to ensure data robustness. System integrators also contributed valuable perspectives on market dynamics.
Scenario-bracketing defined the forecast framework, considering various economic and technological trajectories across the analysis window. The analytical model segmented the market by deployment, solution offering, use case, and end user industry, alongside regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers. Key forecast inputs included industrial investment cycles and regulatory enforcement trends.
Sensitivities concentrate around geopolitical shifts and major technological breakthroughs impacting industrial digitalization. Forecasts reflect a baseline of current market assumptions and known project pipelines. Material shifts in regulatory policy or global economic stability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Camera Tracking Software Market
Software & Services
User Retention Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Course Authoring Software Market
Software & Services
Construction Simulation Software Market
Software & Services
Sales Platforms Software Market
Software & Services
API Testing Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Interior Design Software Market
Software & Services
Performance Management Software Market
Software & Services
Landscaping Engineering Software Market