
 Lifecycle Management Software Market | 2026-2036
Lifecycle Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lifecycle Management Software Market Insights
EU AI Act compliance is recalibrating the cost-of-entry calculus for lifecycle management software vendors serving regulated industries. Siemens AG leverages deep integration between its Teamcenter platform and digital twin infrastructure to anchor industrial automation workflows. Dassault Systèmes SE sustains competitive differentiation through 3DEXPERIENCE's model-based systems engineering capabilities across aerospace and medical device verticals. PTC Inc. specializes in closed-loop quality management, extending its Windchill footprint into FDA-regulated traceability requirements.
Lifecycle management software coordinates product data, engineering processes, and compliance documentation across the complete value chain from concept through retirement, typically operating through centralized repositories with version control, workflow automation, and multi-CAD interoperability at its technical core. Enterprise solutions dominate current revenue pools given their entrenched position in automotive and heavy machinery sectors, while cloud-based platforms represent the fastest-expanding segment as manufacturers migrate from capital-intensive on-premise installations to subscription models with faster implementation cycles. Integrated tools capture concentrated margin pools where ALM-PLM convergence serves safety-critical applications in medical technology and autonomous systems development.
FDA 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements shape product development and compliance management application demand, with both frameworks mandating traceable design history files that lifecycle platforms automate. ISO 26262 functional safety standards and IEC 62304 medical device software protocols further constrain architecture choices, forcing vendors to embed risk management and verification workflows natively. Stakeholders must monitor how emerging cybersecurity certification schemes under EU Cyber Resilience Act timelines reshape validation requirements for connected product ecosystems.
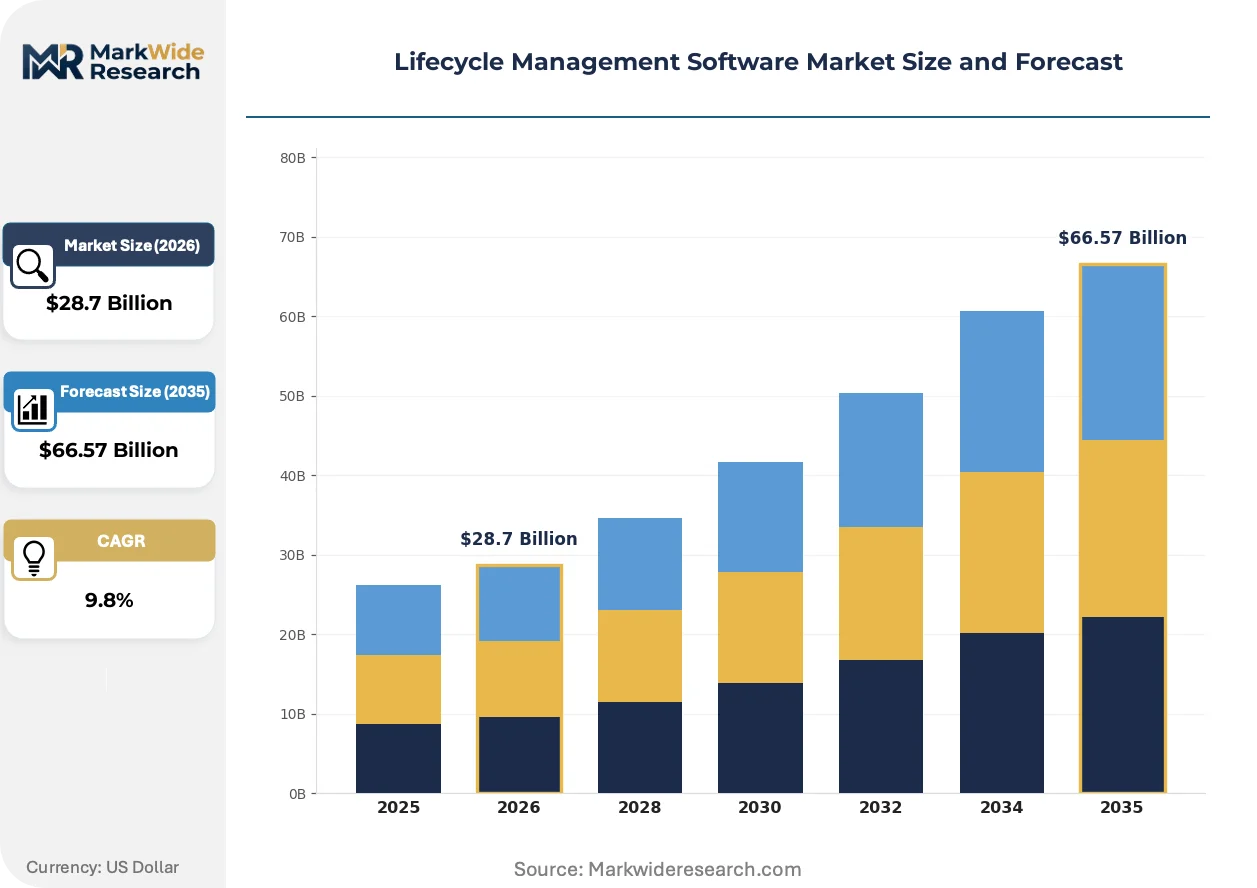
Market Dynamics
Cloud migration mandates from EU data residency rules are compressing vendor architecture roadmaps and forcing re-platforming investments across the installed base. Medical device manufacturers now require traceable design history files that span FDA submission workflows through post-market surveillance, creating structural pull for integrated ALM-PLM suites.
Growth Catalysts
- FDA 21 CFR Part 820:Quality system regulations mandate automated design controls and document traceability that lifecycle platforms embed natively. Medical device developers purchase integrated suites to compress submission preparation cycles.
- Automotive functional safety:ISO 26262 standards for autonomous systems development require closed-loop verification workflows. German OEMs anchor regional demand for model-based systems engineering capabilities.
- Cloud architecture migration:Subscription models with faster implementation cycles displace capital-intensive on-premise installations. Manufacturers prioritize operational expenditure flexibility over ownership.
Market Restraints
- Data sovereignty compliance costs:EU GDPR and emerging national data localization laws force redundant infrastructure deployment. Vendors absorb margin compression from multi-region hosting requirements.
- Legacy system entrenchment:Heavy machinery and automotive sectors operate decades-old PLM installations with deep customization. Switching costs and retraining timelines extend replacement cycles.
- Specialized talent scarcity:Model-based systems engineering and regulatory affairs expertise concentrates in aerospace clusters. Generalist IT consultancies lack domain depth for safety-critical implementations.
Strategic Opportunities
- EU Cyber Resilience Act timelines:Emerging cybersecurity certification schemes for connected products create validation service adjacencies. Vendors bundle compliance automation with core platform licenses.
- ALM-PLM convergence:Software-defined product architectures in medical technology and industrial automation demand unified requirements management. Integrated tools capture concentrated margin pools.
- Digital twin infrastructure:Industrial equipment makers in Germany seek lifecycle platforms that feed operational data back into design iterations. Real-time performance telemetry closes product improvement loops.
Industry Challenges
- Multi-CAD interoperability:Engineering teams deploy heterogeneous mechanical and electrical design tools that resist seamless data exchange. Integration middleware adds implementation complexity and latency.
- Verification workflow standardization:IEC 62304 medical device software protocols and ISO 26262 functional safety standards impose conflicting documentation formats. Platform vendors maintain multiple compliance templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifecycle Management Software Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $66.57 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Solutions, Cloud-based Platforms, On-premise Software, Integrated Tools End User: Manufacturers, Healthcare Providers, Retailers, Service Providers Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Application: Product Development, Compliance Management, Project Management, Asset Tracking |
| Companies Covered | Siemens AG, Dassault Systèmes SE, Autodesk Inc., PTC Inc., SAP SE, Oracle Corporation, IBM Corporation, Synopsys Inc., Cadence Design Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifecycle Management Software Market Trends and Innovations
Artificial intelligence capabilities are embedding into lifecycle platforms to automate requirements traceability and risk assessment workflows that previously demanded manual engineering review. Regulatory pressure from the EU AI Act and FDA software guidance is accelerating vendor investment in explainable automation.
Generative AI is automating the synthesis of design history files from fragmented engineering data sources. Medical device developers in the United States adopt these tools to compress FDA pre-submission documentation preparation. The technology is automating cross-referencing between requirements, verification protocols, and post-market surveillance reports that previously required dedicated quality assurance staff.
The EU AI Act's risk classification framework for software as a medical device imposes conformity assessment obligations on lifecycle management vendors themselves. Platform providers must demonstrate audit trail integrity and algorithmic transparency to serve high-risk application categories. German medical technology manufacturers are prioritizing vendors with pre-validated quality system modules that map directly to notified body expectations.
Buyer preference is consolidating around subscription pricing with embedded compliance automation rather than perpetual licenses with separate professional services. Automotive OEMs in Germany negotiate enterprise agreements that bundle regulatory template libraries with core platform access. This procurement pattern compresses vendor revenue recognition timelines while expanding recurring revenue pools.
Lifecycle Management Software Market Segmentation
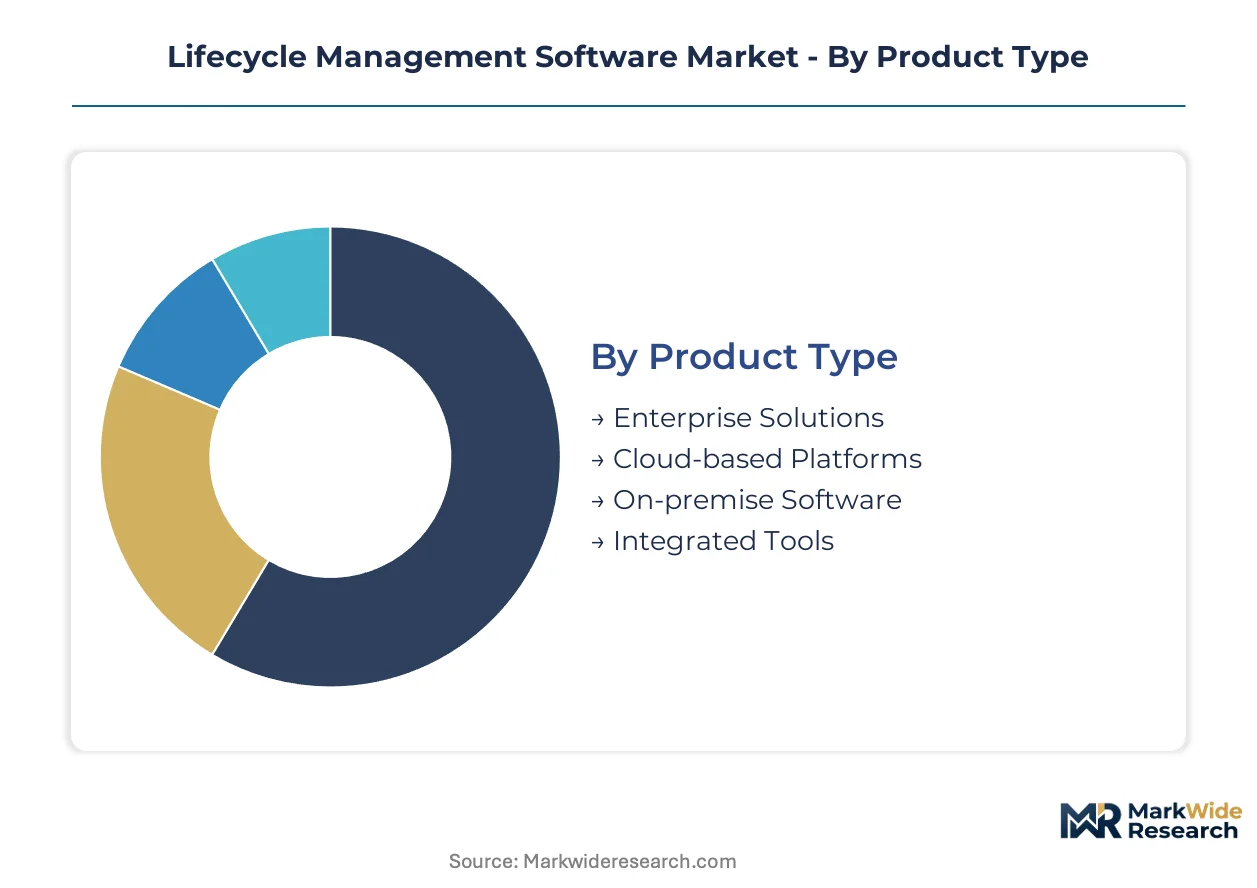
Lifecycle management software segmentation reveals how vendor architecture choices align with customer risk tolerance, data sovereignty requirements, and integration complexity. Deployment models and application scope determine pricing structures, implementation timelines, and recurring revenue durability across regulated industries.
Product Type:
Customization depth varies sharply across this category, from heavily configured enterprise installations to standardized cloud subscriptions with limited tailoring.
- Enterprise Solutions:Comprehensive on-premise or hosted platforms with deep CAD integration, workflow automation, and multi-site collaboration. Automotive OEMs in Germany and heavy machinery manufacturers in Japan anchor demand for these capital-intensive installations with decade-long replacement cycles.
- Cloud-based Platforms:Subscription-delivered software with API-first architecture and rapid deployment templates. Medical device developers in the United States prioritize these for FDA submission workflow automation without infrastructure ownership burdens.
- On-premise Software:Perpetually licensed deployments within customer-controlled data centers. Defense contractors and classified manufacturing facilities in France require these for air-gapped security compliance.
- Integrated Tools:Purpose-built modules combining ALM-PLM functionality for safety-critical applications. These capture premium pricing in autonomous systems development where ISO 26262 traceability is mandatory.
Leading the category by volume: Enterprise Solutions. Expanding most quickly: Cloud-based Platforms.
End User:
Procurement authority and compliance burden shape how each user type evaluates lifecycle platform investments.
- Manufacturers:Industrial equipment makers, automotive suppliers, and electronics producers with complex BOM management needs. German automotive OEMs drive regional demand for digital twin integration and real-time performance feedback loops.
- Healthcare Providers:Hospitals and health systems managing medical device fleets and clinical asset lifecycle. These organizations prioritize FDA 21 CFR Part 820 compliance modules for post-market surveillance documentation.
- Retailers:Consumer goods companies coordinating private-label product development across distributed supplier networks. Fast-fashion retailers in Spain use these platforms to compress seasonal design-to-shelf timelines.
- Service Providers:Engineering consultancies and systems integrators delivering lifecycle management as a managed service. These intermediaries aggregate demand from mid-market manufacturers lacking in-house implementation expertise.
Dominant by procurement scale: Manufacturers. Fastest adoption acceleration: Healthcare Providers.
Deployment:
Data residency mandates and cybersecurity postures fragment deployment preferences across regulated verticals.
- Public Cloud:Multi-tenant infrastructure operated by hyperscale providers with shared security models. Small and mid-market manufacturers in the United States favor these for operational expenditure flexibility and rapid scaling.
- Private Cloud:Single-tenant environments with dedicated infrastructure and custom security configurations. EU MDR compliance requirements push medical technology firms toward these for GDPR-aligned data sovereignty.
- Hybrid Cloud:Architectures splitting sensitive data on-premise with compute-intensive workloads in cloud. Aerospace manufacturers in France and Germany deploy these to protect ITAR-controlled designs while leveraging elastic simulation capacity.
- On-premises:Fully customer-managed infrastructure with no external data transmission. Critical infrastructure operators in Japan and defense supply chain participants mandate these for national security compliance.
Widest installed base: Public Cloud. Steepest expansion trajectory: Hybrid Cloud.
Application:
Functional scope determines integration complexity and the breadth of stakeholder workflows a platform must accommodate.
- Product Development:Requirements management, design collaboration, and engineering change control from concept through prototype. Medical device developers use these capabilities to automate design history file generation for FDA pre-submission packages.
- Compliance Management:Regulatory documentation, audit trail maintenance, and conformity assessment workflow automation. EU AI Act risk classification obligations are accelerating adoption among software-as-a-medical-device manufacturers.
- Project Management:Resource allocation, milestone tracking, and cross-functional coordination for product launches. Consumer electronics producers in South Korea integrate these with PLM data to synchronize hardware and software release schedules.
- Asset Tracking:Post-deployment monitoring, maintenance scheduling, and end-of-life planning for physical equipment. Industrial automation vendors in Germany feed operational telemetry back into design iterations through these capabilities.
Highest revenue concentration: Product Development. Gaining share fastest: Compliance Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Baden-Württemberg region concentrate automotive OEM procurement authority for integrated PLM-ALM suites. These tax-advantaged manufacturing clusters anchor the largest European deployment base for lifecycle management platforms serving safety-critical applications.
Germany
Automotive OEMs in Stuttgart and Munich drive demand for ISO 26262-compliant verification workflows. The KBA enforces functional safety standards that mandate closed-loop traceability for autonomous systems development. Bavarian industrial equipment makers feed operational telemetry from deployed assets back into design iterations through digital twin infrastructure.
United States
Medical device developers in Massachusetts and Minnesota prioritize FDA 21 CFR Part 820 automation for pre-submission documentation. The FDA's software guidance accelerates adoption of generative AI tools that synthesize design history files from fragmented engineering data. Greater Boston clusters concentrate software-as-a-medical-device manufacturers requiring EU AI Act-aligned audit trail integrity.
France
Aerospace manufacturers in Toulouse and Paris deploy hybrid cloud architectures to protect ITAR-controlled designs while leveraging elastic simulation capacity. ANSM conformity assessment obligations for high-risk medical devices push vendors toward pre-validated quality system modules. Île-de-France hosts defense contractors mandating air-gapped on-premise installations for classified manufacturing.
Japan
Industrial automation vendors in Nagoya and Osaka seek lifecycle platforms that coordinate multi-CAD interoperability across mechanical and electrical design teams. METI standards for connected product ecosystems reshape validation requirements for post-market surveillance. Chubu region heavy machinery manufacturers operate decades-old PLM installations with deep customization that extends replacement cycles.
China
Electronics producers in Shenzhen and Shanghai integrate compliance management modules to navigate GB standards and emerging cybersecurity certification schemes. MIIT cloud migration mandates compress vendor architecture roadmaps for data residency alignment. Yangtze River Delta manufacturing bases represent expanding demand for subscription pricing with embedded regulatory template libraries.
Lifecycle Management Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise software vendors with broad industrial automation portfolios anchor high-value contracts through platform integration advantages. Three strategic archetypes dominate: engineering-centric specialists with deep CAD interoperability, cloud-native challengers with API-first architectures, and diversified conglomerates bundling lifecycle tools within enterprise suites. Competitive dynamics center on M&A activity consolidating ALM-PLM convergence capabilities and strategic partnerships embedding compliance automation within core platform licenses.
Among Germany-based industrial software providers, Siemens AG exemplifies the diversified conglomerate archetype through deep integration between lifecycle platforms and digital twin infrastructure. Dassault Systèmes SE occupies a position representing engineering-centric specialists with model-based systems engineering capabilities. PTC Inc. anchors the compliance-focused tier with specialized closed-loop quality management for FDA-regulated traceability requirements.
| Leading Market Players |
|---|
| Siemens AG |
| Dassault Systèmes SE |
| Autodesk Inc. |
| PTC Inc. |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Synopsys Inc. |
| Cadence Design Systems |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up cloud-native specialists have consolidated fragmented implementation services, tightening pricing discipline while compressing margin pools for legacy on-premise vendors. Subscription pricing models now dominate procurement patterns, with buyers trading capital expenditure flexibility for faster deployment cycles and embedded compliance automation.
Pricing Analysis
Short lead-time deployments command premium pricing tiers, while extended implementation timelines attract standard-rate subscriptions. Pricing stratifies across enterprise, professional, and essential tiers differentiated by customization depth and regulatory template library access. Cost compression in essential tiers is intensifying because hyperscale cloud providers bundle competing workflow tools at marginal cost. Mid-market manufacturers exhibit highest price sensitivity, whereas FDA-regulated medical device developers prioritize audit trail integrity over subscription cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for professional services delivery and compliance template localization. Platform development draws from specialized engineering talent pools in India and Eastern Europe, with regulatory affairs expertise concentrated in Boston and Stuttgart clusters. Single-source vulnerability persists for ISO 26262-certified verification modules, where qualified assessor capacity limits scaling. Distribution runs through direct enterprise sales with embedded implementation partners, supplemented by hyperscaler marketplaces for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with platform vendors pursuing downstream control over compliance validation services to capture recurring revenue from regulated customers.
For Market Incumbents: Lock in switching costs by deepening digital twin integration with operational technology stacks. Acquire specialized ALM-PLM convergence boutiques before cloud-native challengers consolidate them. Siemens AG and Dassault Systèmes SE face margin pressure from API-first competitors unbundling workflow automation.
For New Entrants and Emerging Players: Enter via post-market surveillance modules for mid-tier medical device manufacturers underserved by enterprise suites. White-space concentrates in EU MDR technical documentation automation for notified body submission preparation. Partner with regional systems integrators in Germany lacking native compliance expertise.
For Investors and Strategic Acquirers: EU AI Act conformity assessment obligations hitting software-as-a-medical-device vendors is the leading indicator that pre-validated quality system modules will command acquisition premiums. Target specialists with embedded FDA 21 CFR Part 820 templates and established notified body relationships. Watch for hyperscaler marketplace traction as the inflection signal for platform commoditization risk.
| Strategic Initiative | Industry Significance |
|---|---|
| ALM-PLM Convergence Acquisition | Consolidates traceability workflows for ISO 26262 autonomous systems development in Stuttgart clusters. |
| EU Cyber Resilience Act Pre-Certification | Positions vendors for connected product validation mandates before ANSM conformity deadlines. |
| Digital Twin Infrastructure Partnership | Feeds operational telemetry from Bavarian industrial equipment into design iteration loops. |
| Hyperscaler Marketplace Distribution | Expands mid-market reach through AWS and Azure procurement channels with self-service templates. |
| Generative AI Documentation Automation | Compresses FDA pre-submission preparation cycles for Massachusetts medical device developers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across platform engineering directors, regulatory affairs leads at medical device manufacturers, healthcare procurement officers, and automotive OEM systems engineers. FDA 510(k) submission databases, EU MDR notified body audit reports, and hyperscaler capex disclosures supplemented demand-side validation. Bottom-up deployment counts reconciled against top-down vendor revenue segmentation.
Data-stream reconciliation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs derived from segment-level growth rate convergence over the projection horizon. Forecast inputs incorporated cloud migration velocity indices from EU data residency compliance timelines and ISO 26262 certification pipeline data from KBA regulatory disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged hyperscaler price competition. Outputs reflect documented assumptions regarding regulatory implementation timelines and enterprise replacement cycle elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Virtual Fitting Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
PAC Programming Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Fitness App Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Subscription Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Lead Mining Software Market
Software & Services
Europe Printing Software Market
Software & Services
Global Personalisation Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market