
 Global Anchors and Grouts Market | 2026-2036
Global Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anchors and Grouts Market Foresight
European specialty chemical producers is pivoting toward low-carbon grout formulations to align with EU Green Deal mandates. Sika AG leverages its Swiss manufacturing base to sustain R&D intensity in epoxy grout chemistry. MBCC Group GmbH anchors its competitive position through vertical integration into cementitious raw materials. BASF SE differentiates via controlled expansion technology for infrastructure-grade mechanical anchors.
Anchors and grouts encompass load-transfer devices and gap-filling compounds engineered to bond structural elements to substrates, with epoxy grouts typically achieving compressive strengths exceeding 80 MPa and chemical anchors relying on resin-cartridge injection systems for cracked-concrete applications. Cementitious grouts dominate volume due to cost efficiency in standard construction, while epoxy grouts command premium positioning in power generation and marine infrastructure where vibration resistance and chemical exposure define performance thresholds. Non-shrink technology leads growth in bridge reinforcement applications, as state agencies specify zero-shrinkage guarantees for post-tensioned cable anchorage zones.
REACH compliance in Europe, EPA emissions guidelines in the United States, and BIS certification requirements in India collectively elevate product testing costs and restrict market entry for uncertified suppliers. The EU AI Act and emerging digital-product-passport rules will soon mandate supply-chain traceability for construction chemicals, reshaping procurement qualification protocols. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and avoid stranded inventory in cross-border projects.
Market Dynamics
EU Green Deal mandates on embodied carbon are forcing construction chemical suppliers to reformulate cementitious grouts while maintaining load-bearing performance, compressing R&D timelines and raw-material sourcing flexibility across the supply base.
Growth Catalysts
- Metro Rail Expansion:India's urban transit buildout is accelerating specification of high-performance chemical anchors for tunnel lining and platform construction in seismic zones.
- REACH Compliance:European chemical registration requirements are elevating product testing protocols, advantaging incumbent formulators with established certification portfolios.
- Non-Shrink Technology:Zero-shrinkage guarantees for post-tensioned bridge anchorage zones are displacing conventional grout specifications in state infrastructure procurement.
Market Restraints
- Epoxy Resin Volatility:Petrochemical feedstock price swings compress margin stability for specialty grout formulators serving marine and power generation end-uses.
- Supply Concentration:Cementitious raw-material sourcing clusters in select South Asian and Middle Eastern production zones expose buyers to logistics disruption risk.
- Cracked-Concrete Limitations:Mechanical anchor pull-out performance degrades in compromised substrate conditions, restricting specification in aging infrastructure rehabilitation.
Strategic Opportunities
- Coastal Port Modernization:India's maritime infrastructure upgrades are creating specification windows for corrosion-resistant chemical anchoring systems in salt-exposure environments.
- Digital Product Passports:EU AI Act supply-chain traceability mandates will reward early adopters of blockchain-verified formulation documentation in cross-border project bidding.
- Carbon-Capture Formulations:Low-carbon cementitious chemistry converging with supplementary cementitious material substitution is opening premium positioning in green building certification pathways.
Industry Challenges
- Formulation Chemistry Expertise:Scarcity of polymer chemists with cracked-concrete resin-system experience constrains product development velocity for mid-tier suppliers.
- Multi-Jurisdiction Certification:Divergent BIS, EPA, and REACH testing timelines extend product launch cycles and strand inventory in regional warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anchors and Grouts Market |
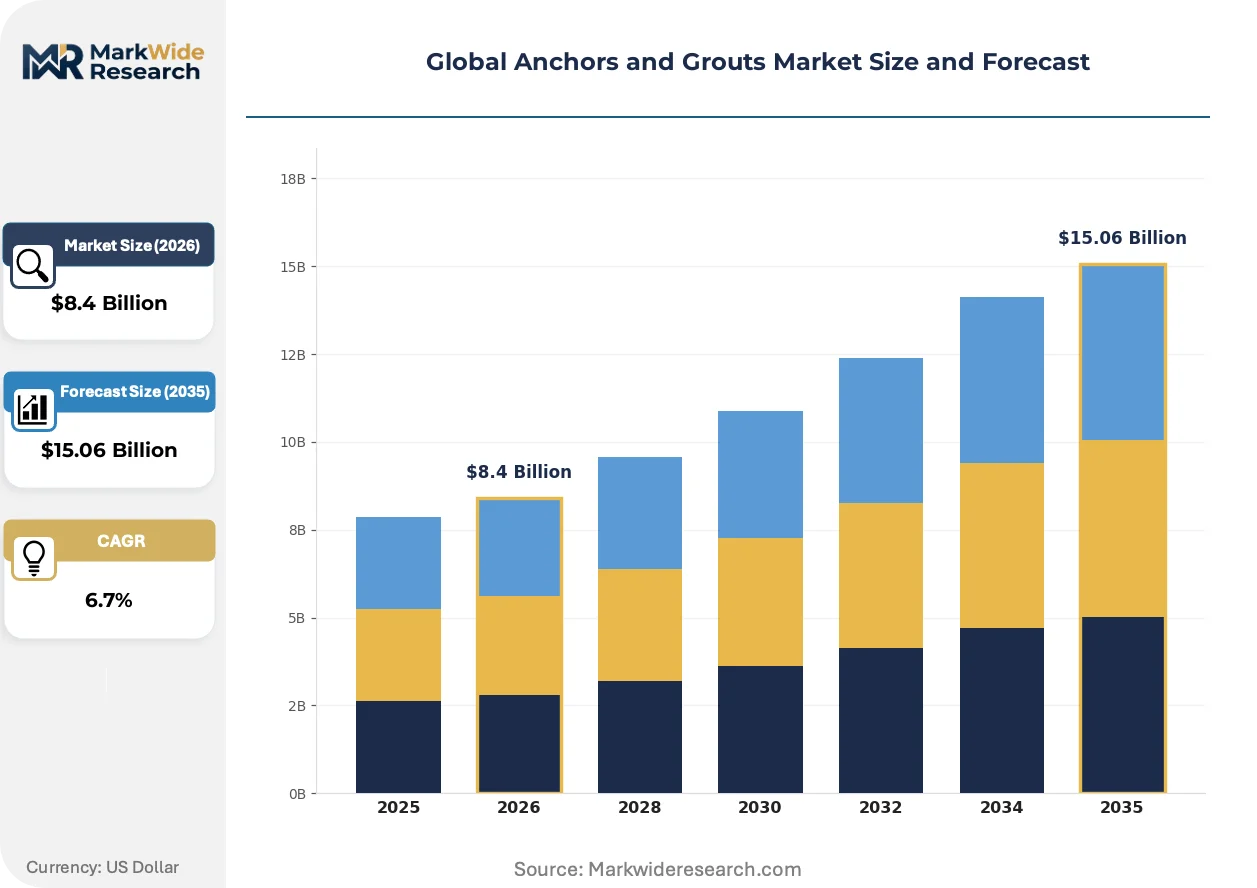
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Cementitious Grouts, Epoxy Grouts, Polyester Grouts Technology: Injection, Expansion, Underwater, Non-Shrink, Microfine Application: Construction, Mining, Tunneling, Marine Infrastructure, Bridge Reinforcement End User Industry: Industrial Manufacturing, Infrastructure Development, Oil & Gas Platforms, Power Generation, Water Treatment Plants |
| Companies Covered | MAPEI S.p.A., MBCC Group GmbH, Sika AG, W. R. Grace & Co., RPM International Inc., BASF SE, Fosroc International, Saint-Gobain Weber, Hilti AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anchors and Grouts Market Shifts & Advancements
Formulation chemistry and procurement protocols are undergoing parallel transformation as sustainability mandates and digital traceability requirements reshape competitive positioning across construction chemical supply chains.
Hybrid epoxy-cementitious grout systems are electrifying specification standards for heavy machinery baseplates in power generation facilities. Plant engineering contractors in Germany and Japan are adopting these systems for vibration-dampening performance. The technology is compressing traditional pure-cementitious volume in premium infrastructure segments while commanding formulation patent premiums.
EU Green Deal embodied-carbon thresholds are mandating environmental product declarations for construction chemicals entering public procurement. ECHA registration dossiers now require lifecycle assessment data that many import-dependent suppliers cannot furnish. Bridge and tunnel agencies in France and the Netherlands are rejecting uncertified grout bids, redirecting volume toward integrated European manufacturers.
Engineering-procurement-construction firms are consolidating anchor and grout purchasing through centralized technical qualification portals. Tier-one contractors in India and Saudi Arabia are displacing fragmented local distributor relationships with direct manufacturer framework agreements. This concentration is most visible in metro rail and airport terminal projects where single-source accountability reduces interface risk.
Global Anchors and Grouts Market Segmentation
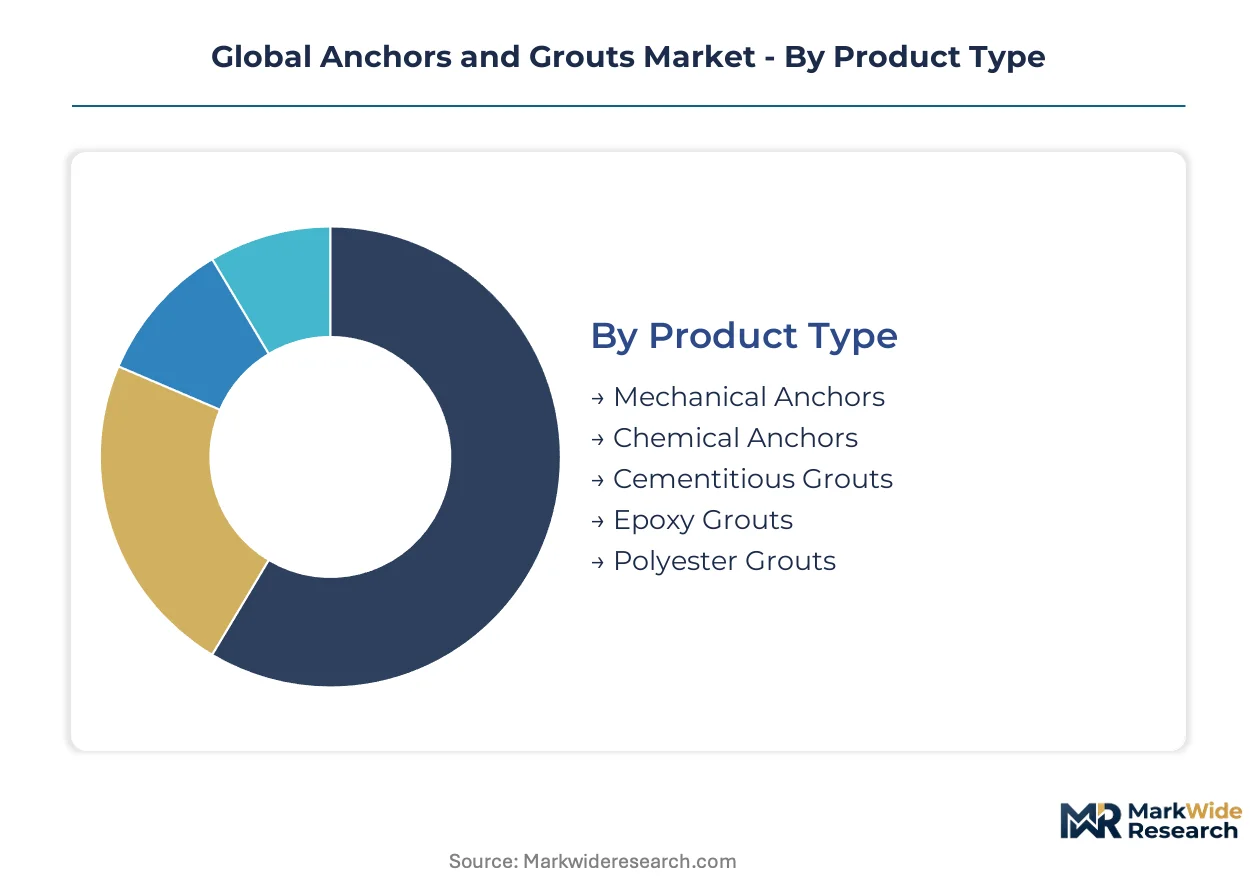
Segmentation in anchors and grouts reveals how capital intensity and technical certification requirements stratify competitive access. Product type and technology categories demand specialized manufacturing assets, while application and end-user segments dictate formulation complexity and compliance burdens.
Product Type:
Capital intensity peaks in resin-based systems requiring controlled-environment polymerization and precision dosing equipment, while cementitious formulations leverage lower fixed-cost batching infrastructure.
- Chemical Anchors:These resin-cartridge systems bond steel elements into cracked concrete through epoxy, vinyl ester, or hybrid polymer chemistry. Metro rail agencies in India specify these for seismic-zone tunnel linings where mechanical expansion anchors risk substrate fracture. REACH dossier requirements for European public procurement elevate testing costs and compress margins for uncertified entrants.
- Epoxy Grouts:High-performance gap-filling compounds achieve compressive strengths exceeding 80 MPa with superior vibration damping and chemical resistance. Power generation facilities in Germany and Japan adopt these for heavy machinery baseplates where precision alignment tolerances are non-negotiable. Petrochemical feedstock volatility compresses margin stability for formulators serving marine and industrial end-uses.
- Mechanical Anchors:Expansion and undercut designs transfer load through friction and mechanical interlock in uncracked concrete.
- Cementitious Grouts:Portland cement-based systems dominate volume through cost efficiency in standard construction applications.
- Polyester Grouts:Rapid-cure formulations serve repair and maintenance windows in transportation infrastructure.
Most installed capacity flows through Cementitious Grouts. Expansion is steepest in Chemical Anchors.
Technology:
Technology selection tracks substrate condition severity and environmental exposure, with premium systems commanding patent-protected formulation premiums.
- Non-Shrink:Zero-shrinkage chemistry guarantees dimensional stability in post-tensioned bridge anchorage zones where cable lock-off precision determines structural integrity. State transportation agencies in France and the Netherlands now mandate these specifications, displacing conventional grout bids from uncertified suppliers. ECHA lifecycle assessment requirements for EU public procurement reward integrated manufacturers with in-house EPD capabilities.
- Injection:Resin-cartridge and pump-injection systems enable deep embedment in cracked concrete and hollow masonry. Tunneling contractors in India's Himalayan rail projects specify these for rock bolt anchoring in variable geology. BIS certification timelines extend product launch cycles and strand inventory in regional warehouses.
- Expansion:Mechanical interlock technology serves standard construction in uncracked substrates with rapid installation cycles.
- Underwater:Specialized anti-washout formulations maintain cohesion in tidal and submerged conditions for port and marine applications.
- Microfine:Ultra-low particle size grouts penetrate hairline cracks and porous substrates in heritage structure rehabilitation.
Non-Shrink technology captures the dominant specification share in bridge reinforcement. Microfine systems are gaining share fastest in heritage and precision infrastructure.
Application:
Application segments diverge by performance threshold severity and regulatory inspection intensity, with transportation infrastructure imposing the most demanding qualification protocols.
- Bridge Reinforcement:Post-tensioned cable systems and bearing replacement demand zero-shrinkage guarantees and fatigue-resistant anchorage. EU Green Deal embodied-carbon thresholds now mandate environmental product declarations, redirecting volume toward low-carbon cementitious formulations from integrated European manufacturers. ECHA registration dossiers exclude import-dependent suppliers lacking lifecycle assessment data.
- Marine Infrastructure:Salt-exposure environments specify corrosion-resistant chemical anchoring systems with stainless steel or duplex hardware. Coastal port modernization in India creates specification windows for hybrid epoxy-cementitious systems combining vibration damping with chloride resistance. Petrochemical resin price swings compress margin stability for specialty formulators.
- Construction:General building applications span structural connections, facade support, and equipment anchoring with standard performance requirements.
- Mining:Rock bolt and cable bolt systems secure underground excavations in high-stress geologies with rapid installation demands.
- Tunneling:Segment bolting and ground support applications combine injection anchors with shotcrete in variable ground conditions.
Construction absorbs the largest volume share. Marine Infrastructure is climbing the fastest on coastal infrastructure investment.
End User Industry:
End-user concentration determines procurement centralization and technical qualification intensity, with energy and water infrastructure imposing the most stringent vendor approval processes.
- Infrastructure Development:Metro rail, airport, and highway agencies consolidate purchasing through centralized technical qualification portals. Engineering-procurement-construction firms in India and Saudi Arabia displace fragmented distributor relationships with direct manufacturer framework agreements. EU AI Act supply-chain traceability mandates will soon reward early adopters of blockchain-verified formulation documentation.
- Power Generation:Turbine and generator baseplate installations demand vibration-dampening epoxy grouts with precision alignment tolerances. Plant engineering contractors in Germany specify hybrid epoxy-cementitious systems for combined-cycle gas turbine installations. REACH compliance elevates product testing protocols, advantaging incumbent formulators with established certification portfolios.
- Industrial Manufacturing:Machinery installation and heavy equipment anchoring span standard to premium performance tiers.
- Oil & Gas Platforms:Offshore structures specify corrosion-resistant systems with fire-resistant ratings and helicopter landing load capacity.
- Water Treatment Plants:Chemical-resistant anchoring and grouting for process equipment in aggressive effluent environments.
Infrastructure Development channels the majority of specification volume. Power Generation is expanding most quickly on energy transition capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting cementitious grout production toward jurisdictions with lower embodied-carbon compliance costs, while premium epoxy formulation capacity clusters near European and Japanese demand centers where REACH and METI standards elevate technical barriers.
United States
Infrastructure investment from the Bipartisan Infrastructure Law drives chemical anchor specification for bridge seismic retrofits and highway expansion. EPA emissions guidelines tighten manufacturing compliance burdens, advantaging domestic formulators with established testing protocols. Gulf Coast petrochemical corridors supply resin feedstocks to specialty grout producers serving offshore platform and power generation markets.
Germany
Power plant engineering contractors specify hybrid epoxy-cementitious systems for turbine baseplate installations requiring vibration damping. EU Green Deal embodied-carbon mandates enforce environmental product declarations, excluding import-dependent suppliers lacking lifecycle assessment data. The Rhine-Ruhr industrial cluster hosts integrated construction chemical manufacturing with captive cementitious raw material processing.
India
Metro rail expansion in Mumbai, Delhi, and Bengaluru accelerates high-performance chemical anchor procurement for tunnel lining and platform construction in seismic zones. BIS certification requirements extend product launch timelines and strand inventory in regional warehouses. Coastal port modernization at Mundra and Visakhapatnam creates specification windows for corrosion-resistant anchoring systems in salt-exposure environments.
Japan
Nuclear restart programs and LNG import terminal construction drive precision epoxy grout demand for machinery alignment applications. METI standards enforce rigorous quality certification for construction chemicals in public infrastructure. The Chubu/Nagoya industrial corridor concentrates manufacturing of vibration-dampening grout systems for heavy machinery installation.
Saudi Arabia
NEOM and Red Sea coastal development projects specify chemical anchoring for marine infrastructure in high-chloride environments. The Saudi Standards, Metrology and Quality Organization (SASO) implements technical regulations converging with Gulf Cooperation Council harmonization. Eastern Province industrial cities host formulation facilities serving pan-Gulf construction demand.
Global Anchors and Grouts Market Competitive Landscape
European integrated chemical producers anchor the premium formulation tier; Asian cementitious specialists hold volume positions through cost-efficient batching infrastructure. The market structure stratifies across three tiers: multinational construction chemical conglomerates with full certification portfolios, regional cementitious formulators serving standard construction, and niche resin-system specialists. Competitive moves concentrate on backward integration into cementitious raw materials and direct framework agreements with engineering-procurement-construction firms displacing fragmented distributor networks.
Among Swiss and German-based integrated suppliers, Sika AG, MBCC Group GmbH, and BASF SE exemplify the premium-tier archetype through in-house environmental product declaration capabilities and REACH-compliant formulation portfolios. These entities occupy positions where EU AI Act supply-chain traceability mandates and digital-product-passport requirements will reward early blockchain-verified documentation adopters in cross-border project bidding.
| Leading Market Players |
|---|
| MAPEI S.p.A. |
| MBCC Group GmbH |
| Sika AG |
| W. R. Grace & Co. |
| RPM International Inc. |
| BASF SE |
| Fosroc International |
| Saint-Gobain Weber |
| Hilti AG |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant European formulators and import-dependent cementitious suppliers splits pricing power along compliance capability lines. Premium epoxy grout producers command formulation patent premiums while commodity cementitious batching operations compete on freight-adjusted landed costs.
Pricing Analysis
Distributor margins compress most severely in cementitious grouts where regional batching plants compete on proximity pricing. Three-tier pricing structure across premium, standard, and economy levels separates patented hybrid epoxy-cementitious systems from certified non-shrink formulations and uncertified commodity blends. Pricing pressure stems from petrochemical resin volatility in specialty formulations. Infrastructure Development procurement teams exhibit lowest price sensitivity for seismic-zone chemical anchors; standard construction contractors drive hardest bargains on cementitious volume.
Supply Chain Analysis
Freight cost differentials favor cementitious raw material sourcing from India, Vietnam, and Saudi Arabia where limestone and clinker processing clusters near coastal export terminals. Epoxy resin feedstocks draw from Gulf Coast petrochemical corridors and Rotterdam refining complexes. Single-source vulnerability concentrates in bisphenol-A derivatives for vinyl ester anchor cartridges. Distribution runs through engineering-procurement-construction framework agreements displacing fragmented regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in low-carbon formulation premiums and direct procurement consolidation, as EU Green Deal compliance costs filter uncertified competitors from public infrastructure bidding.
For Market Incumbents: To counter petrochemical feedstock volatility, Sika AG and MBCC Group GmbH should deepen backward integration into cementitious raw materials while accelerating environmental product declaration capabilities ahead of EU AI Act traceability mandates. Captive supply of supplementary cementitious materials insulates margin pressure from import-dependent competitors. For New Entrants and Emerging Players: Launch via direct framework agreements with Indian metro rail engineering-procurement-construction consortia, bypassing fragmented distributor relationships that incumbent European suppliers dominate. Coastal port modernization at Mundra and Visakhapatnam offers specification windows for corrosion-resistant chemical anchoring systems with lower certification barriers than European public procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier cementitious formulators lack in-house lifecycle assessment capabilities to satisfy EU Green Deal embodied-carbon thresholds. Acquisition targets include regional Indian batching operations with BIS certification portfolios and captive limestone reserves. The signal to watch is bridge agency rejection rates for uncertified grout bids in France and the Netherlands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cementitious Raw Materials | Captive limestone processing shields margin from freight volatility and REACH compliance gaps. |
| Environmental Product Declaration Investment | In-house lifecycle assessment capabilities satisfy EU Green Deal procurement mandates ahead of competitors. |
| Direct EPC Framework Agreements | Single-source accountability reduces interface risk in Indian metro rail and Saudi NEOM projects. |
| Hybrid Epoxy-Cementitious Formulation Patents | Vibration-dampening performance commands premium positioning in German power plant installations. |
| Blockchain-Verified Supply Chain Documentation | EU AI Act traceability rewards early adopters in cross-border infrastructure bidding. |
Research Methodology
Coverage spans India, Germany, the United States, Japan, and Saudi Arabia, with primary inputs from each market triangulated against secondary validation. Interviews with plant engineering contractors, metro rail procurement officers, cementitious raw material suppliers, and construction chemical R&D directors combined with customs trade data, ECHA registration dossiers, BIS certification records, and SEC 10-K filings. Bottom-up project pipeline analysis and top-down macroeconomic calibration generated volume and value estimates.
Rate-of-change decomposition across the analysis window disaggregated volume growth into infrastructure investment intensity, specification substitution effects, and regulatory compliance cost pass-through. Segmentation dimensions modeled include product type, technology tier, application severity, and end-user industry concentration. CAGRs derived from regression analysis against cement consumption, power generation capacity additions, and transportation infrastructure budgets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spike scenarios or accelerated EU carbon border adjustment implementation. Forecasts reflect assumptions about regulatory timeline adherence and infrastructure disbursement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Germany Foam Insulation Market