
 Bronchoscopy Market | 2026-2036
Bronchoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchoscopy Market Analysis
Hospital supply chain consolidation is reshaping how bronchoscopy equipment reaches end users, with group purchasing organizations narrowing vendor panels and demanding validated sterility documentation. Olympus Corporation leverages its integrated manufacturing footprint to control costs across optical and electromechanical product lines. Boston Scientific Corporation competes through specialized therapeutic portfolios targeting interventional pulmonology. Ambu A/S anchors the single-use segment with disposable bronchoscope platforms that eliminate reprocessing liability for outpatient clinics.
Bronchoscopy encompasses the endoscopic examination of airways using flexible or rigid instruments with working channels typically measuring 1.2 to 2.8 millimeters, enabling tissue sampling, foreign body retrieval, and localized drug delivery under direct visualization. Flexible bronchoscopes dominate procedural volume due to navigational reach through subsegmental bronchi, while robotic assistants represent the fastest-growing technology segment as surgeons seek stabilized platform control during complex interventions. Diagnostic applications sustain the largest revenue pool, though therapeutic procedures capture expanding margins as electromechanical devices enable tumor debulking and stent placement.
The FDA enforces reprocessing validation under 510(k) pathways, while the EU Medical Device Regulation mandates clinical evidence for reusable device claims, collectively elevating compliance costs for manufacturers. ISO 13485 quality management standards and Japan's PMDA facility inspections further shape market access requirements across major economies. Stakeholders must monitor how regulatory divergence between the FDA's disposable device fast-track and Europe's MDR sustainability criteria influences capital allocation between single-use and reusable platform development.
Market Dynamics
Single-use bronchoscope platforms are compressing capital equipment cycles as outpatient clinics abandon reprocessing infrastructure, forcing manufacturers to choose between disposable revenue streams and durable goods service contracts.
Growth Catalysts
- EU MDR sterility mandates:Europe's Medical Device Regulation tightens clinical evidence requirements for reusable device claims, accelerating hospital procurement of validated single-use alternatives.
- Interventional pulmonology expansion:Electromechanical tumor debulking and stent placement procedures are widening therapeutic applications beyond diagnostic biopsy.
- Japan's aging demographic:Lung cancer screening volumes in Japanese metropolitan centers are sustaining replacement demand for high-definition imaging platforms.
Market Restraints
- Optical component supply concentration:Precision lens assemblies depend on specialized German and Japanese suppliers, exposing manufacturers to regional production bottlenecks.
- Reprocessing validation costs:FDA 510(k) pathway requirements for sterilization documentation elevate compliance expenditures for reusable platform developers.
- Capital intensity of robotic integration:Stabilized platform control systems require substantial R&D allocation, constraining mid-tier manufacturer participation.
Strategic Opportunities
- India's diagnostic infrastructure buildout:Tier-2 city hospitals present untapped demand for cost-optimized flexible bronchoscopes with simplified reprocessing protocols.
- AI-assisted navigation convergence:Integration of electromagnetic tracking with real-time imaging is enabling peripheral lesion access previously requiring surgical intervention.
- US outpatient clinic channel:Ambulatory surgical centers are adopting disposable procurement models that bypass traditional hospital supply chain hierarchies.
Industry Challenges
- Interventional pulmonology training pipelines:Complex therapeutic procedures require specialized physician credentialing that outpaces fellowship program expansion.
- ISO 13485 certification timelines:Quality management system audits for multi-site manufacturing create months-long market entry delays for platform modifications.
- Legacy equipment integration:New visualization systems must maintain backward compatibility with existing video processors and documentation infrastructure.
Report Scope
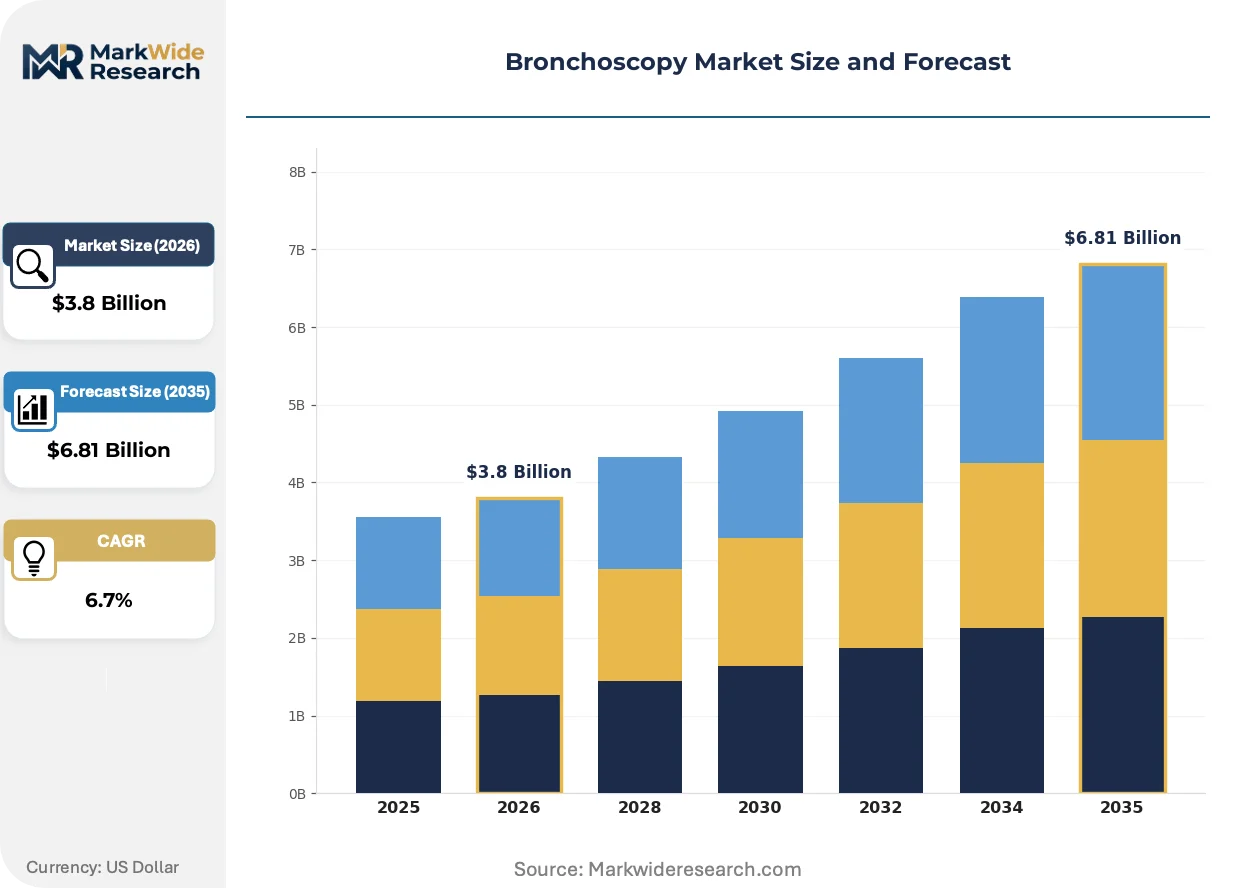
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchoscopy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bronchoscopes, Rigid Bronchoscopes, Accessories, Imaging Systems Application: Diagnosis, Therapeutic Procedures, Research, Education End User: Hospitals, Outpatient Clinics, Emergency Centers, Research Institutes Technology: Optical Systems, Electromechanical Devices, Robotic Assistants, Others |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, KARL STORZ, FUJIFILM Holdings Corporation, Ambu A/S, Medtronic, HOYA Corporation, Teleflex Incorporated, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchoscopy Market Emerging Trajectories
Electromechanical miniaturization and disposable platform economics are converging to redefine bronchoscope lifecycle management, compressing the traditional durable goods model toward consumable-centric revenue architectures.
Chip-on-tip CMOS imaging technology is rendering obsolete fiber-optic bundles in flexible bronchoscope distal ends. Outpatient clinics across the United States and Germany are adopting these solid-state platforms to eliminate fiber degradation and repair costs. The shift is rendering obsolete the decades-old service contract model that tethered hospitals to single-vendor maintenance networks.
Europe's MDR clinical evidence requirements for reusable device sterility claims are forcing manufacturers to submit prospective validation studies. The regulation compresses time-to-market for iterative reusable designs while accelerating FDA fast-track applications for single-use alternatives. German notified bodies are experiencing audit backlogs that extend certification timelines for electromechanical therapeutic platforms.
Hospital group purchasing organizations are consolidating vendor panels and demanding unbundled pricing for devices, reprocessing equipment, and maintenance services. The purchasing model disrupts traditional bundled contracts that locked facilities into decade-long equipment relationships. This restructuring is most visible in United States integrated delivery networks where supply chain offices now negotiate disposable volume commitments separately from capital equipment acquisitions.
Bronchoscopy Market Segmentation
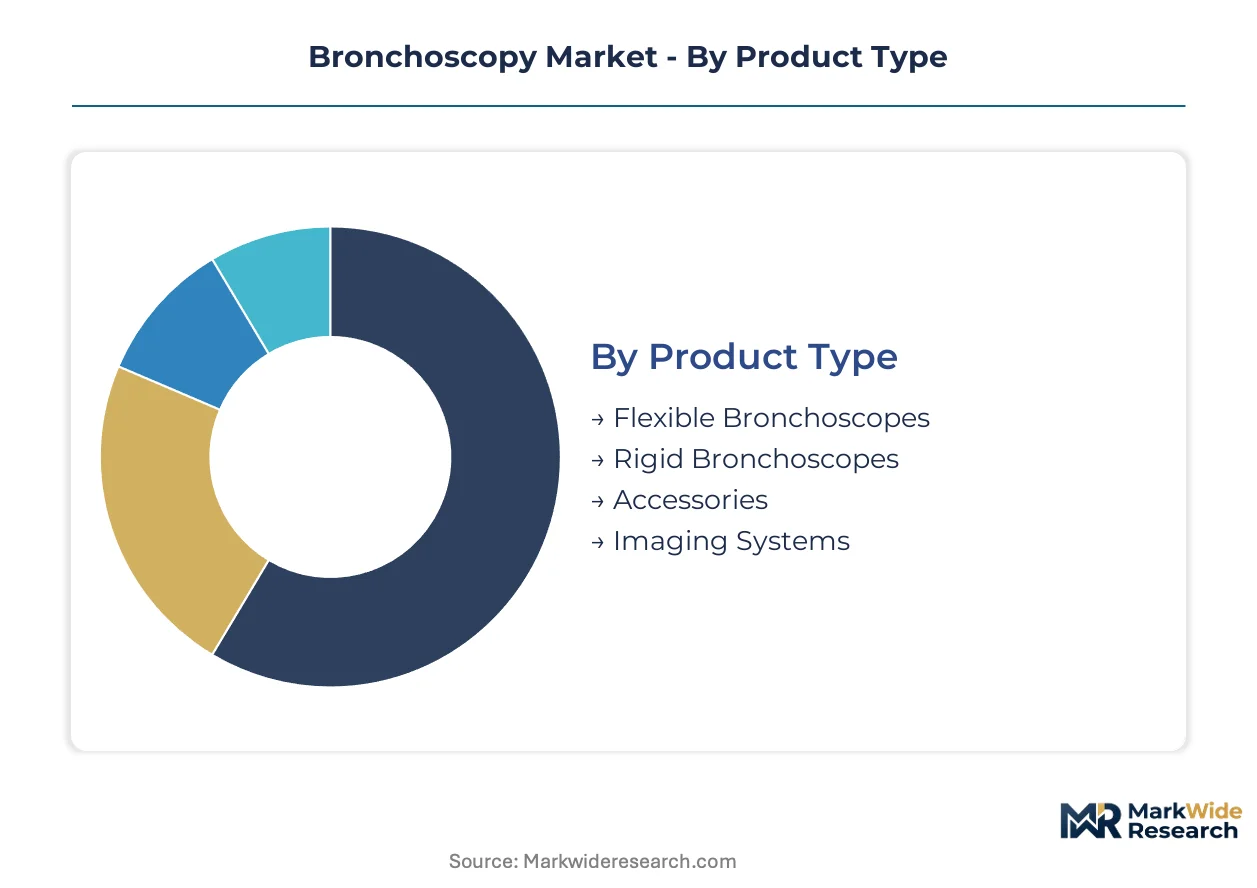
Bronchoscopy market segmentation reveals distinct service intensity profiles across product categories, with reusable platforms demanding multi-year maintenance contracts while disposable alternatives shift revenue toward consumable replenishment cycles. Hospital procurement committees now evaluate total cost of ownership across these divergent lifecycle models.
Product Type:
After-sales service intensity varies dramatically across product types, with flexible bronchoscopes requiring quarterly preventive maintenance and rigid platforms needing annual refurbishment cycles that tether hospitals to manufacturer service networks.
- Flexible Bronchoscopes:Fiber-optic or chip-on-tip CMOS instruments with 1.2 to 2.8 millimeter working channels enable subsegmental airway navigation. Demand concentrates in United States hospital systems where lung cancer screening programs drive high-definition imaging procurement.
- Rigid Bronchoscopes:Metal-sleeved instruments with large-bore suction capability support therapeutic interventions including tumor debulking and foreign body retrieval. German thoracic surgery centers sustain replacement demand for integrated video-rigid systems with ventilating side ports.
- Accessories:Biopsy forceps, brushes, and aspiration needles constitute high-velocity consumable revenue streams.
- Imaging Systems:Video processors and documentation platforms require software upgrade pathways to maintain compatibility.
Flexible bronchoscopes hold the largest share; momentum sits with single-use disposable platforms that eliminate reprocessing liability.
Application:
Application-based segmentation tracks procedure reimbursement differentials, with therapeutic interventions commanding premium coding that justifies capital investment in electromechanical platforms.
- Diagnosis:Tissue sampling and visual inspection for malignancy, infection, or interstitial disease represents the volume base. Japanese metropolitan screening centers sustain demand for high-definition diagnostic platforms with narrow-band imaging capability.
- Therapeutic Procedures:Stent placement, tumor debulking, and foreign body retrieval require specialized instrument channels and electromechanical energy sources. United States interventional pulmonology programs are expanding therapeutic service lines faster than diagnostic capacity.
- Research:Academic medical centers deploy experimental navigation platforms for peripheral lesion access studies.
- Education:Simulation-based training programs drive procurement of durable training bronchoscopes with replaceable distal tips.
Diagnostic applications maintain volume leadership; therapeutic procedures are climbing the fastest as reimbursement codes mature for interventional techniques.
End User:
End user segmentation reflects procurement authority consolidation, with hospital supply chain offices centralizing vendor negotiations while outpatient clinics bypass traditional hierarchies through disposable direct purchasing.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts spanning capital equipment, reprocessing infrastructure, and maintenance services. United States health systems are unbundling these agreements to compare single-use versus reusable total cost models.
- Outpatient Clinics:Ambulatory surgical centers prioritize disposable platforms that eliminate reprocessing facility investment. German outpatient pulmonology practices are adopting single-use bronchoscopes to comply with MDR sterility documentation requirements.
- Emergency Centers:Rapid-access requirements favor portable video bronchoscopy systems with battery-powered processors.
- Research Institutes:Academic procurement emphasizes electromagnetic navigation compatibility and open-architecture software interfaces.
Hospitals retain the dominant procurement volume; outpatient clinics are gaining share fastest as ambulatory migration accelerates.
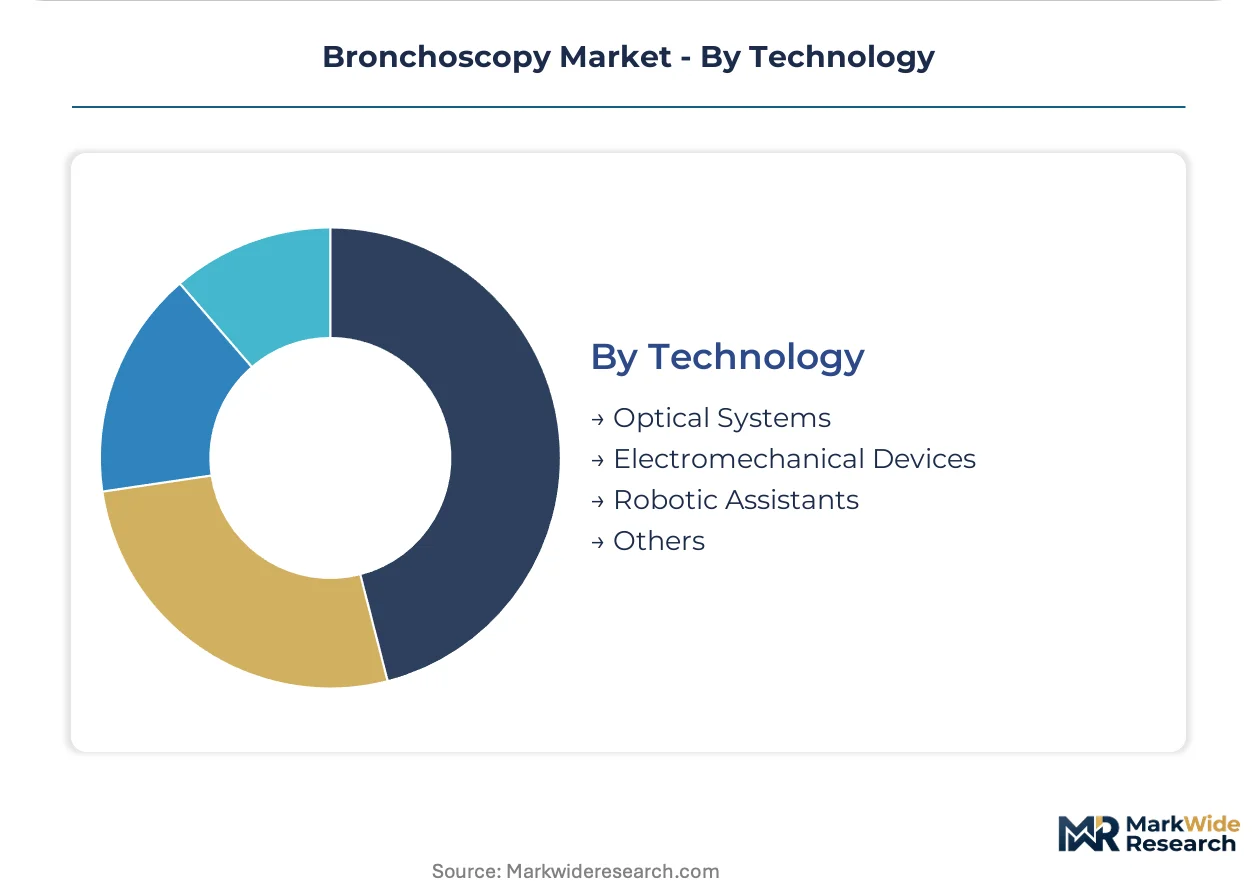
Technology:
Technology segmentation tracks component miniaturization trajectories, with solid-state imaging displacing fiber-optic bundles and robotic platforms requiring substantial R&D allocation that constrains mid-tier participation.
- Optical Systems:CMOS chip-on-tip sensors deliver high-definition visualization without fiber degradation. United States outpatient clinics are prioritizing these platforms to eliminate repair costs and fiber replacement cycles.
- Electromechanical Devices:Integrated energy delivery systems enable tumor debulking and hemostasis during therapeutic procedures. Japanese manufacturers dominate precision motor and articulation mechanism supply.
- Robotic Assistants:Stabilized platform control systems support complex peripheral navigation with electromagnetic tracking.
- Others:Hybrid navigation technologies combining virtual bronchoscopy with real-time imaging.
Optical systems command the installed base; robotic assistants show the steepest expansion trajectory as interventional complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for bronchoscopy equipment, while Japan's Kansai International Airport cold chain infrastructure supports precision optical component transit from Osaka manufacturing clusters.
United States
Lung cancer screening expansion in Medicare populations and ambulatory surgical center proliferation drive flexible bronchoscope procurement. FDA 510(k) reprocessing validation requirements tighten sterility documentation standards for reusable platforms. Texas Medical Center in Houston anchors interventional pulmonology training pipelines that sustain therapeutic device demand.
Germany
Thoracic surgery center consolidation in metropolitan regions sustains rigid bronchoscope replacement cycles. EU MDR sterility mandates accelerate notified body audit backlogs that delay reusable device certifications. Berlin-Brandenburg medical technology corridor hosts precision lens assembly suppliers serving electromechanical platform manufacturers.
Japan
Aging demographic screening volumes in metropolitan centers drive high-definition imaging platform procurement. PMDA facility inspections enforce ISO 13485 quality management compliance across multi-site manufacturing networks. Nagoya industrial cluster concentrates precision motor and articulation mechanism production for flexible instrument supply chains.
India
Tier-2 city hospital diagnostic infrastructure buildout generates cost-optimized flexible bronchoscope demand. CDSCO medical device registration pathways streamline market entry for simplified reprocessing protocol platforms. Maharashtra pharmaceutical and medical device manufacturing belt near Mumbai hosts contract sterilization service providers.
China
Domestic production capacity expansion for chip-on-tip CMOS sensors reduces import dependency for visualization platforms. NMPA medical device classification rules differentiate registration pathways for diagnostic versus therapeutic bronchoscope categories. Yangtze River Delta medical device industrial park near Shanghai concentrates electromechanical component assembly operations.
Bronchoscopy Market Vendor Landscape
On the supply side, the industry is consolidating around integrated manufacturing footprints that control optical and electromechanical production costs. Tiered competitive positioning separates diversified medical technology conglomerates from specialized interventional pulmonology platforms. Three archetypes dominate: diversified endoscopy incumbents with service contract networks, single-use disposable specialists with outpatient clinic channels, and precision electromechanical component suppliers. M&A activity targets navigation technology capabilities, while geographic expansion concentrates on ambulatory surgical center procurement relationships.
Within the diversified endoscopy tier, Olympus Corporation and FUJIFILM Holdings Corporation exemplify integrated manufacturing scale that spans optical component production through video processor integration. Ambu A/S occupies the single-use specialist position, representing disposable platform economics that eliminate reprocessing infrastructure for outpatient settings. Boston Scientific Corporation anchors the interventional therapeutic segment, exemplifying electromechanical portfolio breadth targeting tumor debulking and stent placement procedures.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| KARL STORZ |
| FUJIFILM Holdings Corporation |
| Ambu A/S |
| Medtronic |
| HOYA Corporation |
| Teleflex Incorporated |
| Richard Wolf GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Japanese precision motor manufacturing is tightening supplier leverage across electromechanical bronchoscope platforms, compressing margins for reusable device developers while amplifying pricing power for single-use disposable specialists. This utilization dynamic feeds directly into procurement committee evaluations as hospitals weigh total cost of ownership against capital equipment cycles.
Pricing Analysis
Volume-discount tiering structures separate enterprise health system contracts from ambulatory surgical center spot purchases across the bronchoscopy market. Premium-mid-economy pricing differentiation tracks FDA 510(k) clearance status and ISO 13485 certification grade, with German notified body audit backlogs adding compliance cost premiums to reusable platforms. Price erosion runs through outpatient clinic channels as disposable procurement models bypass traditional GPO hierarchies. Integrated delivery networks exhibit lowest price sensitivity due to unbundled contract negotiation authority, while tier-2 Indian hospitals face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for CMOS chip-on-tip sensors draws from Taiwan semiconductor foundries and Japanese precision optical glass manufacturers, tethering visualization platform output to East Asian wafer capacity cycles. Electromechanical articulation mechanisms hinge on Nagoya industrial cluster production, with German lens assembly suppliers serving rigid bronchoscope therapeutic platforms. Single-source vulnerability concentrates in specialized fiber-optic bundle suppliers facing obsolescence pressure from solid-state imaging conversion. Distribution runs through Rotterdam medical device logistics hubs for European hospital networks and direct disposable shipments to United States ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection in bronchoscopy hinges on interoperability between robotic navigation systems and existing hospital video processor infrastructure, compressing vendor-switching costs for disposable platform adoption.
For Market Incumbents: Entrench service contract networks by backward integrating into CMOS sensor production and securing FDA fast-track pathways for single-use alternatives before MDR sterility mandates harden. Olympus Corporation's manufacturing footprint exemplifies optical-electromechanical integration that constrains mid-tier competitor access to precision component supply. For New Entrants and Emerging Players: India's tier-2 city hospital diagnostic infrastructure presents white-space demand for cost-optimized flexible platforms with simplified reprocessing protocols. CDSCO registration streamlining supports market entry ahead of domestic production scale-up by Chinese CMOS manufacturers. Target GPO contract penetration through unbundled pricing proposals that separate device procurement from maintenance services. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among single-use disposable specialists with ambulatory surgical center channel density, offering superior cash flow predictability over capital equipment cycles. Long-term viability through the next decade rests on navigation technology integration capabilities rather than standalone visualization hardware. Watch FDA guidance divergence from EU MDR sterility requirements as signal for regional platform strategy allocation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR sterility documentation requirements compress reusable device certification timelines for German notified bodies. |
| Hospital System Partnership | United States integrated delivery networks unbundle contracts to compare single-use versus reusable total cost models. |
| Software Companion Development | AI-assisted electromagnetic tracking integration enables peripheral lesion access previously requiring surgical intervention. |
| Reimbursement Strategy | Therapeutic procedure coding maturation in interventional pulmonology justifies electromechanical platform capital investment. |
| Backward Integration | In-house CMOS sensor production insulates against Taiwan foundry capacity constraints and fiber-optic supplier obsolescence. |
Methodological Framework
Cross-validation between primary interviews with interventional pulmonologists and hospital GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body audit records, and CMS Medicare procedure reimbursement databases. Conversations with biomedical engineers and ambulatory surgical center procurement officers supplement bottom-up demand assessment, while Japanese PMDA facility inspection reports and Indian CDSCO registration data provide regulatory pathway triangulation.
Calibration approaches stress-test volume projections across product type, application, end user, and technology segmentation dimensions over the projection horizon. CAGRs derive from installed base replacement cycles, outpatient clinic migration rates, and robotic platform adoption curves modeled through the analysis window. Electromechanical miniaturization cost curves and disposable platform economics feed directly into pricing scenario sensitivity analysis.
Practitioners should monitor FDA reprocessing guidance revisions and EU MDR audit backlog resolution for early signals affecting reusable device time-to-market assumptions. Cross-checking against hospital procurement database benchmarks from United States integrated delivery networks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Global Endoscopes Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
China Arthroscopy Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endoscopy Procedures Estimates Market