
 Endoscope Tracking Solutions Market | 2026-2036
Endoscope Tracking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Tracking Solutions Market Foresight
Germany's precision manufacturing corridor is rewriting supply dynamics for endoscope tracking hardware. Olympus Corporation leverages its endoscopy heritage to anchor tracking software within existing instrument fleets. Karl Storz SE & Co. KG sustains R&D intensity in optical tracking architectures for rigid endoscope workflows. Stryker Corporation competes through channel control across North American surgical suites.
Endoscope tracking solutions comprise sensor-based systems that monitor instrument location, usage cycles, and sterilization status through RFID tags, electromagnetic coils, or optical markers integrated with hospital information networks. These platforms prevent retained surgical items, enforce reprocessing protocols, and generate compliance audit trails for reusable endoscopes. RFID Solutions dominate installed base due to low per-tag cost and mature infrastructure compatibility, while Cloud Integration segments expand fastest as health systems consolidate data across distributed surgical sites. Electromagnetic Systems occupy premium positioning in complex interventional suites where line-of-sight occlusion limits optical alternatives.
FDA Unique Device Identification rules and EU MDR instrument traceability requirements are mandating serialized tracking for reusable surgical devices, directly expanding addressable demand for automated platforms. Japan's PMDA and METI coordinate digital health standards that encompass endoscope lifecycle management, creating parallel compliance obligations for vendors. Stakeholders must monitor evolving interoperability standards between tracking platforms and electronic health records to preserve technology investments.
Market Dynamics
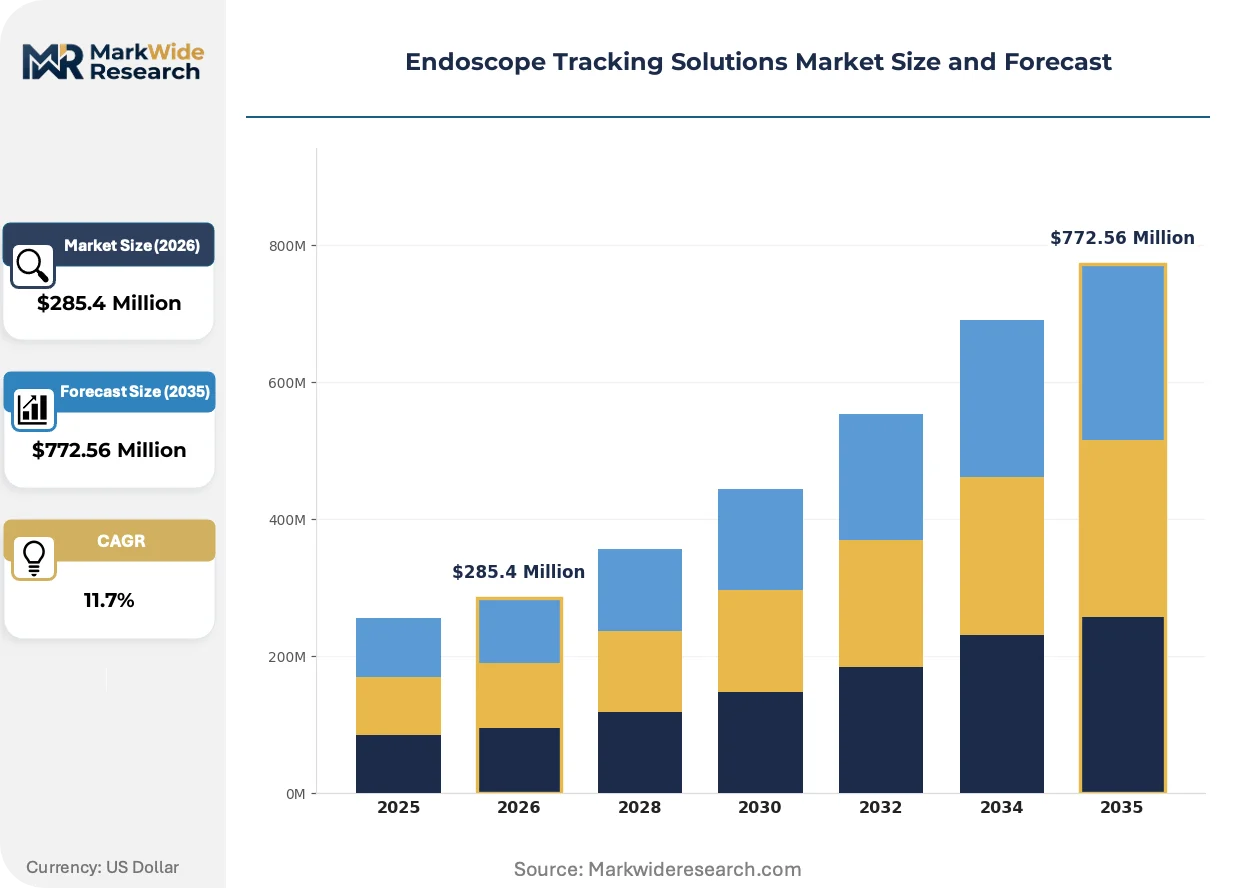
FDA Unique Device Identification mandates and EU MDR instrument traceability requirements are compressing upgrade cycles for hospital tracking infrastructure, forcing capital allocation toward automated serialization platforms before legacy systems reach end-of-life.
Growth Catalysts
- FDA UDI Rule Phase 3:Class II reusable device tracking deadlines are accelerating hospital procurement of RFID-enabled cabinets and automated handoff stations across US surgical networks.
- Cloud Integration:Health systems consolidating data across distributed ambulatory surgical centers are expanding SaaS-based tracking subscriptions faster than on-premise deployments.
- Japan METI Digital Health Standards:Coordinated PMDA lifecycle management protocols are mandating end-to-end instrument traceability in tertiary hospitals throughout Tokyo and Osaka medical corridors.
Market Restraints
- RFID Tag Cost Volatility:Copper and silver antenna substrate prices fluctuate with commodity markets, squeezing per-unit margins for disposable tracking components in high-volume sterilization departments.
- Optical System Limitations:Line-of-sight occlusion in crowded interventional suites restricts camera-based tracking adoption, preserving electromagnetic premium positioning despite higher hardware costs.
- EU MDR Compliance Friction:Notified body backlogs for tracking software as medical device classification are extending certification timelines and freezing procurement decisions in German and French hospital groups.
Strategic Opportunities
- Underpenetrated Indian Tertiary Care:CDSCO medical device rules alignment with IMDRF standards is opening procurement pathways for automated tracking in Mumbai and Delhi NCR super-specialty hospitals.
- AI-Enhanced Predictive Maintenance:Machine learning integration with usage-cycle data is enabling just-in-time endoscope availability guarantees that reduce surgical delays and instrument inventory.
- Subscription Revenue Models:Per-procedure tracking fees are displacing capital purchase structures in US outpatient endoscopy centers, smoothing cash flows for vendors and lowering entry barriers for buyers.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospital IT departments lack personnel trained in RFID electromagnetic interference mitigation and surgical network cybersecurity hardening.
- Legacy HIS Integration Complexity:Proprietary data formats in entrenched electronic health record systems require expensive middleware development for real-time tracking synchronization.
- Multi-Site Standardization Delays:Health systems acquiring independent surgical facilities face years-long harmonization of tracking protocols across incompatible vendor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Tracking Solutions Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $772.56 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Optical Tracking, Electromagnetic Systems, RFID Solutions End User: Hospitals, Clinics, Research Institutions, Surgical Centers Technology: 3D Imaging, Motion Sensors, Cloud Integration, Data Analytics Application: Minimally Invasive Surgery, Diagnostic Imaging, Surgical Navigation, Patient Safety |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Stryker Corporation, FUJIFILM Holdings Corporation, Hoya Corporation, Medtronic plc, Boston Scientific Corporation, Smith & Nephew plc, Intuitive Surgical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Tracking Solutions Market Shifts & Advancements
Sensor fusion architectures and regulatory serialization mandates are converging to transform endoscope tracking from passive inventory control into active clinical workflow orchestration systems.
RFID-electromagnetic hybrid detection is hybridizing location accuracy in complex interventional environments where metallic equipment and dense staff movement degrade single-technology performance. Academic medical centers in Boston and Houston are piloting dual-mode cabinets that switch sensing modalities based on real-time interference detection. This convergence is compressing the performance gap between premium electromagnetic suites and standard RFID deployments, forcing mid-tier vendors to differentiate on software analytics rather than hardware sensing.
EU MDR instrument traceability requirements are mandating Unique Device Identification serialization for all reusable surgical devices placed on the European market after specific compliance deadlines. German manufacturers are reconfiguring production lines to embed permanent machine-readable identifiers during endoscope fabrication rather than applying adhesive labels post-assembly. Rigid endoscope producers in Tuttlingen and Berlin surgical clusters face the steepest adaptation costs due to legacy stainless steel instrument inventories lacking embedded tracking elements.
Consolidated procurement by US health system parent organizations is displacing independent purchasing authority previously held by individual hospital materials management departments. Multi-hospital networks in Texas and Florida are negotiating enterprise tracking contracts that standardize across ambulatory surgery centers, inpatient operating rooms, and specialty clinics. This concentration is most visible in IDN-affiliated endoscopy suites where chief supply officers now mandate single-vendor tracking platforms to simplify training and maintenance contracts.
Endoscope Tracking Solutions Market Segmentation
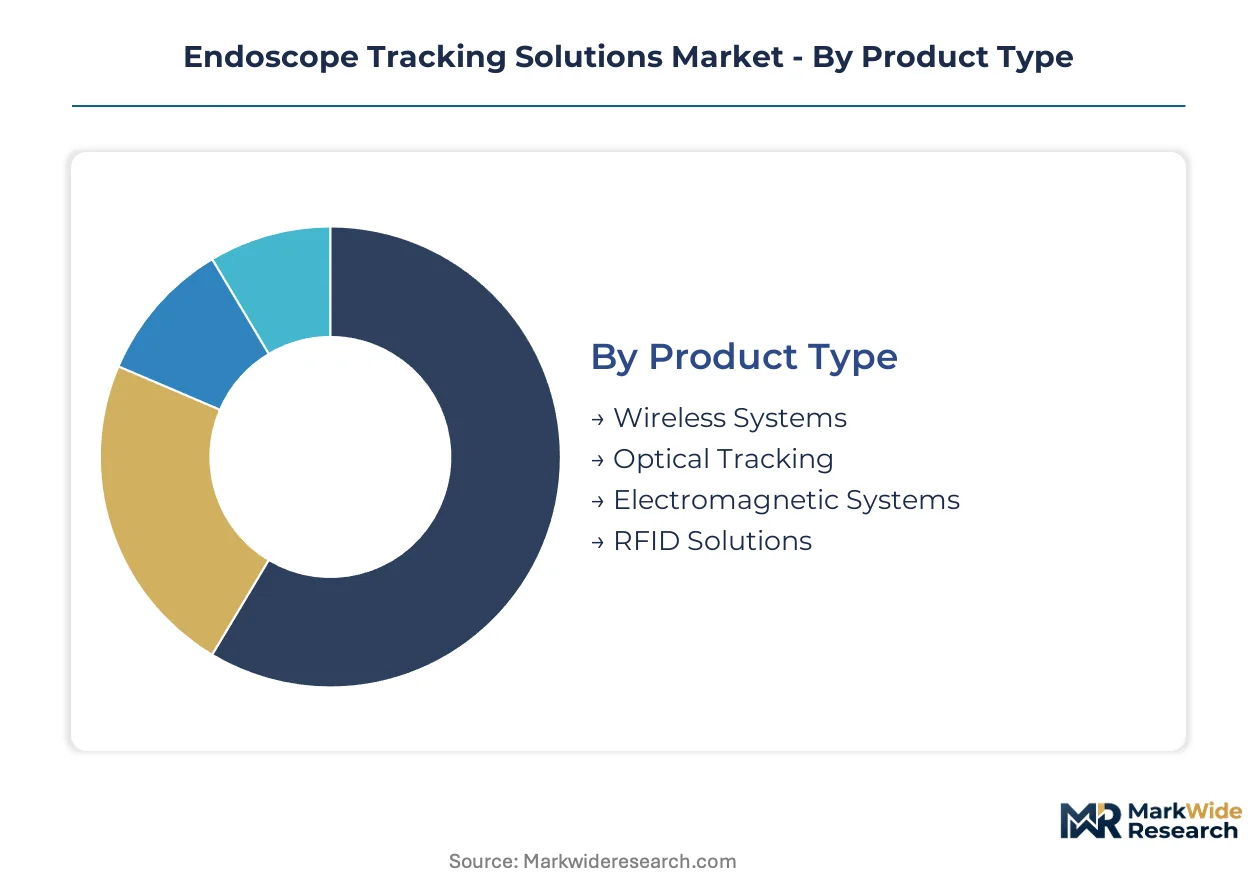
Endoscope tracking solutions fragment across hardware modalities, care settings, and data architectures that determine deployment economics. Procurement decisions hinge on interoperability with existing sterilization workflows and the granularity of traceability required by national regulators.
Product Type:
Cost tier determines hardware selection, with capital intensity varying tenfold between basic RFID tagging and electromagnetic surgical suites.
- RFID Solutions:Passive and active radio-frequency identification tags embed in endoscope handles or sterilization trays, transmitting location and cycle-count data through hospital WiFi or dedicated receivers. United States health systems concentrate procurement here, driven by FDA UDI Phase 3 compliance deadlines for Class II reusable devices.
- Electromagnetic Systems:Field generators and sensor coils track instrument position in six degrees of freedom without line-of-sight requirements. Complex interventional suites in German university hospitals favor this architecture where metallic equipment occludes optical alternatives.
- Optical Tracking:Stereoscopic cameras and reflective markers triangulate instrument position in real time. Budget-constrained Japanese clinics deploy these where electromagnetic interference from MRI suites complicates alternative sensing.
- Wireless Systems:Bluetooth Low Energy and ultra-wideband tags enable room-level localization without infrastructure retrofit. Indian tertiary care pilots favor these for rapid deployment in legacy facilities lacking hardwired tracking networks.
RFID Solutions command the established base. The steepest expansion runs through Cloud-integrated hybrid architectures.
End User:
Customer type shapes contract structure, with enterprise health systems negotiating multi-site subscriptions that outpatient centers cannot match.
- Hospitals:Tertiary academic medical centers deploy enterprise tracking platforms across operating rooms, endoscopy suites, and central sterile processing departments. United States IDN consolidation is compressing vendor selection to single-platform mandates spanning 15-plus facilities.
- Surgical Centers:Ambulatory endoscopy centers prioritize per-procedure SaaS subscriptions over capital purchases. Texas and Florida multi-site operators favor this model to preserve liquidity for expansion.
- Clinics:Solo and group gastroenterology practices deploy basic RFID cabinets for regulatory compliance without workflow integration. German outpatient colonoscopy networks concentrate here under EU MDR instrument traceability obligations.
- Research Institutions:Academic medical centers in Boston and Houston pilot sensor fusion architectures, treating tracking infrastructure as experimental platforms for surgical robotics integration.
Hospitals absorb the majority of installed value. Surgical Centers are climbing the fastest as outpatient migration accelerates.
Technology:
Maturity gradients separate proven sensing modalities from emerging data architectures that require cybersecurity hardening.
- Cloud Integration:SaaS platforms consolidate instrument traceability across distributed surgical sites, enabling real-time dashboards for supply chain and compliance officers. United States health system parent organizations mandate these for standardization across acquired ambulatory centers.
- Data Analytics:Machine learning models predict endoscope availability and flag reprocessing protocol deviations before surgical delays occur. Japanese METI-funded pilots in Tokyo medical corridors validate these algorithms for PMDA digital health standards compliance.
- Motion Sensors:Accelerometers and gyroscopes detect instrument movement patterns to automate usage logging. German rigid endoscope manufacturers embed these during fabrication to satisfy EU MDR Unique Device Identification serialization.
- 3D Imaging:Volumetric reconstruction of endoscope position enables augmented reality overlay for surgical navigation. Complex cardiac and neuro-interventional suites in Houston and Berlin trial these for procedure-specific tracking accuracy.
Cloud Integration captures the majority of new contract value. Data Analytics is expanding most quickly as AI procurement frameworks mature.
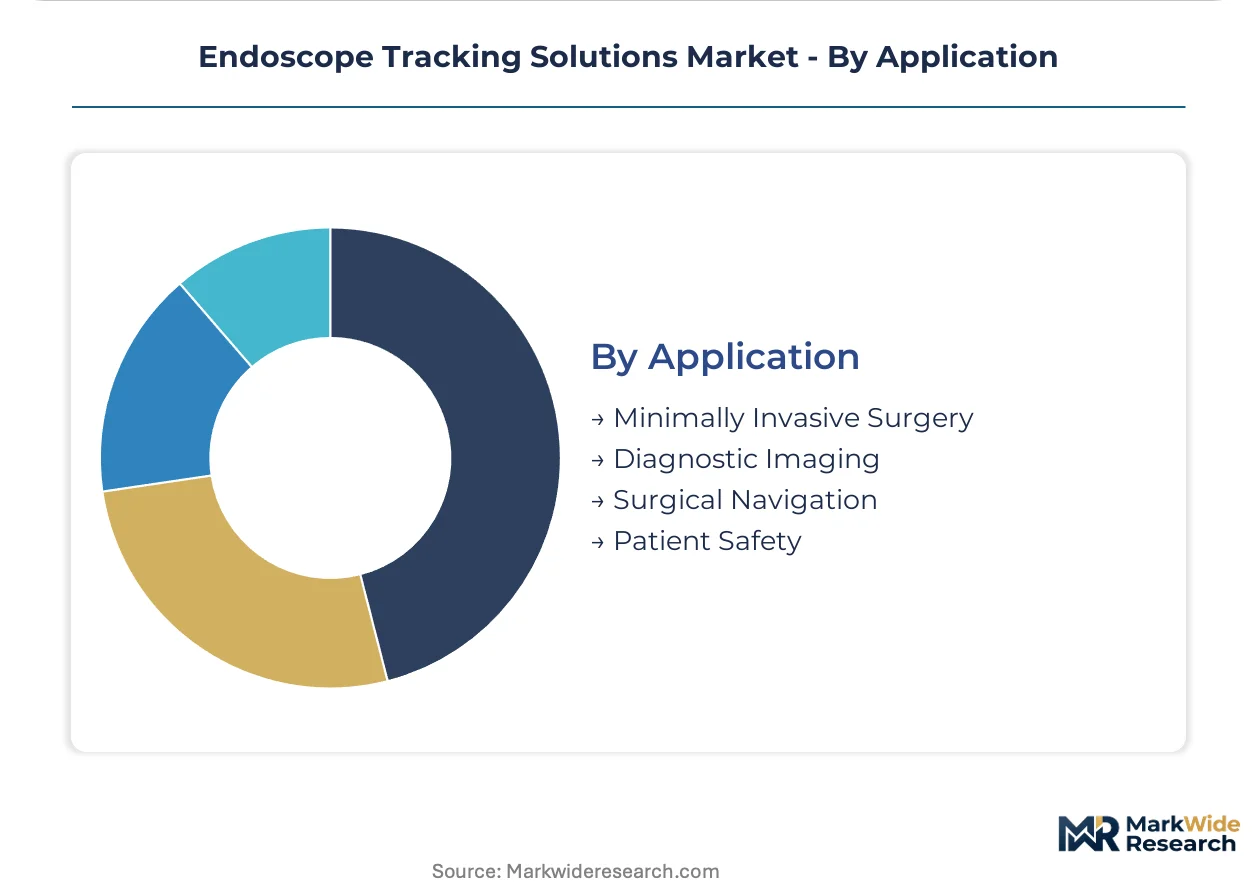
Application:
Clinical use case determines sensor precision requirements, with navigation-grade tracking commanding premiums over basic inventory control.
- Patient Safety:Automated detection of retained surgical items and sterilization protocol violations prevents adverse events. United States malpractice liability exposure drives hospital procurement here regardless of capital cost.
- Minimally Invasive Surgery:Real-time instrument tracking enables robotic arm coordination and laparoscopic tool guidance. German precision manufacturing clusters supply optical tracking for rigid endoscope workflows in Tuttlingen and Berlin.
- Surgical Navigation:Sub-millimeter position accuracy fuses endoscope location with preoperative imaging for augmented reality guidance. Complex spine and ENT procedures in Japanese tertiary centers require electromagnetic alternatives where line-of-sight fails.
- Diagnostic Imaging:Usage-cycle logging and maintenance scheduling extend endoscope functional life. Outpatient endoscopy centers in India deploy basic RFID for CDSCO medical device rule compliance without workflow integration.
Patient Safety applications anchor the installed base. Minimally Invasive Surgery is gaining share fastest as robotic platform adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA UDI Phase 3 deadlines anchor North American procurement intensity while EU MDR serialization mandates compress upgrade cycles across German hospital networks. Japanese METI digital health standards and Indian CDSCO alignment with IMDRF protocols are opening parallel compliance-driven demand corridors.
United States
Hospital end users expand automated tracking infrastructure across IDN-affiliated surgical suites. FDA UDI Phase 3 mandates for Class II reusable devices accelerate RFID-enabled cabinet procurement. Texas and Florida multi-site operators negotiate enterprise contracts standardizing platforms across ambulatory surgery centers.
Germany
Precision manufacturing corridors in Tuttlingen and Berlin reconfigure production lines for EU MDR instrument traceability compliance. Notified body backlogs for tracking software classification extend certification timelines. Karl Storz SE & Co. KG sustains R&D intensity in optical tracking architectures for rigid endoscope workflows.
Japan
PMDA and METI coordinate digital health standards encompassing endoscope lifecycle management. Tokyo and Osaka medical corridors mandate end-to-end instrument traceability in tertiary hospitals. Olympus Corporation leverages its endoscopy heritage to anchor tracking software within existing instrument fleets.
India
CDSCO medical device rules alignment with IMDRF standards opens procurement pathways in Mumbai and Delhi NCR super-specialty hospitals. Tertiary care facilities pilot wireless tracking for rapid deployment in legacy infrastructure. Basic RFID cabinets address compliance without full workflow integration.
United Kingdom
NHS procurement frameworks prioritize interoperability with existing electronic health record systems. London and Southeast academic medical centers pilot sensor fusion architectures for surgical robotics integration. Cloud-based SaaS subscriptions gain traction among hospital trusts consolidating data across distributed sites.
Endoscope Tracking Solutions Market Competitive Landscape
Endoscopy heritage conglomerates and surgical technology integrators split the market between instrument-anchored software platforms and channel-controlled suite solutions. The vendor base concentrates around three strategic archetypes: legacy endoscope manufacturers extending into tracking software, diversified surgical technology conglomerates bundling tracking with capital equipment, and specialized RFID infrastructure vendors. Competitive moves center on enterprise contract consolidation across IDN networks and backward integration into sensor hardware manufacturing.
Within the endoscopy heritage tier, Olympus Corporation and Karl Storz SE & Co. KG exemplify instrument-anchored platform strategies, while Stryker Corporation occupies a position among surgical technology conglomerates competing through North American channel control. These three entities represent divergent approaches to capturing compliance-driven upgrade cycles.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| FUJIFILM Holdings Corporation |
| Hoya Corporation |
| Medtronic plc |
| Boston Scientific Corporation |
| Smith & Nephew plc |
| Intuitive Surgical, Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in electromagnetic coil manufacturing across German precision engineering clusters is compressing lead times and hardening supplier pricing power for premium tracking hardware. FDA UDI Phase 3 procurement surges are stretching RFID tag substrate capacity, forcing hospital buyers into longer-term offtake commitments to secure allocation.
Pricing Analysis
Geographic price spreads between United States and Indian procurement run three-to-one for equivalent RFID cabinet configurations. Three-tier pricing structure across premium electromagnetic suites, standard RFID deployments, and economy optical systems anchors the market. Price differentiation centers on FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in passive RFID tags is intensifying because copper antenna substrate volatility squeezes disposable component margins. Outpatient endoscopy centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Boston prioritize navigation-grade accuracy over capital cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for RFID reader hardware and Bluetooth Low Energy chipsets. Component manufacturing concentrates in China, Germany, and Japan for electromagnetic field generators, optical sensor arrays, and sterilization-grade encapsulation materials. Raw material dependencies span rare-earth magnets for coil assemblies, medical-grade stainless steel for rigid endoscope integration, and copper-silver antenna substrates. Single-source vulnerability in ultra-wideband chip supply threatens wireless system deployment timelines. Distribution runs through GPO contracts in United States hospital networks and direct OEM relationships in German surgical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscope tracking solutions represent a service-attach opportunity where SaaS-based analytics subscriptions expand faster than hardware replacement cycles. Cloud-integrated compliance dashboards and per-procedure tracking fees now generate recurring revenue streams that outpace capital equipment sales.
For Market Incumbents: Entrench platform stickiness through backward integration into sterilization-grade RFID tag manufacturing and exclusive GPO contract lockups. Cloud-native entrant pressure demands defensive software R&D spending to preserve installed-base migration costs. Channel control across IDN-affiliated surgical suites remains the critical lever for margin defense.
For New Entrants and Emerging Players: Indian tertiary care facilities in Mumbai and Delhi NCR offer the most penetrable geographic entry point where CDSCO compliance deadlines outpace local vendor capacity. Wireless tracking pilots in legacy infrastructure require minimal capital retrofit. A SaaS-first go-to-market angle with per-procedure pricing lowers hospital procurement committee friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-integrated tracking vendors with established hospital system subscriptions. Five-to-ten year viability favors platforms with FDA UDI compliance certification and embedded EHR interoperability. Acquisition targets should demonstrate proven sensor fusion R&D pipelines. The signal to watch is IDN enterprise contract consolidation velocity as health system parent organizations mandate single-vendor standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Hardware Development | Dual-mode RFID-electromagnetic cabinets capture complex interventional suite demand in Houston and Berlin academic centers. |
| Cloud-Native Platform Migration | SaaS architectures enable real-time compliance dashboards across distributed ambulatory surgery centers for IDN standardization. |
| EU MDR Serialization Compliance | Embedded UDI tracking elements during endoscope fabrication satisfy notified body requirements for German rigid instrument producers. |
| Hospital System Partnership | Enterprise contracts with Texas and Florida multi-site operators lock out competitor access across 15-plus facility networks. |
| AI-Enhanced Predictive Maintenance | Machine learning integration with usage-cycle data reduces surgical delays and instrument inventory for Japanese METI-funded pilots. |
Research Methodology
A standing panel of hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and sterile processing department supervisors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract repositories, and CDSCO medical device registration records. Bottom-up tracking platform deployment counts triangulated against top-down health system capital expenditure surveys.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for regulatory deadline delays and commodity input volatility. Segmentation dimensions modeled include hardware modality, care setting, data architecture, and geographic regulatory cluster. CAGRs derived from installed base growth rates and average selling price trajectories. Forecast inputs incorporated FDA UDI Phase 3 compliance timelines and EU MDR serialization mandate enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and copper commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and health system consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Colonic Stents Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Global Neuroendoscopy Market