
 United Kingdom Endoscopy Devices Market | 2026-2036
United Kingdom Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Endoscopy Devices Market Analytics
4K visualization and single-use sterile specifications are bifurcating the United Kingdom endoscopy devices landscape. Olympus Corporation leverages its vertically integrated imaging sensor supply to sustain premium positioning across NHS trusts. Karl Storz SE & Co. KG anchors its competitive stance through rigid endoscope specialization in laparoscopic suites. FUJIFILM Holdings Corporation differentiates via advanced image processing platforms that dominate gastrointestinal diagnostic workflows.
Endoscopy devices encompass illumination, optical, and digital imaging systems designed for minimally invasive internal examination, typically employing CMOS or CCD sensors with working channels of 2.0–3.7 mm diameter for instrument passage and fluid delivery. These systems enable diagnostic visualization and therapeutic intervention across mucosal surfaces, visceral organs, and joint spaces without open surgical access. Visualization systems command substantial margin pools as hospitals upgrade from standard-definition to 4K and 3D platforms. Laparoscopy technology leads procedural volume within the technology dimension while single-use endoscopes represent the fastest-expanding product type segment as infection control protocols intensify.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking and post-market vigilance under retained EU Medical Device Regulation frameworks, elevating compliance costs for reusable device reprocessing. The Care Quality Commission inspects endoscopy decontamination facilities, directly shaping capital allocation toward disposable alternatives. NHS England's sterilization guidelines and Health Technical Memorandum standards further constrain device selection criteria. Stakeholders must monitor MHRA divergence from EU MDR harmonization timelines and calibrate product registration strategies accordingly.
Market Dynamics
The United Kingdom endoscopy devices market is bifurcating around infection control mandates from the Medicines and Healthcare products Regulatory Agency and the operational economics of single-use versus reusable platforms. NHS England's sterilization guidelines and accelerated screening programmes are compressing procurement cycles while elevating capital allocation toward disposable alternatives.
Growth Catalysts
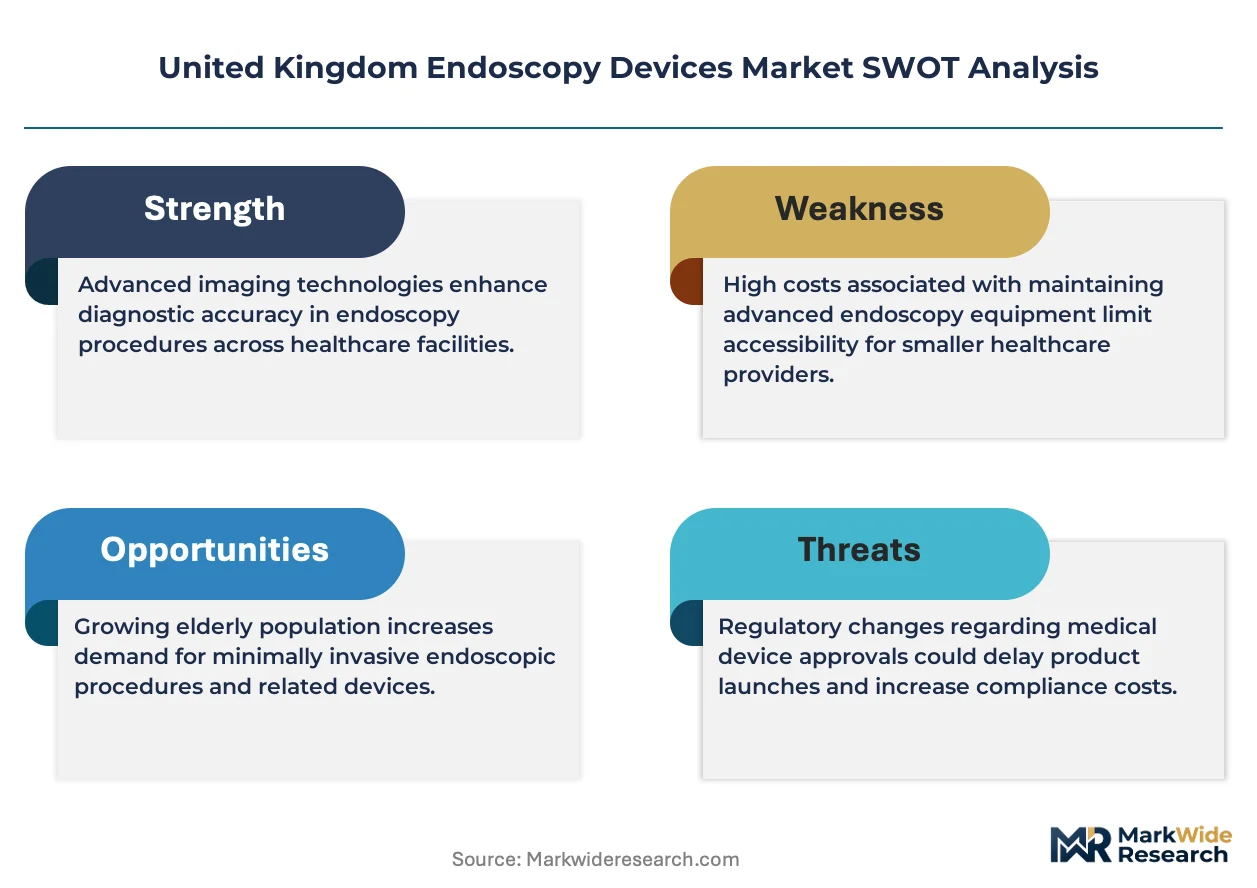
- NHS England's accelerated colorectal screening programmes:Expanded diagnostic volumes across hospital endoscopy units are driving capital equipment refresh cycles and consumable throughput requirements.
- Health Technical Memorandum standards:Decontamination facility inspections by the Care Quality Commission are redirecting provider budgets toward single-use endoscope platforms that bypass reprocessing infrastructure.
- CMOS sensor proliferation:Solid-state imaging technology is displacing legacy CCD architectures across gastrointestinal and laparoscopic visualization systems, enabling cost reduction at equivalent resolution.
Market Restraints
- UKCA marking compliance costs:Retained EU Medical Device Regulation frameworks under MHRA enforcement are elevating registration expenses and technical documentation burdens for reusable device manufacturers.
- Specialized reprocessing workforce scarcity:Certified decontamination technicians concentrate in London, Manchester, and Birmingham tertiary centres, constraining service expansion into peripheral NHS trusts.
- Single-use polymer cost volatility:Medical-grade plastics and specialty polymers face input price instability that compresses margin pools for disposable endoscope producers.
Strategic Opportunities
- Semi-disposable platform hybridization:Modular designs separating reusable imaging cores from disposable insertion tubes offer NHS procurement teams capital-expenditure flexibility alongside infection control assurance.
- Scotland and Wales screening programme lag:Underpenetrated diagnostic infrastructure outside England's core metropolitan clusters presents whitespace for regional distribution partnerships and mobile endoscopy unit deployment.
- 4K-3D visualization convergence:Surgical suites in complex interventional centres are integrating ultra-high-definition displays with stereoscopic depth mapping, opening premium replacement cycles for visualization towers.
Industry Challenges
- Interoperability with legacy PACS infrastructure:New visualization systems must integrate with hospital-specific picture archiving and communication architectures, extending deployment timelines and technical validation requirements.
- MHRA-EU MDR divergence monitoring:Regulatory strategy teams must track harmonization timeline uncertainty, calibrating product registration pathways against potential future misalignment between UK and continental conformity assessment procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Endoscopy Devices Market |
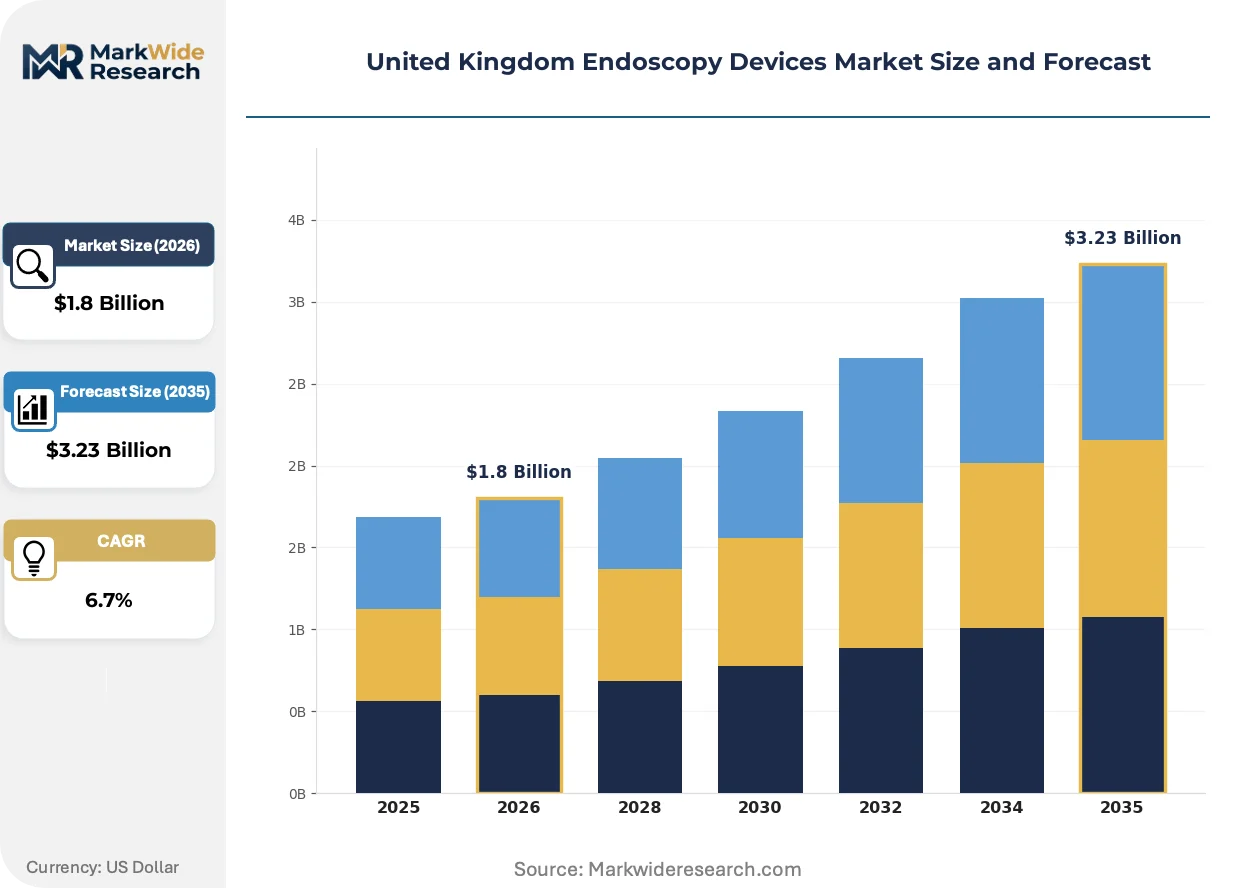
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
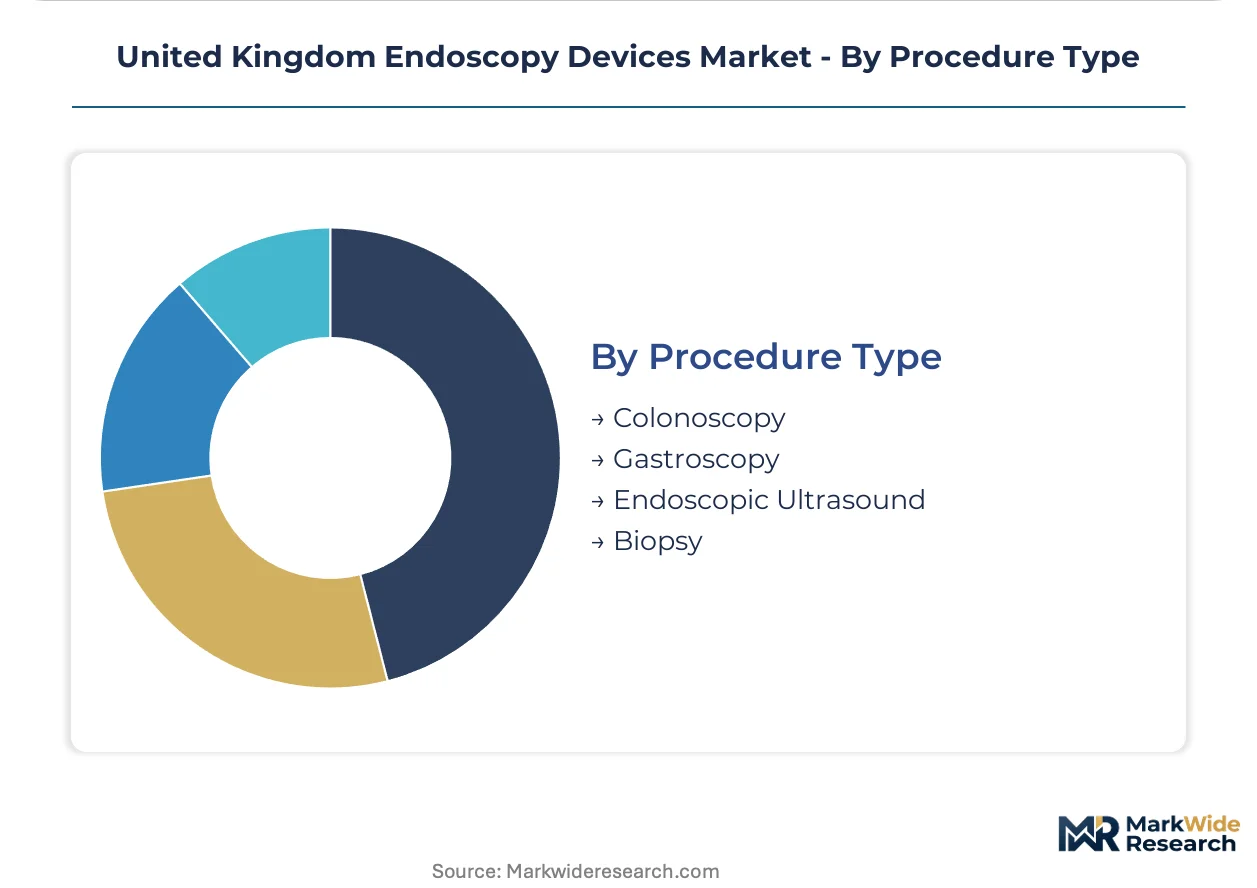
| Segmentation | Product Type: Endoscopes, Surgical Instruments, Visualization Systems, Accessories Technology: GI Endoscopy, Bronchoscopy, Urology Endoscopy, Laparoscopy End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Clinics, Research Laboratories Procedure Type: Colonoscopy, Gastroscopy, Endoscopic Ultrasound, Biopsy |
| Companies Covered | Olympus Corporation, FUJIFILM Holdings Corporation, Karl Storz SE & Co. KG, Boston Scientific Corporation, Medtronic plc, Stryker Corporation, Richard Wolf GmbH, Cook Medical Incorporated, CONMED Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Endoscopy Devices Market Evolving Landscape
Digital imaging sensor miniaturization and disposable platform engineering are converging to reshape procurement economics across NHS endoscopy services. The competitive frontier has shifted from optical performance specifications toward total cost of ownership and infection risk mitigation.
CMOS imaging sensors with sub-2.0 mm working channel integration are miniaturizing diagnostic endoscope distal tips while preserving 1080p resolution thresholds. Gastroenterology units in London teaching hospitals are adopting these platforms for transnasal esophagoscopy procedures. The technology is compressing the addressable market for traditional flexible fiberoptic scopes in outpatient diagnostic settings.
The Medicines and Healthcare products Regulatory Agency's retained EU MDR post-market surveillance requirements are mandating enhanced vigilance reporting for reusable endoscope adverse events. Manufacturers must now maintain UK-based authorized representatives and expanded clinical evidence portfolios. Single-use endoscope categories are capturing disproportionate commercial attention as providers seek to eliminate reprocessing-related liability exposure.
Trust-level procurement consolidation is aggregating purchasing authority across former district general hospital networks. NHS Supply Chain frameworks and collaborative procurement hubs are displacing individual hospital capital committees as the primary decision locus for visualization platform acquisitions. This concentration is most visible across the Midlands and North West England, where integrated care systems are standardizing equipment specifications across multiple endoscopy units simultaneously.
United Kingdom Endoscopy Devices Market Segmentation
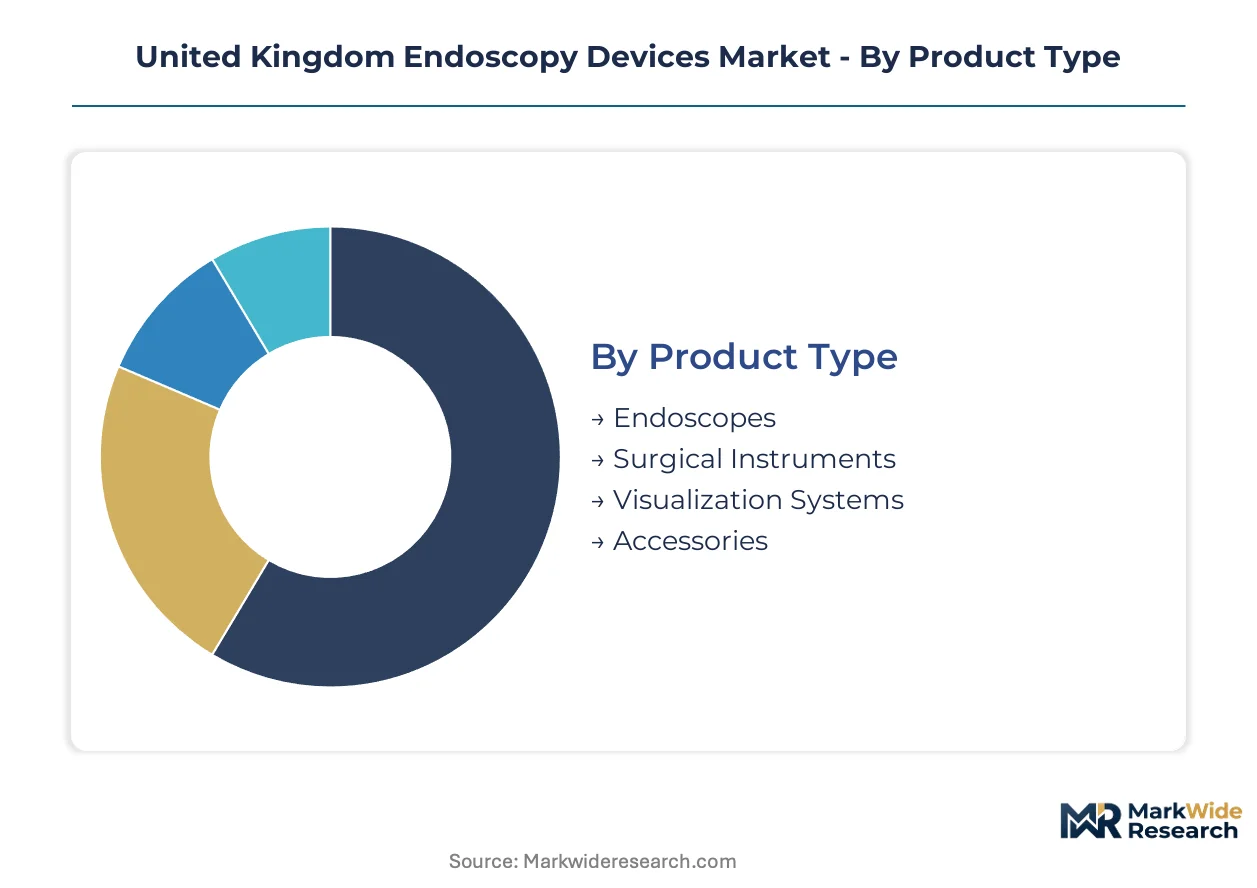
Endoscopy device segmentation in the United Kingdom reveals distinct procurement patterns across NHS trusts and private providers. Technology substitution pressures and infection control mandates are reshaping capital allocation priorities across every category.
Product Type:
Single-use platform substitution threatens reusable endoscope margins most acutely in this category, driving bifurcation between capital-intensive and consumable-heavy procurement models.
- Endoscopes:Flexible fiberoptic and video endoscopes incorporate CMOS sensors with 2.0–3.7 mm instrument channels. NHS England's accelerated screening programmes concentrate demand across London, Manchester, and Birmingham tertiary centres where procedure volumes justify dedicated reprocessing infrastructure or disposable alternatives.
- Visualization Systems:These comprise processor units, light sources, and 4K/3D display towers enabling ultra-high-definition mucosal examination. Hospital trusts in the Midlands and North West England are aggregating purchasing authority through integrated care systems, standardizing visualization specifications across multiple endoscopy units simultaneously.
- Surgical Instruments:Biopsy forceps, snares, and electrocautery devices designed for endoscopic working channels.
- Accessories:Irrigation pumps, insufflators, and bite blocks supporting procedural workflow efficiency.
Visualization Systems retain volume leadership; Endoscopes hold the steepest expansion curve as single-use alternatives gain procurement share.
Technology:
Cost tier stratification separates high-volume diagnostic procedures from complex interventional applications requiring specialized optical engineering.
- GI Endoscopy:Gastrointestinal platforms dominate procedural throughput across NHS colorectal screening pathways. The Care Quality Commission's decontamination facility inspections are redirecting provider budgets toward single-use gastroscopes that bypass reprocessing liability in London teaching hospitals.
- Laparoscopy:Rigid endoscopic systems enable minimally invasive abdominal surgery through trocar access. Complex interventional centres in Birmingham and Manchester are integrating 4K-3D visualization convergence for stereoscopic depth mapping in surgical suites.
- Bronchoscopy:Pulmonary diagnostic and therapeutic access for airway examination and biopsy.
- Urology Endoscopy:Cystoscopic and ureteroscopic platforms for urinary tract visualization and stone management.
GI Endoscopy commands the largest installed base; Laparoscopy demonstrates the most rapid technology refresh cycles driven by visualization upgrades.
End User:
Customer type determines capital availability and infection control risk tolerance, with NHS trusts facing distinct procurement constraints versus independent sector providers.
- Hospitals:Acute NHS trusts maintain centralized endoscopy units with dedicated decontamination facilities. MHRA's retained EU MDR post-market surveillance requirements mandate enhanced vigilance reporting for reusable device adverse events, elevating compliance costs and redirecting capital toward disposable platforms.
- Ambulatory Surgery Centers:Independent sector treatment centres concentrate on high-volume diagnostic procedures with streamlined patient pathways. These facilities favour single-use endoscopes to eliminate reprocessing infrastructure investment and reduce Care Quality Commission inspection exposure.
- Diagnostic Clinics:Community-based endoscopy services supporting NHS screening programme delivery.
- Research Laboratories:Academic medical centres developing novel interventional techniques and imaging protocols.
Hospitals retain volume leadership; Ambulatory Surgery Centers are gaining share fastest as NHS outsourcing expands diagnostic capacity.
Procedure Type:
Application maturity varies from routine screening to advanced interventional techniques, with reimbursement pathways shaping technology adoption speed.
- Colonoscopy:Complete large bowel examination with polypectomy capability represents the procedural anchor for NHS England's colorectal screening expansion. Demand concentrates in tertiary referral centres handling complex interventional procedures and high-risk patient cohorts.
- Endoscopic Ultrasound:EUS combines endoscopic access with ultrasonic imaging for mediastinal and pancreaticobiliary evaluation. London teaching hospitals are adopting these platforms for transnasal esophagoscopy procedures, compressing the addressable market for traditional flexible fiberoptic scopes.
- Gastroscopy:Upper gastrointestinal examination for dyspepsia and Barrett's surveillance.
- Biopsy:Tissue sampling procedures across all anatomical territories.
Colonoscopy retains volume leadership; Endoscopic Ultrasound holds the steepest expansion curve as interventional capabilities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German endoscope manufacturers export visualization systems and rigid laparoscopic platforms to NHS procurement frameworks, while Japanese imaging specialists supply CMOS sensor technology to London teaching hospitals.
London and the Southeast
NHS England's accelerated colorectal screening programmes concentrate demand across tertiary referral centres in London. The Care Quality Commission inspects decontamination facilities at St Bartholomew's and Guy's Hospital, redirecting capital toward single-use gastroscope platforms. Royal Free Hospital and University College Hospital anchor complex interventional endoscopy volumes for Endoscopic Ultrasound procedures.
Midlands
Integrated care systems across Birmingham and Coventry aggregate purchasing authority through NHS Supply Chain frameworks. Queen Elizabeth Hospital Birmingham handles complex interventional procedures requiring 4K-3D visualization convergence. The region's sterilization infrastructure constraints push procurement teams toward disposable alternatives that bypass Health Technical Memorandum compliance burdens.
North West England
Manchester Royal Infirmary and Salford Royal anchor high-volume diagnostic workflows for NHS screening programme delivery. Certified decontamination technician scarcity concentrates service capability in these tertiary centres, constraining expansion into peripheral Lancashire and Cumbria trusts. Ambulatory surgery centres in Greater Manchester favour single-use platforms to eliminate reprocessing infrastructure investment.
Scotland
NHS Scotland's diagnostic infrastructure lags England's screening programme expansion, presenting whitespace for mobile endoscopy unit deployment. Glasgow Royal Infirmary and Edinburgh Royal Infirmary maintain centralized endoscopy services with limited satellite capacity. The Scottish Government's health technology assessment processes extend procurement timelines compared to NHS England frameworks.
Wales
Cardiff and Vale University Health Board concentrates endoscopy capacity with limited distributed service points. Welsh Government screening programme implementation trails England's accelerated pathway, constraining equipment refresh cycles. Swansea Bay University Health Board explores collaborative procurement with English integrated care systems to access NHS Supply Chain pricing.
United Kingdom Endoscopy Devices Market Competitive Landscape
Listed leaders compete with private specialists across visualization platform and endoscope technology dimensions. The United Kingdom market structures around three tiers: diversified medical technology conglomerates with full-stack portfolios, specialized endoscopy equipment manufacturers with vertical imaging capabilities, and single-use disposable platform entrants. Strategic moves concentrate on modular platform hybridization separating reusable imaging cores from disposable insertion tubes, alongside trust-level procurement consolidation through integrated care system frameworks.
Among Japanese and German imaging specialists, Olympus Corporation and Karl Storz SE & Co. KG exemplify divergent archetypes—Olympus representing vertically integrated sensor-to-system capability, Karl Storz occupying rigid endoscope specialization for laparoscopic suites. FUJIFILM Holdings Corporation anchors advanced image processing differentiation within gastrointestinal diagnostic workflows. These three entities sit within distinct competitive positions: conglomerate-scale imaging platform ownership, precision optical engineering heritage, and computational imaging software integration respectively.
| Leading Market Players |
|---|
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| Karl Storz SE & Co. KG |
| Boston Scientific Corporation |
| Medtronic plc |
| Stryker Corporation |
| Richard Wolf GmbH |
| Cook Medical Incorporated |
| CONMED Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization differentials between German precision-optics manufacturers and Asian CMOS sensor fabricators concentrate pricing power upstream while compressing margin pools for NHS procurement intermediaries. Scale advantages in disposable polymer molding anchor price floors for single-use endoscope categories, forcing reusable-platform vendors toward service-bundle differentiation.
Pricing Analysis
Standard-definition to 4K visualization platform spreads define the technology-generation pricing gap, with legacy towers trading at substantial discounts to 3D-capable systems. Three-tier pricing structure across premium, standard, and economy levels segments by optical resolution, software integration depth, and after-sales service bundling. Cost compression in standard-definition tiers is intensifying because NHS integrated care systems aggregate purchasing authority across multiple trusts. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while London teaching hospitals prioritize performance over procurement cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate CMOS sensor procurement from Japanese and South Korean fabricators, while strategic stockpiling of medical-grade polymers buffers against petrochemical feedstock volatility. German and Japanese manufacturers anchor optical component supply, with Chinese assembly operations handling final device integration. Raw material dependencies center on rare-earth elements for lens coatings, specialty polymers for insertion tubes, and high-purity glass for fiberoptic bundles. Single-source vulnerability concentrates in CMOS sensor wafer fabrication. Distribution runs through NHS Supply Chain frameworks and specialized medical device distributors serving independent sector providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use platform substitution represents a high-growth disruption, with MHRA infection control mandates accelerating procurement pivot away from reusable infrastructure.
For Market Incumbents: Secure decontamination facility partnerships with London teaching hospitals to lock in service revenue streams against disposable-platform erosion. Backward integration into CMOS sensor supply chains preserves margin control as Japanese fabricators consolidate. Certification investment in UKCA marking pathways ahead of potential EU MDR divergence protects market access. For New Entrants and Emerging Players: Lead with semi-disposable modular designs targeting Midlands integrated care systems seeking capital-expenditure flexibility. Scotland and Wales screening programme lag presents the most penetrable geographic whitespace. Mobile endoscopy unit deployment partnerships with regional NHS trusts offer rapid go-to-market validation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among single-use platform specialists with NHS Supply Chain framework inclusion. Long-term viability over the next decade hinges on infection control regulatory trajectory rather than technology performance metrics. Acquisition targets should demonstrate sterilization liability elimination capabilities. The signal to watch is MHRA-EU MDR harmonization timeline announcements as inflection indicators for reusable-platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Hybridization | Separates reusable imaging cores from disposable insertion tubes, aligning with NHS capital constraints. |
| UKCA Marking Acceleration | Expedites regulatory clearance ahead of potential EU MDR divergence timelines. |
| Integrated Care System Partnership | Aggregates purchasing authority across Midlands and North West England trust networks. |
| Mobile Endoscopy Unit Deployment | Addresses Scotland and Wales infrastructure gaps without fixed-capital investment. |
| CMOS Sensor Supply Agreement | Secures imaging component access from Japanese and South Korean fabricators. |
Research Methodology
Operator-level perspectives from NHS procurement managers, biomedical engineers in London teaching hospitals, Care Quality Commission inspection leads, and independent sector treatment centre directors anchored the qualitative base. Primary interview data combined with secondary validation from MHRA device registration databases, NHS Supply Chain framework awards, hospital procurement records, and EU MDR retained legislation documentation. Bottom-up equipment installation counts triangulated against top-down market sizing from trade flow analysis.
Sensitivity analysis tested forecast outputs against single-use adoption velocity scenarios and regulatory divergence timing assumptions across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user facility category, and procedure application complexity. CAGRs derived from equipment replacement cycle analysis and consumable throughput projections tied to NHS screening programme expansion targets. CMOS sensor cost curves and polymer feedstock indices informed input cost trajectories.
The analysis sits within stated boundaries; outcomes outside maintained MHRA-EU regulatory alignment or sustained NHS capital allocation levels would require recalibration. Forecasts reflect documented assumptions regarding screening programme implementation pace and infection control protocol stringency. Revision becomes warranted when single-use platform procurement share crosses threshold levels that trigger reusable infrastructure abandonment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market