
 Global Digital Pathology Systems Market | 2026-2036
Global Digital Pathology Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Pathology Systems Market Intelligence
The digital whole slide image, as a replacement for physical glass slides, is expanding the scope of remote diagnostics and collaborative research. Koninklijke Philips N.V. leverages its extensive background in clinical informatics and medical imaging to offer integrated solutions. Danaher Corporation, through its Leica Biosystems subsidiary, competes by offering a full workflow from tissue processing to digital scanning. Proscia specializes in AI-driven software platforms for enterprise-wide pathology operations.
Digital pathology systems convert physical glass slides into high-resolution digital images via whole slide imaging scanners, often at 40x magnification. Their purpose is to enable efficient management, sharing, and analysis of pathological images for diagnosis and research. Image Management Software and cloud-based platforms are critical for handling the immense data volume. The market's value is increasingly found in Artificial Intelligence and Image Analysis software, especially for oncology applications.
Regulatory clearance is a critical gatekeeper, with the FDA in the United States providing specific guidance for primary diagnostic use. In Europe, compliance with the In Vitro Diagnostic Regulation (IVDR) and CE marking is mandatory for market entry. The central challenge for providers is now to ensure interoperability between different scanner and software platforms to create a seamless, vendor-agnostic workflow.
Market Dynamics
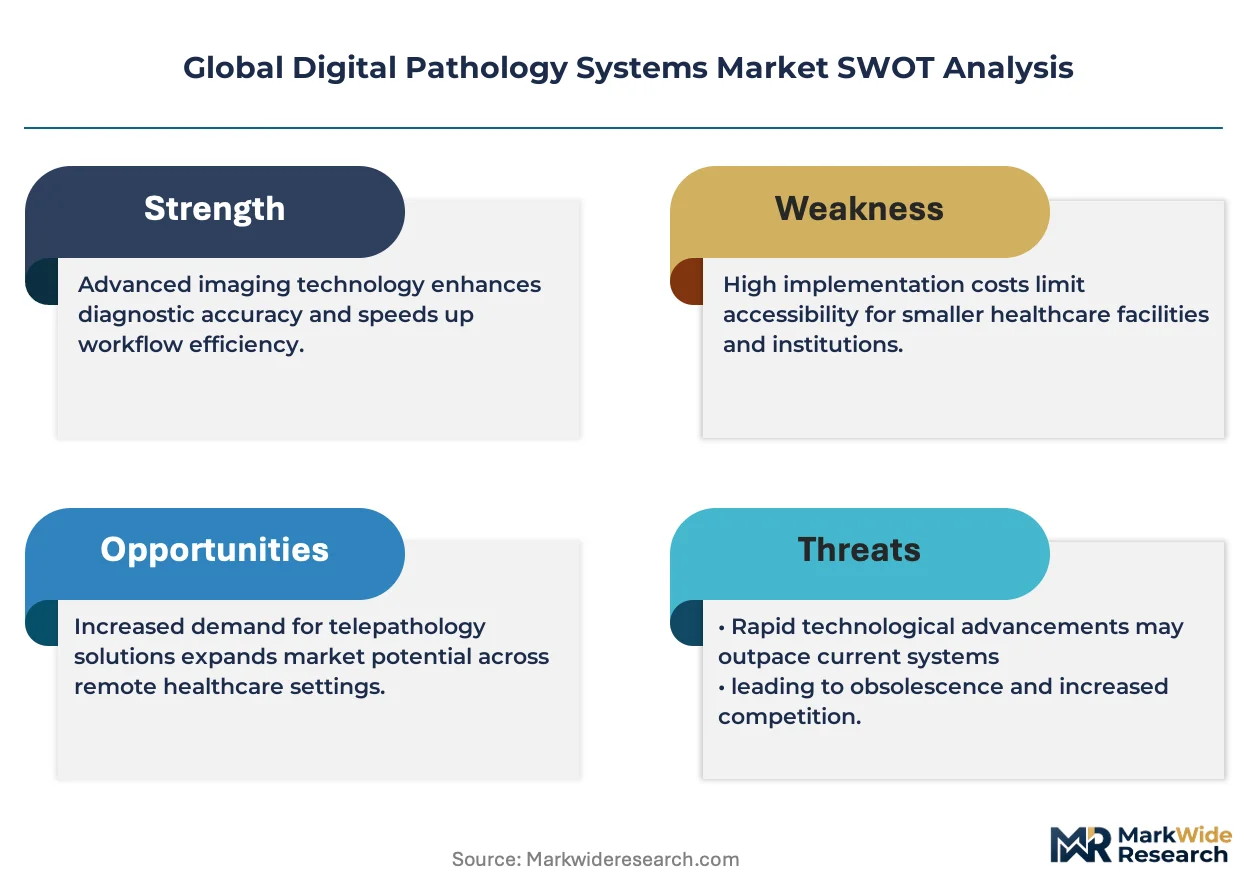
The convergence of computational power and clinical necessity defines the digital pathology market's momentum. The increasing demand for precision in oncology diagnostics, coupled with the maturation of artificial intelligence for image analysis, creates a powerful pull for digitizing traditional histopathology workflows.
Growth Catalysts
- Artificial Intelligence Integration:The application of machine learning algorithms to analyze whole slide images enhances diagnostic accuracy and workflow efficiency, particularly in quantifying biomarkers for cancer diagnosis and research.
- Regulatory Approvals:Landmark clearances by the FDA for primary diagnostic use in the United States have legitimized digital pathology, encouraging broader clinical adoption and investment in laboratory digitization.
- Pathology Lab Consolidation:A trend towards lab consolidation in developed healthcare systems, such as in Germany, necessitates scalable, networked solutions that enable remote case sharing and workload balancing.
Market Restraints
- High Implementation Cost:The substantial upfront capital investment required for whole slide imaging scanners, high-capacity servers, and network infrastructure remains a primary barrier for smaller independent laboratories and hospitals.
- Data Storage Burdens:High-resolution digital slides generate enormous data files, creating significant challenges and costs related to long-term storage, archival, and data lifecycle management for pathology departments.
- Interoperability Gaps:A lack of universal standards between different vendors' scanner file formats and image management software creates vendor lock-in and complicates the creation of integrated, multi-site pathology networks.
Strategic Opportunities
- Predictive and Prognostic AI:Moving beyond simple diagnostic assistance, AI algorithms present an opportunity to provide prognostic information and predict patient response to specific therapies, adding significant clinical value.
- Expansion in Emerging Economies:Markets in countries like Brazil and India represent significant growth potential as healthcare spending increases and laboratory infrastructure undergoes modernization, creating demand for digital solutions.
- Multi-Omics Data Integration:There is a clear opportunity to combine digital pathology image data with genomic and proteomic information, creating integrated diagnostic platforms for a holistic view of disease.
Industry Challenges
- Pathology Informatics Skill Gap:A shortage of personnel with hybrid expertise in pathology, computer science, and data management hinders the effective implementation and maintenance of complex digital pathology systems.
- Legacy System Integration:Integrating new digital pathology platforms with existing, often outdated, Laboratory Information Systems (LIS) and hospital-wide Electronic Health Records (EHR) is a major technical and operational hurdle.
- Regulatory Pathway Complexity:Navigating the stringent requirements of regulations like the EU's IVDR for software as a medical device demands extensive validation and documentation, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Pathology Systems Market |
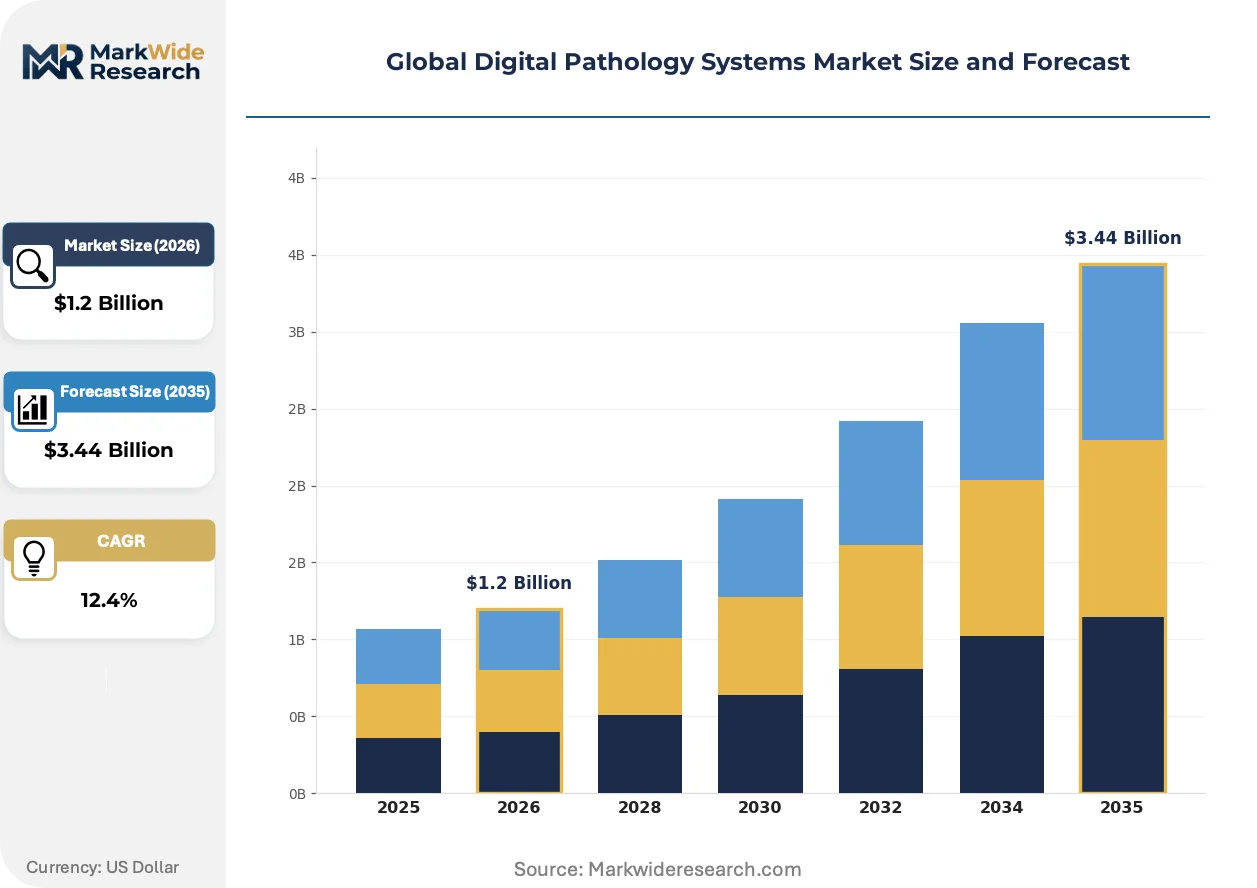
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.44 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Slide Imaging, Digital Microscopes, Image Management Software, Automated Slide Scanners, Visualization Tools Technology: Cloud-Based Platforms, Artificial Intelligence, Machine Learning, Image Analysis, Data Storage Solutions Application: Oncology Diagnostics, Research & Development, Drug Discovery, Education & Training, Teleconsultation End User: Pharmaceutical Companies, Academic Institutions, Diagnostic Laboratories, Biotechnology Firms, Government Research Centers |
| Companies Covered | Koninklijke Philips N.V., Olympus Corporation, Proscia, Hamamatsu Photonics K.K., Visiopharm A/S, Danaher Corporation (Leica Biosystems), PathAI, 3DHISTECH Ltd., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Pathology Systems Market Strategic Shifts & Innovations
The market's value proposition is shifting from hardware-centric sales of scanners to software-driven, enterprise-level data management solutions. This evolution is driven by the capabilities of cloud computing and the increasing sophistication of AI-powered analytical tools, which are becoming the core of modern pathology operations.
Multiplex immunofluorescence imaging allows for the simultaneous detection and spatial analysis of numerous biomarkers within a single tissue sample. Pharmaceutical companies and contract research organizations are rapidly adopting this technique to dissect the complex tumor microenvironment in immuno-oncology studies. The ability to overlay this rich biomarker data onto a digital whole slide image is electrifying the development of companion diagnostics and spatially-informed biological research.
Europe's In Vitro Diagnostic Regulation (IVDR) establishes a more rigorous regulatory framework for all diagnostic products, including software. Its implementation directly impacts digital pathology vendors by requiring more extensive clinical evidence, risk management documentation, and post-market surveillance to achieve and maintain CE marking. The regulation particularly affects AI-based software intended for primary diagnosis, compelling developers to conduct robust clinical performance studies to prove safety and efficacy.
A clear behavioral shift sees large healthcare organizations procuring enterprise-wide imaging platforms rather than individual departmental systems. This model favors cloud-hosted, subscription-based software that can be scaled across multiple hospitals and laboratories, disrupting the traditional one-time capital equipment sale. This trend is most visible in integrated delivery networks in the United States, which seek to centralize pathology services and enable remote consultations.
Global Digital Pathology Systems Market Segmentation
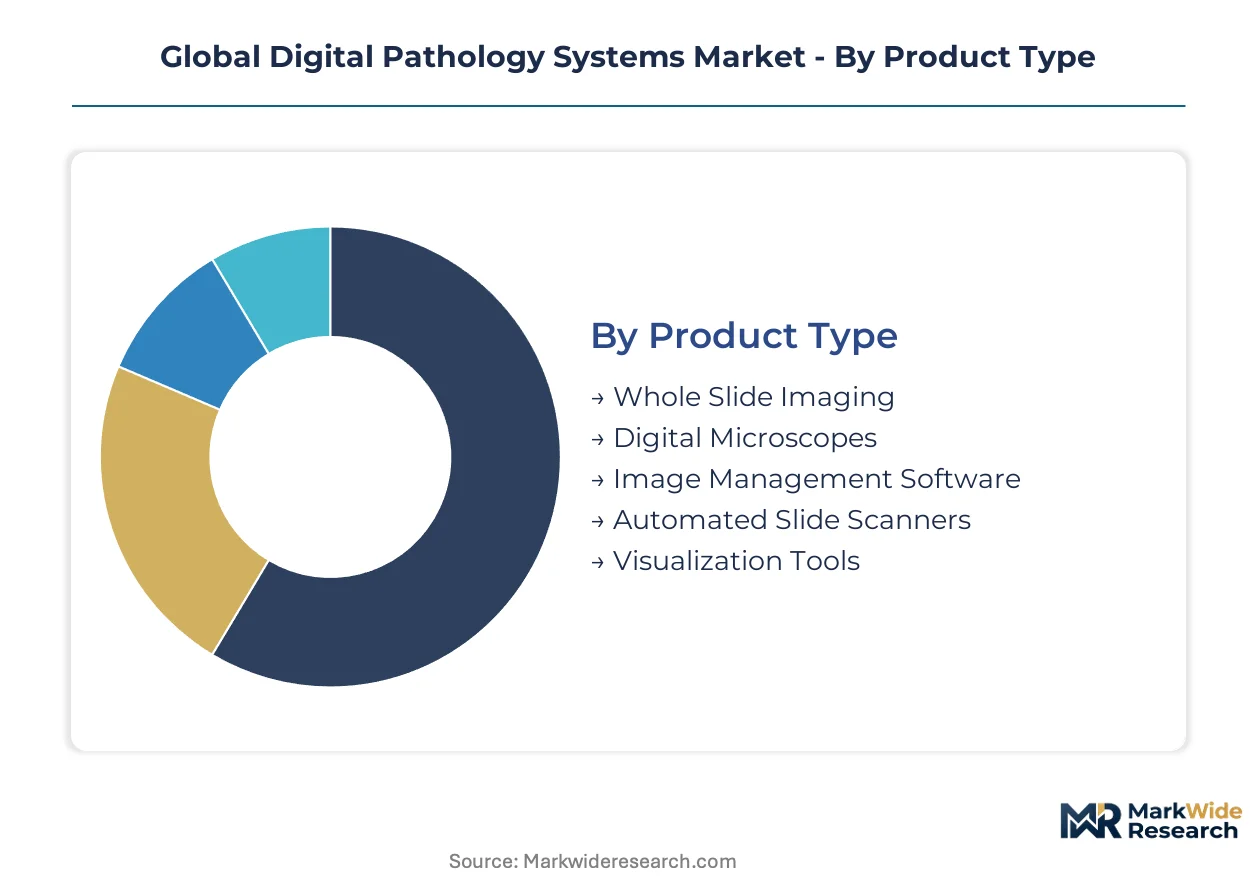
Understanding the Global Digital Pathology Systems Market requires a detailed segmentation to identify specific demand patterns and technological influences. This analysis dissects the market by product type, underlying technology, primary application areas, and diverse end-user profiles. Each segment illuminates distinct value propositions.
Product Type:
Product types range from standalone hardware components to deeply integrated software solutions that form laboratory operational backbones. These offerings cater to various levels of digitization, from image acquisition to advanced data management.
- Whole Slide Imaging:High-throughput scanners convert physical glass slides into high-resolution digital images for foundational datasets. Developed markets like the United States drive demand, spurred by laboratory digitization and remote diagnostics.
- Image Management Software:This software forms the central repository and workflow engine for digital pathology images, enabling efficient storage and sharing. Integrated delivery networks concentrate demand for robust, cloud-hosted image management solutions.
- Digital Microscopes:These devices capture live digital images from glass slides, offering localized viewing for pathologists.
- Automated Slide Scanners:High-volume laboratories utilize these systems to automatically load, scan, and offload multiple slides.
- Visualization Tools:Software applications provide interactive viewing and manipulation of digital whole slide images.
Volume placements concentrate in Whole Slide Imaging scanners; faster expansion belongs to Image Management Software platforms.
Technology:
Technological underpinnings deliver distinct value propositions, enhancing diagnostic capabilities and operational efficiency. These innovations transform how pathological data is processed, analyzed, and managed.
- Artificial Intelligence:AI algorithms apply machine learning to whole slide images, providing quantitative analysis, enhancing diagnostic accuracy, and identifying patterns. Pharmaceutical companies invest in AI for predictive and prognostic insights.
- Cloud-Based Platforms:Scalable, secure infrastructures host digital pathology data and applications, enabling remote access, collaborative workflows, and multi-site integration. Integrated delivery networks prioritize cloud solutions for centralized pathology services.
- Machine Learning:A subset of AI, it enables systems to learn from image datasets, refining diagnostic algorithms.
- Image Analysis:This technology extracts quantitative data from digital images, measuring features like cell morphology and tissue architecture.
- Data Storage Solutions:High-capacity, secure storage systems manage immense digital pathology image volumes.
Artificial Intelligence drives new capabilities, while Cloud-Based Platforms ensure foundational support for scalable operations.
Application:
Digital pathology systems address a spectrum of clinical and scientific needs, with each application benefiting from enhanced precision, efficiency, and collaborative potential. These diverse uses highlight the technology's broad utility.
- Oncology Diagnostics:Digital pathology provides high-precision image analysis for cancer diagnosis, staging, and treatment planning, supporting biomarker quantification. Developed markets like the United States prioritize this application for precision oncology.
- Research & Development:Researchers utilize digital pathology for quantitative analysis of tissue samples, accelerating disease understanding and biomarker identification. Academic institutions leverage these systems for advanced scientific investigations.
- Drug Discovery:Pharmaceutical companies employ digital pathology to analyze tissue responses in trials, aiding drug efficacy.
- Education & Training:Digital slides offer accessible, standardized teaching material for pathology residents and students.
- Teleconsultation:Pathologists use digital systems to share cases remotely for second opinions.
Clinical necessity drives growth in Oncology Diagnostics; long-term development is sustained by Research & Development initiatives.
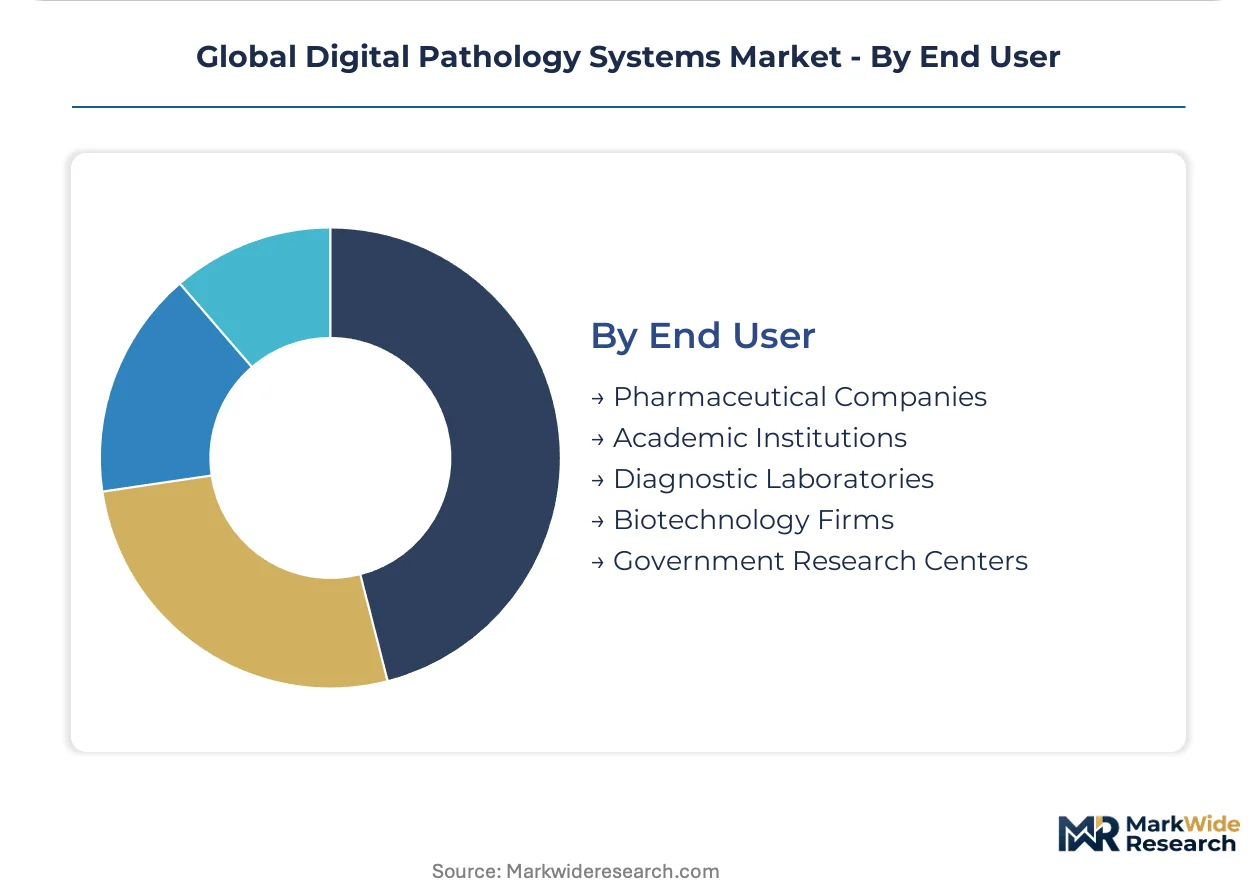
End User:
Adoption of digital pathology systems varies across end-user organizational structures, each driven by unique operational requirements and strategic objectives. These entities enhance their specific diagnostic, research, or commercial workflows.
- Diagnostic Laboratories:These entities, including hospital and independent reference labs, are primary adopters for routine clinical diagnosis, workflow efficiency, and remote services. Lab consolidation in Germany accelerates investment in scalable digital solutions.
- Pharmaceutical Companies:Drug developers integrate digital pathology into discovery and development pipelines for preclinical toxicology, clinical trial analysis, and companion diagnostic development. They seek advanced AI solutions for quantitative biomarker analysis.
- Academic Institutions:Universities and teaching hospitals utilize digital pathology for research, medical education, and diagnostic services.
- Biotechnology Firms:These companies leverage digital pathology for specialized research, biomarker discovery.
- Government Research Centers:Publicly funded research organizations employ digital pathology for large-scale studies and public health initiatives.
Procurement volume is highest among Diagnostic Laboratories, with Pharmaceutical Companies exhibiting rapid investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for digital pathology systems concentrates significantly in developed healthcare markets, driven by the push for diagnostic precision and efficiency. These regions are rapidly digitizing laboratory infrastructure to support advanced medical applications. Emerging economies also present substantial growth potential as healthcare spending increases and infrastructure modernizes.
United States
Demand for digital pathology systems in the United States is driven by the need for precision oncology diagnostics and the expansion of integrated delivery networks. The FDA's landmark clearances for primary diagnostic use have legitimized broader clinical adoption. Major academic medical centers and large hospital systems in areas like Boston and Houston are centralizing pathology services and enabling remote consultations.
Germany
Germany's digital pathology market experiences strong demand from laboratory consolidation and the push for networked solutions to balance workloads. Compliance with the In Vitro Diagnostic Regulation (IVDR) and CE marking is mandatory for market entry, ensuring high standards. Major diagnostic laboratories in regions such as North Rhine-Westphalia are actively investing in scalable digital solutions for enhanced efficiency.
India
India represents significant growth potential for digital pathology systems as healthcare spending rises and laboratory infrastructure undergoes modernization. The country's national pharmaceutical regulator is increasingly focusing on quality standards for diagnostic tools. Major metropolitan areas like Mumbai and Bangalore are seeing new investments in advanced digital pathology labs to support growing diagnostic needs.
Brazil
Brazil's market for digital pathology systems is expanding due to increasing investment in healthcare technology and the need for improved diagnostic access across vast geographies. ANVISA, the national health surveillance agency, regulates medical devices and software, influencing market entry. Public and private hospitals in São Paulo and Rio de Janeiro are adopting digital solutions to enhance diagnostic capabilities and remote consultation.
Japan
Japan exhibits steady demand for digital pathology systems, supported by an aging population and a strong focus on advanced medical technologies. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous regulatory oversight for diagnostic devices. Leading research institutions and university hospitals in Tokyo and Osaka are integrating AI-driven image analysis for oncology and precision medicine research.
Global Digital Pathology Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the digital pathology market, reflecting varying levels of vertical integration. The market structure appears tiered, with established medical imaging giants alongside agile, software-focused innovators. Archetypes include integrated solution providers offering end-to-end workflows, AI-driven analytics specialists, and dedicated high-throughput scanner manufacturers. Dominant competitive moves involve strategic partnerships to ensure system interoperability and continuous portfolio diversification into advanced AI-powered applications and cloud platforms.
Specialists in AI-driven software platforms, such as Proscia, exemplify the market's shift towards enterprise-wide pathology operations, focusing on advanced analytical capabilities and enterprise solutions. These firms develop sophisticated algorithms for quantitative image analysis and seamless data management across institutions. Koninklijke Philips N.V. occupies a position as an integrated solution provider, leveraging its extensive background in clinical informatics and medical imaging to offer comprehensive digital pathology solutions that span hardware and software. Danaher Corporation, through its Leica Biosystems subsidiary, anchors the full workflow segment, providing robust solutions from tissue processing to high-resolution digital scanning, illustrating a vertically integrated approach to laboratory digitization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Olympus Corporation |
| Proscia |
| Hamamatsu Photonics K.K. |
| Visiopharm A/S |
| Danaher Corporation (Leica Biosystems) |
| PathAI |
| 3DHISTECH Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Cost & Logistics Intelligence
Specialized semiconductor component pricing influences the capital expenditure for digital pathology scanners, cascading into tiered system costs. This affects the overall pricing structure for integrated hardware and software solutions.
Pricing Analysis
Volume sales of digital pathology hardware carry lower margins compared to high-value, recurring software subscriptions. Pricing stratifies across premium, standard, and economy tiers based on scanner resolution and software analytical capabilities. Pricing softness for basic hardware stems from increasing competition and manufacturing efficiencies. Smaller independent laboratories exhibit the highest price sensitivity, while large hospital systems prioritize comprehensive, integrated solutions.
Supply Chain Analysis
Dual-sourcing requirements for critical components like high-resolution image sensors and specialized optical lenses mitigate supply chain risks for digital pathology system manufacturers. Supply concentrates in East Asian nations for semiconductor fabrication and European countries for precision optical engineering. The industry relies on high-capacity data storage solutions and robust server infrastructure. Single-source vulnerability for certain advanced components remains a structural risk. Distribution runs through direct sales channels to large healthcare networks and specialized distributors for smaller laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global digital pathology systems market is navigating a significant technology-transition phase, as Artificial Intelligence-driven image analysis displaces manual microscopic review. This shift enables new diagnostic precision and operational efficiency across laboratories.
For Market Incumbents: Deepen existing clinical informatics and medical imaging portfolios by acquiring agile AI software specialists. This counters the threat posed by software-focused innovators who challenge traditional hardware sales. Invest in robust clinical validation for AI algorithms to secure broader regulatory approvals like FDA clearances. Focus on creating seamless, vendor-agnostic workflows to enhance user adoption and reduce interoperability gaps.
For New Entrants and Emerging Players: Specialized software integrators can target underpenetrated diagnostic laboratories in emerging economies by offering cloud-native, subscription-based AI solutions. Focus on developing predictive and prognostic AI algorithms for specific oncology biomarkers, adding significant clinical value beyond basic diagnostics. Forge strategic partnerships with established hardware manufacturers to ensure interoperability and broader market access. This approach allows agile entry into high-growth application areas.
For Investors and Strategic Acquirers: Distressed-cycle entries favor well-capitalized integrated solution providers in developed healthcare markets aiming to consolidate technology. Long-term viability rests on platforms that can integrate multi-omics data with AI-driven image analysis for precision medicine. Target AI-driven software platforms with robust clinical evidence and a clear regulatory pathway, particularly those specializing in oncology. The signal to watch is the acceleration of FDA and IVDR clearances for AI software as a primary diagnostic tool.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch Predictive AI Diagnostic Software | This initiative expands clinical value by offering prognostic insights for oncology patients. |
| Form Interoperability Partnerships | These alliances ensure seamless data exchange between diverse scanner and software platforms. |
| Acquire AI Analytics Innovator | Acquiring specialized firms enhances a company's advanced image analysis capabilities. |
| Pursue Global Regulatory Clearances | Achieving FDA and IVDR approvals legitimizes AI for primary diagnostic use worldwide. |
| Expand into Emerging Economies | This move taps into new patient populations and modernizing laboratory infrastructures in India and Brazil. |
Research Approach
Independent corroboration across regulatory filings, scientific publications, and company financial reports underwrites the qualitative findings of this study. Primary interviews with pathologists, laboratory directors, and medical imaging engineers provided granular insights into market dynamics. This approach combined top-down market sizing with bottom-up validation from industry stakeholders. Secondary research validated primary data points across diverse information sources.
Historical data from comparable periods anchored the forecast window, establishing a robust baseline for projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, underlying technology, application areas, and end-user profiles. Compound annual growth rates derived from historical trends and projected growth drivers informed future market expansion. AI adoption rates and regulatory approval timelines served as key industry-specific forecast inputs.
Caveats apply where unforeseen regulatory changes or disruptive technological breakthroughs could materially shift the outlook for digital pathology systems. Forecasts reflect assumptions regarding market evolution and macroeconomic stability. Deviation in AI integration patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Saudi Arabia Respiratory Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Laryngeal Masks Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Global Portable Oxygen Concentrators Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Gamma Knife Market
Medical Devices
Global Biliary Stents Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Global Photobiostimulation Market