
 Global Biliary Stents Market | 2026-2036
Global Biliary Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biliary Stents Market Foresight
Ambulatory surgery center preference is hardening across mature healthcare systems as payors bundle reimbursement for outpatient biliary interventions. Boston Scientific Corporation leverages its integrated endoscopy and interventional radiology portfolio to dominate hospital purchasing committees. Cook Medical anchors its position through specialized manufacturing scale in custom-configured plastic stent geometries.
Biliary stents are tubular prosthetic devices, typically constructed from polyethylene, polyurethane, or nitinol alloys, designed to maintain patency within the bile duct lumen following obstructive pathologies or iatrogenic strictures. Metal stents occupy the premium tier where malignant obstruction cases require sustained radial force and longer indwell times. Plastic stents compete aggressively on cost in benign stricture management where exchange intervals remain shorter.
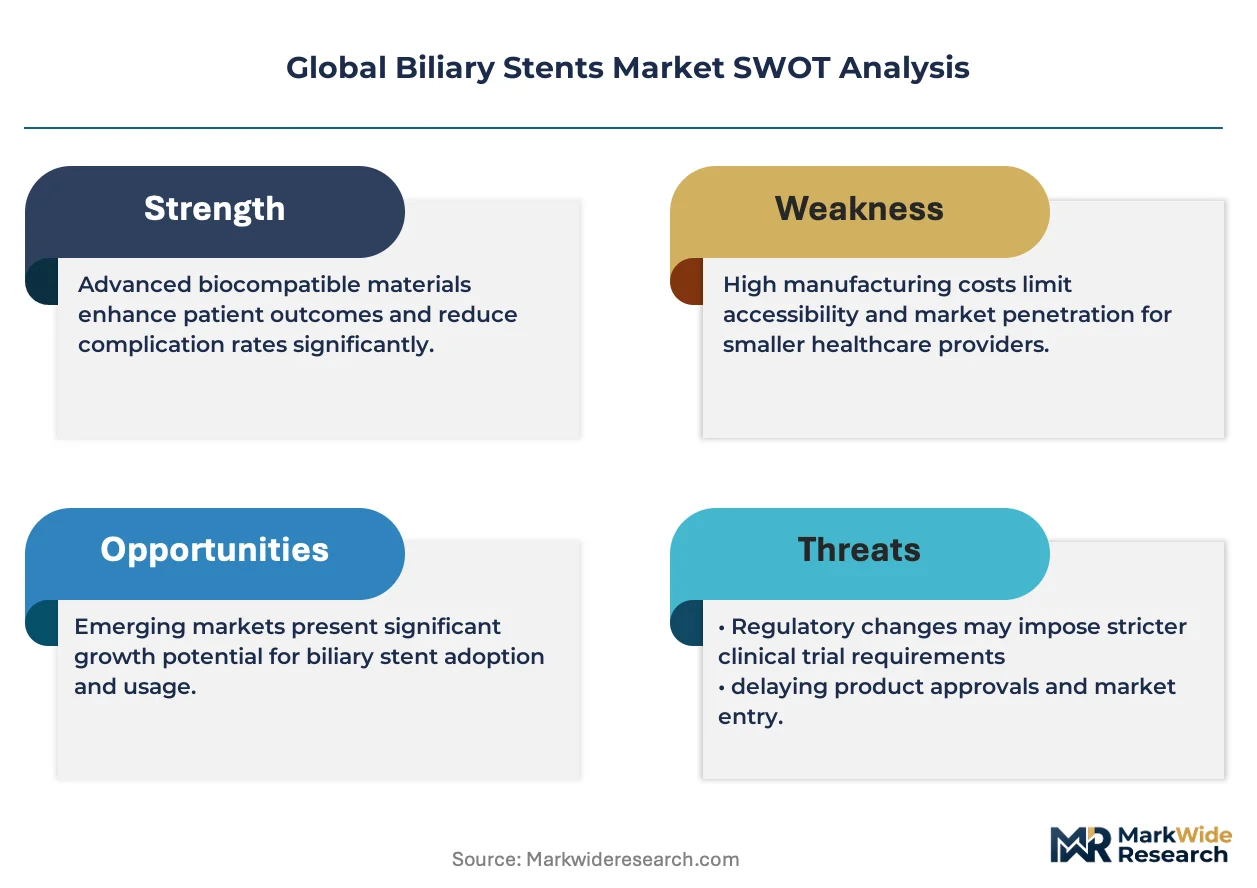
FDA 510(k) clearance pathways and EU MDR clinical evaluation requirements shape product development timelines and market access costs for manufacturers targeting both jurisdictions. Japan's PMDA enforces distinct biocompatibility testing protocols that delay entry for firms lacking prior Asian regulatory experience. Stakeholders must monitor how evolving CMS outpatient procedure codes and parallel European DRG revisions redistribute volume across inpatient and ambulatory settings.
Market Dynamics
Reimbursement bundling for outpatient procedures is compressing hospital inpatient volumes and accelerating ambulatory surgery center capacity expansion across United States, Germany, and Japan healthcare networks.
Growth Catalysts
- CMS Outpatient Procedure Codes:Bundled payment structures incentivize same-day biliary interventions, shifting procedure volume from inpatient suites to ambulatory surgery centers in the United States.
- Nitinol Alloy Advances:Superelastic nickel-titanium compositions enable thinner strut designs with sustained radial force, extending indwell intervals for malignant obstruction management.
- Japan's Aging Demographics:Population over 65 exceeds 29 percent, sustaining elevated incidence of biliary malignancies and recurrent stone disease requiring recurrent stenting.
Market Restraints
- Noble Metal Input Costs:Nitinol production depends on nickel and titanium spot markets, exposing manufacturers to volatility in raw material procurement budgets.
- EU MDR Clinical Evidence Requirements:Metallic stent manufacturers face expanded predicate-device comparison studies and post-market surveillance obligations, lengthening approval timelines.
- Plastic Stent Substitution:Polyethylene and polyurethane alternatives dominate benign stricture protocols where exchange intervals remain short and cost sensitivity is acute.
Strategic Opportunities
- India's Underserved Tier-2 Cities:Interventional gastroenterology infrastructure is expanding beyond Mumbai and Delhi into secondary urban centers with limited stent placement capacity.
- Biodegradable Polymer Convergence:Magnesium alloy scaffolds combined with polylactic acid coatings promise complete resorption, eliminating retrieval procedures for benign indications.
- Japan PMDA Sakigake Pathway:Expedited review designation for novel stent designs with demonstrated superiority over predicate devices accelerates market entry for innovative entrants.
Industry Challenges
- Interventional Radiologist Training Pipeline:Specialized fellowship programs in biliary intervention remain concentrated at academic medical centers, constraining workforce expansion.
- EU MDR Technical Documentation:Compilation of clinical evaluation reports and quality management system audits demands dedicated regulatory affairs personnel and extended preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biliary Stents Market |
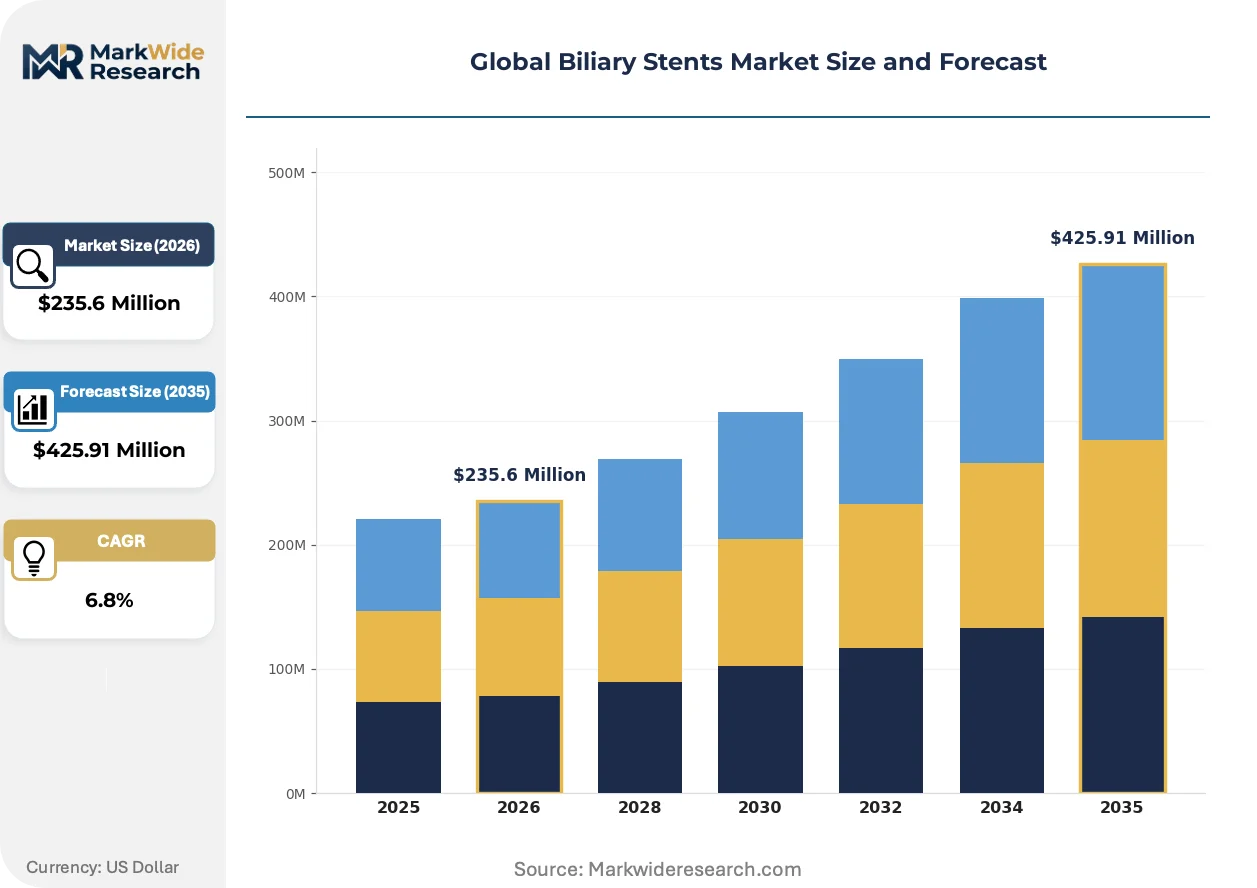
| Market Size in 2026 | $235.6 Million |
| Market Size in 2035 | $425.91 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Stents, Metal Stents, Covered Stents, Uncovered Stents Therapy Area: Malignant Obstruction, Benign Strictures, Post-Surgical Complications, Pancreatitis Management End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Centers Deployment: Elective Procedures, Emergency Interventions, Outpatient Settings, Inpatient Settings |
| Companies Covered | Boston Scientific Corporation, Cook Medical, CONMED Corporation, Medtronic plc, Olympus Corporation, Becton, Dickinson and Company, Merit Medical Systems, Cardinal Health, TAEWOONG Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biliary Stents Market Shifts & Advancements
Material science breakthroughs and regulatory pathway adaptations are compressing product development cycles while reimbursement redesign reshapes where procedures occur.
Drug-eluting biliary stent platforms is rewriting competitive positioning in malignant obstruction care. Academic medical centers in Germany and Japan are piloting sirolimus-coated nitinol designs to suppress neointimal hyperplasia. The technology is rewriting expected patency intervals and challenging conventional metal stent replacement protocols.
EU MDR Article 61 clinical evaluation requirements are elevating evidence thresholds for metallic stent re-certifications. Manufacturers must now submit systematic literature reviews and post-market clinical follow-up data where 510(k) predicates previously sufficed. Smaller European notified bodies are withdrawing from device certification, concentrating review capacity among residual organizations.
Ambulatory surgery centers are capturing biliary stent placement volume previously reserved for hospital inpatient departments. United States payor contracts now bundle physician and facility fees for outpatient ERCP procedures, compressing per-case revenue but accelerating patient throughput. Gastroenterology groups are consolidating into multi-site platforms to negotiate favorable payer rates.
Global Biliary Stents Market Segmentation
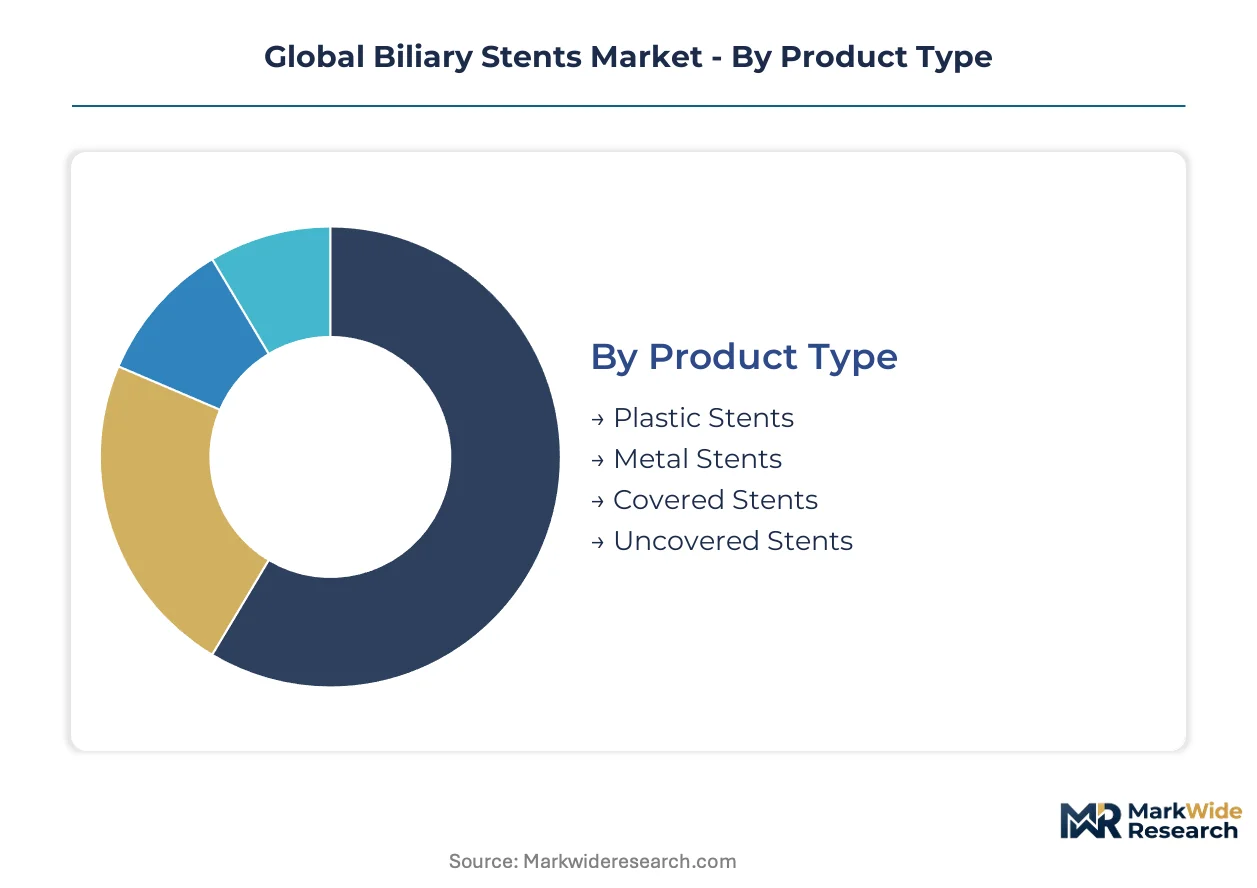
Biliary stent purchasing decisions split across material specifications, clinical indication severity, and site-of-service economics. Manufacturers must align product portfolios with distinct reimbursement pathways and intervention workflows that vary sharply between malignant and benign patient populations.
Product Type:
Material composition and structural design determine radial force, indwell duration, and retrieval requirements across the stent portfolio.
- Metal Stents:Nitinol alloy construction delivers superelastic radial force for malignant biliary obstruction cases requiring sustained patency. Demand concentrates in United States academic medical centers and German oncology networks where longer indwell intervals reduce reintervention burden.
- Plastic Stents:Polyethylene and polyurethane formulations enable cost-effective short-term drainage for benign stricture protocols. Exchange intervals remain brief, driving volume in Japan's high-throughput endoscopy centers where procedure frequency offsets lower per-unit pricing.
- Covered Stents:Polymer membrane barriers prevent tumor ingrowth and tissue hyperplasia in complex malignant presentations.
- Uncovered Stents:Open mesh designs facilitate epithelialization and stable anchoring in native duct anatomy.
Mature deployment sits with plastic stents in high-volume benign protocols. Newer deployment is concentrated in covered metal platforms for complex oncologic interventions.
Therapy Area:
Clinical indication severity dictates stent selection criteria, exchange protocols, and reimbursement coding intensity.
- Malignant Obstruction:Pancreatic, cholangiocarcinoma, and metastatic disease presentations require durable palliation with metal stent platforms. United States CMS bundled payments and German DRG structures prioritize single-procedure durability over serial plastic stent exchanges.
- Benign Strictures:Post-inflammatory, ischemic, or anastomotic strictures respond to temporary stenting with scheduled retrieval. Japan's aging biliary stone disease population sustains recurrent procedural demand in this category.
- Post-Surgical Complications:Iatrogenic bile duct injury and leak management requires tailored stent configurations.
- Pancreatitis Management:Pancreatic duct disruption and pseudocyst drainage applications represent specialized interventional scenarios.
Revenue concentration aligns with malignant obstruction cases. Procedure volume expansion is climbing the fastest in post-surgical complication management as hepatobiliary surgery volumes rise.
End User:
Site-of-care economics and capital equipment requirements fragment the customer base across facility types.
- Hospitals:Inpatient suites and interventional radiology departments manage complex cases requiring anesthesia support and intensive care backup. Germany's university hospital networks anchor metal stent utilization for oncologic multidisciplinary care.
- Ambulatory Surgery Centers:Freestanding endoscopy facilities capture elective ERCP volume under bundled reimbursement structures. United States payor contracts now favor same-day discharge protocols that bypass hospital facility fees.
- Specialty Clinics:Gastroenterology group practices with in-house endoscopy suites serve routine biliary interventions.
- Diagnostic Centers:Imaging-affiliated facilities provide preliminary assessment and referral coordination.
Capital intensity favors hospital-based deployment for complex metal stent cases. Volume migration is accelerating most quickly toward ambulatory surgery centers as reimbursement redesigns take hold.
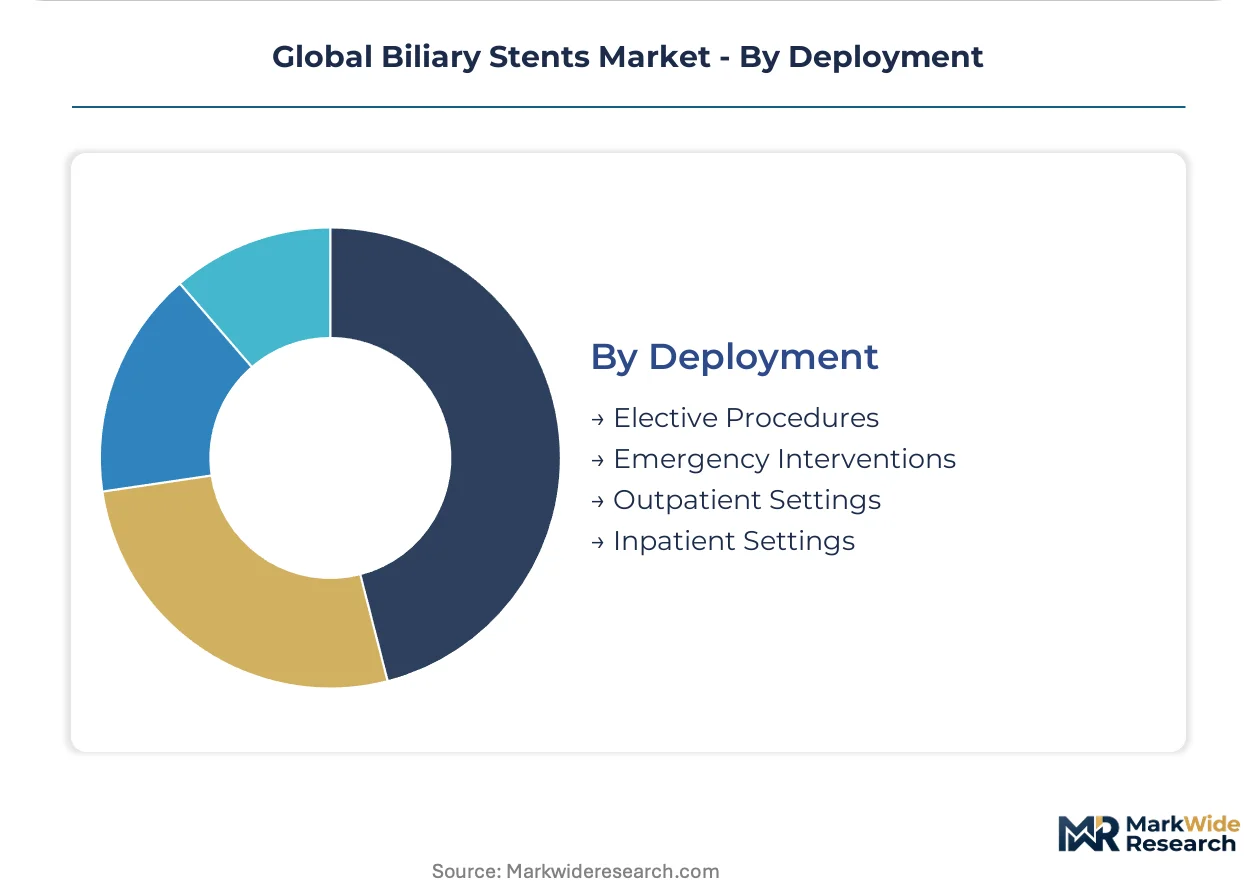
Deployment:
Scheduling urgency and care setting determine resource allocation and reimbursement capture.
- Elective Procedures:Scheduled ERCP interventions for stable biliary strictures or preoperative drainage optimize ambulatory surgery center utilization. Japan's dense urban endoscopy networks minimize wait times for non-urgent cases.
- Emergency Interventions:Acute cholangitis, sepsis, and complete obstruction demand immediate decompression through available inpatient capacity. United States hospital emergency departments retain this volume regardless of reimbursement differentials.
- Outpatient Settings:Same-day discharge protocols require streamlined recovery observation.
- Inpatient Settings:Overnight admission supports complex cases and comorbid patient populations.
Emergency deployment remains tethered to hospital infrastructure. Elective deployment is expanding most quickly in outpatient configurations as clinical confidence in same-day protocols hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of nitinol alloys and polymer formulations clusters in Germany, Japan, and the United States, while procedure consumption concentrates in aging healthcare systems with established interventional networks. This geographic split shapes trade flows and regulatory prioritization across the value chain.
United States
FDA 510(k) clearance pathways and CMS bundled outpatient reimbursement codes sustain high-volume ambulatory surgery center deployment. Boston Scientific Corporation and Cook Medical anchor domestic manufacturing capacity in Massachusetts and Indiana. Interventional gastroenterology networks in the Northeast and Midwest corridor drive metal stent utilization for malignant obstruction protocols.
Germany
EU MDR clinical evaluation requirements and DRG reimbursement structures prioritize durable metal stent platforms over serial plastic exchanges. University hospital networks in Bavaria and North Rhine-Westphalia concentrate oncologic multidisciplinary care. EMA-notified bodies in Berlin and Munich handle metallic stent re-certifications under tightened post-market surveillance obligations.
Japan
PMDA biocompatibility testing protocols and the Sakigake expedited review pathway shape market entry timelines for novel designs. Population over 65 exceeds 29 percent, sustaining elevated biliary malignancy incidence. Tokyo and Osaka metropolitan areas host dense endoscopy networks with high-throughput plastic stent exchange protocols for benign stone disease.
India
CDSCO medical device registration requirements and expanding PLI scheme incentives attract contract manufacturing investment. Tier-2 cities beyond Mumbai and Delhi lack interventional gastroenterology infrastructure. Hyderabad and Chennai clusters are emerging as distribution hubs for imported metal and plastic stent platforms.
South Korea
MFDS regulatory harmonization with international standards accelerates approval timelines for predicate-device stent platforms. MFDS-designated medical device innovation centers in Seoul and Daegu support local manufacturing scale-up. Aging demographics and universal health coverage sustain procedure volume growth in the Seoul Capital Area.
Global Biliary Stents Market Competitive Landscape
Top-tier vendors anchor hospital purchasing committees through integrated endoscopy and interventional radiology portfolios, while mid-tier specialists compete on custom-configured plastic stent geometries and regional regulatory expertise. The vendor base stratifies across three archetypes: diversified medtech conglomerates with full-suite interventional platforms, specialized stent manufacturers with dedicated biliary focus, and regional fabricators serving price-sensitive procurement channels. Consolidation pressure intensifies through strategic partnerships between device makers and ambulatory surgery center networks, alongside technology licensing agreements for drug-eluting stent coatings.
Among diversified medtech conglomerates, Boston Scientific Corporation and Medtronic plc occupy positions spanning endoscopy, interventional radiology, and surgical portfolios. Cook Medical exemplifies the specialized manufacturer archetype with concentrated expertise in custom-configured stent geometries. TAEWOONG Medical represents regional fabrication scale serving Asia-Pacific procurement channels.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| CONMED Corporation |
| Medtronic plc |
| Olympus Corporation |
| Becton, Dickinson and Company |
| Merit Medical Systems |
| Cardinal Health |
| TAEWOONG Medical |
| Others |
Supply & Pricing Matrix
Metal-plastic stent bifurcation separates premium nitinol platforms commanding sustained radial force premiums from commodity polyethylene alternatives competing on per-unit cost. This material divergence manifests in procurement strategies across United States ambulatory surgery centers and German university hospitals, where reimbursement bundling compresses plastic stent margins while supply chains for nitinol alloys concentrate in specialized metallurgy clusters.
Pricing Analysis
Short lead-time premiums for emergency metal stent deployment contrast with volume discounts for scheduled plastic stent exchanges in high-throughput Japanese endoscopy networks. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, nitinol alloy grade, and covered versus uncovered mesh configurations. Cost compression in plastic stent tiers is intensifying because polyethylene spot pricing volatility and ambulatory surgery center procurement consolidation. Hospital purchasing committees demonstrate lowest price sensitivity for malignant obstruction metal platforms, while Indian tier-2 city clinics exhibit acute cost responsiveness in benign stricture protocols.
Supply Chain Analysis
Workforce availability constraints in Massachusetts and Indiana nitinol processing facilities limit superelastic alloy fabrication scale for North American demand. Nitinol production draws from nickel and titanium feedstock dependencies anchored in Australian mining operations and Ukrainian titanium sponge processing. Single-source vulnerability permeates specialized nitinol wire drawing capabilities concentrated among limited European and Japanese metallurgy houses. Distribution runs through hospital-centered GPO contracts in the United States, direct university hospital procurement in Germany, and dense metropolitan endoscopy distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biliary stents market sits in a technology-transition phase as drug-eluting nitinol platforms displace conventional bare-metal stents in malignant obstruction care. Sirolimus-coated designs are rewriting patency interval expectations and challenging established replacement protocols across United States academic medical centers and German oncology networks.
For Market Incumbents: Deploy backward integration into nitinol alloy sourcing to buffer nickel spot price volatility and secure superelastic wire supply. Cook Medical anchors position through captive manufacturing of custom-configured plastic stent geometries, while Boston Scientific Corporation leverages integrated endoscopy portfolios to dominate hospital purchasing committees. Counter drug-eluting entrant threats by accelerating FDA submission timelines for coated platforms and locking ambulatory surgery center networks through multi-year GPO contracts. For New Entrants and Emerging Players: Enter via India's underserved tier-2 cities where interventional gastroenterology infrastructure expansion outpaces established distributor coverage. Hyderabad and Chennai distribution hubs offer white-space penetration before Mumbai and Delhi saturation hardens. Target biodegradable polymer convergence segments where magnesium alloy scaffolds promise complete resorption and elimination of retrieval procedures. Pursue Japan PMDA Sakigake expedited review pathway for novel stent designs demonstrating superiority over predicate devices. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medtech conglomerates seeking interventional radiology portfolio gaps. Long-term viability favors specialized manufacturers with dedicated biliary focus and regulatory expertise across FDA 510(k) and EU MDR pathways. Watch drug-eluting stent patency data from German and Japanese academic pilot programs as inflection indicator for platform displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears pathway for nitinol alloy platforms in malignant obstruction protocols across United States academic networks. |
| CE Marking Pathway | Unlocks EU MDR-compliant market access for metallic stent re-certifications under tightened surveillance obligations. |
| Hospital System Partnership | Secures volume commitment from German university hospital networks prioritizing durable palliation over serial exchanges. |
| Software Companion Development | Enables procedure planning integration with endoscopy suites in Japan's high-throughput metropolitan centers. |
| Reimbursement Strategy | Aligns product positioning with CMS bundled outpatient codes shifting volume toward ambulatory surgery centers. |
Research Methodology
Multi-period observation of procedure volume migration, reimbursement code revisions, and nitinol alloy pricing anchored the trend analysis, supplemented by interviews with interventional gastroenterologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at metallic stent manufacturers. Secondary validation drew from FDA 510(k) filings, EMA notified body certification databases, CMS Medicare outpatient procedure data, and hospital procurement contract disclosures. Bottom-up demand modeling across patient indication severity and site-of-care economics triangulated against top-down market sizing from manufacturer revenue disclosures.
Input-output matrices mapped nitinol raw material flows through wire drawing, laser cutting, and surface coating fabrication stages against procedure demand across malignant obstruction, benign stricture, and post-surgical complication segments. Segmentation dimensions modeled included material composition, clinical indication severity, end-user facility type, and deployment urgency across the projection horizon. CAGRs derived from regression analysis of historical procedure volumes adjusted for demographic aging trajectories and reimbursement redesign impacts. Forecast inputs incorporated Japan's PMDA approval timelines and EU MDR clinical evaluation burden estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden nickel price spikes or accelerated biodegradable polymer platform adoption. Projections reflect assumptions about ambulatory surgery center capacity expansion rates, interventional radiologist fellowship pipeline growth, and regulatory pathway stability across FDA and EU MDR jurisdictions. Material deviation in nitinol supply disruptions, reimbursement bundling scope changes, or drug-eluting stent superiority trial outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Catheter Securement Devices Market
Medical Devices
Global Skin Grafting Device Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Cervical Dilators Market
Medical Devices
Blood Lancet Market
Medical Devices
Active Humidifier Devices Market
Medical Devices
India Artificial Organs and Bionics Market