
 Global Industrial Temperature Controller Market | 2026-2036
Global Industrial Temperature Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Temperature Controller Market Outlook
The split between premium precision controllers and commodity on-off units is rebalancing as semiconductor fabs and pharmaceutical lyophilization lines demand tighter set-point accuracy, while basic manufacturing tolerates wider dead bands. Siemens AG leverages its automation software stack to anchor premium positioning in process industries. Honeywell International Inc. competes through distributed control system integration across North American petrochemical complexes. RKC Instrument Inc. specializes in compact PID controllers for Japanese packaging machinery OEMs.
An industrial temperature controller is an electromechanical or solid-state device that measures process temperature through sensor input and modulates heating or cooling output to maintain a programmed set point, typically achieving stability within ±0.1°C in precision applications. These instruments serve as critical guardians of thermal uniformity in extrusion dies, bioreactors, and climate chambers where deviation risks product loss or safety failure. Digital technology segments command margin premiums through embedded self-tuning algorithms and multi-loop coordination, while analog installations persist in legacy infrastructure where replacement economics favor like-for-like swaps. IoT-enabled architectures are gaining traction in pharmaceutical cold chains, though wireless deployments remain constrained by electromagnetic interference protocols in heavy industrial settings.
The EU F-Gas Regulation and REACH framework constrain refrigerant choices and sensor material compositions, compelling redesigns of controller-integrated HVAC and refrigeration systems. FDA 21 CFR Part 11 and EMA GMP Annex 15 impose validation burdens on temperature recording in pharmaceutical manufacturing, favoring vendors with embedded audit-trail capabilities. IEC 61010-1 safety standards govern electrical isolation requirements, creating compliance moats for established players against low-cost entrants. Stakeholders must weigh the capital cost of controller upgrades against the operational risk of audit failures in regulated end-use environments.
Market Dynamics
Precision semiconductor fabrication in Taiwan and South Korea is compressing thermal tolerance windows from ±0.5°C to ±0.1°C, forcing controller architectures toward multi-loop PID coordination and embedded self-tuning algorithms that legacy analog installations cannot support.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential refrigerants are accelerating controller-integrated HVAC retrofits across European pharmaceutical cold chains, creating replacement demand for compatible thermal management systems.
- Semiconductor fabrication expansion:Taiwan and South Korean fabs are deploying precision controllers for EUV lithography thermal stabilization, where nanometer-scale pattern fidelity requires sub-0.1°C chamber uniformity.
- Bioreactor scale-up:Single-use bioprocessing vessels in contract manufacturing organizations now specify IoT-enabled controllers with embedded audit trails for FDA 21 CFR Part 11 compliance.
Market Restraints
- Platinum group metal volatility:RTD sensor elements depend on platinum wire whose price swings directly compress controller gross margins for mid-tier manufacturers.
- East Asian supply concentration:Shenzhen and Nagoya industrial zones produce over 70% of compact PID controller PCBs, exposing buyers to single-point geopolitical disruption risk.
- Analog legacy lock-in:Petrochemical complexes in the US Gulf Coast retain 4-20mA analog installations where replacement economics favor like-for-like swaps over digital migration.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO GMP enforcement is expanding temperature validation requirements for sterile injectable production, opening controller upgrade cycles in underpenetrated facilities.
- Edge-AI convergence:Self-optimizing PID algorithms running on ARM Cortex-M4 microcontrollers are enabling predictive thermal management without cloud dependency.
- Refrigerant transition services:Contractors bundling controller reprogramming with R-410A to R-32 conversions capture service revenue streams adjacent to hardware sales.
Industry Challenges
- Embedded firmware certification:IEC 61010-1 safety validation for self-tuning algorithms extends product launch timelines by 8-14 months versus fixed-parameter controllers.
- Interference-hardened wireless:Heavy industrial electromagnetic environments constrain IoT deployments, forcing redundant wired backhaul that negates installation cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Temperature Controller Market |
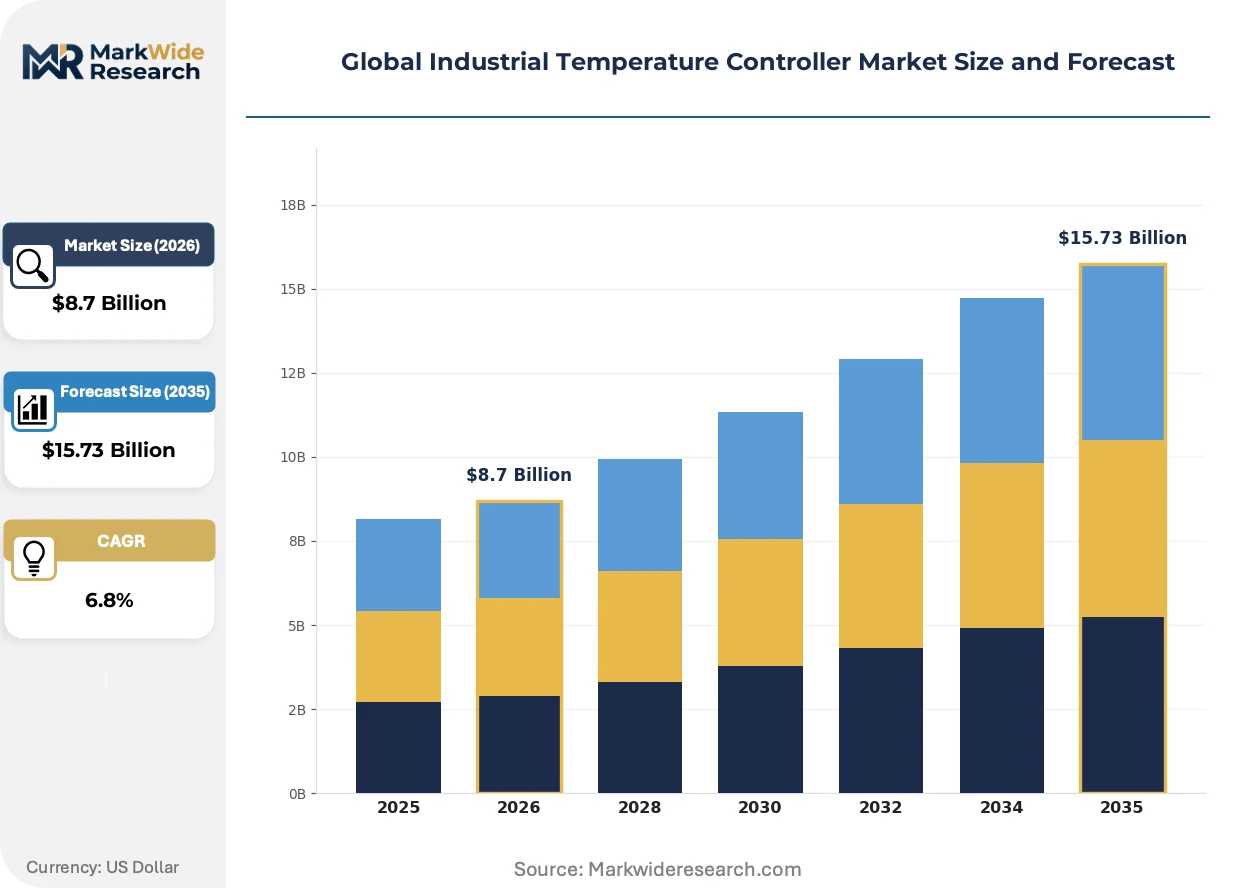
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, RTDs, Bimetallic Sensors, Infrared Sensors Technology: Analog, Digital, Wireless, IoT-Enabled End User: Manufacturing, Food & Beverage, Pharmaceuticals, HVAC Installation: Wall-Mounted, Panel-Mounted, Portable, Rack-Mounted |
| Companies Covered | ABB Ltd., Panasonic Corporation, Siemens AG, RKC Instrument Inc., Emerson Electric Co., Honeywell International Inc., Omron Corporation, Danfoss A/S, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Temperature Controller Market Strategic Shifts
Controller architectures are fragmenting along precision-grade lines as semiconductor and pharmaceutical buyers demand closed-loop coordination while commodity manufacturing tolerates wider dead bands. This bifurcation is compressing mid-tier vendor margins and rewarding automation software stacks that anchor premium positioning.
Multi-loop controller hardware is modularizing around standardized I/O backplanes that accept swappable thermocouple, RTD, and 4-20mA input cards. Pharmaceutical lyophilization line builders in Switzerland and Germany are adopting these platforms to reduce spare parts inventory. The approach is modularizing supplier relationships, allowing end-users to mix sensor vendors within unified control architectures.
REACH framework restrictions on lead-based solder and cadmium-plated sensor housings are compelling controller OEMs to redesign PCB assemblies and terminal blocks. Medical device manufacturers face EMA GMP Annex 15 validation burdens for any material change, slowing product refresh cycles. European temperature controller vendors are responding with pre-validated material declarations that transfer compliance burden to component suppliers.
Service unbundling is disrupting traditional controller distribution as pharmaceutical buyers separate hardware procurement from calibration and validation contracts. Third-party metrology laboratories in Massachusetts and North Carolina now capture recurring revenue streams that OEMs previously monopolized. This pattern is most visible in FDA-regulated sterile manufacturing where external audit-trail custody reduces liability exposure.
Global Industrial Temperature Controller Market Segmentation
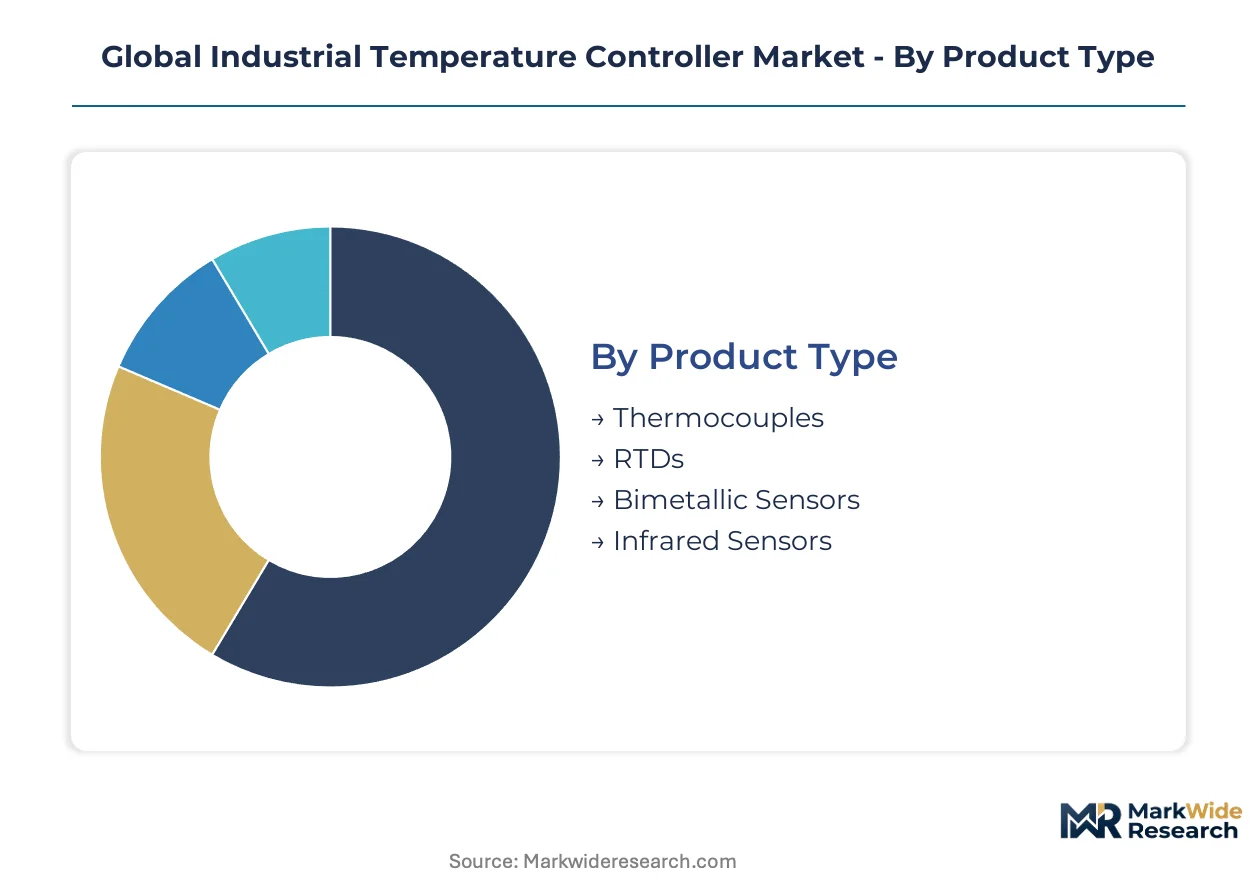
Industrial temperature controller segmentation reveals how capital deployment, regulatory exposure, and precision requirements reshape procurement patterns across sensor technologies and system architectures. Buyers in semiconductor fabrication and pharmaceutical manufacturing prioritize validation-ready digital platforms, while commodity process industries tolerate wider performance tolerances in analog installations.
Product Type:
Capital intensity varies sharply across sensor technologies, with platinum-based RTD systems demanding the highest upfront investment in calibration infrastructure and signal conditioning hardware.
- Thermocouples:Junction-based sensors spanning Type K, J, T, and N alloys deliver wide temperature range coverage from cryogenic to 1700°C. Demand concentrates in US Gulf Coast petrochemical complexes where Type K thermocouples monitor cracking furnace tubes under OSHA Process Safety Management requirements. Platinum group metal volatility in RTD alternatives reinforces thermocouple preference in sulfur-laden process streams.
- RTDs:Platinum wire-wound or thin-film elements achieve ±0.1°C stability essential for EUV lithography thermal chambers in Taiwanese and South Korean fabs. The platinum wire dependency exposes mid-tier controller OEMs to margin compression when spot prices spike, favoring long-term supply contracts with Johnson Matthey or Heraeus.
- Bimetallic Sensors:Mechanical coil-and-gear assemblies serve HVAC safety limit applications where electrical isolation is mandatory under IEC 61010-1.
- Infrared Sensors:Non-contact pyrometers monitor moving webs in German packaging lines without thermal mass interference.
RTDs absorb the bulk of installed capacity in precision manufacturing; infrared sensors are expanding most quickly in food safety inspection lines.
Technology:
Application criticality determines technology selection, with FDA-regulated pharmaceutical operations mandating digital audit trails that analog systems cannot provide.
- Analog:4-20mA loop-powered controllers with fixed PID parameters persist in legacy US Gulf Coast petrochemical infrastructure where replacement economics favor like-for-like swaps. These installations lack embedded diagnostics, forcing manual calibration cycles that digital platforms automate.
- Digital:Microprocessor-based units with self-tuning algorithms and multi-loop coordination dominate Swiss and German lyophilization equipment where EMA GMP Annex 15 validation requires embedded audit trails. ARM Cortex-M4 architectures enable edge-AI thermal prediction without cloud dependency.
- Wireless:IEEE 802.15.4 mesh networks face electromagnetic interference constraints in heavy industrial settings, limiting deployment to light manufacturing.
- IoT-Enabled:Cloud-connected controllers with predictive maintenance APIs serve pharmaceutical cold chains in Massachusetts and North Carolina where third-party metrology custody reduces liability exposure.
Digital platforms command the majority of new capital expenditure; IoT-enabled architectures are climbing the fastest in contract manufacturing organizations.
End User:
Customer type segmentation reflects divergent validation burdens, with pharmaceutical and food safety regulators imposing documentation requirements that manufacturing and HVAC buyers escape.
- Manufacturing:Discrete automation and process control applications span extrusion dies, injection molding barrels, and heat treatment furnaces. Japanese packaging machinery OEMs in Nagoya specify compact PID controllers from specialist vendors for integration into export equipment.
- Food & Beverage:Pasteurization and retort monitoring require HACCP-compliant temperature recording with tamper-evident data storage. FSSAI enforcement in Indian dairy processing is expanding digital controller penetration beyond metropolitan cooperatives.
- Pharmaceuticals:Sterile injectable production and active pharmaceutical ingredient synthesis demand FDA 21 CFR Part 11 validation with electronic signature capability. CDSCO GMP enforcement in Indian contract manufacturing organizations is accelerating upgrade cycles in underpenetrated facilities.
- HVAC:Building automation and refrigeration systems face EU F-Gas Regulation mandates for low-global-warming-potential refrigerant compatibility, forcing controller reprogramming alongside R-410A to R-32 conversions.
Manufacturing holds the largest installed base; pharmaceuticals is gaining share fastest on regulatory compliance spending.
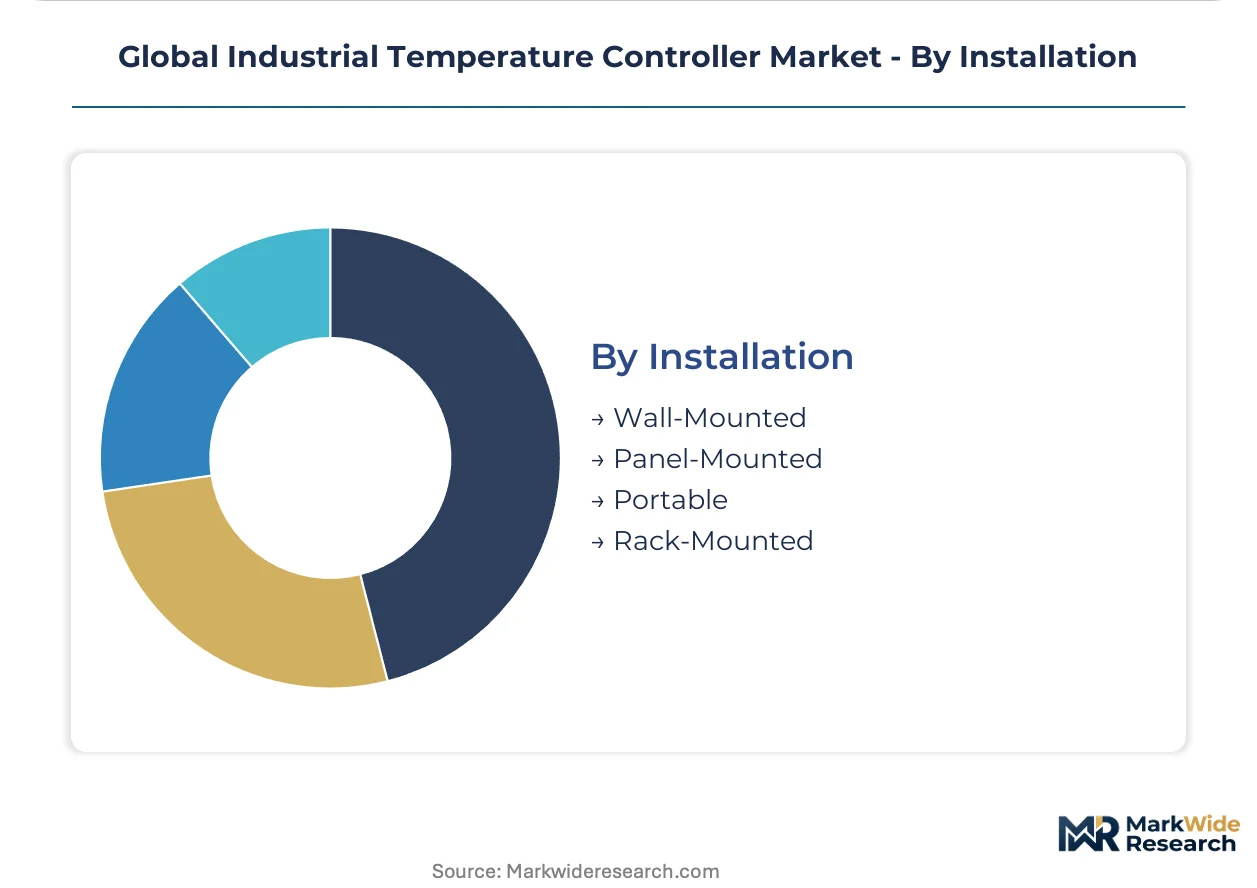
Installation:
Physical mounting configuration shapes procurement economics, with panel-mounted and rack-mounted systems requiring enclosure integration expertise that portable and wall-mounted alternatives avoid.
- Wall-Mounted:Enclosed controllers with IP65 ratings serve outdoor refrigeration compressors and rooftop HVAC units. European contractors bundle these with refrigerant transition services to capture adjacent revenue streams.
- Panel-Mounted:DIN-rail or cutout installations dominate OEM equipment builds where controller supplier relationships modularize around standardized I/O backplanes. Swiss and German lyophilization line builders adopt these platforms to reduce spare parts inventory.
- Portable:Handheld calibrators and temporary monitoring units support commissioning and troubleshooting in field service applications.
- Rack-Mounted:19-inch chassis configurations consolidate multi-loop coordination in distributed control system architectures across North American petrochemical complexes where Honeywell integration is prevalent.
Panel-mounted systems represent the dominant configuration; rack-mounted units are expanding most quickly in greenfield semiconductor fabs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors precision controller PCB fabrication, with Nagoya and Taipei industrial corridors supplying adjacent sensor and automation ecosystems. Demand clusters concentrate in East Asian manufacturing zones where semiconductor fabs and automotive OEMs drive thermal management specifications.
United States
Gulf Coast petrochemical complexes sustain analog controller demand through OSHA Process Safety Management compliance cycles. EPA refrigerant phase-down rules force HVAC controller retrofits in commercial cold chains. Houston and Bay Area industrial clusters host distributed control system integrators serving upstream oil and gas operations.
Germany
Lyophilization equipment builders in Baden-Württemberg specify EMA GMP Annex 15-validated digital platforms for pharmaceutical export compliance. REACH framework restrictions on sensor materials compel PCB redesigns with pre-validated material declarations. Munich-Stuttgart industrial corridor concentrates precision automation engineering talent.
China
Shenzhen's electronics manufacturing services sector produces over seventy percent of compact PID controller circuit boards for global OEM integration. MIIT industrial internet policies accelerate edge-AI controller adoption in smart factories. Yangtze River Delta fabs deploy precision thermal management for domestic semiconductor self-sufficiency drives.
Japan
Nagoya packaging machinery OEMs embed compact PID controllers from specialist vendors into export equipment bound for Southeast Asian food processing lines. METI carbon neutrality roadmaps push refrigerant transition services bundling controller reprogramming. Osaka-Tokyo industrial corridor maintains analog-to-digital migration expertise for legacy infrastructure.
India
CDSCO GMP enforcement expands temperature validation requirements for sterile injectable production in Maharashtra and Gujarat contract manufacturing organizations. FSSAI dairy processing regulations drive digital controller penetration beyond metropolitan cooperatives into tier-two processing clusters. Bangalore-Hyderabad pharmaceutical corridor attracts cold chain infrastructure investment.
Global Industrial Temperature Controller Market Competitive Environment
Premium-margin players sit above commodity-margin players across precision-grade and software-integration dimensions, with automation software stacks anchoring the upper tier. The vendor base stratifies into three archetypes: diversified industrial conglomerates with control system integration capabilities, specialist precision controller fabricators serving OEM equipment builders, and regional electronics manufacturers supplying cost-optimized PCB assemblies. Competitive moves concentrate on strategic partnerships for refrigerant transition service bundling and portfolio diversification into IoT-enabled audit-trail platforms for pharmaceutical compliance.
Within the diversified industrial tier, Siemens AG and Honeywell International Inc. occupy positions defined by automation software depth and distributed control system integration respectively. RKC Instrument Inc. exemplifies the specialist precision fabricator archetype, with its company name indicating Japanese origin and compact controller specialization for packaging machinery OEMs. These three entities represent distinct competitive vectors: control system integration at scale, precision-grade hardware for export equipment, and embedded automation software anchoring.
| Leading Market Players |
|---|
| ABB Ltd. |
| Panasonic Corporation |
| Siemens AG |
| RKC Instrument Inc. |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Omron Corporation |
| Danfoss A/S |
| Schneider Electric SE |
| Others |
Value Chain & Pricing Dynamics
Multi-loop PID controller architectures with embedded self-tuning algorithms are simultaneously compressing production economics for precision-grade units and concentrating manufacturing capability in East Asian electronics corridors. This technological shift forces mid-tier vendors to absorb platinum group metal volatility in RTD sensor elements while premium players capture value through automation software bundling.
Pricing Analysis
Uptime-guarantee contracts in pharmaceutical cold chains anchor value-based pricing for IoT-enabled controllers with predictive maintenance APIs. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-validated platforms from commodity on-off units. Cost compression in mid-tier digital controllers is intensifying because Shenzhen-based PCB assemblers compete on volume scale. Contract manufacturing organizations exhibit highest price sensitivity; semiconductor fabs in Taiwan and South Korea show least sensitivity due to yield-loss economics.
Supply Chain Analysis
Container freight rates from Shenzhen to European pharmaceutical hubs directly amplify landed costs for compact PID controller assemblies. Controller PCB fabrication concentrates in China, Japan, and Taiwan; platinum wire for RTD elements draws from South African and Russian mining operations. Single-source vulnerability sits with Heraeus and Johnson Matthey for thin-film platinum deposition. Distribution runs through OEM equipment builders in Nagoya and Swiss lyophilization specialists rather than direct end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automation software depth as REACH compliance costs and IEC 61010-1 certification timelines force sub-scale players toward exit.
For Market Incumbents: Anchor premium positioning through backward integration into ARM Cortex-M4 microcontroller firmware development, defending against edge-AI specialists. Deepen control system integration partnerships with North American petrochemical complexes to lock out modular competitors. Certification investment in pre-validated material declarations transfers REACH burden to component suppliers. For New Entrants and Emerging Players: Indian contract manufacturing organizations present the most penetrable buyer archetype given CDSCO GMP enforcement gaps in tier-two Maharashtra and Gujarat facilities. Refrigerant transition service bundling offers a service-revenue wedge adjacent to hardware margins. Target FDA audit-trail custody contracts in Massachusetts and North Carolina through third-party metrology partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with precision controller fabricators possessing embedded algorithm portfolios given EU F-Gas Regulation retrofit demand. Long-term viability favors specialists with pharmaceutical validation capabilities over commodity analog assemblers. Watch platinum group metal price volatility as margin inflection signal for RTD-dependent vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Firmware Development | Self-optimizing PID algorithms on ARM Cortex-M4 microcontrollers enable predictive thermal management without cloud dependency. |
| Refrigerant Transition Service Bundling | European contractors capture adjacent revenue by pairing controller reprogramming with R-410A to R-32 conversions under EU F-Gas Regulation. |
| Pre-Validated Material Declarations | REACH-compliant PCB assemblies with supplier-transferred compliance burden accelerate pharmaceutical OEM refresh cycles. |
| Third-Party Metrology Custody | External audit-trail custody in Massachusetts and North Carolina reduces liability exposure for FDA-regulated sterile manufacturing. |
| Multi-Loop Controller Modularization | Standardized I/O backplanes with swappable input cards reduce spare parts inventory for Swiss and German lyophilization line builders. |
Study Parameters
Independent corroboration across controller OEM technical directors, pharmaceutical plant engineers, and HVAC refrigeration contractors underwrites the qualitative findings. Primary interviews with maintenance directors at Taiwan semiconductor fabs, procurement leads at Nagoya packaging machinery OEMs, and aftermarket service heads at European distributors combined with secondary validation. Trade data from customs authorities, IEC certification registries, and EMA GMP inspection reports anchored supply-side estimates. Bottom-up unit economics and top-down sectoral expenditure patterns were reconciled across the analysis.
Rate-of-change decomposition across sensor technology, control architecture, and end-use regulatory exposure shaped the analytical framework. Segmentation dimensions modeled include precision grade, communication protocol, validation tier, and regional manufacturing corridor. CAGRs were derived from installed base turnover rates and replacement cycle compression in regulated environments. Platinum group metal price trajectories and EU F-Gas Regulation implementation timelines served as industry-specific forecast inputs.
Revisions become necessary when semiconductor capital expenditure cycles stall, REACH restrictions expand to additional sensor materials, or wireless interference protocols in heavy industrial settings advance beyond current IEEE 802.15.4 limitations. Forecasts reflect assumptions about regulatory enforcement continuity and technology migration economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
India Industrial Sensors and Transmitters Market