
 Two Wheeler Sensors Market | 2026-2036
Two Wheeler Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Sensors Market Analytics
Aftermarket sensor calibration services is reshaping margin distribution away from pure hardware sales across the two-wheeler value chain. Robert Bosch GmbH leverages its integrated manufacturing footprint to dominate Hall Effect sensor supply for European OEMs. Continental AG anchors its position through R&D intensity in optical sensing architectures for performance motorcycles. DENSO Corporation specializes in temperature and pressure sensor miniaturization for Asian scooter platforms.
Two wheeler sensors are electromechanical transducers that convert physical variables—wheel speed, throttle angle, engine temperature, brake pressure—into electrical signals readable by engine control units and safety modules, typically operating within temperature ranges of minus forty to one hundred fifty degrees Celsius and voltage rails of five to twelve volts. Their primary purpose is to enable real-time powertrain optimization, anti-lock braking intervention, and emissions compliance in motorcycles and scooters. Hall Effect sensors lead the technology dimension due to their contactless durability in wheel-speed and position-sensing roles, while MEMS sensors represent the fastest-expanding category as manufacturers integrate multi-axis inertial measurement into stability control and connected-vehicle telematics. The end-user structure concentrates margin pools with OEMs and tier-1 suppliers who specify sensor performance thresholds during vehicle platform development, leaving aftermarket providers to compete on reverse-engineered compatibility and price.
India's Ministry of Road Transport and Highways mandates ABS fitment through CMVR notifications, while the EU F-Gas Regulation and REACH framework constrain refrigerant and material choices in temperature sensor housings. The EPA and NHTSA in the United States enforce OBD-II compatibility and brake-system performance standards that dictate sensor accuracy thresholds. Stakeholders must monitor how emissions-test protocol harmonization between European and Indian regulators reshapes sensor calibration requirements and platform certification costs.
Market Dynamics
India's CMVR ABS mandate is compressing the decision window for Hall Effect sensor procurement across South Asian motorcycle manufacturing clusters, forcing tier-1 suppliers to localize production ahead of the compliance deadline.
Growth Catalysts
- CMVR ABS Mandate (India):The Ministry of Road Transport and Highways requires anti-lock braking on two-wheelers above 125cc, creating immediate demand for wheel-speed sensors in commuter motorcycle platforms.
- Hall Effect Localization:Tier-1 suppliers are establishing captive Hall Effect production lines in Tamil Nadu and Gujarat manufacturing corridors to serve cost-sensitive domestic assemblers.
- MEMS Integration:Multi-axis inertial measurement units are penetrating stability control and telematics applications as OEMs specify higher sensor density per vehicle.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in Chinese processing facilities transmit directly into Hall Effect sensor bill-of-materials.
- Foundry Concentration Risk:MEMS wafer fabrication for automotive-grade sensors concentrates in Taiwanese and South Korean semiconductor facilities, exposing supply chains to single-point disruption.
- REACH Material Constraints:The EU F-Gas Regulation and ECHA substance restrictions limit housing material choices for temperature sensors, forcing reformulation of established designs.
Strategic Opportunities
- Vietnam Assembly Expansion:Honda and Yamaha are expanding scooter production in northern Vietnamese industrial zones, creating greenfield sensor specification opportunities outside established Indian supply relationships.
- Optical Sensing Convergence:Performance motorcycle OEMs in Italy and Germany are specifying optical position sensors for throttle-by-wire systems, converging with existing Hall Effect architectures.
- Aftermarket Calibration Services:Independent service networks in Indonesia and Thailand are unbundling sensor recalibration from dealer maintenance, opening channel innovation for diagnostic equipment providers.
Industry Challenges
- Embedded Software Competency Gap:Tier-2 sensor module suppliers struggle to hire firmware engineers capable of integrating sensor fusion algorithms with OEM engine control unit architectures.
- ISO 26262 Certification Timeline:Functional safety documentation for ABS-critical wheel-speed sensors extends platform development cycles by 8-14 months, compressing supplier quotation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Sensors Market |
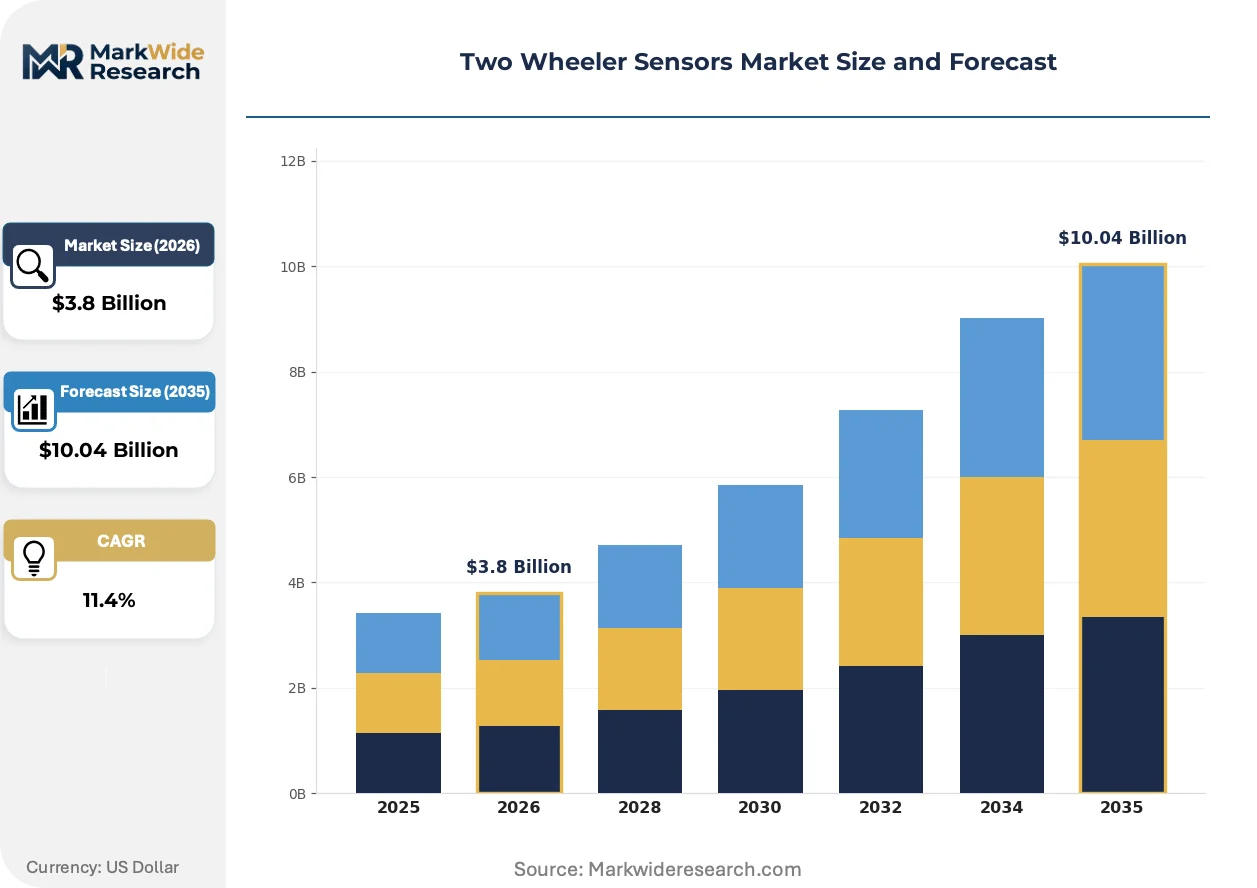
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Speed Sensor, ABS Sensor, Throttle Position Sensor, Temperature Sensor Application: Safety Monitoring, Performance Tracking, Engine Management, Fuel Efficiency End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Optical Sensors, Ultrasonic Sensors, Hall Effect Sensors, MEMS Sensors |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Infineon Technologies AG, ZF Friedrichshafen AG, Sensata Technologies Inc, NXP Semiconductors NV, Delphi Automotive LLP, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Sensors Market Evolving Landscape
Sensor fusion architectures are collapsing discrete component boundaries as motorcycle OEMs demand consolidated modules that combine wheel-speed, inertial, and temperature sensing within single housing units.
Hall Effect sensor integration with magnetoresistive elements is collapsing the traditional separation between position and speed sensing functions in two-wheeler powertrains. European performance motorcycle assemblers in Germany and Italy are specifying these consolidated modules for 2026 platform launches. This convergence is collapsing the addressable market for standalone speed sensors while expanding average content value per wheel hub.
The EU F-Gas Regulation is tightening refrigerant containment requirements for two-wheeler climate control systems, directly affecting temperature sensor housing specifications. ECHA substance restrictions are forcing sensor manufacturers to reformulate potting compounds and connector plastics. Asian suppliers serving European export markets are responding by establishing separate production lines with REACH-compliant material certification.
Aftermarket sensor procurement is fragmenting as Indonesian and Thai independent repair networks build direct purchasing relationships with Chinese sensor distributors, bypassing traditional tier-1 wholesale channels. These buyers prioritize reverse-engineered compatibility databases over OEM certification, compressing margin structures for branded replacement parts. The shift is most visible in Jakarta and Bangkok metropolitan service corridors where scooter fleet operators maintain captive maintenance facilities.
Two Wheeler Sensors Market Segmentation
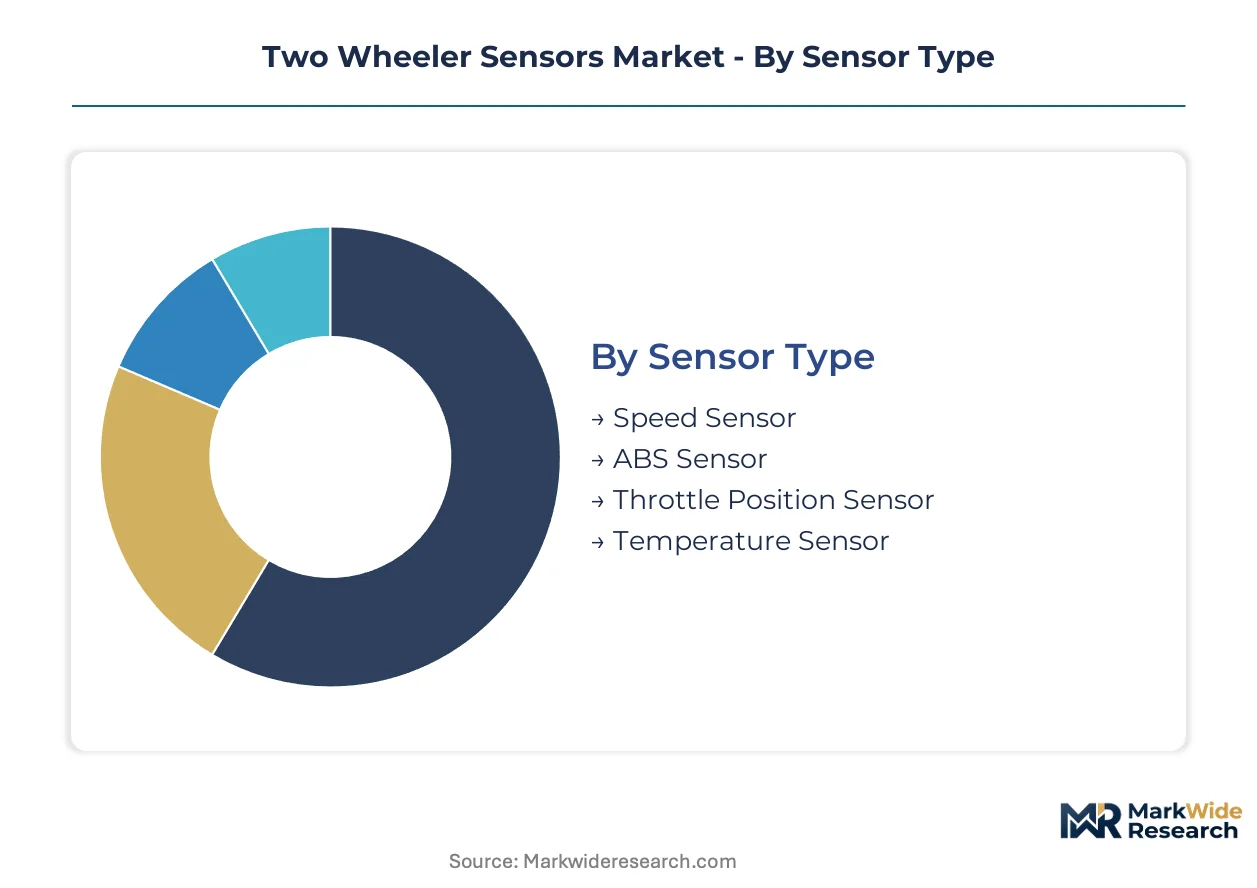
Two wheeler sensor procurement patterns diverge sharply across technology platforms and supply chain tiers. Understanding these divides reveals where margin pools concentrate and which specifications drive platform development decisions.
Sensor Type:
Cost tier determines specification rigor, with safety-critical sensors commanding premium validation protocols against utility-grade alternatives.
- Speed Sensor:Magnetic pick-up or Hall Effect elements detect wheel rotation frequency for odometer and traction control functions. Commuter motorcycle OEMs in India specify these for CMVR compliance across 125cc-plus platforms, with Tamil Nadu assemblers driving procurement volume.
- ABS Sensor:Wheel-speed transducers with ISO 26262 functional safety certification enable anti-lock braking intervention. India's Ministry of Road Transport mandates these for displacement categories above 125cc, compressing supplier qualification timelines to 8-14 months.
- Throttle Position Sensor:Potentiometric or Hall Effect devices translate rider input into voltage signals for engine control units.
- Temperature Sensor:Thermistor or RTD-based probes monitor engine coolant, exhaust gas, and ambient conditions for thermal management.
ABS sensors command the established base. The steepest expansion runs through speed sensors as CMVR mandates broaden fitment requirements.
Application:
Application focus shapes sensor density per vehicle, with safety modules integrating multiple transducer types against single-purpose engine management units.
- Safety Monitoring:Consolidated wheel-speed, lean-angle, and brake-pressure sensing enables stability control and collision avoidance. European performance motorcycle assemblers in Germany and Italy specify multi-sensor fusion architectures for 2026 platform launches.
- Performance Tracking:Accelerometer, gyroscope, and GPS integration supports lap timing, suspension telemetry, and rider analytics. Track-day enthusiasts and racing teams in Italy drive aftermarket specification for data-logging compatibility.
- Engine Management:Air-fuel ratio, knock detection, and camshaft position sensing optimize combustion efficiency and emissions compliance.
- Fuel Efficiency:Oxygen sensors and manifold absolute pressure transducers enable closed-loop fuel injection control for scooter platforms.
Safety monitoring commands the established base. The steepest expansion runs through performance tracking as connected-vehicle telematics penetrate premium segments.
End User:
Customer type determines procurement authority, with OEMs and tier-1 suppliers controlling specification versus aftermarket price competition.
- OEMs:Vehicle manufacturers define sensor performance thresholds, calibration protocols, and supplier qualification criteria during platform development. Honda and Yamaha expanding Vietnamese assembly operations create greenfield specification opportunities outside established Indian supply relationships.
- Aftermarket Providers:Independent distributors and service networks compete on reverse-engineered compatibility and price. Indonesian and Thai repair networks in Jakarta and Bangkok metropolitan corridors bypass tier-1 wholesale channels to source directly from Chinese distributors.
- Tier-1 Suppliers:Integrated module manufacturers consolidate discrete sensing functions into consolidated housing units for OEM delivery.
- Vehicle Assemblers:Contract manufacturers in South Asian industrial zones execute final integration of sensor-equipped subsystems.
OEMs command the established base. The steepest expansion runs through aftermarket providers as fleet operators in Southeast Asia build captive maintenance capabilities.
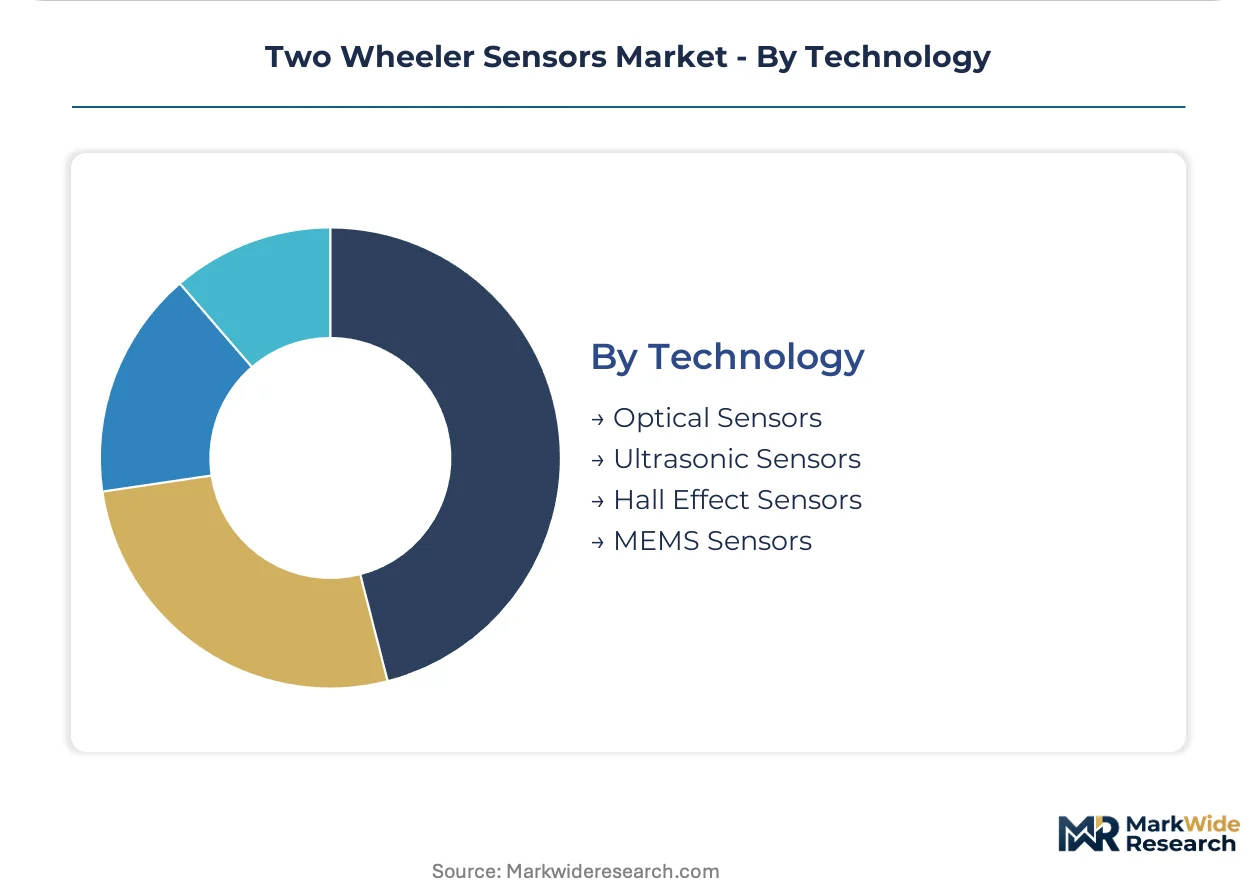
Technology:
Maturity curves separate contactless architectures with proven durability against emerging MEMS platforms expanding sensing degrees of freedom.
- Hall Effect Sensors:Contactless magnetic field detection delivers position and speed sensing without mechanical wear. Robert Bosch GmbH dominates European OEM supply through integrated manufacturing footprints, while tier-1 suppliers localize production in Tamil Nadu and Gujarat corridors for cost-sensitive assemblers.
- MEMS Sensors:Micro-electromechanical systems enable multi-axis inertial measurement in compact packages. Multi-axis IMU penetration into stability control and telematics applications is climbing the fastest as OEMs specify higher sensor density per vehicle.
- Optical Sensors:Photoelectric or laser-based position detection supports throttle-by-wire and encoder applications.
- Ultrasonic Sensors:Time-of-flight distance measurement enables parking assistance and blind-spot detection on premium scooters.
Hall Effect sensors command the established base. The steepest expansion runs through MEMS sensors as sensor fusion architectures collapse discrete component boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys two-wheeler sensors predominantly for regulatory compliance, while European and Japanese markets prioritize performance telemetry and rider analytics. This consumption-mix differential shapes procurement patterns, calibration requirements, and supplier qualification protocols across manufacturing clusters.
India
Commuter motorcycle OEMs drive Hall Effect sensor procurement for CMVR ABS mandates on 125cc-plus platforms. The Ministry of Road Transport and Highways enforces anti-lock braking fitment through statutory notifications, compressing supplier qualification timelines. Tamil Nadu and Gujarat manufacturing corridors host tier-1 suppliers establishing captive production lines for cost-sensitive domestic assemblers.
Germany
Performance motorcycle assemblers specify optical sensing architectures and multi-sensor fusion modules for throttle-by-wire systems. The KBA enforces brake-system performance standards that dictate sensor accuracy thresholds for type approval. Bavaria and Baden-Württemberg industrial zones concentrate R&D-intensive module development for premium European OEMs.
Japan
Scooter platforms and compact motorcycles integrate MEMS-based inertial measurement for stability control and connected-vehicle telematics. METI promotes sensor miniaturization through industrial technology grants targeting multi-axis integration. Kansai and Chubu manufacturing belts host precision component fabricators supplying temperature and pressure transducers to Asian vehicle assemblers.
Vietnam
Honda and Yamaha expansion in northern Vietnamese industrial zones creates greenfield sensor specification opportunities outside established Indian supply relationships. The country's national automotive regulator harmonizes type-approval protocols with ASEAN standards, streamlining cross-border component certification. Hanoi and Hai Phong metropolitan corridors attract tier-1 suppliers establishing proximity logistics for Japanese OEM assembly operations.
United States
Aftermarket diagnostic equipment providers target sensor recalibration services for independent repair networks serving cruiser and touring motorcycle fleets. The EPA and NHTSA enforce OBD-II compatibility and brake-system performance standards that shape sensor accuracy requirements. Midwest industrial zones concentrate distribution infrastructure for replacement parts serving North American dealer and independent service channels.
Two Wheeler Sensors Market Competitive Landscape
Capability concentration sits with integrated module manufacturers possessing functional safety certification expertise; scale advantage sits with diversified component suppliers serving multiple vehicle platforms. The market structures around three tiers: multinational tier-1 integrators with captive semiconductor fabrication, regional specialists in Hall Effect and MEMS packaging, and aftermarket distributors competing on reverse-engineered compatibility. Dominant competitive moves include backward integration into magnet and wafer supply, plus geographic co-location with expanding ASEAN assembly operations.
Within the integrated manufacturing tier, Robert Bosch GmbH and Continental AG exemplify archetypes of European-origin diversified suppliers with broad automotive sensor portfolios. DENSO Corporation occupies a position representing Japanese-origin specialists in powertrain and thermal sensing modules. These three anchors illustrate how geographic origin and historical vehicle-system focus shape competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Infineon Technologies AG |
| ZF Friedrichshafen AG |
| Sensata Technologies Inc |
| NXP Semiconductors NV |
| Delphi Automotive LLP |
| Hitachi Ltd. |
| Others |
Value Network & Pricing Analysis
Tamil Nadu manufacturing corridors host tier-1 suppliers establishing captive Hall Effect production lines, and this localized capacity expansion is compressing procurement costs for Indian motorcycle OEMs facing CMVR ABS mandates. The concentration of magnet processing in Chinese rare-earth facilities transmits volatility directly into sensor bill-of-materials, forcing assemblers to hedge through long-term offtake structures.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-1 integrators and domestic assemblers, insulating against neodymium price swings while spot purchasing persists for aftermarket distributors sourcing from Chinese traders. Price differentiation separates ISO 26262-certified ABS modules from utility-grade speed sensors, with certification tier commanding premium positioning. Pricing pressure stems from Indonesian and Thai fleet operators bypassing traditional wholesale channels to source reverse-engineered alternatives directly. Aftermarket providers exhibit highest price sensitivity, while European performance motorcycle OEMs prioritize optical sensing accuracy over unit cost.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows to Chinese foundries are constraining MEMS wafer fabrication capacity expansion, concentrating automotive-grade sensor production in Taiwanese and South Korean facilities. The supply chain draws from Chinese rare-earth processing for Hall Effect magnets, Vietnamese assembly operations for Honda and Yamaha platforms, and Indian domestic manufacturing for CMVR-compliant commuter motorcycles. Single-source vulnerability concentrates in Taiwanese MEMS foundries serving multi-axis inertial measurement demand. Distribution runs through tier-1 module integrators delivering consolidated housing units to OEM platform engineers, with aftermarket channels fragmenting toward direct Chinese distributor relationships in Southeast Asian metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as India's ABS mandate penetration accelerates sensor density per vehicle beyond regulatory minimums into stability control and telematics applications. MEMS integration into scooter platforms and performance motorcycles indicates adoption tailwinds extending through the projection horizon.
For Market Incumbents: Build certification moats through accelerated ISO 26262 documentation for wheel-speed sensors, compressing the 8-14 month qualification window that threatens margin capture from emerging MEMS specialists. Deepen backward integration into magnet supply through captive rare-earth partnerships, insulating against Chinese processing volatility that erodes Hall Effect sensor profitability. Anchor channel control by co-locating module assembly with expanding Vietnamese Honda and Yamaha operations, preempting greenfield specification opportunities for rival tier-1 suppliers. For New Entrants and Emerging Players: Establish a beachhead in aftermarket calibration services for Indonesian and Thai independent repair networks, where fleet operators in Jakarta and Bangkok metropolitan corridors seek diagnostic equipment unbundled from dealer maintenance. Target optical sensing architectures for European throttle-by-wire specifications, where performance motorcycle OEMs in Germany and Italy converge beyond established Hall Effect supply relationships. Pursue direct distributor relationships with Chinese sensor wholesalers, bypassing tier-1 margin extraction through reverse-engineered compatibility databases. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compounding play because emissions-test protocol harmonization between European and Indian regulators is reshaping calibration requirements and platform certification costs in ways that favor integrated module manufacturers with multi-geography compliance expertise. Acquisition targets should concentrate on regional Hall Effect packaging specialists in Tamil Nadu and Gujarat corridors possessing captive OEM relationships but lacking MEMS competency. The signal to watch is ASEAN type-approval protocol harmonization, which would streamline cross-border component certification and accelerate Vietnamese assembly expansion beyond current Honda and Yamaha footprints.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures multi-axis inertial measurement capacity for stability control integration ahead of demand inflection. |
| Rare-Earth Magnet Backward Integration | Captures neodymium supply chain control insulating Hall Effect sensor margins from Chinese processing volatility. |
| Vietnamese Assembly Co-location | Positions module manufacturing within Honda and Yamaha expansion corridors for greenfield specification capture. |
| ISO 26262 Certification Acceleration | Compresses functional safety documentation timelines threatening platform development cycle participation. |
| Aftermarket Diagnostic Platform Launch | Enters Indonesian and Thai fleet maintenance networks seeking sensor recalibration unbundled from dealers. |
Research Methodology
The analysis maps Hall Effect speed sensors, MEMS inertial measurement units, optical position sensors, and temperature-pressure transducers, each validated through tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operators, and semiconductor foundry account managers. Primary interview data triangulates against vehicle production databases, CMVR regulatory filings, IHS Markit registration data, and customs trade records for rare-earth magnet flows. Bottom-up sensor content-per-vehicle estimates reconcile with top-down market value reconstruction across technology platforms.
Assumptions held fixed include India's CMVR ABS mandate enforcement timeline and current ASEAN type-approval harmonization progress, while variables include MEMS penetration rates into scooter stability control and European optical sensing adoption for throttle-by-wire. The analytical framework segments by sensor type, application module, technology architecture, and end-user procurement authority, with CAGRs derived from installed base growth and content expansion trajectories. Forecast inputs incorporate OEM platform launch schedules and tier-1 supplier capacity expansion announcements.
Sensitivities concentrate around rare-earth price volatility, Taiwanese foundry disruption risk, and regulatory harmonization acceleration between European and Indian emissions protocols. Forecasts reflect assumptions on CMVR compliance penetration and MEMS cost curves. Material shifts in Chinese export controls for semiconductor manufacturing equipment or ASEAN regulatory integration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Electrochemical Sensor Market