

Control Network Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Control Network Modules Market Insights
Gallium nitride is repositioning power module economics by enabling higher switching frequencies at reduced thermal loads. Siemens leverages captive semiconductor foundry partnerships to secure GaN supply for its SINAMICS drive families. Rockwell Automation anchors North American demand through its Integrated Architecture platform, which bundles ControlLogix processors with embedded Ethernet modules. Schneider Electric differentiates via EcoStruxure, a vendor-agnostic framework that competes for multi-protocol brownfield deployments.
Control network modules are embedded computing devices that bridge field-level sensors and actuators with supervisory control systems, typically operating across temperature ranges of minus 40 to 85 degrees Celsius and supporting real-time cycle times below one millisecond. Their primary purpose is to translate heterogeneous industrial protocols into unified data streams for programmable logic controllers and distributed control systems. Communication modules lead volume as Ethernet and EtherCAT displace legacy fieldbus architectures in automotive and food processing lines. Power modules command premium pricing where GaN and silicon carbide architectures serve high-density motor control applications in oil and gas upstream facilities. Interface modules sustain steady replacement demand across chemical processing plants that maintain mixed DeviceNet and Profibus estates.
IEC 62443 cybersecurity standards, the EU Cyber Resilience Act, and FCC Part 15 emissions rules collectively determine product certification requirements and procurement eligibility across target end-use sectors. OEMs now embed hardware security modules and secure boot capabilities directly into network interface designs to satisfy these overlapping compliance regimes. Stakeholders must weigh protocol migration timelines against the operational risk of maintaining unsupported fieldbus infrastructure as vendor support windows contract.
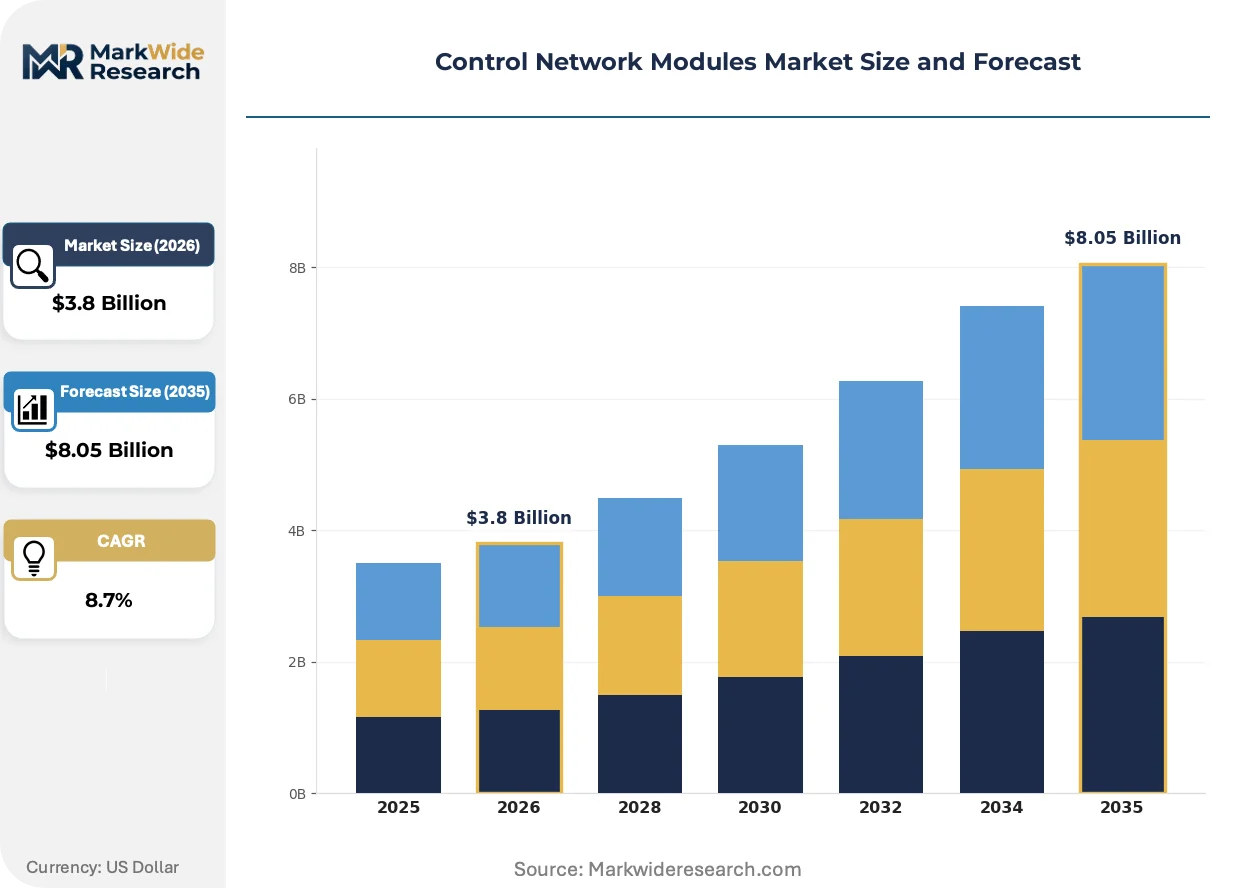
Market Dynamics
Migration from fieldbus to Ethernet-based control architectures is compressing replacement cycles across automotive and food processing lines, forcing module vendors to recertify entire product families against IEC 62443 cybersecurity tiers within shortened development windows.
Growth Catalysts
- Edge computing architectures:Factory floor data processing requirements are pulling intelligence downward from PLCs into distributed I/O modules, expanding addressable module count per installation.
- NIS2 Directive compliance deadlines:European critical infrastructure operators must upgrade network segmentation by October 2024, accelerating module procurement with embedded hardware security.
- Germany's industrial corridor concentration:Automotive OEMs in Baden-Württemberg and Bavaria are retrofitting legacy lines with EtherCAT modules, creating sustained replacement demand.
Market Restraints
- Silicon carbide substrate shortages:Power module manufacturers face allocation constraints for SiC wafers, extending lead times for high-density motor control applications.
- Foundry capacity concentration in Taiwan:Advanced node semiconductor fabrication for security-enabled network processors remains geographically concentrated, exposing supply continuity risk.
- Legacy protocol persistence:DeviceNet and Profibus estates in chemical processing plants create technical debt that slows full Ethernet migration.
Strategic Opportunities
- Battery gigafactory construction:Lithium-ion cell manufacturing lines in Hungary and Poland require synchronized multi-axis motion control, opening greenfield module deployment.
- EU Cyber Resilience Act certification:First-mover vendors securing CE-RED plus cybersecurity dual certification gain preferential listing with industrial distributors.
- GaN-SiC hybrid power modules:Converging wide-bandgap materials enable 100kHz+ switching frequencies that unlock new servo drive form factors.
Industry Challenges
- Embedded cybersecurity engineering scarcity:Firmware developers with IEC 62443-4-2 implementation experience command premium compensation, constraining vendor R&D scaling.
- Multi-protocol certification timelines:Simultaneous Profinet, EtherCAT, and OPC UA compliance testing extends product launch schedules by 8-14 months.
- Brownfield integration complexity:Retrofitting 1990s-era DCS architectures without production line shutdowns demands specialized system integrator partnerships.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Control Network Modules Market Trends and Innovations
Ethernet-based deterministic protocols are collapsing the historical separation between information technology and operational technology networks, requiring module designs that satisfy both IEEE 802.1 time-sensitive networking and Purdue Model security zoning simultaneously.
Gallium nitride power semiconductors is rewriting thermal management economics in compact servo drives. Machine builders in packaging machinery are adopting GaN-based inverter modules at three-year replacement intervals versus seven years for silicon IGBT predecessors. The technology is compressing enclosure sizes by 40 percent while doubling switching frequency ceilings.
The EU Cyber Resilience Act's mandatory vulnerability disclosure requirements are forcing firmware architecture redesigns. Industrial OEMs must now maintain secure update pipelines for deployed modules across fifteen-year service lives. Network interface card suppliers serving German automotive Tier-1s are prioritizing over-the-air update capabilities in new designs.
Buying committees are consolidating vendor relationships from an average of four protocol specialists to two full-platform suppliers. System integrators in France are bundling hardware procurement with long-term cybersecurity monitoring contracts. This concentration is most visible in pharmaceutical manufacturing, where FDA 21 CFR Part 11 validation requirements favor incumbent relationships over new vendor qualification.
Control Network Modules Market Segmentation
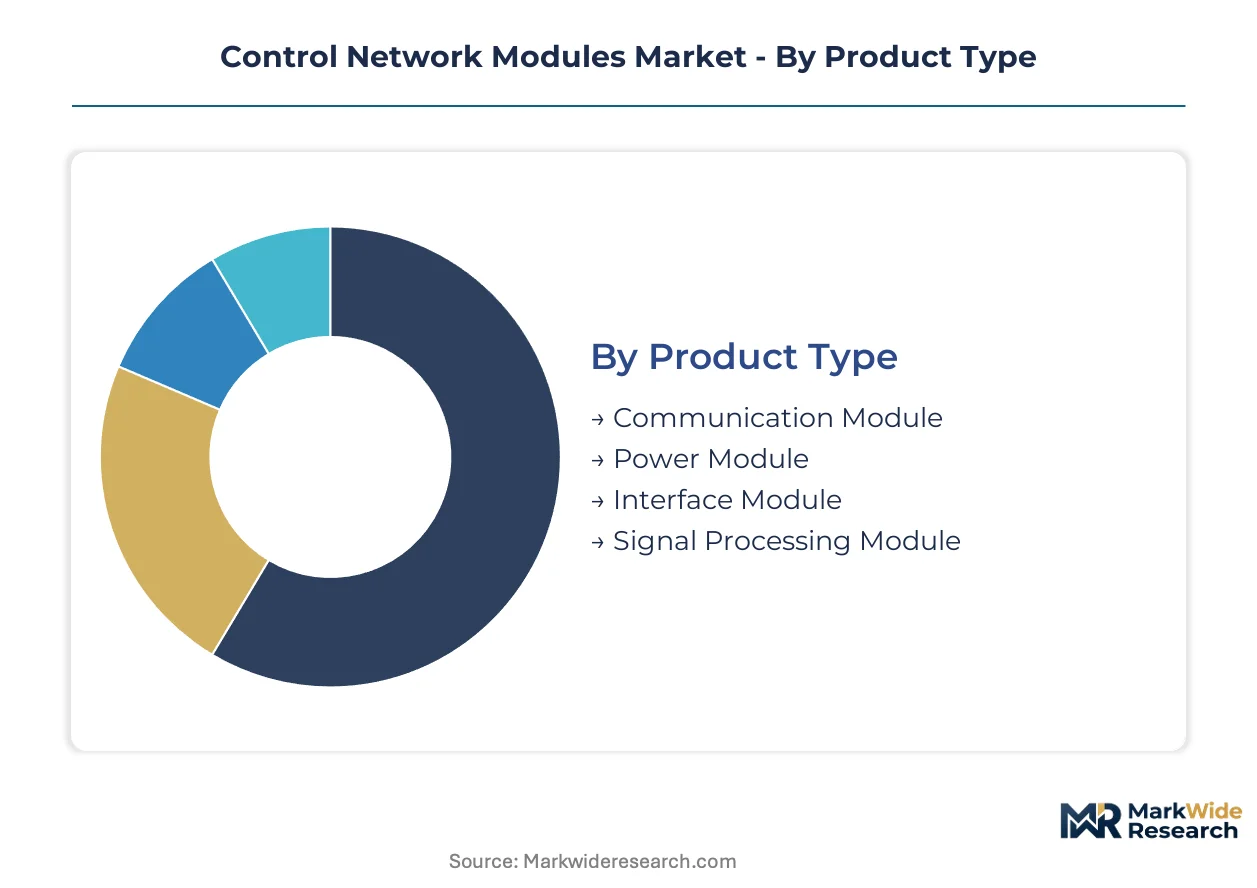
Control network module purchasing follows distinct technical and commercial logics across product categories, protocol standards, and end-use environments. Procurement committees weight real-time performance specifications against cybersecurity certification tiers and legacy infrastructure compatibility.
Product Type:
Buyer capital allocation prioritizes communication density and thermal performance over raw unit cost.
- Communication Module:These units embed protocol translation engines and hardware security modules for Ethernet-to-fieldbus bridging. Demand concentrates in Baden-Württemberg automotive assembly plants where EtherCAT retrofit programs compress replacement cycles to three-year intervals.
- Power Module:Gallium nitride and silicon carbide architectures enable 100kHz+ switching frequencies in compact servo drives. Oil and gas upstream facilities in the North Sea command premium pricing for explosion-rated variants that survive minus 40 degree Celsius startup conditions.
- Interface Module:Mixed-signal conditioning units bridge legacy DeviceNet sensors with modern control architectures.
- Signal Processing Module:Real-time filtering and edge analytics engines for vibration monitoring applications.
Volume sits with communication modules; growth tilts toward power modules.
Technology:
Protocol selection determines vendor lock-in duration and cybersecurity recertification burden.
- Ethernet:IEEE 802.1 time-sensitive networking enables deterministic cycle times below one millisecond over standard cabling. Food processing lines in Bavaria are collapsing IT and OT network separation using Ethernet modules that satisfy both Purdue Model zoning and FDA 21 CFR Part 11 validation.
- EtherCAT:Distributed clock synchronization achieves sub-microsecond jitter for multi-axis motion control. Battery gigafactory construction in Hungary and Poland drives greenfield deployment of EtherCAT-based synchronized servo systems.
- CAN Bus:Lightweight automotive-derived protocol persists in compact machinery.
- Profibus:Process industry incumbent with declining new installation share.
- Modbus:Simple register-based protocol for cost-constrained building automation.
- DeviceNet:Legacy fieldbus with concentrated replacement demand in chemical processing estates.
Ethernet commands the largest installed base; EtherCAT is climbing the fastest.
Application:
Operational environment dictates ingress protection ratings, temperature range, and hazardous area certification requirements.
- Manufacturing Automation:High-density I/O architectures serve discrete assembly and packaging machinery. German automotive OEMs in Bavaria retrofit legacy lines with edge-connected modules that push data preprocessing downward from central PLCs.
- Process Control:Continuous chemical and petrochemical operations demand SIL-rated redundancy. North Sea oil and gas platforms specify marine-certified modules with 15-year service life commitments and embedded hardware security.
- Building Management:BACnet and Modbus integration for HVAC and lighting control.
- Energy Management:Substation automation and renewable generation monitoring.
- Transportation Automation:Rail signaling and airport baggage handling systems.
- Smart Grid:Distribution automation and demand response infrastructure.
Manufacturing automation generates the highest shipment volumes; process control sustains the steepest pricing premiums.
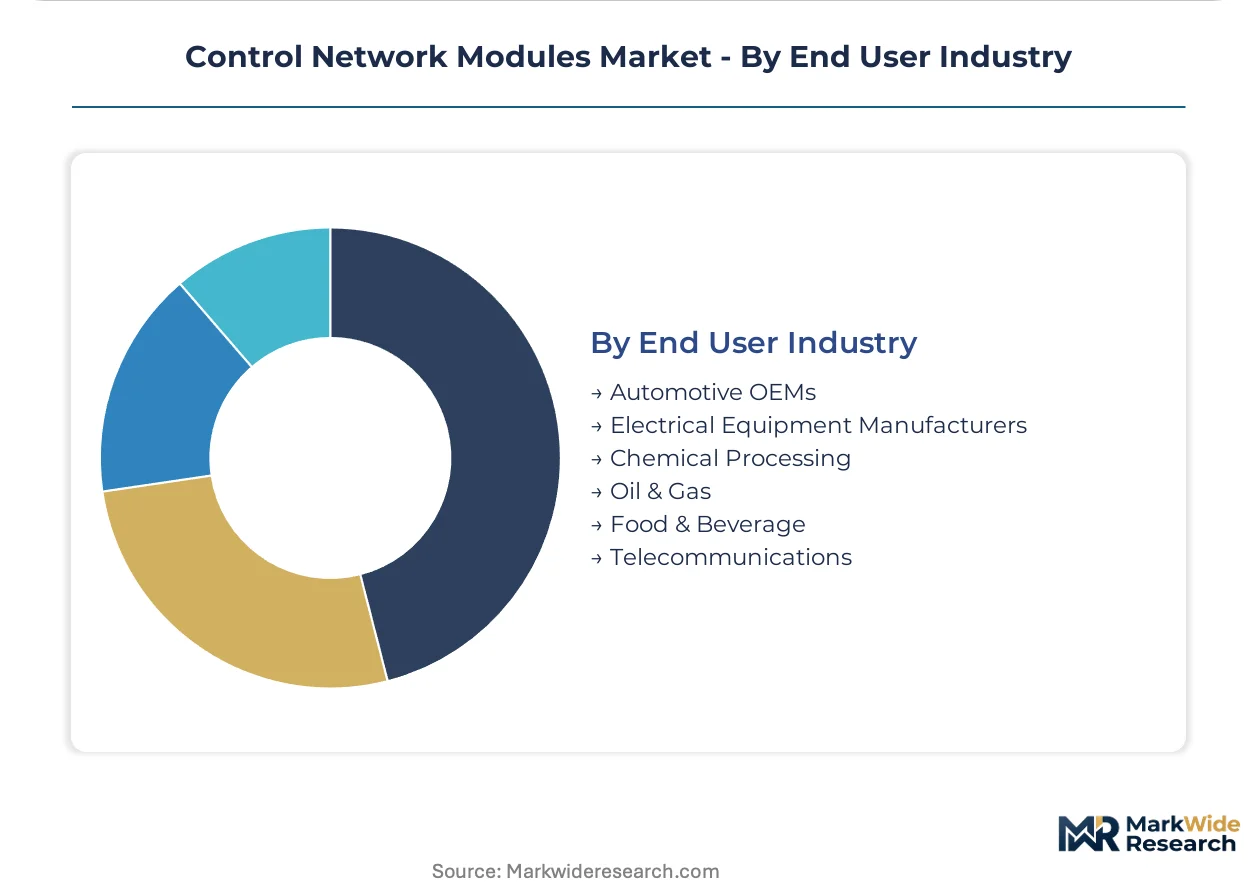
End User Industry:
Industry-specific regulatory compliance and operational technology maturity shape procurement specifications.
- Automotive OEMs:Just-in-time assembly lines require sub-millisecond cycle times and 99.999% availability. German Tier-1 suppliers in Baden-Württemberg mandate IEC 62443-4-2 SL2 certification and over-the-air firmware update capabilities for all new network interface deployments.
- Chemical Processing:Hazardous area classifications and FDA validation requirements for pharmaceutical intermediates. Mixed DeviceNet and Profibus estates in Ludwigshafen and Leverkusen create sustained replacement demand for protocol translation modules.
- Electrical Equipment Manufacturers:Drive and inverter OEMs integrate modules into packaged automation systems.
- Oil & Gas:Upstream and midstream facilities specify explosion-proof enclosures.
- Food & Beverage:Washdown-rated designs for sanitary processing environments.
- Telecommunications:Data center power and cooling infrastructure monitoring.
Automotive OEMs anchor procurement volume; chemical processing offers the most complex brownfield integration opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Industrie 4.0 tax incentives and accelerated depreciation schemes for smart manufacturing equipment concentrate control network module demand in European industrial corridors. Special economic zones in Hungary and Poland attract battery gigafactory investments that require synchronized motion control infrastructure.
United States
FCC Part 15 emissions compliance and NIST cybersecurity frameworks reshape procurement specifications for industrial network hardware. The Inflation Reduction Act's clean energy manufacturing credits accelerate domestic semiconductor packaging investments. Houston's oil and gas engineering cluster drives demand for explosion-rated power modules in upstream automation retrofits.
Germany
NIS2 Directive enforcement deadlines and IEC 62443 certification requirements compress vendor qualification timelines for critical infrastructure operators. KBA automotive safety standards intersect with industrial cybersecurity mandates for Tier-1 supplier networks. Baden-Württemberg's automotive assembly corridor sustains three-year replacement cycles for EtherCAT communication modules.
China
GB standards for industrial automation equipment and MIIT's smart manufacturing pilot programs standardize domestic protocol adoption. Dual carbon goals accelerate wide-bandgap semiconductor substitution in motor control applications. The Yangtze River Delta's electronics manufacturing belt integrates edge-connected I/O architectures into export-oriented production lines.
Japan
METI's Society 5.0 roadmap and JIS industrial network standards harmonize domestic automation procurement. PMDA pharmaceutical manufacturing guidelines extend to validated control system infrastructure for drug production facilities. The Nagoya automotive engineering cluster maintains mixed legacy-Ethernet estates that sustain interface module replacement demand.
South Korea
KC certification for industrial equipment and national semiconductor self-sufficiency initiatives reshape component sourcing patterns. MFDS pharmaceutical validation requirements drive cybersecurity-hardened control architectures in biologics manufacturing. The Busan-Ulsan heavy industry corridor deploys marine-certified modules in shipbuilding automation systems.
Control Network Modules Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in greenfield deployments while component specialists capture replacement cycles in brownfield estates. The vendor base concentrates around three strategic archetypes: full-stack automation platforms, protocol-specific communication specialists, and power semiconductor-integrated module suppliers. Consolidation pressure intensifies as cybersecurity certification costs favor scaled R&D operations over niche players. Geographic expansion and strategic partnerships constitute the dominant competitive moves as vendors seek to anchor distributor relationships in emerging battery manufacturing corridors.
Within the full-stack automation tier, Siemens AG and Rockwell Automation anchor competitive positioning through integrated hardware-software platforms that bundle control processors with network interface modules. Schneider Electric SE occupies a distinct position via vendor-agnostic framework approaches that compete for multi-protocol brownfield integration contracts. These three companies exemplify divergent strategic bets on proprietary ecosystem lock-in versus interoperability-oriented market penetration.
| Leading Market Players |
|---|
| Siemens |
| Rockwell Automation |
| Schneider Electric |
| ABB |
| Mitsubishi Electric |
| Omron |
| Honeywell |
| Emerson |
| Belden |
| Others |
Pricing and Supply Chain Analysis
NIS2 Directive compliance deadlines are compressing procurement timelines for European critical infrastructure operators, forcing module vendors to absorb expedited certification costs into contract pricing or sacrifice margin to secure foundry slots for security-enabled silicon. This demand-side urgency intersects with concentrated semiconductor fabrication capacity to reshape how pricing power distributes across the value chain.
Pricing Analysis
Lead-time-based pricing premiums dominate contract negotiations, with automotive OEMs in Baden-Württemberg paying substantial markups for EtherCAT modules deliverable within twelve-week windows versus standard twenty-six-week schedules. Three-tier pricing structure across IEC 62443-4-2 SL2-certified premium, standard industrial-grade, and economy fieldbus-legacy tiers reflects certification burden and thermal performance differentiation. Pricing pressure stems from silicon carbide substrate allocation constraints extending power module lead times and forcing spot-market premiums. Chemical processing buyers exhibit highest price sensitivity due to mixed legacy estate maintenance costs, while oil and gas upstream operators show lowest sensitivity given explosion-rated specification requirements.
Supply Chain Analysis
IEC 62443 cybersecurity certification gates access to European critical infrastructure procurement, filtering qualified suppliers to those with scaled R&D operations capable of sustaining multi-protocol compliance testing. Advanced node semiconductor fabrication concentrates in Taiwan and South Korea, while power module assembly localizes in Germany and China. Raw material dependencies include gallium nitride wafers, silicon carbide substrates, and marine-grade aluminum enclosures. Single-source vulnerability in Taiwan-based foundry capacity for security-enabled network processors exposes continuity risk. Distribution runs through industrial automation distributors and direct OEM contracts, with system integrator bundling gaining share in pharmaceutical and food processing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cybersecurity-certified platform vendors as IEC 62443 compliance costs and multi-protocol development timelines force niche communication specialists toward acquisition or exit.
For Market Incumbents: Deploy captive semiconductor foundry partnerships to secure gallium nitride supply allocations against emerging fabless competitors. Anchor distributor relationships in Hungary and Poland battery gigafactory corridors before greenfield specifications crystallize. Deepen over-the-air firmware update capabilities to capture fifteen-year service life cybersecurity monitoring revenue streams threatened by software-defined automation entrants. For New Entrants and Emerging Players: The gap between premium IEC 62443-4-2 SL2-certified modules and economy DeviceNet replacement units offers white-space opportunity for mid-tier cybersecurity-hardened alternatives. Target chemical processing brownfield estates in Ludwigshafen and Leverkusen where protocol translation demand outpaces incumbent service capacity. Pursue system integrator co-development partnerships to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: The window for entry favors protocol-specific communication specialists with established EtherCAT or Profinet certification assets before full-stack platform vendors complete portfolio consolidation. Long-term viability hinges on embedded cybersecurity engineering talent density and multi-protocol compliance breadth. Watch battery gigafactory construction permitting velocity in Central Europe as inflection indicator for synchronized motion control module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-SiC Hybrid Module Development | Enables 100kHz switching frequencies that unlock compact servo drive form factors for packaging machinery OEMs. |
| IEC 62443-4-2 SL2 Certification Investment | Secures procurement eligibility with German automotive Tier-1 suppliers under NIS2 Directive enforcement. |
| Battery Gigafactory Channel Partnership | Captures greenfield EtherCAT deployment demand in Hungary and Poland manufacturing corridors. |
| Over-the-Air Firmware Architecture | Satisfies EU Cyber Resilience Act mandatory vulnerability disclosure across fifteen-year module service lives. |
| Multi-Protocol Brownfield Integration | Competes for chemical processing retrofit contracts requiring DeviceNet-to-Ethernet translation capabilities. |
Research Methodology
Trade association filings, customs and trade flow databases, and SEC regulatory disclosures formed the secondary backbone, validated through primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and industrial distributor category managers. Bottom-up and top-down triangulation reconciled module shipment data against end-use industry capital expenditure patterns.
Bottom-up modeling aggregated product-type, protocol standard, and end-use industry segments across the projection horizon, while top-down validation cross-checked against regional industrial automation equipment spending. CAGRs derived from regression analysis of historical replacement cycle compression and greenfield deployment trajectories. Forecast inputs incorporated foundry capacity utilization rates for wide-bandgap semiconductors and NIS2 Directive compliance deadline impacts on European procurement timing.
Underlying measurement precision varies by segment; communication module volume estimates carry tighter precision than power module pricing given standardized product configurations versus project-customized explosion-rated variants. Forecasts reflect assumptions regarding semiconductor substrate allocation continuity and regulatory certification timeline stability. A model refresh is warranted upon material change in Taiwan foundry capacity utilization or EU cybersecurity directive enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.