
 Middle-East and Africa Nanosensors Market | 2026-2036
Middle-East and Africa Nanosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Nanosensors Market Outlook
CE marking under the EU Medical Device Regulation is redrawing competitive access for nanosensor suppliers targeting Gulf healthcare procurement channels. Robert Bosch GmbH leverages its automotive sensor heritage to transfer electrochemical detection platforms into industrial safety applications across the region. Texas Instruments Inc. sustains dominance in integrated signal conditioning circuits that bridge raw nanomaterial responses to processable data streams. SABIC anchors regional supply security through captive production of specialized polymer substrates that host nanostructured sensing layers.
Nanosensors are transduction devices with at least one functional dimension below 100 nanometers, typically fabricated through lithographic patterning or bottom-up self-assembly of metal oxides, carbon nanotubes, or quantum dots to detect chemical, biological, or physical stimuli at trace concentrations. Their primary commercial purpose spans real-time environmental contaminant tracking, point-of-care pathogen identification, and perimeter security screening where conventional sensors lack resolution. Optical sensors command premium positioning due to the complexity of plasmonic substrate engineering and alignment with Gulf petrochemical leak-detection mandates. Biosensors represent the fastest-expanding category, propelled by Saudi Arabia's biomanufacturing localization targets and South African tuberculosis diagnostic programs. Gas sensors retain mature volume status, particularly in UAE oilfield hydrogen sulfide monitoring, though margin compression from standardized electrochemical designs limits upside.
Saudi Food and Drug Authority (SFDA) registration requirements and South African Health Products Regulatory Authority (SAHPRA) quality benchmarks jointly determine which nanosensor platforms enter clinical and food-safety deployments across the region. The UAE's Ministry of Health and Prevention (MOHAP) medical device classification rules further fragment approval timelines, compelling suppliers to maintain parallel regulatory dossiers. Stakeholders must monitor how Gulf standardization bodies harmonize nanomaterial characterization protocols with EU REACH substance registration frameworks to avoid duplicated compliance expenditure.
Market Dynamics
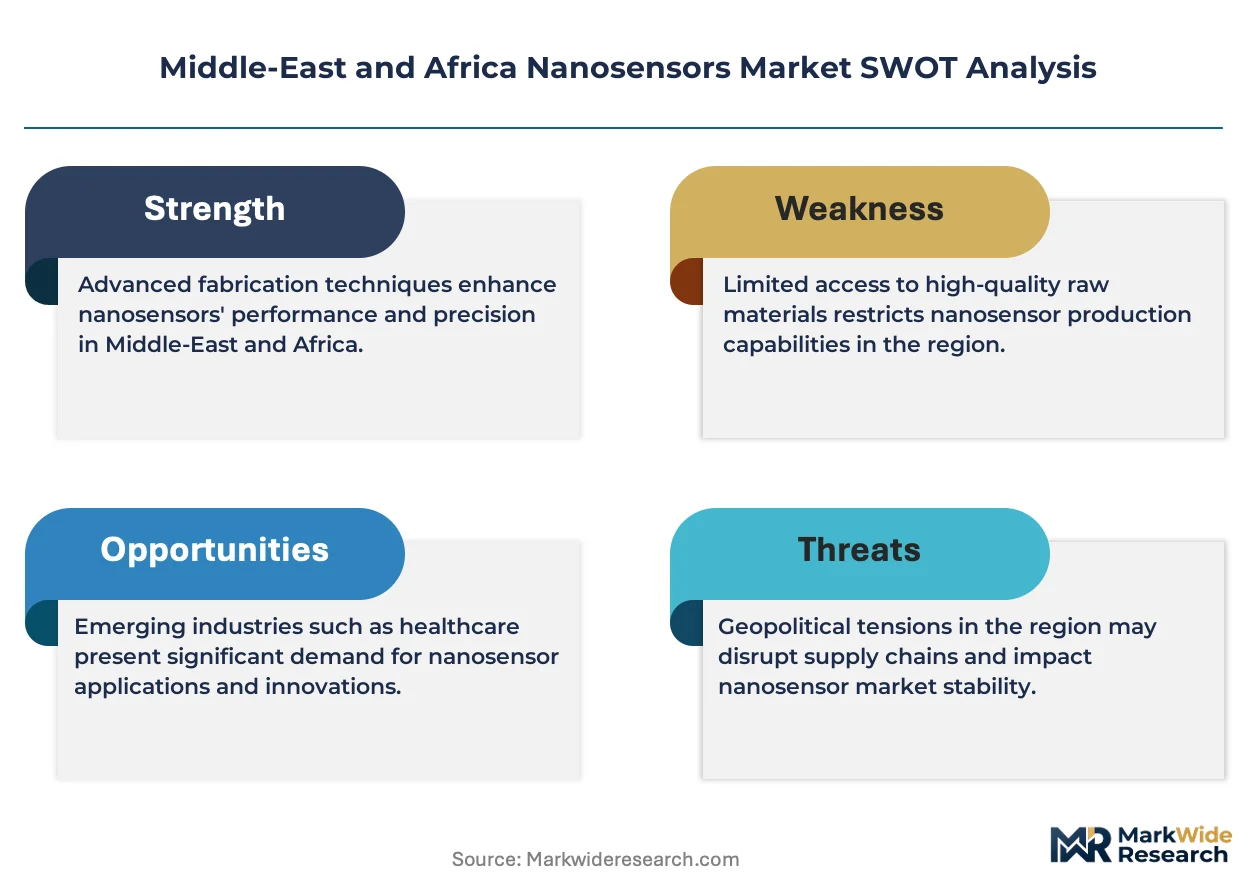
CE marking under the EU Medical Device Regulation is redrawing competitive access for nanosensor suppliers targeting Gulf healthcare procurement channels. This regulatory overlay forces parallel dossier maintenance across SFDA, SAHPRA, and MOHAP frameworks, compressing margins for entrants lacking established compliance infrastructure.
Growth Catalysts
- NEOM Infrastructure Mandates:Saudi Arabia's giga-project specifications embed nanosensor networks into smart city foundations from design phase, creating anchored demand for environmental and structural monitoring systems.
- EU AI Act Extraterritoriality:Import certification pathways for sensor-equipped medical devices entering Gulf markets now require algorithmic audit documentation, favoring suppliers with pre-established EU compliance.
- Carbon Nanotube Cost Curves:Bottom-up synthesis methods for CNT-based electrochemical sensors are achieving scale economies that enable point-of-care deployment in South African tuberculosis diagnostic programs.
Market Restraints
- Specialized Polymer Substrate Concentration:SABIC's captive production of host materials for nanostructured sensing layers creates single-source dependency for regional device fabricators.
- Plasmonic Engineering Skill Scarcity:Optical sensor fabrication requires rare expertise in noble metal nanopatterning that concentrates in European and East Asian supplier bases.
- Electrochemical Gas Sensor Commoditization:Standardized designs for hydrogen sulfide monitoring in UAE oilfields have compressed margins below sustainable levels for new entrants.
Strategic Opportunities
- Red Sea Project Greenfield Deployment:Tourism infrastructure construction offers first-mover positioning for integrated nanosensor networks without legacy system retrofit burdens.
- Biomanufacturing Localization Targets:Saudi Arabia's pharmaceutical sovereignty agenda creates demand for biosensor platforms in upstream bioprocess monitoring and quality control.
- Gulf Standardization Harmonization:Emerging alignment between regional nanomaterial characterization protocols and EU REACH substance registration frameworks promises consolidated compliance expenditure.
Industry Challenges
- Multi-Jurisdictional Certification Timelines:Parallel SFDA, SAHPRA, and MOHAP medical device classification rules fragment approval pathways and extend time-to-revenue for clinical nanosensor platforms.
- Signal Conditioning Integration Complexity:Bridging raw nanomaterial responses to processable data streams requires specialized analog front-end design expertise that concentrates at integrated circuit suppliers.
- REACH-Equivalent Substance Documentation:Gulf regulators are developing nanomaterial registry requirements without precedent clarity, creating regulatory uncertainty for importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Nanosensors Market |
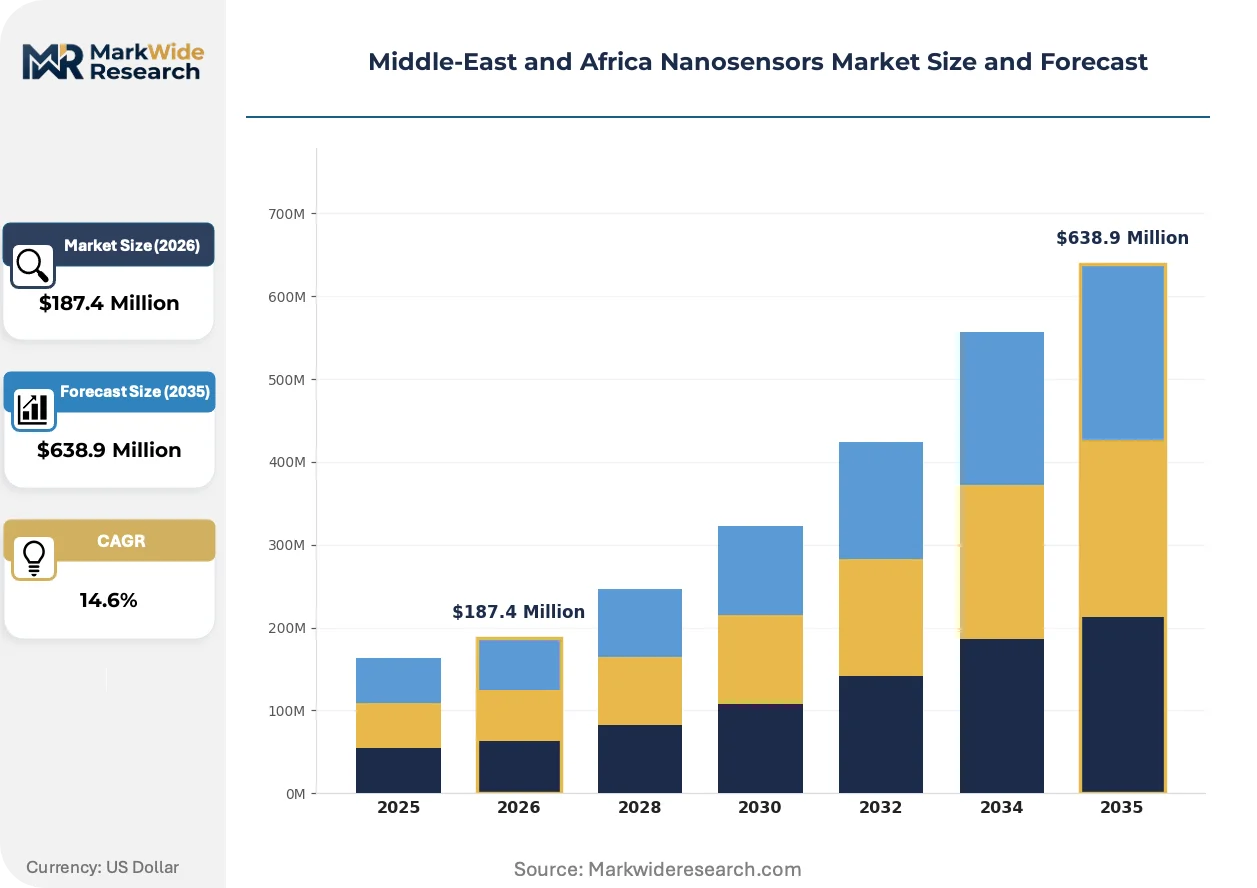
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Sensors, Chemical Sensors, Optical Sensors, Biosensors Application: Environmental Monitoring, Healthcare Diagnostics, Food Safety, Security End User: Healthcare Providers, Research Organizations, Industrial Manufacturers, Agricultural Firms Technology: Electrochemical, Optical, Nanomaterials, Surface Plasmon Resonance |
| Companies Covered | Analog Devices Inc., Robert Bosch GmbH, Denso Corporation, Omron Corp., STMicroelectronics, Honeywell International Inc., Texas Instruments Inc., SABIC, Saudi Aramco, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Nanosensors Market Strategic Shifts
Plasmonic substrate engineering is commanding premium positioning as Gulf petrochemical operators mandate sub-ppm leak detection resolution that conventional electrochemical methods cannot achieve. Three active developments are restructuring competitive positioning across the value chain.
Quantum dot fluorescence sensing is decomposing the dominance of label-dependent immunoassays in pathogen identification workflows. Saudi diagnostic laboratories are adopting CdSe/ZnS core-shell architectures for multiplexed respiratory panel testing. This displacement is compressing reagent cost structures while elevating capital equipment requirements for spectral detection hardware.
EU AI Act algorithmic transparency mandates are reshaping import certification for sensor-equipped medical devices entering Saudi and UAE markets. Device registrants must now submit technical documentation covering training data provenance and performance validation across demographic subgroups. Cardiovascular monitoring platforms with embedded nanosensor arrays face the steepest compliance escalation.
Hospital procurement consortia in South Africa are consolidating tuberculosis diagnostic instrument purchasing through centralized tender mechanisms. This concentration is displacing distributed point-of-care acquisition models that previously favored lower-throughput biosensor configurations. Gauteng and Western Cape provincial health authorities are driving the structural shift toward integrated laboratory automation.
Middle-East and Africa Nanosensors Market Segmentation
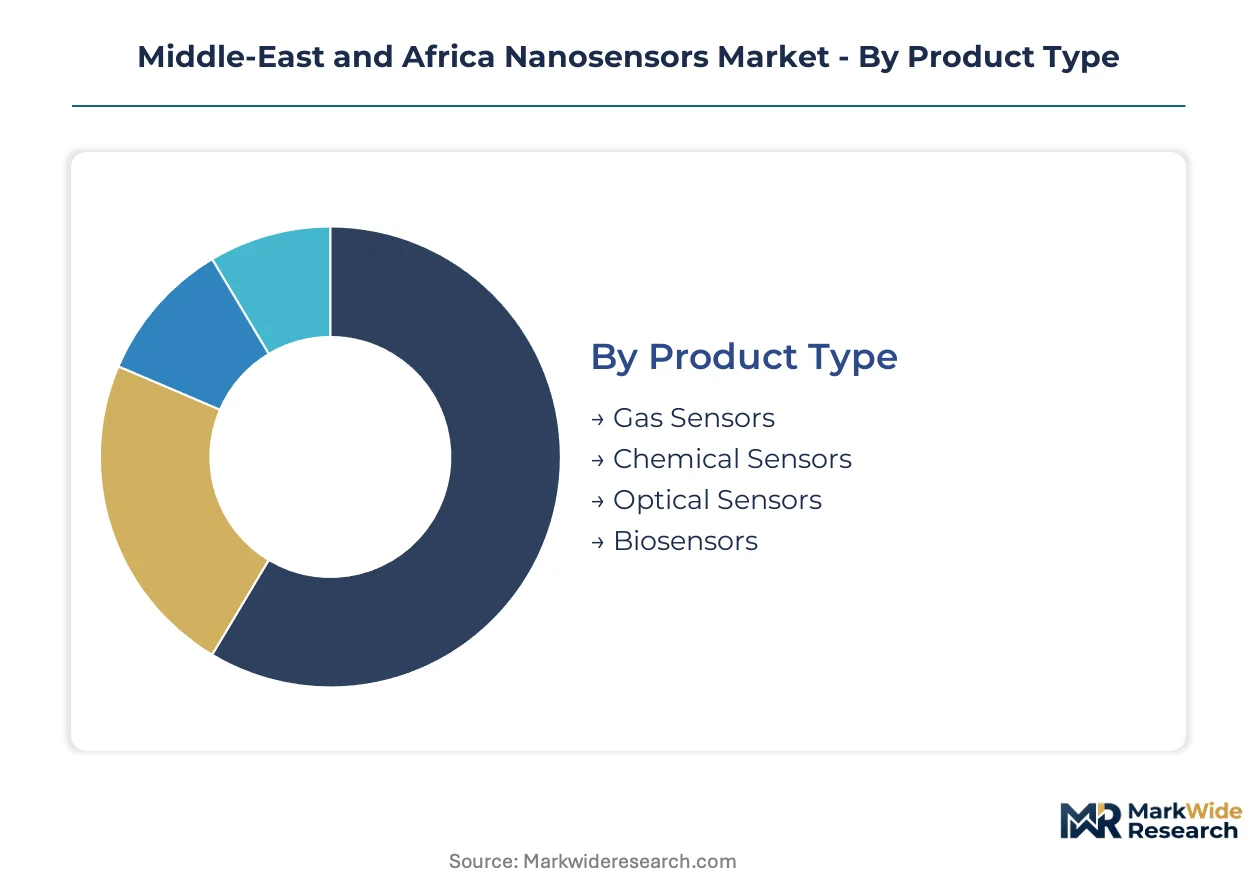
Nanosensor procurement across the Middle-East and Africa flows through distinct channel architectures that favor bundled system sales in Gulf healthcare and component supply in South African research markets. Understanding segment-channel alignment reveals where margin pools concentrate versus where volume scales.
Product Type:
Gas sensors move primarily through industrial distributor networks serving UAE and Saudi oilfield operators, while biosensors route through specialized medical device channels requiring SFDA pre-approval.
- Optical Sensors:Plasmonic substrates engineered with noble metal nanopatterns detect sub-ppm chemical leaks in Saudi Aramco and ADNOC facilities. Gulf petrochemical mandates for leak-detection resolution beyond electrochemical limits anchor demand in the premium tier.
- Biosensors:Electrochemical and fluorescence-based platforms identify pathogens at point-of-care in South African tuberculosis programs and Saudi biomanufacturing quality control. Saudi Arabia's pharmaceutical localization targets are accelerating platform adoption in upstream bioprocess monitoring.
- Gas Sensors:Standardized electrochemical designs for hydrogen sulfide monitoring dominate UAE oilfield deployments.
- Chemical Sensors:Metal oxide and carbon nanotube architectures track environmental contaminants in NEOM smart city infrastructure.
Gas sensors dominate installed base in industrial safety applications. Biosensors are where expansion concentrates as clinical procurement shifts toward molecular diagnostic platforms.
Application:
Cost tier stratification separates environmental monitoring as a capital-equipment sale from healthcare diagnostics as a consumables-driven recurring revenue stream.
- Healthcare Diagnostics:Multiplexed respiratory panels using quantum dot fluorescence displace label-dependent immunoassays in Saudi diagnostic laboratories. CdSe/ZnS core-shell architectures elevate capital equipment requirements while compressing per-test reagent costs.
- Environmental Monitoring:Distributed nanosensor networks embedded in NEOM and Red Sea Project infrastructure enable real-time air and water quality surveillance. Greenfield smart city construction eliminates legacy retrofit costs that burden brownfield deployments elsewhere.
- Food Safety:Pathogen detection platforms face fragmented approval pathways across SFDA, SAHPRA, and Gulf standardization bodies.
- Security:Perimeter screening applications for trace explosive and narcotic detection concentrate in UAE and Saudi critical infrastructure protection budgets.
Environmental monitoring commands the highest average contract value per deployment. Healthcare diagnostics is climbing the fastest as provincial health authorities in South Africa consolidate tuberculosis instrument purchasing.
End User:
Customer type determines procurement modality: healthcare providers buy through centralized tender, while research organizations acquire via grant-funded spot purchasing.
- Healthcare Providers:Hospital procurement consortia in Gauteng and Western Cape provinces are displacing distributed point-of-care acquisition with integrated laboratory automation. Centralized tender mechanisms favor higher-throughput biosensor configurations over lower-throughput alternatives.
- Industrial Manufacturers:Petrochemical operators in UAE and Saudi Arabia specify nanosensor networks in greenfield project engineering, procurement, and construction contracts.
- Research Organizations:Academic and national laboratory demand in South Africa concentrates on carbon nanotube synthesis scale-up for tuberculosis diagnostic development.
- Agricultural Firms:Soil and crop monitoring applications remain nascent, with pilot deployments in Saudi food security initiatives.
Healthcare providers anchor current revenue. Industrial manufacturers represent the steepest expansion trajectory as giga-project construction accelerates.
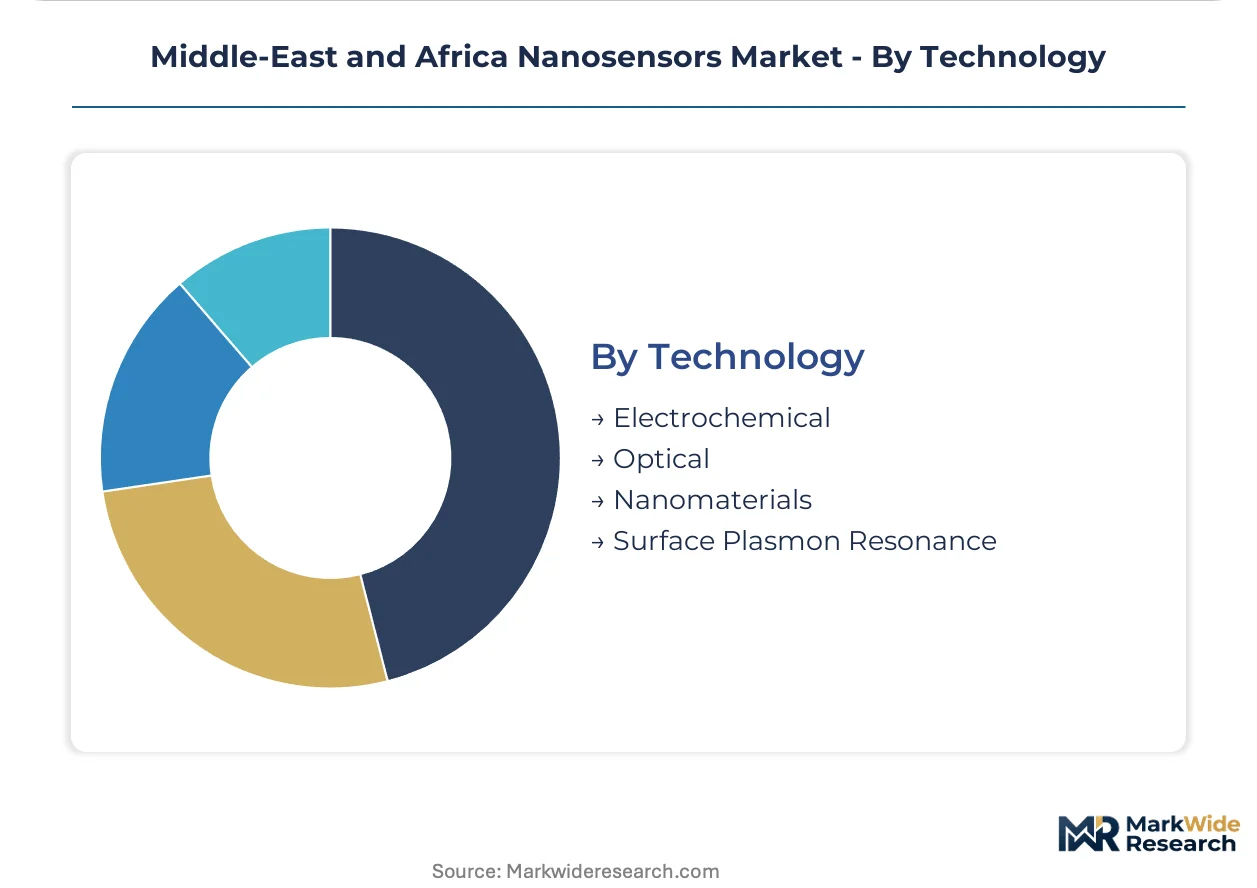
Technology:
Supply concentration in signal conditioning integrated circuits creates dependency on Texas Instruments and analog front-end specialists for all technology platforms.
- Electrochemical:Carbon nanotube cost curves from bottom-up synthesis methods are achieving scale economies that enable point-of-care deployment. South African tuberculosis programs and UAE hydrogen sulfide monitoring both rely on this platform, though margin compression in gas sensing limits supplier participation.
- Nanomaterials:Quantum dots and metal oxide nanoparticles form the functional sensing layer across optical and biosensor categories. SABIC's captive polymer substrate production creates regional supply security for device fabricators.
- Optical:Plasmonic engineering expertise concentrates in European and East Asian supplier bases, creating capability scarcity for Gulf-based system integrators.
- Surface Plasmon Resonance:Label-free biomolecular interaction detection remains concentrated in pharmaceutical R&D applications with limited point-of-care penetration.
Electrochemical platforms dominate unit volume. Nanomaterials are gaining share fastest as multi-functional sensing layers displace single-purpose transduction elements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial procurement consortia and healthcare system consolidators anchor nanosensor demand across the Middle-East and Africa, with project-based Gulf buyers and South African provincial health authorities driving divergent channel architectures.
Saudi Arabia
NEOM and the Red Sea Project mandate embedded nanosensor networks for environmental and structural monitoring from the design phase. SFDA medical device registration requirements force parallel dossier maintenance for clinical platforms. Riyadh and the Eastern Province concentrate petrochemical operator procurement for leak-detection systems.
United Arab Emirates
ADNOC facilities specify sub-ppm chemical leak detection that elevates plasmonic optical sensor demand above electrochemical alternatives. MOHAP medical device classification rules fragment approval timelines for diagnostic imports. Dubai and Abu Dhabi anchor oilfield hydrogen sulfide monitoring deployments and critical infrastructure security screening budgets.
South Africa
Gauteng and Western Cape provincial health authorities consolidate tuberculosis diagnostic instrument purchasing through centralized tender mechanisms. SAHPRA quality benchmarks determine biosensor platform eligibility for clinical deployment. Academic and national laboratory demand in Pretoria and Cape Town concentrates on carbon nanotube synthesis scale-up for point-of-care development.
Israel
Research-intensive institutions drive quantum dot fluorescence sensing adoption for multiplexed pathogen identification workflows. National nanomaterial characterization protocols align with EU REACH substance registration frameworks to streamline import compliance. Tel Aviv and Haifa clusters host plasmonic engineering expertise for optical substrate development.
Egypt
Food security initiatives pilot soil and crop monitoring applications with nascent nanosensor deployment in agricultural zones. The country's national pharmaceutical regulator develops nanomaterial registry requirements without precedent clarity. Cairo and Alexandria industrial zones attract component supply relationships for regional device fabricators.
Middle-East and Africa Nanosensors Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with sensor divisions alongside specialized semiconductor fabricators. The competitive terrain bifurcates between integrated system suppliers serving Gulf petrochemical operators and component specialists feeding South African research markets. Three archetypes dominate: automotive heritage players transferring electrochemical platforms, integrated circuit suppliers controlling signal conditioning, and captive polymer substrate producers. Capacity expansion in carbon nanotube synthesis and strategic partnerships for regulatory dossier sharing constitute the dominant competitive moves.
Among diversified industrial conglomerates, Robert Bosch GmbH and Honeywell International Inc. occupy positions that leverage automotive and aerospace sensor heritage for industrial safety applications. Texas Instruments Inc. anchors the integrated circuit tier where analog front-end design expertise concentrates. SABIC exemplifies the captive supply archetype through in-house production of specialized polymer substrates that host nanostructured sensing layers for regional device fabricators.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Robert Bosch GmbH |
| Denso Corporation |
| Omron Corp. |
| STMicroelectronics |
| Honeywell International Inc. |
| Texas Instruments Inc. |
| SABIC |
| Saudi Aramco |
| Others |
Value Chain & Pricing Dynamics
Ninety-day polymer substrate lead times for SABIC's specialized sensing-layer host materials concentrate pricing power with captive suppliers and compress margin flexibility for regional device fabricators. This inventory-to-pricing coupling intensifies as Gulf healthcare procurement shifts toward bundled system contracts with strict cost-plus indexation clauses.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate procurement for nanosensor-equipped medical devices entering Saudi and UAE hospital systems. Three-tier pricing structure across premium plasmonic optical systems, standard electrochemical platforms, and economy gas sensors differentiates by certification tier and after-sales service bundling. Price erosion runs through standardized hydrogen sulfide monitors as UAE oilfield operators consolidate vendor panels. Research organizations in South Africa exhibit highest price sensitivity due to grant-funded spot purchasing, while Gulf petrochemical operators show lowest sensitivity given greenfield project budgets.
Supply Chain Analysis
Strategic stockpiling of noble metal nanopatterning precursors prevails among optical sensor fabricators, contrasting with just-in-time carbon nanotube feedstock management for electrochemical platforms. Manufacturing concentrates in Germany, Japan, and Taiwan for signal conditioning integrated circuits; Saudi Arabia and South Africa for final device assembly; and China for quantum dot raw materials. Supply chains rest on SABIC's captive polymer substrate production and Texas Instruments' analog front-end dominance. Single-source vulnerability in plasmonic engineering expertise creates chokepoint risk. Distribution runs through industrial distributor networks for oilfield gas sensors and specialized medical device channels for SFDA-pre-approved biosensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement consortia in South Africa and bundled EPC contracting in Saudi giga-projects, fragmenting access for unaligned suppliers.
For Market Incumbents: Secure parallel SFDA-MOHAP-SAHPRA regulatory dossier infrastructure to defend against EU AI Act compliance-anchored entrants. Deepen backward integration into carbon nanotube synthesis capacity in Saudi Arabia to offset SABIC substrate pricing leverage. Channel control through exclusive distributor agreements for UAE oilfield hydrogen sulfide monitoring represents the critical defensive lever. For New Entrants and Emerging Players: Lead with quantum dot fluorescence platforms for South African tuberculosis diagnostic tenders, where provincial consolidation favors new capital equipment suppliers over incumbent reagent providers. The Red Sea Project's greenfield smart city construction offers the most penetrable geography without legacy retrofit burdens. A go-to-market angle anchored on EU AI Act pre-certification documentation accelerates Gulf healthcare access. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because multi-jurisdictional certification timelines create durable moats for dossier-heavy suppliers. Acquisition targets should concentrate on mid-cap electrochemical specialists with existing SFDA registrations and carbon nanotube synthesis scale. The signal to monitor is harmonization between Gulf nanomaterial characterization protocols and EU REACH frameworks, which would consolidate compliance expenditure and favor pre-aligned portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Regulatory Dossier Investment | SFDA-MOHAP-SAHPRA alignment reduces time-to-revenue for clinical nanosensor platforms entering Gulf markets. |
| Backward Integration into CNT Synthesis | Captive carbon nanotube production in Saudi Arabia mitigates SABIC polymer substrate pricing leverage. |
| EU AI Act Pre-Certification | Algorithmic audit documentation accelerates import pathways for sensor-equipped medical devices entering UAE and Saudi Arabia. |
| Plasmonic Engineering Partnership | Access to European noble metal nanopatterning expertise addresses capability scarcity for Gulf optical sensor integrators. |
| Provincial Tender Consolidation Alignment | Positioning for Gauteng and Western Cape centralized tuberculosis diagnostic purchasing displaces distributed point-of-care models. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers at Saudi diagnostic laboratories, SFDA regulatory affairs specialists, UAE oilfield procurement managers, and South African provincial health authority tender officers, then refined through secondary validation. Sources included SFDA medical device registration databases, SAHPRA quality benchmark filings, EU AI Act technical documentation requirements, and Gulf petrochemical operator EPC contract specifications. Bottom-up demand modeling across application segments triangulated with top-down market sizing from integrated circuit supplier revenue disclosures.
Variance decomposition across product type, application, technology platform, and end-user procurement modality structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs incorporated NEOM infrastructure deployment timelines and South African tuberculosis diagnostic instrument replacement cycles.
Forecasts assume regulatory continuity in SFDA, MOHAP, and SAHPRA medical device classification regimes; material policy shifts would require re-modeling. Specific risks include REACH-equivalent nanomaterial registry implementation without precedent clarity and Gulf standardization body harmonization delays. Revision becomes warranted when carbon nanotube synthesis cost curves or EU AI Act extraterritorial enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Aspiration Control Systems Market