
 Capacitive Ceramic Pressure Sensors Market | 2026-2036
Capacitive Ceramic Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Ceramic Pressure Sensors Market Outlook
A capital-intensity divergence between in-house ceramic substrate fabricators and outsourced assembly houses is redrawing competitive boundaries in the capacitive ceramic pressure sensors landscape. Sensata Technologies leverages captive alumina ceramic production to sustain margin control across automotive grade portfolios. Nanjing Jiucheng Technology Co. Limited anchors its position through cost-optimized gauge sensor lines serving domestic industrial automation demand. BD|SENSORS GmbH differentiates via precision differential sensor calibration for process monitoring applications in European chemical plants.
Capacitive ceramic pressure sensors translate mechanical pressure into electrical capacitance variation using alumina or zirconia ceramic diaphragms bonded to capacitive electrode structures, typically achieving accuracy within 0.1% full scale across temperature ranges from minus forty to one hundred twenty five degrees Celsius. These devices primarily enable precise pressure measurement in corrosive media environments where metallic diaphragms degrade. Absolute sensors dominate aerospace and medical device installations where vacuum-referenced measurement protects critical systems. MEMS technology variants represent the fastest-expanding category as semiconductor fabrication methods shrink ceramic cell dimensions while preserving media compatibility. Fluid control applications command the deepest margin pools due to certification requirements for food-contact and pharmaceutical-grade sensor materials.
FDA 21 CFR Part 820 quality system regulations govern medical device sensor submissions in the United States, while REACH and RoHS frameworks restrict hazardous substance content in ceramic formulations sold across European Union member states. China's GB standards for industrial automation equipment mandate electromagnetic compatibility testing that shapes digital output sensor design priorities. Stakeholders must monitor evolving automotive functional safety standards and regional carbon border adjustment mechanisms that could alter ceramic raw material sourcing economics.
Market Dynamics
Automotive electrification programs in Germany and China are accelerating OEM procurement of ceramic pressure sensors for battery thermal management systems, compressing traditional industrial demand share.
Growth Catalysts
- REACH compliance requirements:European material selection protocols for ceramic sensing elements are forcing substrate upgrades that improve corrosion resistance ratings.
- MEMS-compatible ceramic fabrication:China's Yangtze River Delta manufacturing corridor is scaling semiconductor-processed ceramic cells that preserve media compatibility at reduced dimensions.
- Battery thermal management:Automotive OEMs in Germany and China are specifying absolute ceramic sensors for vacuum-referenced protection of critical EV systems.
Market Restraints
- Alumina raw material concentration:High-purity alumina supply concentrates in select Chinese and Brazilian mining jurisdictions, exposing fabricators to export control volatility.
- Technical limitation of zirconia brittleness:Zirconia ceramic diaphragms exhibit fracture susceptibility under rapid thermal cycling, constraining aerospace deployment.
- Substitution threat from silicon piezoresistive:Silicon MEMS pressure sensors are capturing cost-sensitive gauge applications below 10 bar measurement range.
Strategic Opportunities
- Pharmaceutical-grade certification:FDA 21 CFR Part 820 quality system regulations create barrier-protected margin pools for food-contact and pharmaceutical sensor materials.
- Process monitoring in European chemical plants:ECHA enforcement of REACH substance restrictions is displacing metallic diaphragm sensors in corrosive media environments.
- Digital output sensor design:China's GB standards for electromagnetic compatibility are mandating signal conditioning integration that opens module-level value capture.
Industry Challenges
- Functional safety certification timelines:Automotive ISO 26262 ASIL ratings require 18-24 month validation cycles that delay revenue recognition for new sensor platforms.
- MEMS process integration complexity:Ceramic foundries face yield degradation when bonding alumina diaphragms to silicon electrode structures at wafer scale.
- Carbon border adjustment exposure:EU CBAM mechanisms threaten to alter alumina and zirconia raw material sourcing economics for non-European fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Ceramic Pressure Sensors Market |
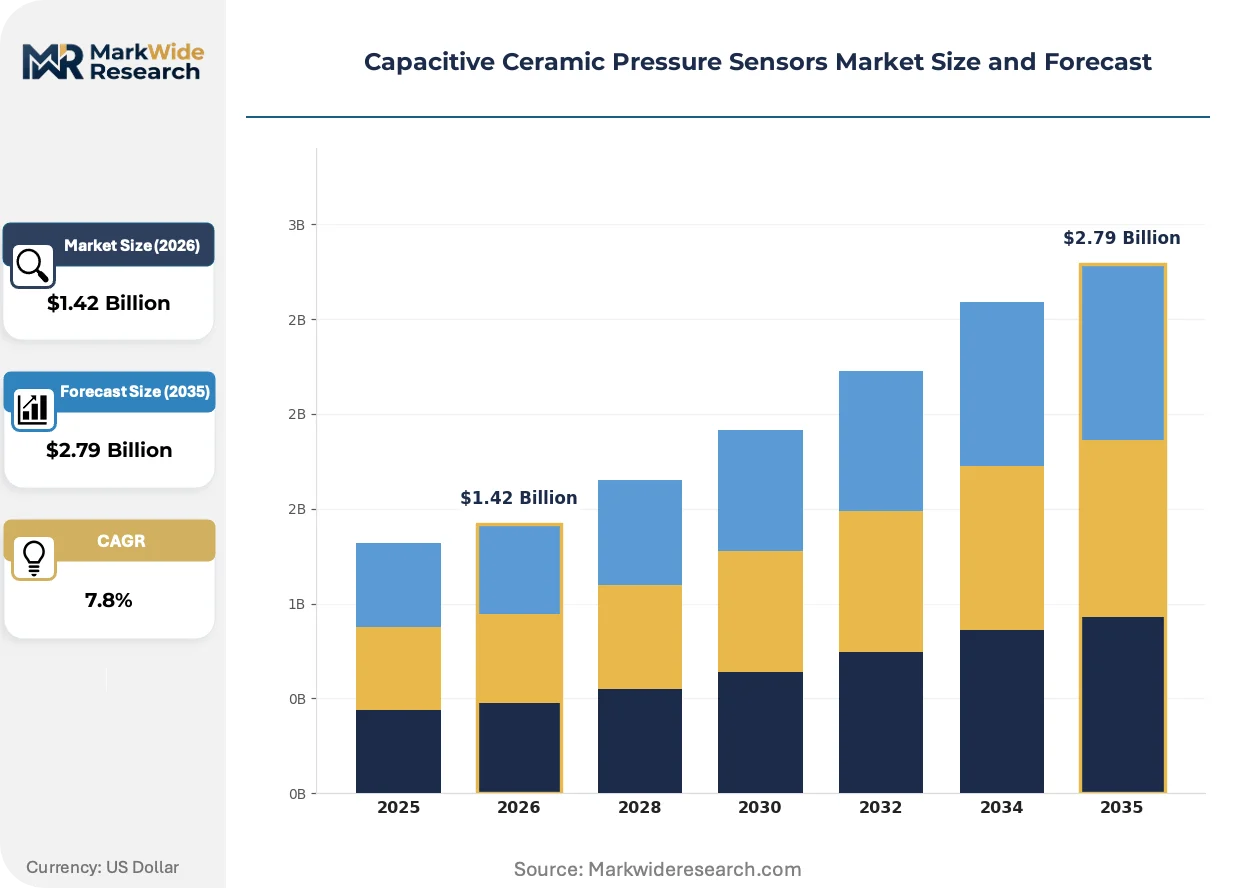
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Gauge Sensors, Differential Sensors, Multichannel Sensors End User: Aerospace, Automotive, Industrial Automation, Medical Devices Technology: Digital, Analog, Wireless, MEMS Application: Fluid Control, Process Monitoring, Environmental Testing, Structural Health Monitoring |
| Companies Covered | Vega Americas Inc., Sensata Technologies, Nanjing Jiucheng Technology Co. Limited, Metallux SA, Angst+Pfister Sensors and Power AG, Setra Systems, ACS Control-System GmbH, BD|SENSORS GmbH, ifm electronic gmbh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Ceramic Pressure Sensors Market Strategic Shifts
Semiconductor fabrication methods are penetrating ceramic sensor manufacturing, while regulatory frameworks in major economies tighten material purity and traceability requirements.
MEMS-processed ceramic pressure cells are fragmenting the traditional macro-scale sensor architecture. These devices bond sub-millimeter alumina diaphragms to capacitive electrode structures using wafer-level packaging. Automotive battery management system designers in Germany and China are adopting them for space-constrained thermal loop monitoring. The technology is fragmenting vendor specialization between semiconductor foundries and legacy ceramic houses.
REACH substance restrictions are reshaping European ceramic formulation protocols. ECHA enforcement of candidate list substances limits heavy metal stabilizers in zirconia toughened alumina composites. Medical device and food-contact sensor manufacturers face reformulation costs and supply qualification delays. German chemical plant operators are responding by consolidating procurement with REACH-certified ceramic sensor suppliers.
Specification consolidation among tier-one automotive OEMs is compressing supplier qualification cycles. Battery thermal management programs in China and Germany now mandate AEC-Q100 stress test compliance and PPAP submission within 12-month windows. Direct OEM engineering relationships are displacing tier-two module integrator channels. This pattern concentrates most visibly in Yangtze River Delta manufacturing clusters serving domestic EV platforms.
Capacitive Ceramic Pressure Sensors Market Segmentation
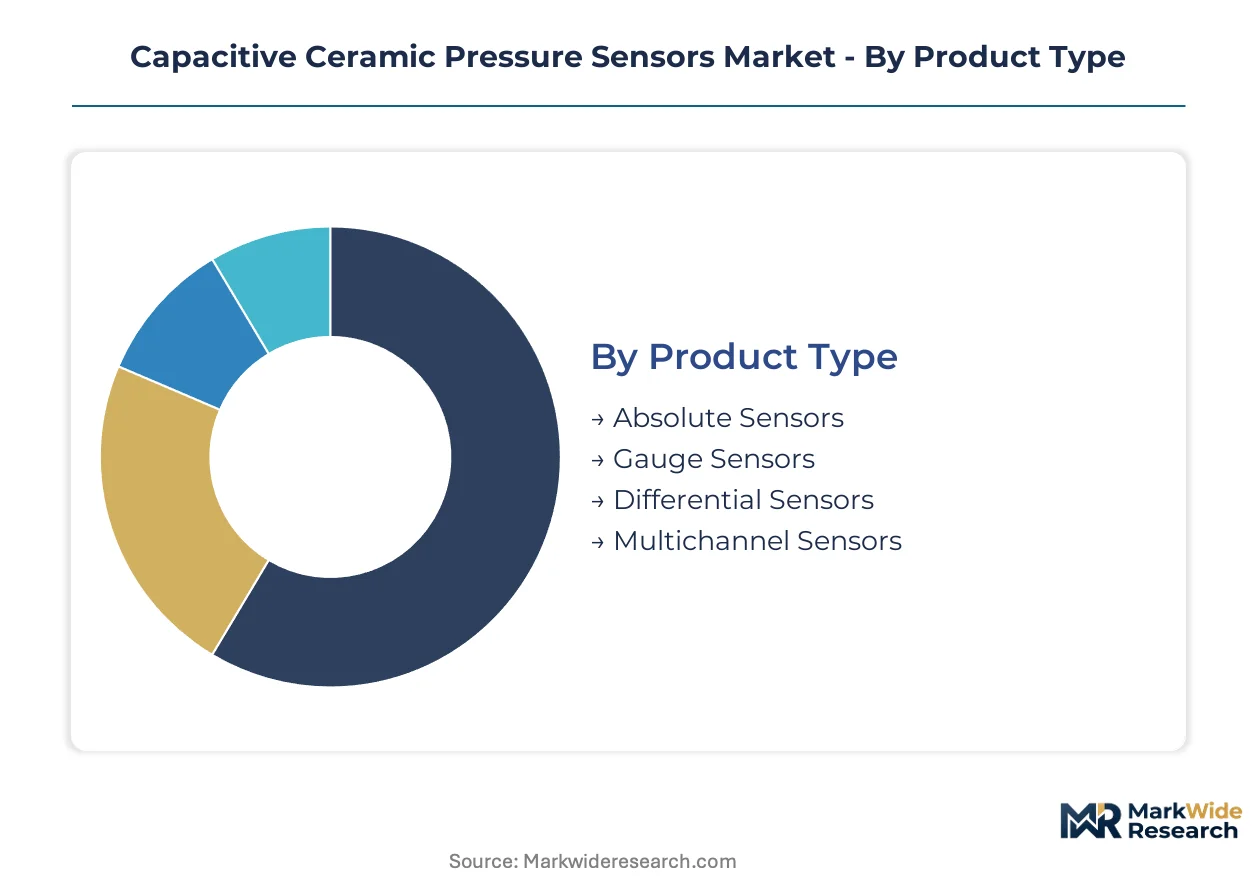
Segmentation in capacitive ceramic pressure sensors reveals distinct procurement channels for each product architecture. OEM battery programs, industrial distributors, and medical device contract manufacturers each source different sensor configurations based on certification requirements and integration complexity.
Product Type:
Channel mix varies sharply by sensor architecture, with absolute sensors flowing through aerospace and medical OEM direct contracts while gauge sensors dominate industrial distributor networks.
- Absolute Sensors:Vacuum-referenced measurement using sealed ceramic diaphragms bonded to capacitive electrode structures achieves accuracy within 0.1% full scale. Demand concentrates in German and Chinese automotive electrification programs for battery thermal management systems where vacuum-referenced protection prevents thermal runaway.
- Gauge Sensors:Ventilated ceramic diaphragms measure pressure relative to atmospheric conditions using alumina or zirconia substrates. China's Yangtze River Delta manufacturing corridor anchors procurement for domestic industrial automation demand where cost-optimized lines compete with silicon piezoresistive alternatives.
- Differential Sensors:Dual-diaphragm architectures measure pressure differences across process barriers in European chemical plants subject to REACH substance restrictions.
- Multichannel Sensors:Integrated ceramic cell arrays enable simultaneous multi-point pressure mapping for structural health monitoring in aerospace applications.
Absolute sensors dominate installed base in safety-critical applications. Gauge sensors are where expansion concentrates as industrial automation scales in China.
End User:
Cost tiers separate these segments, with aerospace and medical commanding certification-premium pricing while automotive and industrial automation compete on volume scale.
- Aerospace:Zirconia-toughened alumina diaphragms withstand extreme temperature cycling from minus forty to one hundred twenty five degrees Celsius. Demand concentrates in vacuum-referenced absolute sensor installations for flight-critical systems where metallic diaphragm degradation poses unacceptable risk.
- Automotive:MEMS-compatible ceramic fabrication lines in Germany and China supply battery thermal management sensors with AEC-Q100 stress test compliance. OEM procurement is compressing traditional tier-two module integrator channels.
- Industrial Automation:Gauge and differential sensors serve process monitoring in corrosive media environments where REACH compliance displaces metallic alternatives.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations govern submissions for implantable and diagnostic equipment using pharmaceutical-grade ceramic formulations.
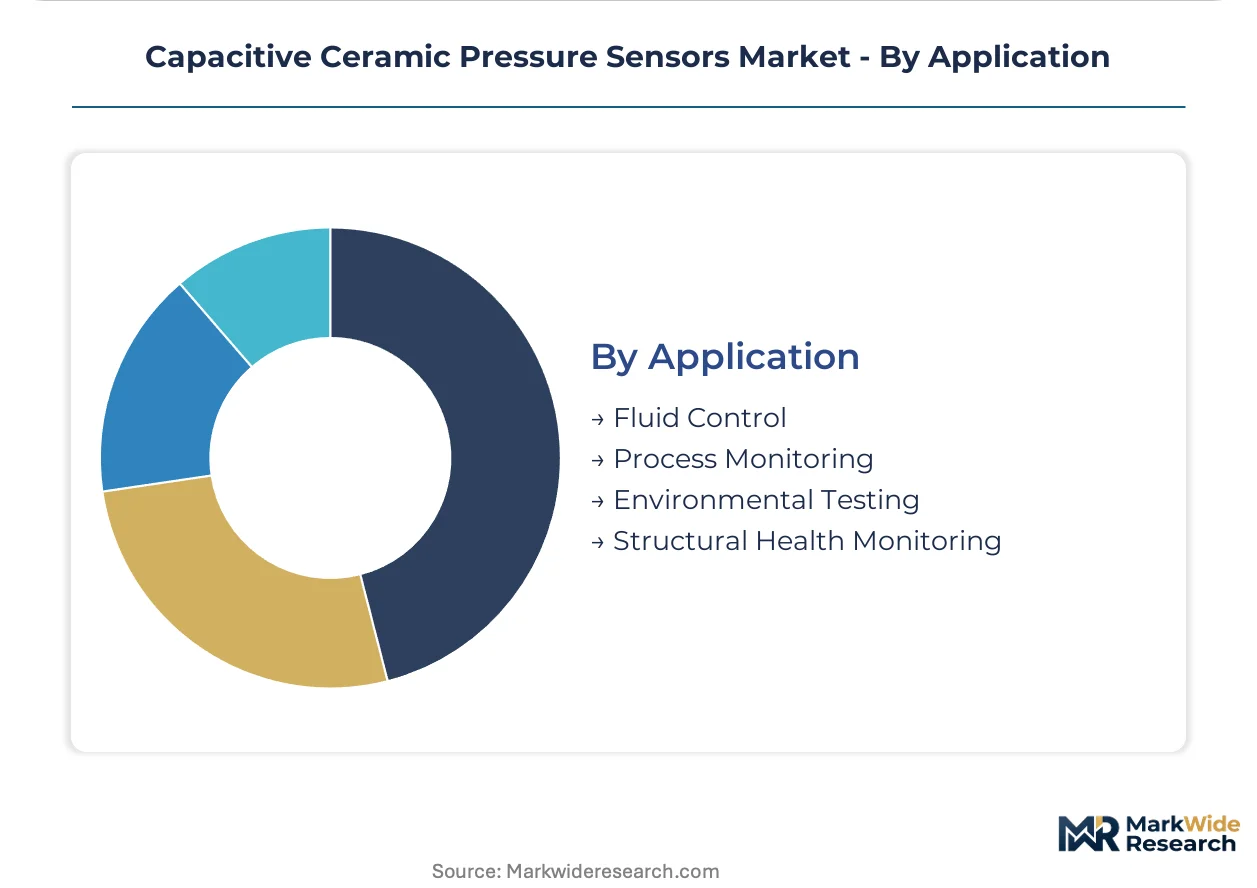
Aerospace and medical devices capture the deepest margin pools. Automotive is climbing the fastest as electrification programs accelerate OEM procurement cycles.
Technology:
Volume concentration favors analog outputs for legacy industrial equipment while digital and MEMS variants capture design wins in new automotive and medical platforms.
- Digital:Integrated signal conditioning with electromagnetic compatibility certification under China's GB standards enables module-level value capture in automotive battery management systems.
- Analog:Raw capacitance output sensors serve cost-sensitive industrial gauge applications below 10 bar measurement range where silicon piezoresistive alternatives threaten substitution.
- Wireless:Battery-powered ceramic pressure nodes enable distributed monitoring in hazardous chemical environments without signal cable infrastructure.
- MEMS:Wafer-level packaging of sub-millimeter alumina diaphragms preserves media compatibility at reduced dimensions for space-constrained thermal loop monitoring.
Analog sensors dominate legacy installed base. MEMS technology is gaining share fastest as semiconductor fabrication methods penetrate ceramic sensor manufacturing.
Application:
Customer type separation distinguishes fluid control and pharmaceutical applications with food-contact certification requirements from industrial process monitoring.
- Fluid Control:Pharmaceutical-grade ceramic formulations with FDA 21 CFR Part 820 compliance enable barrier-protected margin pools in food-contact and medical device sensor materials.
- Process Monitoring:Differential sensor calibration for corrosive media in European chemical plants responds to ECHA enforcement of REACH substance restrictions.
- Environmental Testing:Absolute sensors with vacuum reference support altitude simulation and climate chamber validation for aerospace component qualification.
- Structural Health Monitoring:Multichannel ceramic arrays map pressure distribution across aircraft wings and civil infrastructure for fatigue detection.
Fluid control commands the deepest margin pools due to certification requirements. Process monitoring is where expansion concentrates as REACH compliance reshapes European material selection protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command pricing premiums for AEC-Q100 certified ceramic sensors while Chinese fabricators compete on volume scale in industrial gauge applications. This asymmetry shapes procurement patterns across major demand centers.
Germany
Battery thermal management programs at BMW and Volkswagen drive absolute sensor demand for vacuum-referenced EV protection. KBA vehicle-type approval regulations mandate functional safety documentation that compresses supplier qualification timelines. Bavaria's Munich-Stuttgart corridor hosts captive alumina ceramic production serving tier-one automotive contracts.
China
Domestic EV platforms from BYD and NIO accelerate MEMS-compatible ceramic cell procurement for space-constrained battery monitoring. MIIT GB standards for electromagnetic compatibility shape digital output sensor design priorities. The Yangtze River Delta manufacturing cluster scales semiconductor-processed ceramic fabrication lines serving both automotive and industrial automation demand.
United States
Medical device manufacturers in Minnesota and California source pharmaceutical-grade ceramic formulations for implantable pressure monitoring. FDA 21 CFR Part 820 quality system regulations govern sensor submissions with 18-month validation cycles. Greater Boston anchors precision differential sensor development for aerospace flight-critical systems.
Switzerland
Swissmedic medical device regulations create barrier-protected margin pools for food-contact sensor materials in pharmaceutical manufacturing. Precision instrumentation demand from Roche and Novartis supply chains drives high-accuracy absolute sensor procurement. The Basel-Zurich corridor concentrates cleanroom ceramic fabrication for diagnostic equipment.
Japan
Automotive electrification at Toyota and Honda shifts procurement toward ceramic sensors for hybrid battery thermal loops. METI carbon neutrality roadmaps pressure raw material sourcing transparency in alumina supply chains. The Nagoya-Toyota industrial zone integrates ceramic sensor modules into powertrain control systems.
Capacitive Ceramic Pressure Sensors Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. The vendor base separates between captive ceramic substrate fabricators sustaining margin control and outsourced assembly houses competing on volume scale. Three strategic archetypes dominate: integrated material-to-module producers, regional cost-optimized gauge specialists, and precision calibration houses serving process industries. M&A activity concentrates on semiconductor foundries acquiring ceramic fabrication capabilities, while capacity expansion focuses on MEMS-compatible cleanroom lines in China and Germany.
Among German precision specialists, BD|SENSORS GmbH and ACS Control-System GmbH occupy positions within the differential calibration tier serving European chemical plant demand. Sensata Technologies exemplifies the integrated archetype through captive alumina production, while Nanjing Jiucheng Technology Co. Limited represents cost-optimized gauge fabrication for China's industrial automation market. These three anchors illustrate the geographic and technological segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Vega Americas Inc. |
| Sensata Technologies |
| Nanjing Jiucheng Technology Co. Limited |
| Metallux SA |
| Angst+Pfister Sensors and Power AG |
| Setra Systems |
| ACS Control-System GmbH |
| BD|SENSORS GmbH |
| ifm electronic gmbh |
| Others |
Value Chain & Pricing Dynamics
Silicon piezoresistive substitution in sub-10 bar gauge applications is simultaneously redrawing supply geography toward semiconductor foundries and compressing pricing economics for legacy ceramic houses serving cost-sensitive industrial automation demand.
Pricing Analysis
Configured-to-order absolute sensors for automotive battery thermal management command premium spreads of 40-60% above standard gauge lines due to AEC-Q100 certification and 18-24 month PPAP validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 820 compliant medical grades from REACH-certified industrial variants and uncalibrated OEM bulk supply. Pricing pressure stems from silicon MEMS incursion below 10 bar measurement range where ceramic media compatibility advantages diminish. Industrial automation distributors exhibit highest price sensitivity, while aerospace and medical OEMs prioritize traceability and certification over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive procurement from Germany and China, while medical device manufacturers maintain strategic stockpiles of pharmaceutical-grade alumina substrates to buffer 18-month FDA validation timelines. High-purity alumina supply concentrates in Chinese and Brazilian mining jurisdictions, with zirconia stabilization chemicals drawing from South African and Russian sources. Single-source vulnerability concentrates in Yangtze River Delta MEMS-compatible ceramic fabrication lines serving dual automotive and industrial demand. Distribution runs through tier-one automotive OEM direct contracts for absolute sensors and industrial distributor networks for gauge variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent ceramic sensor manufacturers face a substitution defense imperative against silicon MEMS technology encroaching from below, requiring strategic repositioning toward certification-protected premium tiers.
For Market Incumbents: Secure captive alumina substrate production to sustain margin control against outsourced assembly house competition in China's Yangtze River Delta. Accelerate REACH-compliant formulation portfolios to exploit ECHA enforcement displacing metallic diaphragm alternatives in European chemical plants. Prioritize AEC-Q100 certification investment for automotive battery thermal management contracts compressing traditional tier-two channels. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade ceramic formulations for FDA 21 CFR Part 820 compliant medical device applications where validation barriers protect margin pools. Target process monitoring differential sensors in European chemical plants responding to REACH substance restrictions with consolidated procurement. Pursue direct OEM engineering relationships in German automotive electrification programs bypassing displaced module integrators. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated material-to-module producers with captive ceramic fabrication and semiconductor-processed MEMS capabilities. Long-term viability hinges on exposure to automotive electrification and medical device certification moats rather than commoditized industrial gauge supply. Monitor silicon MEMS technology advancement in corrosive media compatibility as the critical inflection signal threatening ceramic substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-Compatible Cleanroom Expansion | Wafer-level alumina diaphragm bonding preserves media compatibility at reduced dimensions for automotive battery monitoring. |
| REACH-Certified Formulation Investment | ECHA substance restriction compliance displaces metallic alternatives in European chemical plant process monitoring. |
| AEC-Q100 Validation Acceleration | Compressed 12-month PPAP windows at BMW and Volkswagen concentrate procurement with qualified ceramic sensor suppliers. |
| Pharmaceutical-Grade Material Qualification | FDA 21 CFR Part 820 quality systems create barrier-protected margin pools in implantable pressure monitoring devices. |
| Backward Integration into Alumina Substrates | Captive high-purity ceramic production insulates margin control from Chinese and Brazilian raw material export volatility. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with ceramic sensor procurement managers at German automotive OEMs, biomedical engineers at US medical device manufacturers, and process control engineers at European chemical plants; and secondary validation through SEC filings of listed sensor manufacturers, MIIT GB standard documentation, ECHA REACH substance restriction updates, and FDA 510(k) submission databases. Bottom-up unit economics triangulated against top-down market sizing across product architecture, end-use vertical, and regional production cluster dimensions.
Across the projection horizon, the analytical framework modeled volume and value trajectories by sensor type (absolute, gauge, differential, multichannel), technology tier (analog, digital, MEMS, wireless), and application segment (fluid control, process monitoring, environmental testing, structural health). CAGRs derived from regression analysis of historical procurement patterns, OEM platform ramp schedules, and regulatory compliance timeline impacts. Industry-specific forecast inputs included AEC-Q100 stress test adoption curves and REACH candidate list substance restriction enforcement trajectories.
The analysis sits within stated boundaries; outcomes outside continued automotive electrification investment, stable alumina raw material export flows, and sustained REACH enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding MEMS process yield improvements and silicon piezoresistive corrosion resistance advancement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
RET Controller Market