
 Digital Angle Gauge Market | 2026-2036
Digital Angle Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Angle Gauge Market Insights
Chinese electronics manufacturing is expanding its output of MEMS-based digital angle gauges, creating ripple effects across global component supply chains. Bosch Power Tools leverages its sensor integration expertise to dominate premium professional segments across European job sites. Mitutoyo Corporation anchors high-precision metrology applications with calibration-grade instruments that sustain margins in aerospace inspection workflows. Starrett competes in North American industrial distribution through specialized angle measurement products with hardened alloy construction.
A digital angle gauge measures angular displacement between two surfaces using electronic sensors, typically achieving resolution of 0.1 degrees or finer through accelerometer or gyroscopic elements housed in machined aluminum or reinforced polymer enclosures. The device translates gravitational or inertial reference data into digital readouts for machinery setup, structural alignment, and quality verification tasks. Inclinometer variants lead volume shipments due to their utility in construction grading and equipment leveling, while MEMS technology segments capture expanding share as solid-state designs displace traditional pendulum mechanisms in portable tools. Electronic level applications in semiconductor fabrication equipment command the deepest margin pools because cleanroom-certified units require hermetic sealing and traceable calibration protocols.
ISO 9001 quality management standards and NIST-traceable calibration requirements shape product specifications for industrial-grade digital angle gauges sold into regulated manufacturing environments. OSHA workplace safety rules in the United States and CE marking obligations under EU machinery directives mandate measurement accuracy documentation for structural steel erection and heavy equipment assembly. Stakeholders must monitor evolving sensor fusion architectures that combine capacitive and MEMS technologies, as these hybrid designs promise to redefine performance benchmarks without awaiting regulatory revision cycles.
Market Dynamics
MEMS sensor miniaturization is compressing unit costs while extending operational lifespans, creating a structural shift toward solid-state displacement of pendulum-based mechanisms across portable measurement tools.
Growth Catalysts
- CE marking obligations under EU machinery directives:Mandates for measurement accuracy documentation in structural steel erection drive replacement cycles for certified digital angle gauges across German and French construction sites.
- Semiconductor fabrication equipment:Cleanroom-certified inclinometers with hermetic sealing and traceable calibration protocols command sustained demand from wafer processing tool manufacturers in Taiwan and South Korea.
- Shenzhen electronics manufacturing cluster:Concentrated MEMS component production enables rapid prototyping and cost-down trajectories for consumer-grade angle measurement devices.
Market Restraints
- Raw material volatility in machined aluminum enclosures:Aerospace-grade alloy pricing fluctuations compress margins for precision instrument manufacturers dependent on thermal stability specifications.
- Single-source dependency for high-precision gyroscopic elements:Japanese and German MEMS foundries control critical supply nodes for calibration-grade sensors used in metrology applications.
- Technical limitation in magnetic interference environments:Standard accelerometer-based designs experience drift near heavy electrical equipment, restricting deployment in power generation maintenance workflows.
Strategic Opportunities
- India's PLI scheme for electronic manufacturing:Incentive structures for component localization attract gauge assembly operations targeting domestic infrastructure and export markets.
- Sensor fusion architectures:Hybrid capacitive-MEMS designs promise accuracy improvements without awaiting regulatory revision cycles for existing calibration standards.
- Direct-to-contractor digital channels:Bypassing industrial distribution layers enables margin capture from small-scale construction and renovation professionals in Southeast Asian urban centers.
Industry Challenges
- NIST-traceable calibration technician scarcity:Qualified metrology personnel shortages extend certification timelines for aerospace and defense contract compliance.
- Legacy equipment integration complexity:Digital gauge outputs require protocol adaptation for older CNC machinery and manual measurement workflows still prevalent in job shop environments.
- ISO 9001 audit preparation burden:Documentation requirements for quality management system maintenance consume disproportionate administrative resources at mid-tier gauge manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Angle Gauge Market |
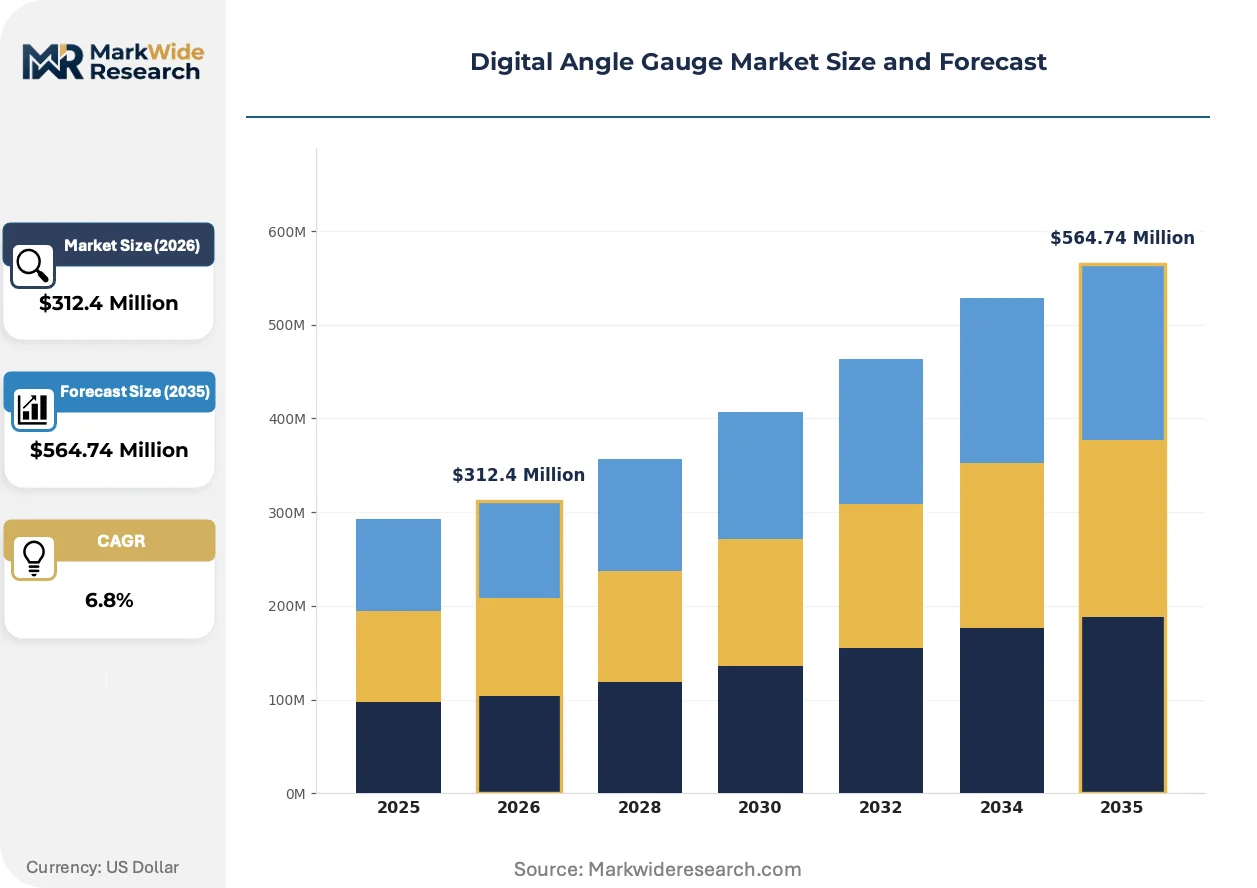
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Protractor, Inclinometer, Universal Angle Gauge, Electronic Level End User: Construction, Automotive, Aerospace, Manufacturing Technology: Laser, Optical, Capacitive, MEMS Application: Measurement, Calibration, Inspection, Maintenance |
| Companies Covered | Klein Tools, Stanley Black & Decker, Bosch Power Tools, Mitutoyo Corporation, Fortune Extendables Corp., FUJI TOOL CO., LTD., Hilti Corporation, General Tools Instruments, Starrett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Angle Gauge Market Trends and Innovations
Wireless connectivity protocols and edge computing capabilities are embedding intelligence directly into handheld measurement devices, transforming angle gauges from passive readout instruments into networked quality control nodes.
MEMS-based inclinometer modules are modularizing around standardized form factors and communication interfaces. Construction equipment OEMs in Japan and Germany are adopting these plug-in sensor blocks for factory-integrated leveling systems. The technology is modularizing supply chains by separating sensor manufacturing from final gauge assembly, enabling specialist producers to enter without vertical integration into MEMS fabrication.
OSHA workplace safety rules in the United States now require documented measurement verification for elevated work platform installation and crane assembly sequences. Industrial compliance officers face expanded liability exposure without calibrated instrumentation traceability. Heavy equipment rental fleets across Texas and California are retrofitting digital angle verification into maintenance protocols to preempt inspection failures.
Certification-driven preference shifts are compressing vendor selection cycles among aerospace subcontractors. Buyers now prioritize pre-qualified suppliers with existing NIST-traceable calibration certificates over price-competitive unverified alternatives. This behavior concentrates procurement among established metrology houses in California, Ohio, and Connecticut, squeezing regional distributors without in-house calibration laboratories.
Digital Angle Gauge Market Segmentation
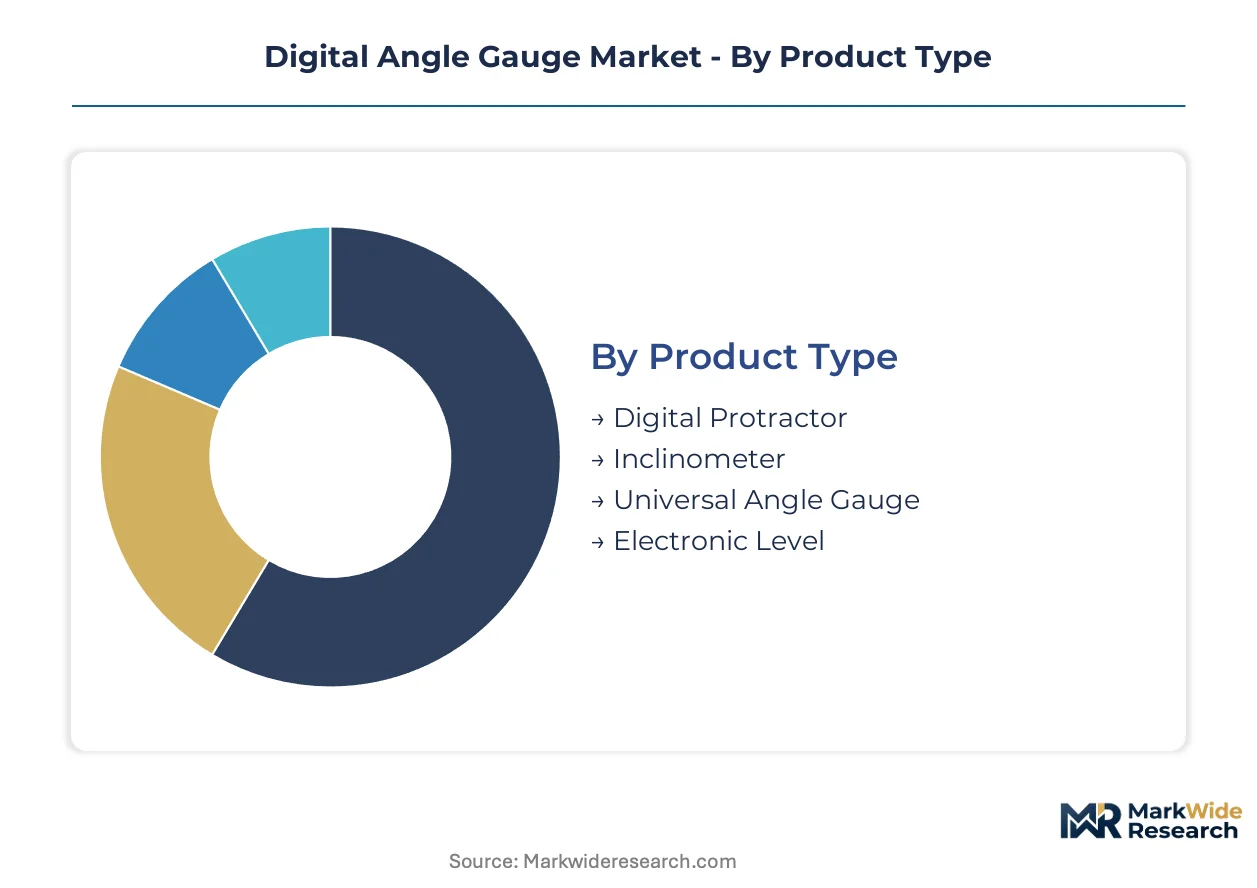
Digital angle gauges serve divergent precision requirements across construction job sites and semiconductor cleanrooms. Segmentation reveals how sensor technology choices and calibration protocols split procurement patterns between cost-sensitive contractors and margin-protected metrology laboratories.
Product Type:
Standardization dominates consumer-grade offerings while calibration-grade instruments demand extensive customization for thermal stability and traceability protocols.
- Inclinometer:Solid-state designs utilizing MEMS accelerometers measure angular tilt relative to gravitational reference within machined aluminum housings. German and Japanese construction contractors specify these for foundation grading and equipment leveling where 0.1-degree resolution satisfies structural codes. MEMS miniaturization has compressed unit costs while extending battery life beyond 2,000 hours.
- Electronic Level:Hermetically sealed units with NIST-traceable calibration certificates command premium positioning in semiconductor fabrication equipment. Wafer processing tool manufacturers in Taiwan and South Korea require cleanroom-certified variants with documented thermal drift coefficients below 0.01 degrees per Celsius.
- Digital Protractor:Combines hinged arms with rotary encoders for direct angle measurement between two surfaces. Woodworking and metal fabrication shops favor these for layout tasks where mechanical simplicity outweighs digital connectivity requirements.
- Universal Angle Gauge:Modular designs accept interchangeable measuring heads for specialized applications including gear tooth inspection and taper verification. Aerospace maintenance facilities specify these for airframe alignment checks.
Most installed capacity flows through Inclinometer variants. Expansion is steepest in Electronic Level applications.
End User:
Volume concentration sits with field-deployable construction tools while margin capture concentrates in regulated manufacturing environments with audit requirements.
- Construction:OSHA workplace safety rules mandate documented measurement verification for crane assembly and elevated platform installation across Texas and California job sites. Rental fleet operators now retrofit digital angle verification into preventive maintenance protocols to preempt inspection failures.
- Aerospace:AS9100 quality standards and FAA repair station requirements drive procurement of calibration-grade instruments with documented uncertainty budgets. Subcontractors in California, Ohio, and Connecticut concentrate procurement among pre-qualified suppliers with captive metrology laboratories.
- Automotive:Powertrain assembly lines utilize compact inclinometers for camshaft timing verification and chassis alignment checks. Electric vehicle battery pack installation requires precise tilt measurement for thermal management system performance.
- Manufacturing:ISO 9001 audit preparation burdens mid-tier gauge producers with documentation requirements that consume disproportionate administrative resources relative to contract value.
Construction absorbs the highest unit volumes. Aerospace delivers the steepest margin expansion trajectory.
Technology:
Cost tiers separate legacy optical designs from solid-state MEMS architectures now displacing pendulum mechanisms across portable measurement tools.
- MEMS:Microelectromechanical systems integrate accelerometer and gyroscopic elements on silicon substrates, enabling sub-dollar component costs at million-unit scales. Shenzhen electronics manufacturing clusters drive rapid prototyping and cost-down trajectories for consumer-grade devices.
- Capacitive:Electrostatic sensing elements achieve nanometer-scale displacement resolution for precision metrology applications. Hybrid capacitive-MEMS sensor fusion architectures promise accuracy improvements without awaiting regulatory revision cycles for existing calibration standards.
- Laser:Interferometric methods provide non-contact measurement for rotating machinery and dynamic alignment tasks where mechanical probe access is restricted.
- Optical:Vernier-scale reading systems persist in legacy equipment and educational institutions where electromagnetic immunity and battery independence outweigh digital convenience.
MEMS technology carries the dominant installed base. Capacitive methods are gaining share fastest in calibration-grade applications.
Application:
Recurring revenue concentrates in calibration services while equipment sales concentrate in initial measurement and inspection deployments.
- Measurement:Primary angular displacement reading for machinery setup and structural alignment constitutes the foundational use case across all end-user segments. Construction grading and equipment leveling generate the highest unit demand.
- Calibration:NIST-traceable certification services face technician scarcity that extends timelines for aerospace and defense contract compliance. Qualified metrology personnel shortages create backlog premiums for expedited certification.
- Inspection:Quality verification workflows in automotive assembly and aerospace subassembly require documented traceability for regulatory audit defense.
- Maintenance:Predictive maintenance programs for rotating equipment and structural monitoring generate recurring sensor replacement demand in power generation and heavy industrial facilities.
Measurement commands the largest installed instrument population. Calibration services are expanding most quickly as certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly operations to jurisdictions with streamlined calibration certification pathways and lower compliance overhead for MEMS component integration.
United States
OSHA workplace safety rules mandate documented measurement verification for crane assembly and elevated platform installation across Texas and California job sites. Heavy equipment rental fleets in Houston and Los Angeles retrofit digital angle verification into preventive maintenance protocols. FAA repair station requirements in Connecticut and Ohio concentrate procurement among pre-qualified suppliers with captive metrology laboratories.
Germany
CE marking obligations under EU machinery directives drive replacement cycles for certified digital angle gauges across construction sites in Bavaria and North Rhine-Westphalia. KBA vehicle inspection protocols require precision alignment instrumentation for commercial fleet maintenance. Industrial clusters around Stuttgart and Munich anchor demand from automotive powertrain assembly lines.
China
Shenzhen electronics manufacturing clusters enable rapid prototyping and cost-down trajectories for consumer-grade MEMS-based angle measurement devices. GB standards for construction machinery safety create compliance pull for domestic gauge producers. Yangtze River Delta fabrication facilities supply sub-dollar MEMS accelerometer components at million-unit scales.
Japan
METI industrial standardization programs support MEMS sensor miniaturization for precision measurement tools deployed in Nagoya automotive manufacturing zones. JIS certification requirements shape product specifications for domestic construction contractors. Chubu region industrial corridors concentrate demand from semiconductor fabrication equipment suppliers.
India
PLI scheme incentive structures for electronic manufacturing attract gauge assembly operations targeting domestic infrastructure buildout and export markets. CEA regulations for power generation equipment maintenance create demand for magnetic-interference-resistant designs. Maharashtra and Gujarat industrial zones host emerging component localization for construction-grade inclinometers.
Digital Angle Gauge Market Competitive Landscape
German and Japanese producers anchor the premium calibration-grade tier; Chinese fabricators hold the high-volume consumer and construction segments. The vendor base splits between consolidated metrology houses with captive calibration laboratories and fragmented specialists serving regional industrial distribution. Three archetypes dominate: precision instrument manufacturers with aerospace certification depth, power tool conglomerates leveraging sensor integration expertise, and MEMS module specialists supplying white-label components. Capacity expansion in East Asian electronics clusters and strategic partnerships between sensor foundries and final gauge assemblers represent the dominant competitive moves.
Within the premium-tier vector, Mitutoyo Corporation and Starrett exemplify precision instrument manufacturers with established metrology laboratory networks. Bosch Power Tools occupies a position among power tool conglomerates that leverage sensor integration capabilities across professional construction segments. These three anchors represent distinct competitive positioning archetypes: calibration-grade certification depth, industrial distribution scale, and MEMS technology integration expertise.
| Leading Market Players |
|---|
| Klein Tools |
| Stanley Black & Decker |
| Bosch Power Tools |
| Mitutoyo Corporation |
| Fortune Extendables Corp. |
| FUJI TOOL CO., LTD. |
| Hilti Corporation |
| General Tools Instruments |
| Starrett |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between NIST-traceable metrology instruments and consumer-grade construction tools manifests in pricing power concentration among German and Japanese precision houses, while Shenzhen MEMS fabricators compress supply chains through modular component sourcing. Three-tier pricing structure across premium calibration, professional jobsite, and economy consumer levels tracks directly to captive laboratory ownership versus white-label assembly models.
Pricing Analysis
Distributor margin layers absorb 25-40 points between MEMS module cost and final gauge retail, with direct-to-OEM channels for construction equipment integrators commanding steepest discounts. Price differentiation hinges on calibration certificate tier and thermal stability specification, with aerospace-grade uncertainty budgets commanding 8-12x multiples over construction-grade resolution. Pricing pressure stems from Shenzhen consumer-grade entrants flooding hardware channels with sub-dollar MEMS units. Construction contractors exhibit highest price sensitivity, while semiconductor fabrication equipment buyers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German MEMS foundries controlling high-precision gyroscopic element fabrication for calibration-grade sensors. Component supply draws from China for machined aluminum enclosures, Taiwan for semiconductor-grade MEMS wafers, and Germany for precision-machined metrology housings. Tariff exposure runs through trans-Pacific electronics component flows. Distribution runs through industrial supply houses and direct OEM integration channels for construction equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening across regulated manufacturing environments as AS9100 and ISO 9001 audit requirements displace unverified instrumentation, positioning calibration-grade suppliers for sustained margin capture.
For Market Incumbents: Anticipate MEMS module commoditization eroding mid-tier positioning by deepening captive calibration laboratory networks and securing NIST-traceable certification capacity before technician scarcity intensifies. Lock in long-term supply agreements with Japanese MEMS foundries to defend sensor access against emerging Chinese fabricators. For New Entrants and Emerging Players: Capture white-space in India's PLI-supported electronics manufacturing zones where domestic infrastructure buildout outpaces calibrated gauge supply. Target CEA-regulated power generation maintenance workflows with magnetic-interference-hardened designs, leveraging direct-to-contractor digital channels to bypass entrenched industrial distribution layers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier gauge producers face ISO 9001 documentation burdens consuming disproportionate administrative resources relative to contract value. Long-term viability favors vertically integrated metrology houses with captive calibration laboratories over assembly-only operations. Watch NIST-traceable technician certification backlogs as inflection signal for expedited service premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captive NIST-traceable capacity locks in aerospace procurement preference concentration. |
| MEMS Foundry Partnership | Japanese sensor access agreements secure high-precision gyroscopic element supply nodes. |
| Direct-to-Contractor Channel Buildout | Bypassing industrial distribution captures margin from Southeast Asian construction professionals. |
| Sensor Fusion R&D Investment | Hybrid capacitive-MEMS architectures promise accuracy gains without regulatory revision delays. |
| India PLI Zone Manufacturing Entry | Domestic assembly positioning targets infrastructure buildout and export market access. |
Research Methodology
Direct dialogue with metrology laboratory directors, construction equipment procurement managers, MEMS foundry operations heads, and industrial distribution channel partners grounded qualitative assessment, cross-referenced with customs trade databases, SEC filings from precision instrument manufacturers, ISO certification registry records, and OSHA compliance documentation. Bottom-up gauge shipment estimates triangulated against top-down construction and manufacturing capital expenditure patterns.
Top-down macroeconomic drivers and bottom-up segment granularity converged across product type, end-user industry, technology architecture, and application use case dimensions over the projection horizon. CAGRs derived from historical shipment trajectories, replacement cycle analysis, and regulatory mandate implementation timelines, with semiconductor fabrication equipment demand and construction safety compliance enforcement as primary forecast inputs.
Raw material volatility in aerospace-grade alloys, MEMS foundry capacity allocation shifts, and regulatory revision cycles for calibration standards are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about sensor miniaturization trajectories and certification requirement proliferation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Rain Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Japan Digital Thermometer Market