
 Reflective Encoder Market | 2026-2036
Reflective Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Encoder Market Analytics
Resolution-grade encoder specifications above 10,000 PPR is unwinding across the Reflective Encoder Market as semiconductor lithography and medical imaging OEMs demand sub-micron positioning fidelity. HEIDENHAIN leverages its captive glass-scale manufacturing in Traunreut to dominate ultra-high-resolution absolute encoder supply. Sensata Technologies anchors North American automotive ADAS encoder demand through backward integration into magnetic sensing die production. Baumer Group differentiates in food-grade and washdown-rated incremental encoders for packaging machinery.
A reflective encoder optically detects position by reading patterned scales through LED-photodiode pairs, achieving resolutions from 500 to 32,000 pulses per revolution depending on line count and interpolation electronics; its primary purpose is closed-loop feedback in servo motor systems requiring repeatable angular or linear measurement. Optical encoder architectures still command the largest installed base in CNC machinery and semiconductor stages, though magnetic encoders are displacing optical designs in automotive and heavy-industrial settings where contamination tolerance matters. TTL output technology retains dominance in legacy industrial networks, while RS-485 interfaces are concentrating in multi-axis robotics and material handling systems requiring differential signaling over longer cable runs.
The EU Machinery Directive and CE marking requirements enforce functional safety integrity levels that compel encoder redundancy in collaborative robotics and autonomous guided vehicles. China's SAMR and GB standards on industrial robot safety are tightening electromagnetic compatibility and shock-resistance testing protocols for encoders deployed in domestic smart factories. Japan's METI circular economy guidelines are pushing encoder manufacturers toward design-for-disassembly and rare-earth reduction in magnetic sensing subassemblies. Stakeholders must monitor how IEC 61508 safety certification timelines and regional content rules for critical infrastructure reshape supplier qualification criteria and sourcing geography.
Market Dynamics
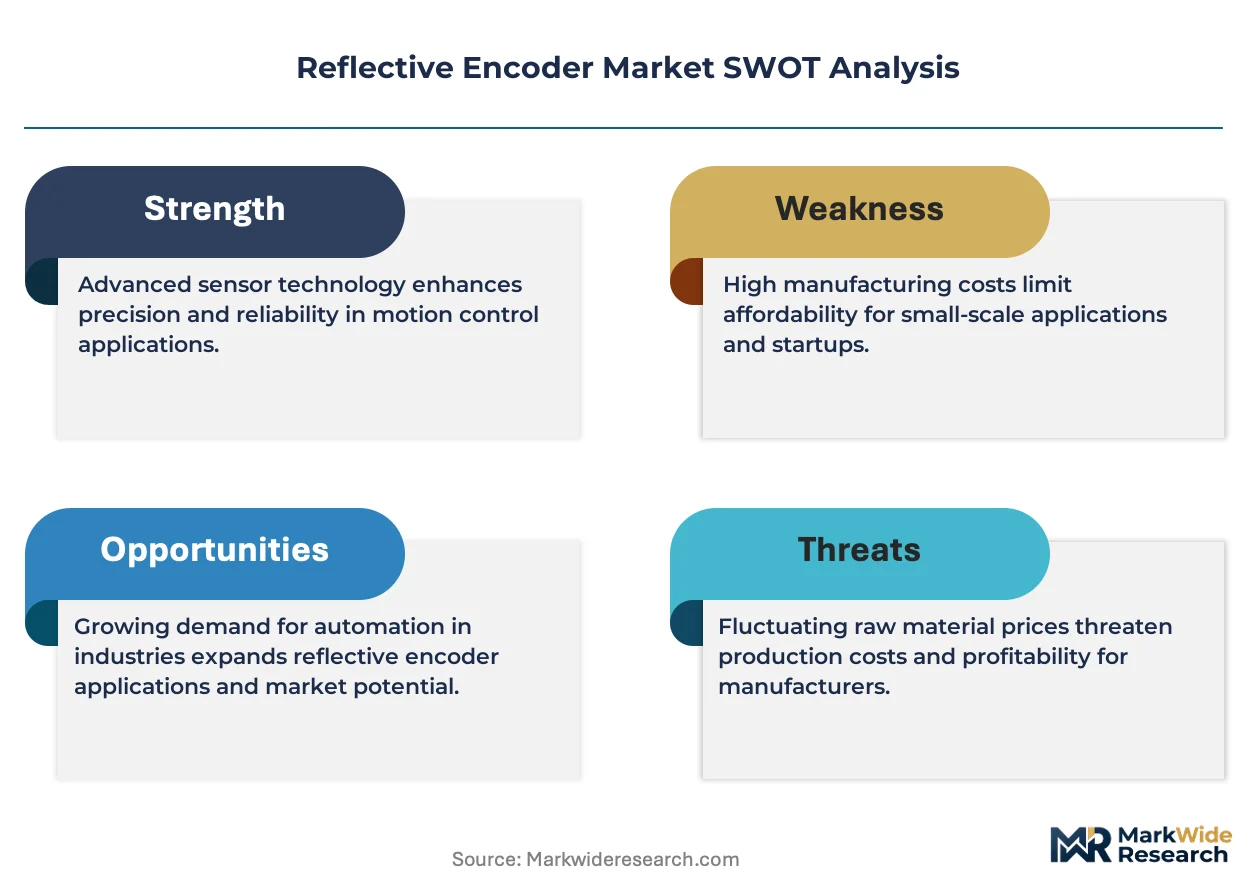
Resolution-grade encoder specifications above 10,000 PPR are compressing supplier margins as semiconductor lithography and medical imaging OEMs demand sub-micron positioning fidelity without proportional price acceptance.
Growth Catalysts
- EU Machinery Directive:Functional safety integrity levels compel encoder redundancy in collaborative robotics and autonomous guided vehicles across German factory automation corridors.
- Semiconductor lithography:Sub-micron positioning requirements in EUV wafer stages pull demand for reflective encoders exceeding 32,000 PPR resolution thresholds.
- China's GB standards:Electromagnetic compatibility and shock-resistance testing protocols for industrial robots tighten qualification criteria for encoder suppliers in domestic smart factories.
Market Restraints
- Rare-earth magnet volatility:Neodymium and dysprosium price swings destabilize magnetic encoder subassembly costs, pressuring hybrid optical-magnetic sourcing strategies.
- Glass-scale supply concentration:Captive manufacturing of ultra-high-resolution scales clusters in southern Germany, creating single-source vulnerability for absolute encoder architectures.
- Optical contamination limits:Dust and oil ingress susceptibility constrains reflective encoder deployment in heavy-industrial forging and mining equipment where magnetic alternatives prevail.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for industrial automation equipment create localized encoder assembly opportunities for robotics OEMs serving domestic automotive lines.
- Medical imaging convergence:MRI-compatible encoder demand opens white space for fiber-optic and capacitive sensing technologies in diagnostic equipment manufacturing.
- Japan's METI circular economy guidelines:Design-for-disassembly mandates push encoder manufacturers toward rare-earth reduction and modular magnetic sensing subassemblies.
Industry Challenges
- IEC 61508 certification timelines:Safety integrity level verification for SIL 3 encoders extends product qualification cycles by 14-18 months, delaying revenue recognition.
- Legacy TTL integration:Backward compatibility requirements with 5V open-collector industrial networks complicate firmware architecture for next-generation RS-485 differential output designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Encoder Market |
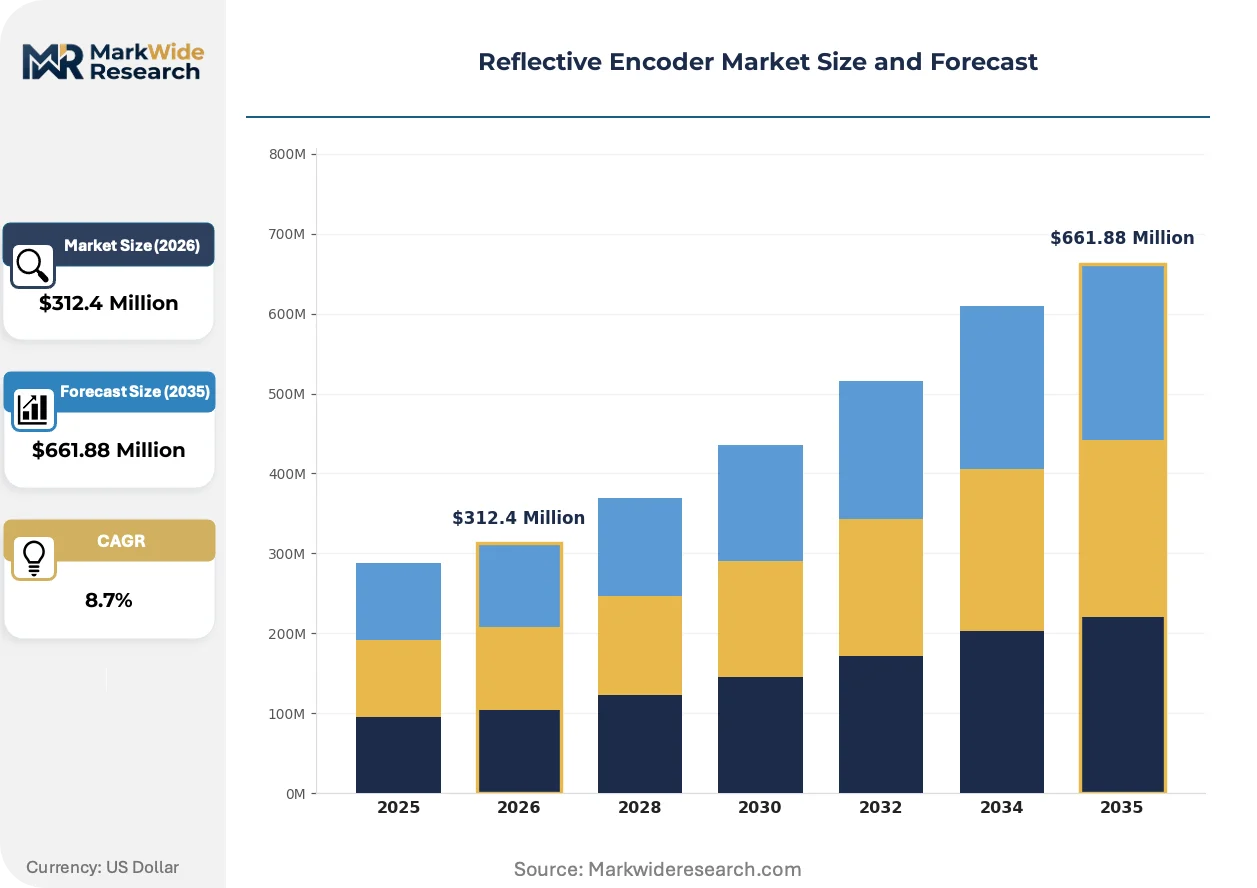
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incremental Encoders, Absolute Encoders, Optical Encoders, Magnetic Encoders Technology: TTL, RS-232, RS-485, I²C End User: Consumer Electronics, Automotive Components, Industrial Automation, Aerospace Systems Application: Motion Control, Robotics, CNC Machinery, Printing Equipment |
| Companies Covered | Sensata Technologies, HEIDENHAIN, Fortive (Dynapar), Renishaw plc, Mitutoyo Corporation, FRABA B.V., Baumer Group, US Digital, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Encoder Market Evolving Landscape
Reflective encoder architectures face active substitution pressure as magnetic sensing advances close the resolution gap while expanding contamination tolerance. Three developments are restructuring competitive positioning.
Magnetic encoder technology with 18-bit absolute resolution is displacing optical designs in automotive ADAS steering-angle modules and heavy-industrial material handling systems. Tier-1 automotive suppliers in Germany and Japan are qualifying magnetic alternatives for electric power steering feedback loops previously reserved for reflective encoders. This substitution compresses addressable market scope for pure optical suppliers in contamination-prone environments.
China's SAMR enforcement of GB/T industrial robot safety standards is accelerating electromagnetic compatibility testing mandates for encoders deployed in collaborative automation cells. Domestic certification bodies now require third-party verification of encoder immunity to 10V/m radiated fields in smart factory deployments. Encoder suppliers are redesigning shielding architectures and cable harness specifications to satisfy these protocols before factory acceptance testing.
Buying patterns among industrial automation OEMs are compressing switching cycles as multi-axis robotics platforms demand unified encoder families across servo, linear, and rotary axes. System integrators in Japan's robotics manufacturing belt now specify single-supplier encoder portfolios to reduce spare parts complexity and unified software commissioning. This concentration preference disadvantages specialized incremental encoder vendors without absolute encoder capabilities or integrated drive-encoder combinations.
Reflective Encoder Market Segmentation
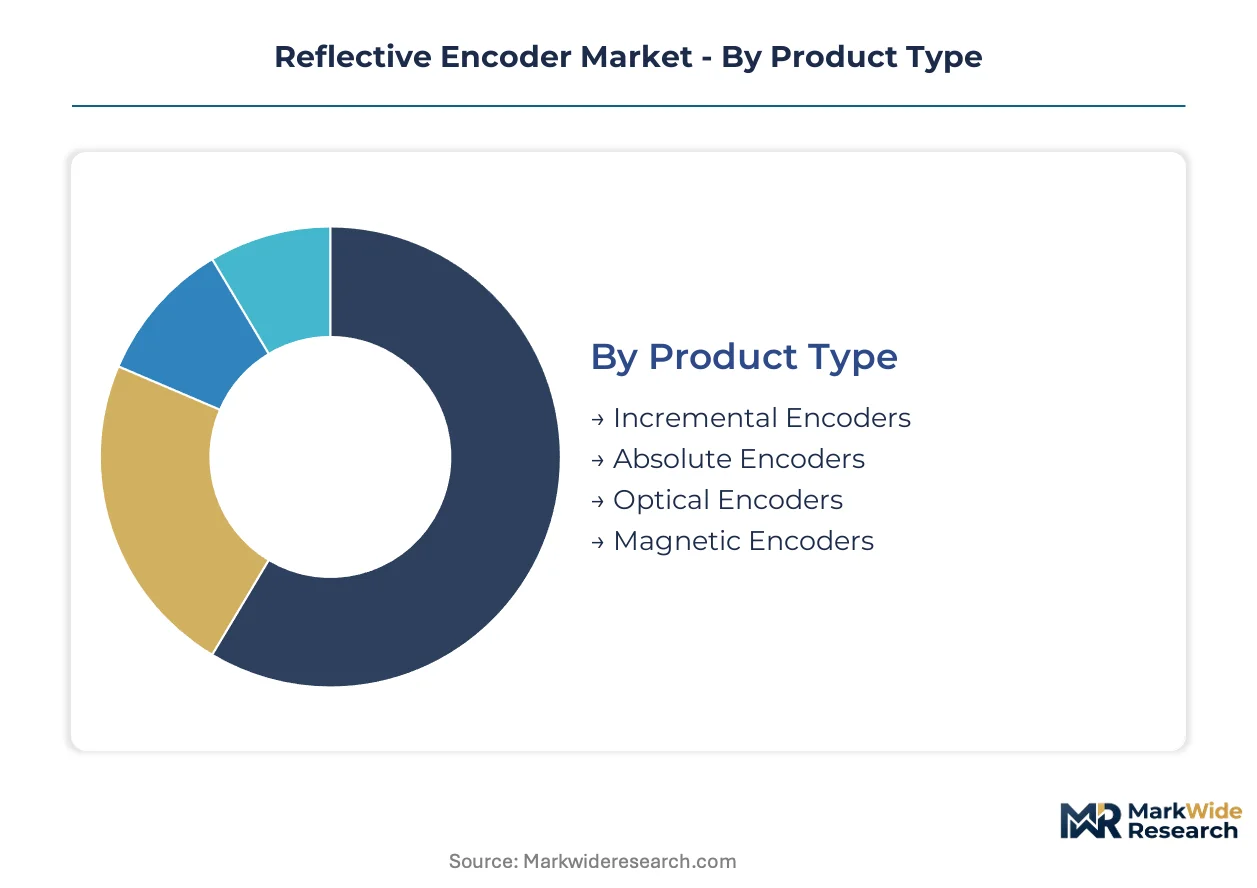
Reflective encoder procurement patterns diverge sharply across product architectures and interface standards. OEM specification committees weight resolution fidelity against environmental tolerance when mapping segments to end-use requirements.
Product Type:
Absolute encoders dominate export flows to semiconductor capital equipment manufacturers, while incremental variants serve price-sensitive domestic automation retrofits.
- Incremental Encoders:Generate position data through pulse counting from a reference point, requiring homing routines on startup. Demand clusters in Germany's packaging machinery OEMs where cost engineering trumps absolute positioning redundancy. TTL output variants retain dominance in legacy retrofit installations despite RS-485 migration in greenfield projects.
- Absolute Encoders:Output unique position codes for every shaft angle, eliminating homing sequences in multi-axis robotics. Sub-micron glass-scale variants from Traunreut supply EUV lithography stages; magnetic absolute encoders penetrate automotive ADAS modules in Japan's tier-1 supply chain.
- Optical Encoders:LED-photodiode pairs read patterned scales with contamination-limited reliability.
- Magnetic Encoders:Hall-effect or magnetoresistive sensing tolerates dust, oil, and vibration in heavy-industrial forging lines.
Absolute encoders hold the largest share; momentum sits with magnetic encoders.
Technology:
Interface selection tracks cable run length and electromagnetic noise exposure in target installations.
- TTL:5V open-collector signaling persists in legacy PLC networks and short-distance encoder-motor pairings. German factory automation corridors still specify TTL for backward compatibility with installed base controllers, though new designs face obsolescence pressure.
- RS-485:Differential signaling extends cable runs beyond 100 meters in multi-axis material handling systems. China's smart factory deployments mandate RS-485 for electromagnetic immunity compliance under GB/T industrial robot safety standards.
- RS-232:Point-to-point asynchronous communication lingers in diagnostic and configuration interfaces.
- I²C:Synchronous serial bus integration suits embedded motor-encoder combinations in compact robotics joints.
RS-485 is climbing fastest in new installations; TTL retains the deepest installed base.
End User:
Customer concentration varies by certification burden and volume scale across verticals.
- Industrial Automation:Servo motor feedback loops in CNC machinery and robotic cells consume the highest encoder volumes. Japan's robotics manufacturing belt specifies unified encoder families across rotary and linear axes to compress spare parts logistics.
- Automotive Components:Electric power steering and brake-by-wire systems demand SIL-rated encoders with extended temperature ranges. Germany's KBA type-approval process extends qualification timelines for safety-critical steering-angle modules.
- Consumer Electronics:Miniature rotary encoders serve camera gimbals and gaming peripherals with relaxed precision requirements.
- Aerospace Systems:DO-178C software certification and MIL-STD-810 environmental testing restrict supplier qualification to a narrow tier.
Industrial automation holds the largest share; automotive components show the steepest expansion trajectory.
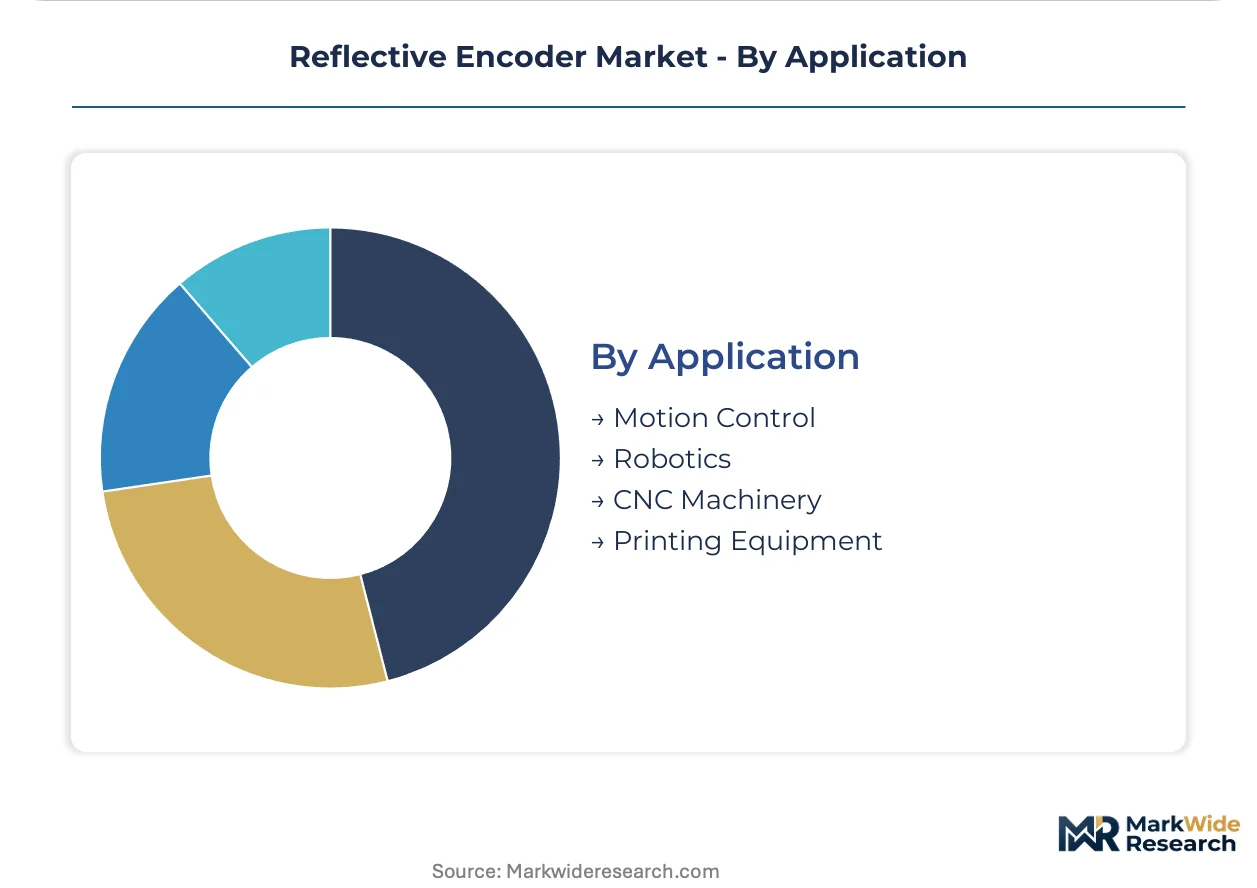
Application:
Use-case differentiation centers on axis count, positioning tolerance, and contamination exposure.
- Motion Control:Closed-loop velocity and position feedback in servo systems spans semiconductor stages to packaging lines. Sub-micron positioning fidelity in EUV lithography pulls demand toward 32,000+ PPR reflective encoders with interpolation electronics.
- Robotics:Collaborative and industrial robot joints require compact, high-resolution feedback for force-controlled assembly. METI circular economy guidelines in Japan push modular encoder designs enabling field serviceability.
- CNC Machinery:Spindle and axis positioning in metal-cutting equipment favors glass-scale optical encoders for thermal stability.
- Printing Equipment:Web tension control and register alignment tolerate lower resolution in exchange for contamination resistance.
Motion control holds the largest share; robotics is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for reflective encoders diverges sharply by geography. Semiconductor lithography OEMs in Germany and Japan absorb ultra-high-resolution premiums without volume contraction, while packaging machinery buyers in India and Southeast Asia trade absolute positioning for cost-engineered incremental designs.
Germany
EU Machinery Directive enforcement compels SIL-rated encoder redundancy in collaborative robotics and autonomous guided vehicles. The KBA type-approval process extends qualification timelines for safety-critical automotive steering-angle modules. Factory automation corridors in Bavaria and Baden-Württemberg concentrate demand for glass-scale absolute encoders serving CNC machinery and EUV lithography stages.
Japan
METI circular economy guidelines push encoder manufacturers toward design-for-disassembly and rare-earth reduction in magnetic sensing subassemblies. JIS standards on industrial robot safety tighten electromagnetic compatibility testing protocols for collaborative automation cells. The robotics manufacturing belt spanning Kanto and Kansai specifies unified encoder families across rotary and linear axes to compress spare parts logistics.
China
SAMR enforcement of GB/T industrial robot safety standards accelerates electromagnetic compatibility testing mandates for encoders in smart factory deployments. The country's national industrial regulator now requires third-party verification of encoder immunity to radiated fields before factory acceptance testing. Yangtze River Delta manufacturing clusters drive demand for RS-485 differential output designs in multi-axis material handling systems.
United States
FDA oversight of diagnostic equipment manufacturing pulls demand for MRI-compatible encoder technologies in medical imaging convergence. NHTSA safety regulations for electric power steering systems mandate extended temperature range specifications. Automotive component manufacturing in Michigan and the Southeast concentrates procurement for SIL-rated encoders serving brake-by-wire feedback loops.
India
PLI scheme production-linked incentives for industrial automation equipment create localized encoder assembly opportunities for robotics OEMs serving domestic automotive lines. The central bank's monetary policy stance influences capital equipment investment cycles across manufacturing sectors. Gujarat and Maharashtra industrial corridors show rising specification of cost-optimized incremental encoders for packaging machinery retrofits.
Reflective Encoder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the reflective encoder market. Ultra-high-resolution absolute encoder supply concentrates around captive glass-scale manufacturing capabilities, while magnetic sensing specialists compete on contamination tolerance and automotive qualification speed. Three archetypes dominate: integrated motion control conglomerates with captive encoder divisions, precision sensor specialists with lithography-grade metrology heritage, and modular component suppliers serving price-sensitive retrofit markets. Competitive moves center on backward integration into sensing die production and strategic partnerships with multi-axis robotics platform OEMs.
Within the precision sensor tier, HEIDENHAIN GmbH and Renishaw plc exemplify technology leadership through metrology heritage and glass-scale manufacturing concentration. Sensata Technologies Inc. anchors North American automotive encoder demand through upstream control over magnetic sensing die production. Among modular component suppliers, US Digital occupies a position serving cost-engineered incremental encoder demand in legacy industrial networks.
| Leading Market Players |
|---|
| Sensata Technologies |
| HEIDENHAIN |
| Fortive (Dynapar) |
| Renishaw plc |
| Mitutoyo Corporation |
| FRABA B.V. |
| Baumer Group |
| US Digital |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Captive glass-scale manufacturing in Traunreut generates steep scale economies that compress cost floors for absolute encoder architectures while elevating entry barriers for aspirant suppliers lacking in-house metrology-grade substrate production. This concentration simultaneously hardens price discipline among German precision sensor specialists and forces modular component vendors toward incremental encoder segments where specification tolerance permits offshore assembly.
Pricing Analysis
EU Machinery Directive functional safety mandates dictate the pricing tier structure across the reflective encoder market, separating SIL 3-certified absolute architectures from standard incremental variants. Certification grade and volume scale drive price differentiation, with lithography-grade glass-scale units commanding substantial premiums over cost-engineered packaging machinery alternatives. Pricing pressure stems from magnetic encoder substitution in automotive ADAS modules, compressing margins for pure optical suppliers. Packaging machinery OEMs in India exhibit highest price sensitivity, while semiconductor capital equipment manufacturers absorb resolution premiums without volume contraction.
Supply Chain Analysis
Germany and Japan anchor precision encoder manufacturing, with Traunreut glass-scale production and Kansai robotics belt assembly feeding global demand for high-resolution absolute architectures. Rare-earth magnet sourcing from China and photodiode die fabrication in Taiwan constitute critical input dependencies. Single-source vulnerability concentrates in ultra-high-resolution glass-scale supply, where captive manufacturing limits alternative sourcing. Distribution runs through authorized industrial automation distributors and direct OEM supply agreements for tier-1 automotive and semiconductor equipment accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reflective encoder market functions as a regulatory-entrenchment defensive moat, where IEC 61508 certification timelines and glass-scale manufacturing heritage create structural barriers that protect incumbent positioning against rapid competitive displacement.
For Market Incumbents: Secure backward integration into magnetic sensing die production to hedge against rare-earth price volatility and defend automotive ADAS positioning against magnetic encoder specialists. Expand captive glass-scale capacity in Traunreut to maintain absolute encoder technology leadership against emerging Asian metrology players. Prioritize SIL 3 certification maintenance to preserve collaborative robotics qualification status under tightening EU Machinery Directive enforcement. For New Entrants and Emerging Players: GB/T electromagnetic compatibility fast-track certification in China offers the most penetrable regulatory pathway for encoder suppliers lacking European heritage. Target India's PLI scheme industrial automation incentives for localized incremental encoder assembly serving domestic packaging machinery retrofits. Pursue fiber-optic sensing technology partnerships to access MRI-compatible medical imaging white space without competing directly against entrenched glass-scale suppliers. For Investors and Strategic Acquirers: Modular component suppliers with established RS-485 interface expertise and automotive qualification pipelines represent the most attractive acquisition target archetype for portfolio diversification. Long-term viability hinges on magnetic-optical hybrid technology positioning that bridges contamination tolerance and resolution fidelity demands. Monitor SAMR enforcement intensity in China as the critical inflection signal for regional supply chain reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensing Die Production | Captive magnetic sensing die manufacturing insulates automotive ADAS margins against rare-earth volatility from Chinese export restrictions. |
| GB/T Electromagnetic Compatibility Certification | SAMR-mandated third-party verification opens smart factory procurement channels in Yangtze River Delta manufacturing clusters. |
| Design-for-Disassembly Modular Architecture | METI circular economy compliance enables field serviceability and rare-earth reduction in Japan's robotics manufacturing belt. |
| RS-485 Interface Standardization | Differential signaling adoption aligns with China's multi-axis material handling system requirements under GB/T robot safety standards. |
| Fiber-Optic Sensing Technology Partnership | MRI-compatible encoder development accesses FDA-regulated diagnostic equipment manufacturing without optical contamination constraints. |
Research Methodology
Operator-level perspectives from encoder product managers at precision sensor specialists, procurement directors at multi-axis robotics OEMs, and certification engineers at notified bodies anchored the qualitative base. Primary interviews with plant engineers in Germany's factory automation corridor, maintenance directors at CNC machinery operators, and aftermarket service heads at industrial distributors supplemented field intelligence. Secondary validation drew from IEC 61508 certification databases, KBA type-approval filings, METI circular economy guideline releases, and SAMR GB/T standard enforcement notices. Bottom-up encoder shipment tracking across product architectures triangulated against top-down industrial automation capital expenditure assessments.
Sensitivity analysis tested demand elasticity assumptions across semiconductor lithography equipment cycles, automotive ADAS penetration trajectories, and collaborative robotics deployment rates over the projection horizon. The analytical framework modeled segmentation across absolute versus incremental architectures, TTL versus RS-485 interface standards, and end-use concentration in industrial automation versus automotive components. CAGRs derived from regression analysis of historical encoder pricing trends against resolution-grade specification trajectories, with magnetic encoder substitution rates and regional regulatory compliance timelines as primary forecast inputs.
Underlying assumptions cover stable rare-earth magnet pricing, continued EU Machinery Directive enforcement intensity, and Chinese smart factory investment continuity, with deviation risk concentrated in semiconductor capital equipment cycle downturns and accelerated magnetic encoder resolution advancement. Recalibration cycles align with material shifts in SAMR enforcement protocols, METI circular economy guideline updates, and IEC 61508 safety certification timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Vacuum Pressure Sensors Market