
 Global Diesel Power Engine Market | 2026-2036
Global Diesel Power Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diesel Power Engine Market Analysis
Data center operators is restructuring demand patterns for diesel power engines as hyperscale facilities prioritize uninterrupted baseload reliability. Cummins sustains technology leadership through in-house production of emission-certified platforms for mission-critical installations. Caterpillar dominates the high-capacity segment with manufacturing scale that anchors its position in prime power contracts across North America and Asia. Weichai Power leverages cost-engineered industrial engines to compete aggressively in emerging market infrastructure projects.
A diesel power engine is an internal combustion engine operating on compression ignition with air-fuel ratios typically exceeding 18:1, designed to convert chemical energy into mechanical work for stationary or mobile power applications. Compression ratios ranging from 14:1 to 25:1 enable thermal efficiency above 40 percent, making these engines indispensable for heavy-duty cycles where fuel economy and torque density outweigh electrification timelines. Industrial engines within the product type dimension command the deepest margin pools due to customization intensity and long service contracts, while standby power generators represent the largest volume category driven by commercial and institutional buyers. The capacity tier spanning 301-500 kW is attracting the fastest specification upgrades as mid-scale manufacturing and healthcare facilities replace aging fleets with Stage V and Tier 4 Final compliant units.
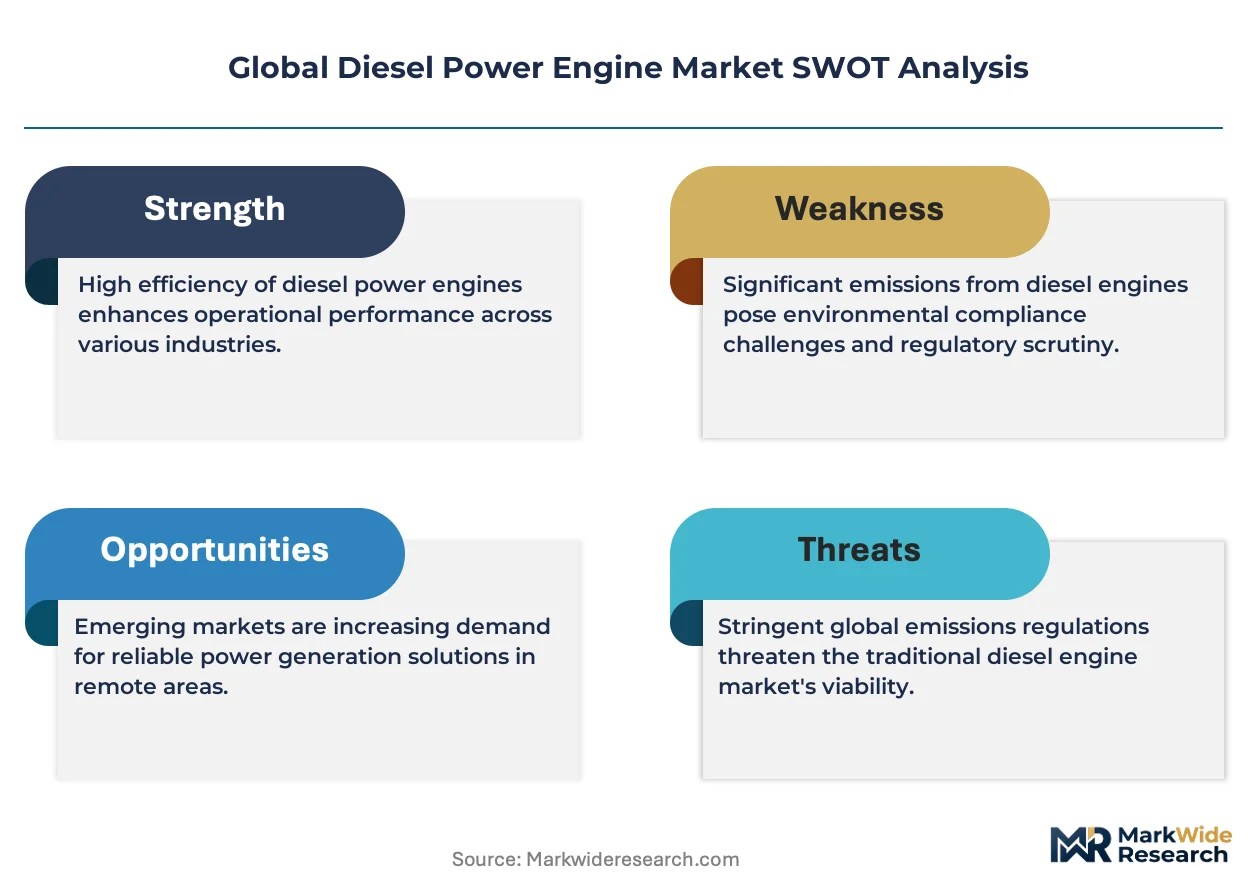
EPA Tier 4 Final, EU Stage V, and India's CEA emission guidelines are reshaping the certified product landscape by restricting market access to engine families demonstrating particulate matter and nitrogen oxide reductions exceeding ninety percent from unregulated baselines. OEMs must navigate divergent testing protocols across these jurisdictions, fragmenting development budgets and lengthening homologation cycles for multi-region platforms. Stakeholders should monitor how hybrid system architectures within the application segment absorb diesel engine share as battery energy density improves and carbon pricing mechanisms expand across industrial power contracts.
Market Dynamics
Compression-ignition technology faces a structural inflection as emission thresholds harden and battery-hybrid architectures capture incremental load cycles in baseload-sensitive installations.
Growth Catalysts
- Data Center Electrification Gaps:Hyperscale facilities in India and Southeast Asia require captive diesel generation to bridge grid instability during peak demand intervals.
- EPA Tier 4 Final Certification:Stringent particulate matter limits in the United States are consolidating specification demand around certified engine families with proven aftertreatment integration.
- Industrial Electrification Lag:Manufacturing corridors in Vietnam and Indonesia outpace utility-scale capacity additions, forcing direct investment in prime power diesel infrastructure.
Market Restraints
- Platinum Group Metal Cost Volatility:Selective catalytic reduction and diesel particulate filter substrates depend on palladium and rhodium, exposing OEM margins to commodity swings.
- Supplier Base Compression:EU Stage V and EPA Tier 4 Final homologation costs have eliminated small-scale engine builders, concentrating certified supply among capital-intensive manufacturers.
- Battery Energy Density Gains:Lithium-ion systems are displacing diesel in sub-500 kW standby applications where runtime requirements fall below four hours.
Strategic Opportunities
- Hybrid System Integration:Converging diesel gensets with battery energy storage systems is unifying spinning reserve and peak shaving functions for mission-critical buyers.
- CEA Emission Guidelines in India:Central Electricity Authority mandates for captive power plants are creating certified-engine procurement mandates in industrial states.
- Maritime Auxiliary Power:Harbor craft and offshore support vessels face IMO Tier III compliance deadlines, opening retrofit demand for medium-speed diesel platforms.
Industry Challenges
- Aftertreatment Calibration Talent Scarcity:EPA and EU-certified engine families require specialized technicians for urea dosing optimization and ash loading management.
- Multi-Jurisdiction Homologation Complexity:Divergent test cycles between EPA, EU Stage V, and India's CEA protocols fragment engineering resources and delay platform launches.
- Legacy Control System Integration:Modern electronic engine management units must interface with decades-old SCADA architectures in existing industrial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diesel Power Engine Market |
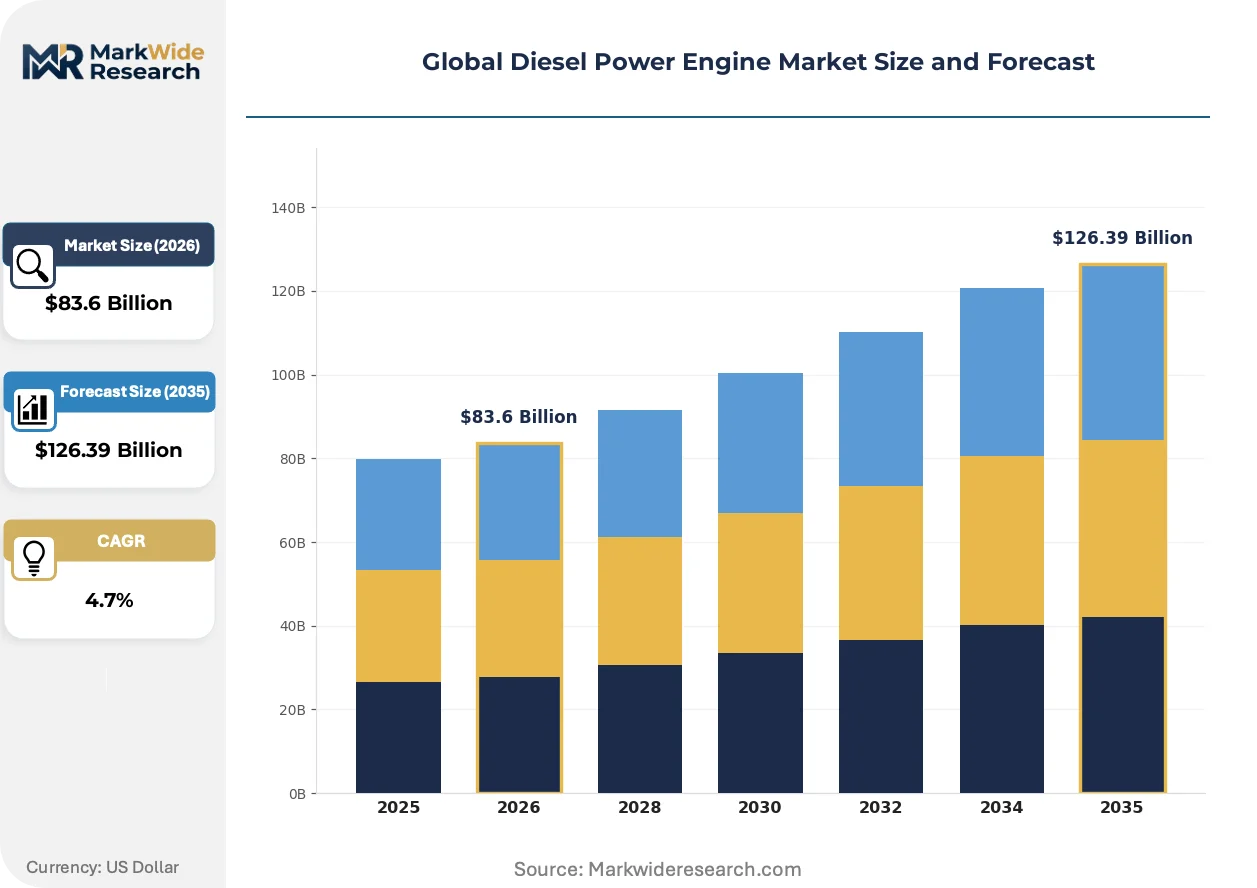
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $126.39 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Power Generators, Marine Engines, Industrial Engines End User: Construction, Agriculture, Transportation, Power Generation Capacity: Below 100 kW, 100-300 kW, 301-500 kW, Above 500 kW Application: Backup Power, Prime Power, Hybrid Systems, Grid Support |
| Companies Covered | MAN, Mitsubishi Heavy Industries, Caterpillar, Volvo Penta, HD Hyundai Infracore, Cummins, Rolls-Royce, Yanmar Holdings, Weichai Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diesel Power Engine Market Emerging Trajectories
Engine architecture is converging with electrical systems as manufacturers reposition compression-ignition assets within hybrid microgrids and emission-capped environments.
Variable geometry turbocharging paired with high-pressure common rail injection is unifying transient response and steady-state efficiency in a single hardware package. Data center operators and healthcare facility managers are specifying these integrated platforms for NFPA 110 Tier IV compliance. The technology is compressing the performance gap between mechanically governed legacy fleets and electronically controlled replacements.
EU Stage V particulate number limits and the F-Gas Regulation's refrigerant phase-down are forcing engine-thermal management redesigns in European markets. Manufacturers must now validate cooling circuits against alternative working fluids with lower global warming potential. The industrial engine segment bears the heaviest engineering burden as customization intensity multiplies validation matrices.
Facility managers are unbundling long-term service contracts from initial equipment procurement, compressing OEM recurring revenue streams. Independent service providers with portable diagnostic equipment are capturing scheduled maintenance intervals previously held by factory-authorized networks. This pattern concentrates in North American and Western European markets where labor mobility supports third-party technician certification.
Global Diesel Power Engine Market Segmentation
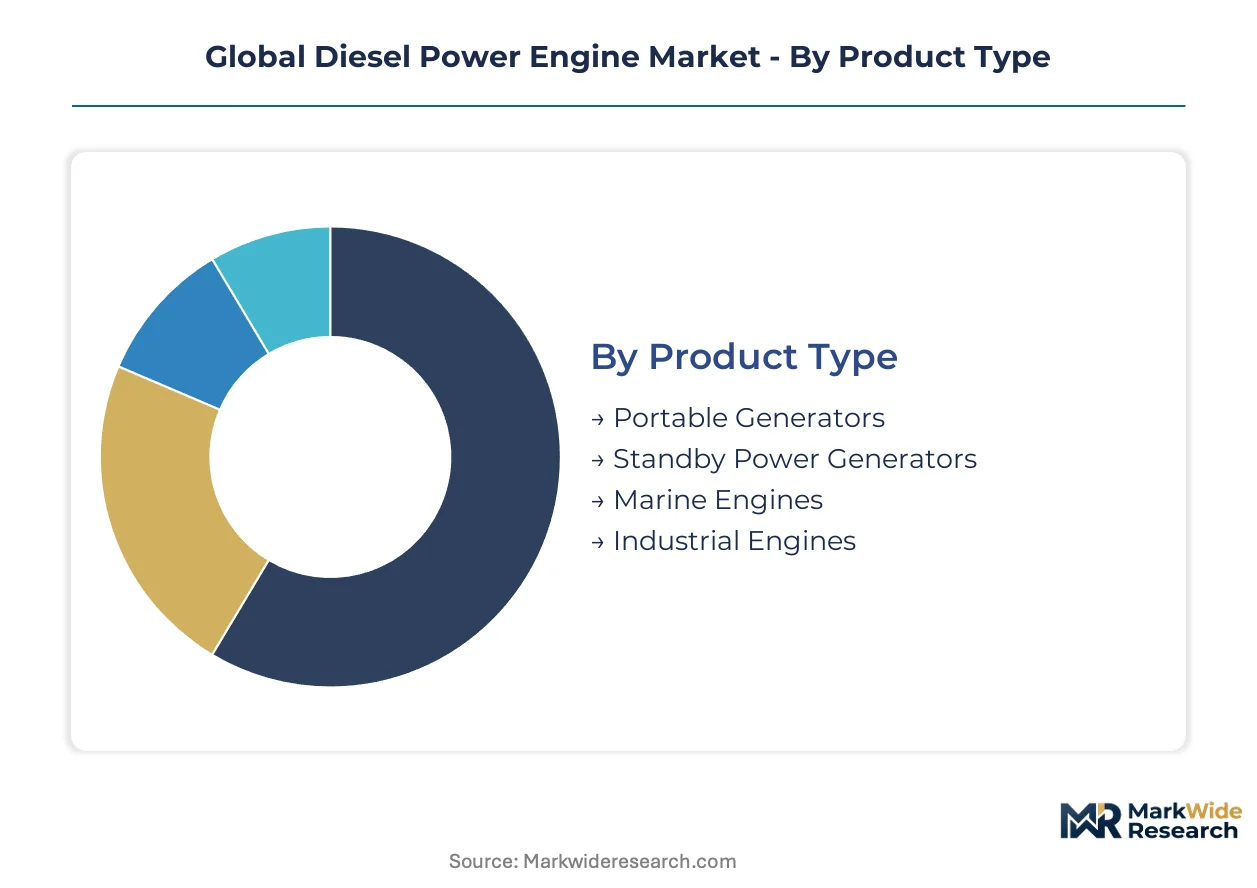
Segmentation in diesel power engines exposes divergent margin structures across product architectures and duty cycles. Industrial buyers prioritize thermal efficiency and emission certification tiers, while commercial purchasers optimize for capital cost and runtime flexibility.
Product Type:
Supply concentration intensifies around platforms with in-house aftertreatment integration, compressing the certified vendor base for emission-regulated segments.
- Industrial Engines:Compression-ignition platforms engineered for continuous-duty cycles in manufacturing plants and processing facilities. Demand concentrates in Vietnam and Indonesia where utility-scale grid additions lag industrial electrification timelines. Customization intensity and long-term service contracts sustain margin premiums above portable alternatives.
- Standby Power Generators:Fixed-installation units designed for automatic load transfer during grid interruption, governed by NFPA 110 standards for mission-critical facilities. Healthcare systems and data centers in India specify these for Tier IV compliance, driving specification upgrades toward electronic governing and fast-start capability.
- Portable Generators:Mobile units serving construction sites and emergency response with sub-72 hour runtime requirements.
- Marine Engines:Medium-speed and high-speed platforms for harbor craft, offshore support, and auxiliary power systems.
Industrial engines absorb the bulk of installed capacity; standby power generators are expanding most quickly.
End User:
Cost tier differentiation separates capital-intensive prime power buyers from price-sensitive intermittent users with lower utilization rates.
- Power Generation:Captive power plants and distributed generation assets serving industrial facilities with baseload or peaking requirements. CEA emission guidelines in India mandate certified engine procurement for captive installations above threshold capacities, restructuring vendor qualification criteria.
- Construction:Temporary power for site electrification, equipment operation, and worker facilities across infrastructure projects. Demand clusters in Southeast Asian manufacturing corridors where grid extension timelines exceed project construction schedules.
- Transportation:Locomotive, mining vehicle, and marine propulsion applications with high torque-density requirements.
- Agriculture:Irrigation pumps, grain drying, and remote equipment operation with seasonal utilization patterns.
Power generation commands the deepest engineering engagement; construction is gaining share fastest.
Capacity:
Application-specific load profiles determine specification intensity, with mid-range tiers attracting the fastest technology refresh cycles.
- 301-500 kW:Mid-scale platforms serving manufacturing facilities, hospitals, and commercial complexes with mixed baseload and standby duty. EPA Tier 4 Final and EU Stage V compliance costs are eliminating non-certified suppliers, concentrating procurement among capital-intensive OEMs with integrated aftertreatment.
- Above 500 kW:High-capacity engines for prime power in industrial parks, data centers, and utility peaking plants. Caterpillar manufacturing scale anchors position in these contracts across the United States and India.
- 100-300 kW:Light commercial and small industrial applications with moderate runtime requirements.
- Below 100 kW:Residential backup and small commercial standby with price-sensitive procurement patterns.
Above 500 kW absorbs the bulk of installed capacity; 301-500 kW is climbing the fastest.
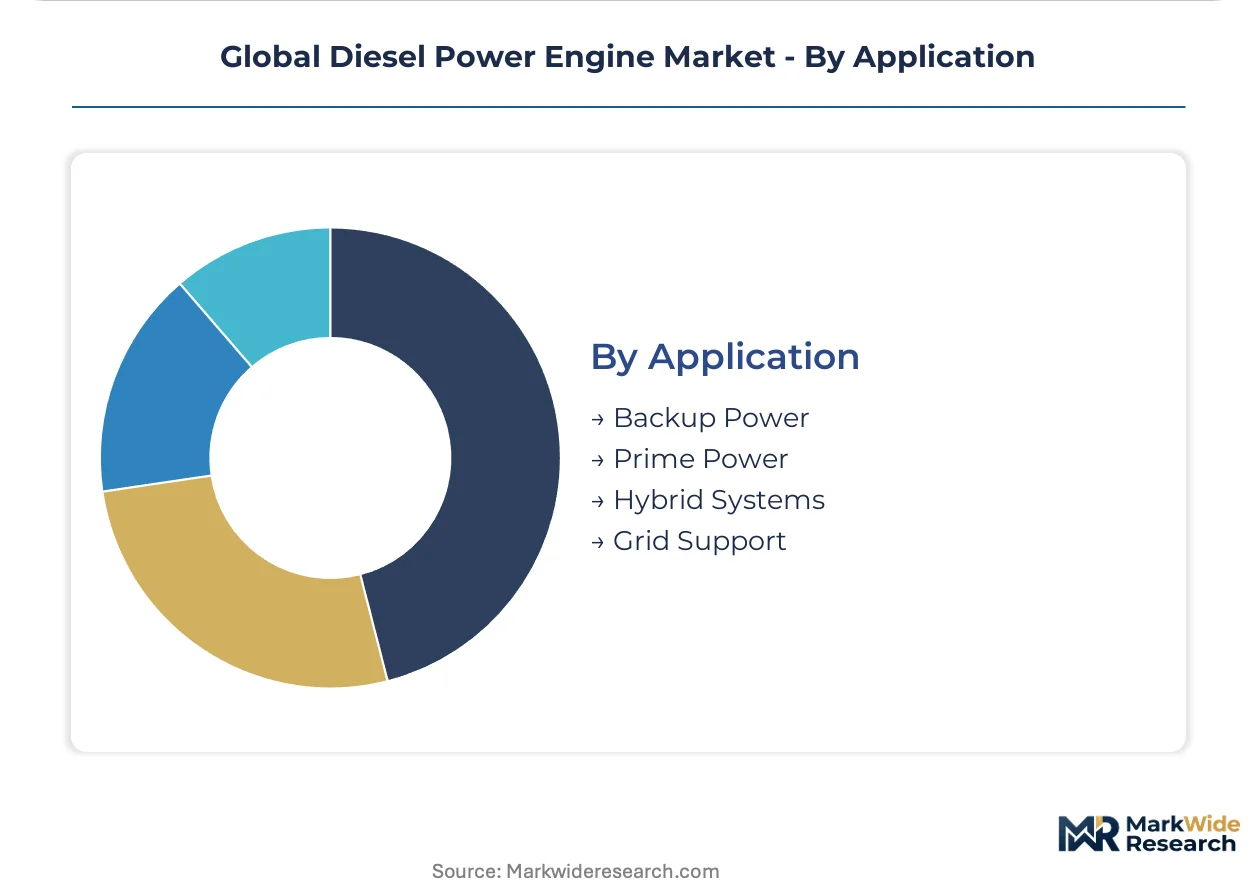
Application:
Customer type segmentation distinguishes mission-critical buyers with uptime guarantees from cost-optimized purchasers with flexible runtime tolerance.
- Prime Power:Continuous-duty operation where diesel serves as the primary energy source, prevalent in off-grid mining and remote industrial processing. Southeast Asian manufacturing corridors in Vietnam and Indonesia drive specification intensity as grid reliability gaps persist.
- Hybrid Systems:Converged diesel-battery architectures unifying spinning reserve, peak shaving, and renewable firming functions. Data center operators specify these configurations to bridge grid instability while reducing fuel consumption during partial load intervals.
- Backup Power:Emergency standby with automatic transfer switching for commercial and institutional facilities.
- Grid Support:Ancillary services including frequency regulation and voltage support in weak grid zones.
Prime power absorbs the bulk of installed capacity; hybrid systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Indonesia concentrate diesel power engine procurement as manufacturing investors secure captive generation ahead of grid extension timelines.
United States
Data center construction in Virginia's Loudoun County and Texas's Dallas-Fort Worth metroplex drives specification intensity for EPA Tier 4 Final certified engines. The EPA enforces particulate matter limits that eliminate non-certified suppliers from prime power contracts. Midwest manufacturing clusters in Ohio and Michigan are replacing aging standby fleets with electronic governing platforms.
India
Hyperscale facility operators in Maharashtra's Mumbai-Pune corridor and Karnataka's Bangalore region expand captive diesel capacity to bridge grid reliability gaps. The Central Electricity Authority mandates emission-compliant engine procurement for captive power plants above threshold capacities. Tamil Nadu's industrial parks near Chennai are retrofitting prime power installations with Stage V-equivalent aftertreatment systems.
Germany
Industrial facilities in North Rhine-Westphalia's Ruhr region and Bavaria's Munich-Stuttgart axis face EU Stage V particulate number compliance deadlines. The F-Gas Regulation forces cooling circuit redesigns with alternative working fluids. Baden-Württemberg's automotive supplier parks are specifying hybrid diesel-battery configurations for peak shaving applications.
China
Manufacturing zones in Guangdong's Pearl River Delta and Jiangsu's Yangtze River Delta absorb medium-speed engine capacity for prime power applications. The Ministry of Ecology and Environment enforces dual carbon goals that compress certified supplier timelines. Shandong's industrial cities are upgrading standby fleets to meet tightened emission benchmarks.
Indonesia
Textile and electronics manufacturers in Java's Bekasi-Tangerang corridor invest in prime power diesel infrastructure as utility-scale additions lag electrification demand. The national energy regulator imposes emission guidelines on captive power installations above defined capacity thresholds. Batam's free trade zone is specifying fast-start generator sets for semiconductor fabrication facilities.
Global Diesel Power Engine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with emission-certified engine families concentrating procurement among capital-intensive OEMs with integrated aftertreatment. The supplier base compresses as homologation costs eliminate small-scale builders. Three archetypes dominate: integrated system providers with in-house turbocharging and fuel injection, component specialists licensing aftertreatment technology, and regional assemblers sourcing certified engine blocks. Competitive moves center on backward integration into emission control substrates and geographic expansion through joint ventures in Southeast Asian manufacturing corridors.
Among integrated system providers, Caterpillar and Cummins occupy positions defined by manufacturing scale and in-house certification capabilities. Weichai Power represents the cost-engineered industrial engine archetype competing aggressively in emerging market infrastructure projects. MAN and Mitsubishi Heavy Industries sit within the medium-speed prime power tier serving maritime auxiliary and stationary generation applications.
| Leading Market Players |
|---|
| MAN |
| Mitsubishi Heavy Industries |
| Caterpillar |
| Volvo Penta |
| HD Hyundai Infracore |
| Cummins |
| Rolls-Royce |
| Yanmar Holdings |
| Weichai Power |
| Others |
Supply Flow & Price Mechanics
Aftertreatment calibration specialists in Germany's Ruhr industrial belt command wage premiums that compress OEM margins and widen spreads between Tier 4 Final-certified premium tiers and uncertified economy alternatives. Labor-cost differentials between Western European engineering centers and Southeast Asian assembly hubs directly feed into three-tier pricing stratification across industrial, standby, and portable generator segments.
Pricing Analysis
Lead-time premiums dominate transaction economics, with spot inventory of EPA-certified engine blocks trading at discounts against six-month forward contracts for integrated aftertreatment platforms. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the sub-300 kW standby tier intensifies as battery energy storage captures four-hour runtime applications. Construction buyers in Vietnam exhibit highest price sensitivity; data center operators in India demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Single-source vulnerability sits with palladium and rhodium suppliers in South Africa and Russia, where platinum group metal refining concentrates. Turbocharger castings draw from precision manufacturing clusters in Germany, Japan, and China. Common rail injection systems rest on German and Japanese component specialists. Tariff exposure on aftertreatment substrates threatens margin stability for multi-region platform builders. Distribution runs through factory-authorized service networks in North America and Western Europe, with independent dealers dominating Southeast Asian construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification cost burdens are forcing consolidation among small-scale engine builders unable to absorb EPA Tier 4 Final and EU Stage V homologation expenses. Surviving players must capture scale economies in aftertreatment integration or exit to branded OEMs.
For Market Incumbents: Lock in captive power plant contracts in India's Maharashtra and Karnataka industrial corridors before CEA emission guidelines fully phase in. Secure backward integration into selective catalytic reduction substrate supply through long-term offtake agreements with South African refiners. Battery-hybrid system architectures from competitor energy storage vendors threaten prime power diesel share in data center applications; counter with fast-start genset-battery integrated platforms certified for NFPA 110 Tier IV compliance. For New Entrants and Emerging Players: Harbor craft operators in Southeast Asian free trade zones represent an underserved buyer archetype facing IMO Tier III compliance deadlines without established retrofit supply chains. Target medium-speed diesel auxiliary power retrofits for offshore support vessels in Indonesia's Batam zone and Vietnam's Vung Tau port cluster. Pursue licensing arrangements with Japanese or German engine block specialists to bypass capital-intensive certification development, then layer proprietary aftertreatment integration for regional emission mandates. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier OEMs possessing EPA Tier 4 Final certification but lacking integrated turbocharger manufacturing, given consolidation pressure from Caterpillar and Cummins manufacturing scale. These targets offer platform breadth across 301-500 kW and above-500 kW tiers with service contract recurring revenue. Long-term viability hinges on hybrid system integration capabilities rather than pure compression-ignition positioning. Monitor battery energy density improvements in the 4-8 hour runtime band as the inflection signal for standby generator demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aftertreatment Substrates | Captive palladium and rhodium supply locks in margin control against commodity volatility from South African refiners. |
| Hybrid System Platform Development | Converged diesel-battery architectures capture data center spinning reserve contracts from pure genset competitors. |
| CEA Certification Pre-Positioning | Early EPA Tier 4 Final homologation accelerates vendor qualification for India's captive power plant procurement mandates. |
| Southeast Asian Joint Venture Manufacturing | Local assembly in Vietnam and Indonesia bypasses logistics chokepoints and tariff exposure on complete engine imports. |
| Maritime Auxiliary Retrofit Service Networks | IMO Tier III compliance deadlines in Indonesian and Vietnamese harbor zones open aftermarket revenue streams for medium-speed platforms. |
Methodological Framework
Independent corroboration across plant engineers at industrial facilities, procurement leads at data center operators, and aftermarket service heads at OEM-authorized networks underwrites the qualitative findings. Primary interviews with maintenance directors in North American manufacturing clusters and EPC contractors in Southeast Asia combined with secondary validation from EPA certification databases, EU Stage V homologation registries, and CEA captive power compliance filings. Bottom-up unit economics triangulate against top-down market sizing across capacity tiers and application segments.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models product type, end user, capacity tier, and application dimensions alongside regional regulatory cluster differentiation. CAGRs derive from segment-level unit forecasts and average selling price trajectories. Key inputs include EPA Tier 4 Final certification timelines, battery energy density improvement curves, and platinum group metal price band assumptions.
Revisions become necessary when battery energy density breakthroughs accelerate standby generator displacement or when India's CEA mandates tighten faster than current implementation schedules. Forecasts reflect assumptions about emission regulation enforcement consistency and grid reliability improvement rates in Southeast Asian manufacturing corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Temporary Load Bank Rental Market
Power
HVDC Capacitor Market
Power
Wind Turbine Drivetrain Market
Power
Europe Power Market
Power
Smart PV Inverters Market
Power
Portugal Power Market
Power
Malaysia Power EPC Market
Power
LNG Power Barge Market
Power
Europe Power Purchase Agreement Market
Power
China Power Market
Power
Digital Power Utility Market
Power
Substation Automation System Market
Power
Power Shelf Market
Power
Wireless Power Receiver Market
Power
Brunei Power Market
Power
Distributed Buoyancy Modules Market