
 Distributed Buoyancy Modules Market | 2026-2036
Distributed Buoyancy Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Buoyancy Modules Market Outlook
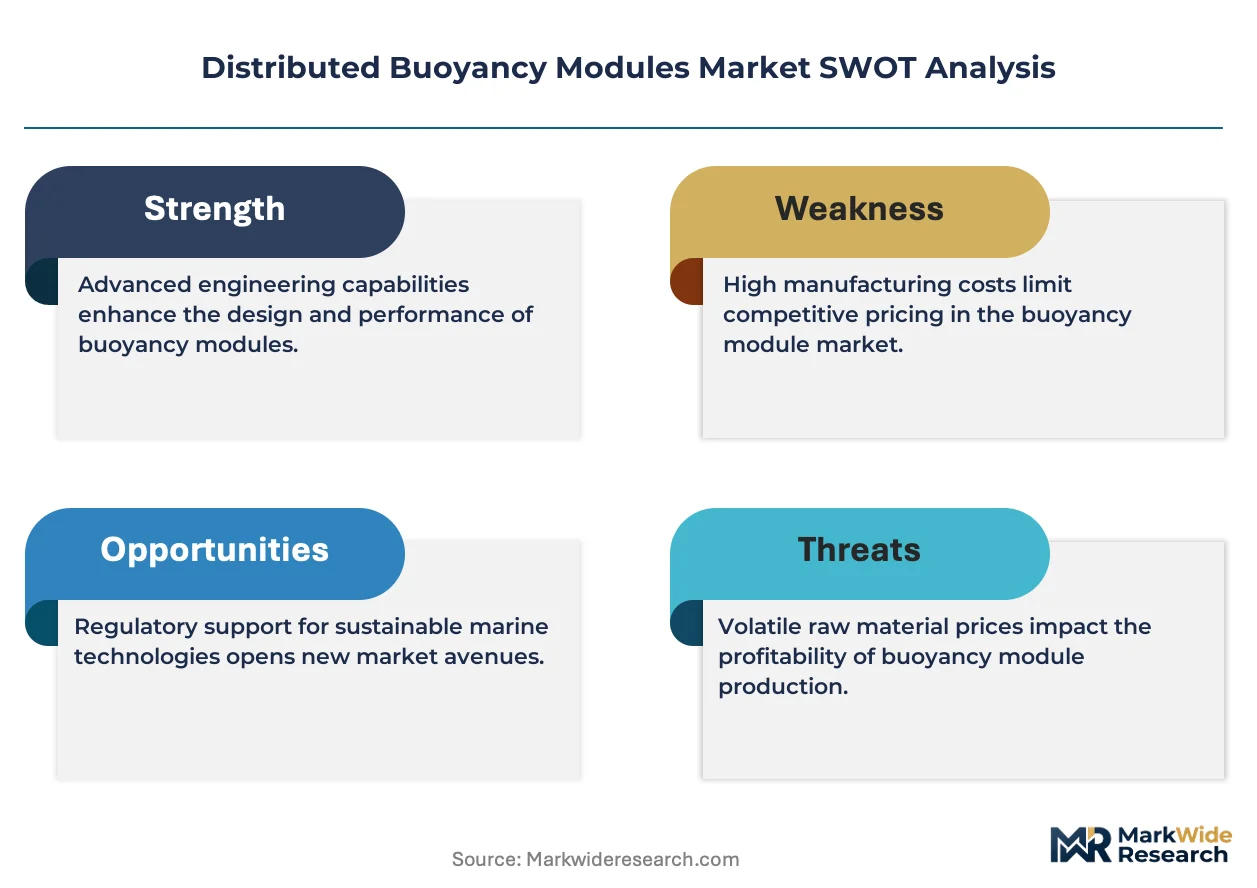
Multi-source procurement of buoyancy modules is expanding as operators diversify supply risk across deepwater projects. Forum Energy Technologies leverages integrated subsea service capabilities to sustain long-term contracts with major operators. Trelleborg anchors its position through advanced polymer and composite material expertise in harsh environment applications. Balmoral Offshore Engineering specializes in custom-engineered buoyancy solutions for ultra-deepwater installations.
Distributed buoyancy modules are structural flotation devices, typically constructed from syntactic foam composites encased in protective polymer shells, designed to provide localized uplift forces along subsea risers, umbilicals, and flowlines at depths exceeding 3,000 meters. Their primary industrial purpose is to maintain optimal riser configuration, reduce top tension loads, and prevent buckling or fatigue damage in dynamic offshore environments. Modular units dominate current procurement volumes due to standardized installation protocols and field-proven reliability across multiple water depths. Subsea buoys represent the fastest-growing product category as tieback architectures for marginal fields proliferate. Oil and gas end users command the largest share of deployed capacity, though research institutions are gaining traction for deep-sea observatory infrastructure.
API RP 2RD and DNV-ST-F203 govern riser and dynamic submarine pipeline design standards, while BSEE enforces safety and environmental compliance for US offshore operations. Brazil's ANP and Norway's PSA impose additional certification requirements for deepwater equipment deployed in their respective pre-salt and North Sea basins. Stakeholders must monitor evolving decommissioning liabilities and circularity mandates as regulators tighten material traceability and end-of-life recovery obligations for subsea hardware.
Market Dynamics
Deepwater field economics are compressing project timelines and forcing riser system standardization, which is modularizing buoyancy procurement patterns across Brazil, Norway, and the US Gulf of Mexico development corridors.
Growth Catalysts
- Pre-salt expansion:Brazil's ANP production-sharing framework is accelerating subsea tieback deployments in the Santos Basin, requiring distributed buoyancy systems for steel lazy-wave riser configurations at depths exceeding 2,000 meters.
- Syntactic foam advances:Glass microsphere-hybrid formulations are extending depth ratings to 4,000 meters while reducing module dry weight by 15-20 percent versus conventional epoxy systems.
- Decommissioning liability rules:Norway's PSA circularity mandates are forcing material traceability upgrades that favor modular, recoverable buoyancy architectures over permanent installations.
Market Restraints
- Raw material concentration:Hollow glass microsphere supply concentrates among three specialty chemical producers in the US and Japan, creating input cost volatility for syntactic foam compounders.
- Installation vessel scarcity:Heavy-lift subsea construction spreads in the North Sea and Gulf of Mexico face 18-24 month charter backlogs, compressing project windows.
- Polymer shell degradation:Long-term hydrostatic creep in thermoplastic polyurethane encapsulants limits module service life to 25 years in ultra-deepwater pressure cycling environments.
Strategic Opportunities
- West Africa underpenetration:Angola and Nigeria subsea developments currently import 90 percent of buoyancy systems from European fabricators, creating localization incentives under domestic content requirements.
- Offshore wind hybrid moorings:Floating offshore wind platforms in the Celtic Sea and US Northeast are adopting adapted oil and gas riser buoyancy technology for dynamic power cable management.
- Digital twin integration:Real-time structural monitoring of buoyancy modules is converging with subsea IoT sensor networks, enabling predictive maintenance contracts.
Industry Challenges
- Composite engineering talent scarcity:Deepwater pressure vessel design expertise concentrates among retiring specialists in Houston, Stavanger, and Rio de Janeiro, constraining R&D throughput.
- API RP 2RD certification timelines:Third-party validation of new buoyancy materials for sour service environments requires 14-18 month test protocols, delaying field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Buoyancy Modules Market |
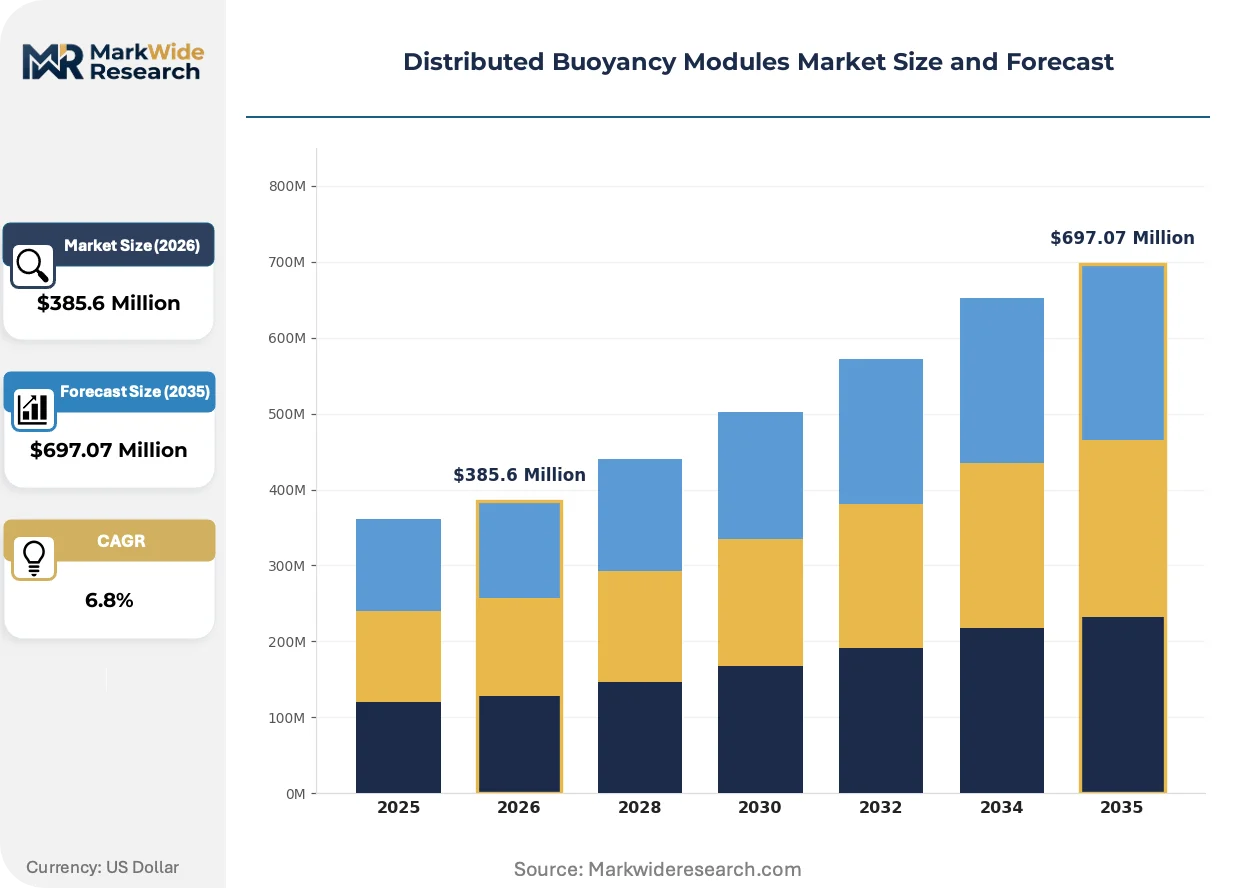
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Subsea Buoys, Surface Buoys, Inflatable Systems End User: Marine Industry, Oil & Gas, Research Institutions, Defense Contractors Application: Underwater Exploration, Oceanographic Research, Oil Spill Response, Marine Safety Installation: Permanent Installations, Temporary Deployments, Modular Arrangements, Custom Solutions |
| Companies Covered | Advanced Insulation, Forum Energy Technologies, Trelleborg, ALSEAMER, Floatex, Balmoral Offshore Engineering, DeepWater Buoyancy, CRP Subsea, Matrix Composites and Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Buoyancy Modules Market Strategic Shifts
Material science breakthroughs and regulatory pressure on subsea hardware circularity are reshaping how buoyancy systems are engineered, certified, and recovered across deepwater basins.
Syntactic foam composites with hybrid ceramic microsphere fillers are modularizing deepwater riser architecture by enabling variable buoyancy density gradients within single-module extrusions. Offshore operators in Brazil's pre-salt province are specifying these graded-density systems for steel catenary riser lazy-wave configurations. The technology is modularizing procurement patterns by allowing operators to stock standardized module segments rather than custom-engineering each riser string.
Norway's PSA and the UK's HSE are tightening material passport requirements for subsea equipment under North Sea decommissioning protocols, forcing buoyancy manufacturers to embed RFID traceability tags and publish full polymer formulation disclosure. This regulatory shift is accelerating design-for-disassembly practices among European fabricators. The compliance burden falls heaviest on legacy module architectures with bonded steel end-fittings that complicate material separation.
Integrated service contracting is displacing discrete equipment purchasing as major operators bundle buoyancy module supply with installation, inspection, and recovery obligations across multi-field development programs. This procurement consolidation favors vendors with captive diving spreads and subsea construction assets. The shift is most visible in the US Gulf of Mexico, where supermajor operators have moved to decade-long integrated riser system agreements.
Distributed Buoyancy Modules Market Segmentation
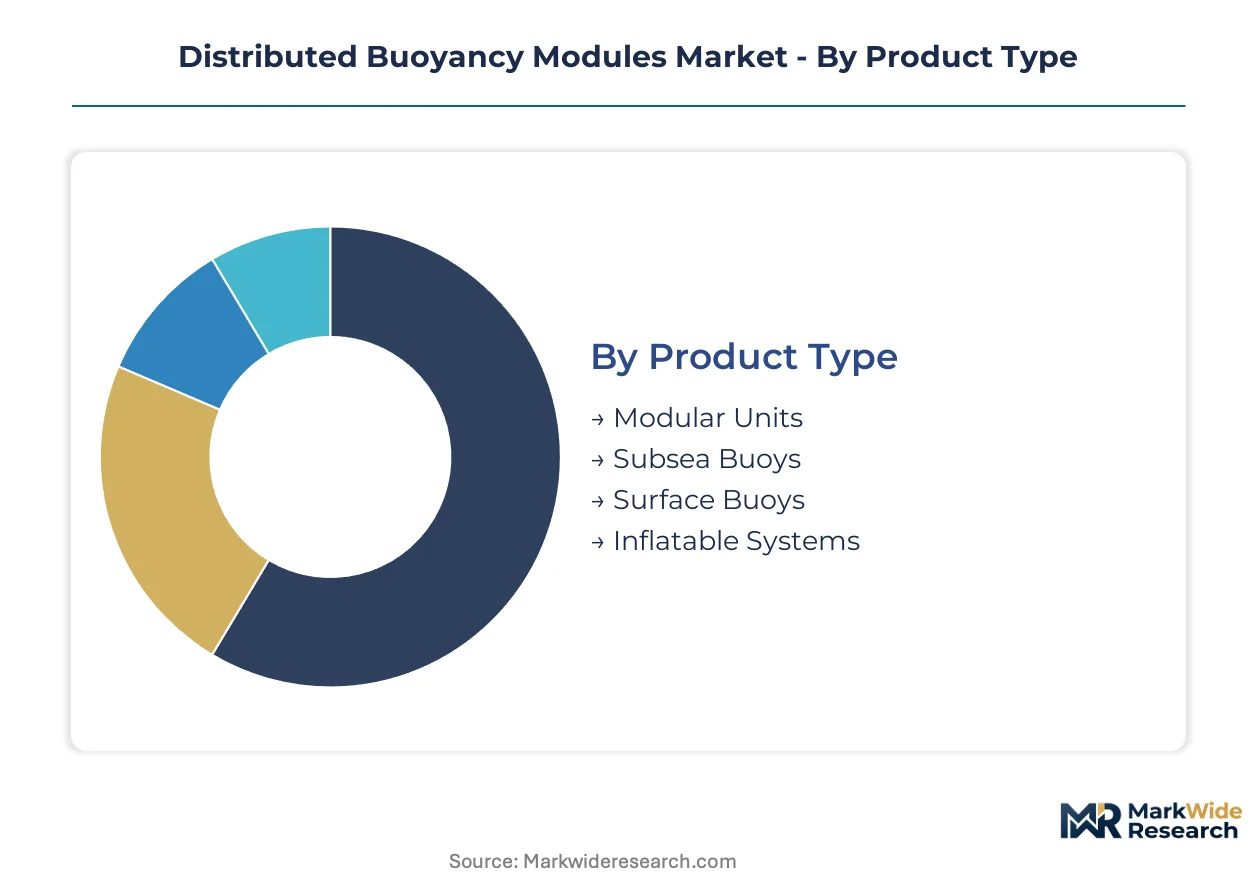
Distributed buoyancy modules serve divergent operational regimes across subsea infrastructure, with certification requirements varying sharply by depth rating and pressure cycling exposure. Segmentation reveals how procurement patterns split between standardized modular systems and custom-engineered solutions for extreme environments.
Product Type:
API RP 2RD and DNV-ST-F203 impose distinct validation protocols on each product category, with depth-rated syntactic foam systems facing 14-18 month certification timelines versus surface-rated alternatives.
- Modular Units:Standardized syntactic foam segments encased in thermoplastic polyurethane shells enable rapid field assembly for steel lazy-wave riser configurations. Brazil's pre-salt operators in the Santos Basin specify these for tieback architectures at 2,000+ meter depths, driven by ANP production-sharing frameworks accelerating subsea deployment timelines.
- Subsea Buoys:Integrated flotation assemblies with steel or composite structural cores provide concentrated uplift forces for umbilical termination and flowline support. Norway's North Sea developments favor these for marginal field tiebacks under PSA circularity mandates requiring recoverable hardware architectures.
- Surface Buoys:Polyethylene or steel-hulled marker systems for temporary mooring and navigation aids.
- Inflatable Systems:Flexible bladder-based flotation for emergency response and rapid deployment scenarios.
Modular Units sit at the top of the volume ranking, with Subsea Buoys climbing the fastest.
End User:
Customer procurement sophistication spans from commodity spot purchasing to decade-long integrated service contracts, with contract duration directly correlating to technical specification complexity.
- Oil & Gas:Supermajor operators in the US Gulf of Mexico and Norway command the largest deployed capacity, bundling buoyancy supply with installation and recovery obligations across multi-field programs. BSEE and PSA enforcement of decommissioning liabilities drives preference for modular, retrievable architectures over permanent installations.
- Research Institutions:Deep-sea observatory infrastructure in the Pacific and Atlantic basins requires precision-engineered buoyancy for long-duration sensor moorings. Academic procurement emphasizes depth rating certification and material traceability over cost optimization.
- Marine Industry:Commercial shipping and aquaculture operators for temporary marking and net support systems.
- Defense Contractors:Naval applications for submarine rescue training and underwater vehicle support.
Oil & Gas captures the dominant revenue share, while Research Institutions expand most quickly.
Application:
Functional requirements dictate material selection, with oil spill response demanding rapid-deployment inflatable systems versus oceanographic research specifying 25-year service life syntactic foam.
- Oil Spill Response:Containment boom flotation and skimmer support systems require UV-stable polymer shells resistant to hydrocarbon exposure. US Coast Guard certification under 33 CFR standards governs procurement for emergency response stockpiles.
- Underwater Exploration:ROV and submersible support platforms utilize variable-density foam modules for precise buoyancy trim. Technical diving operations in the Gulf of Mexico and Mediterranean concentrate demand for portable, depth-rated systems.
- Oceanographic Research:Long-duration moorings for climate monitoring arrays.
- Marine Safety:Navigation aids and emergency evacuation systems.
Oil Spill Response leads procurement volumes, with Underwater Exploration gaining share fastest.
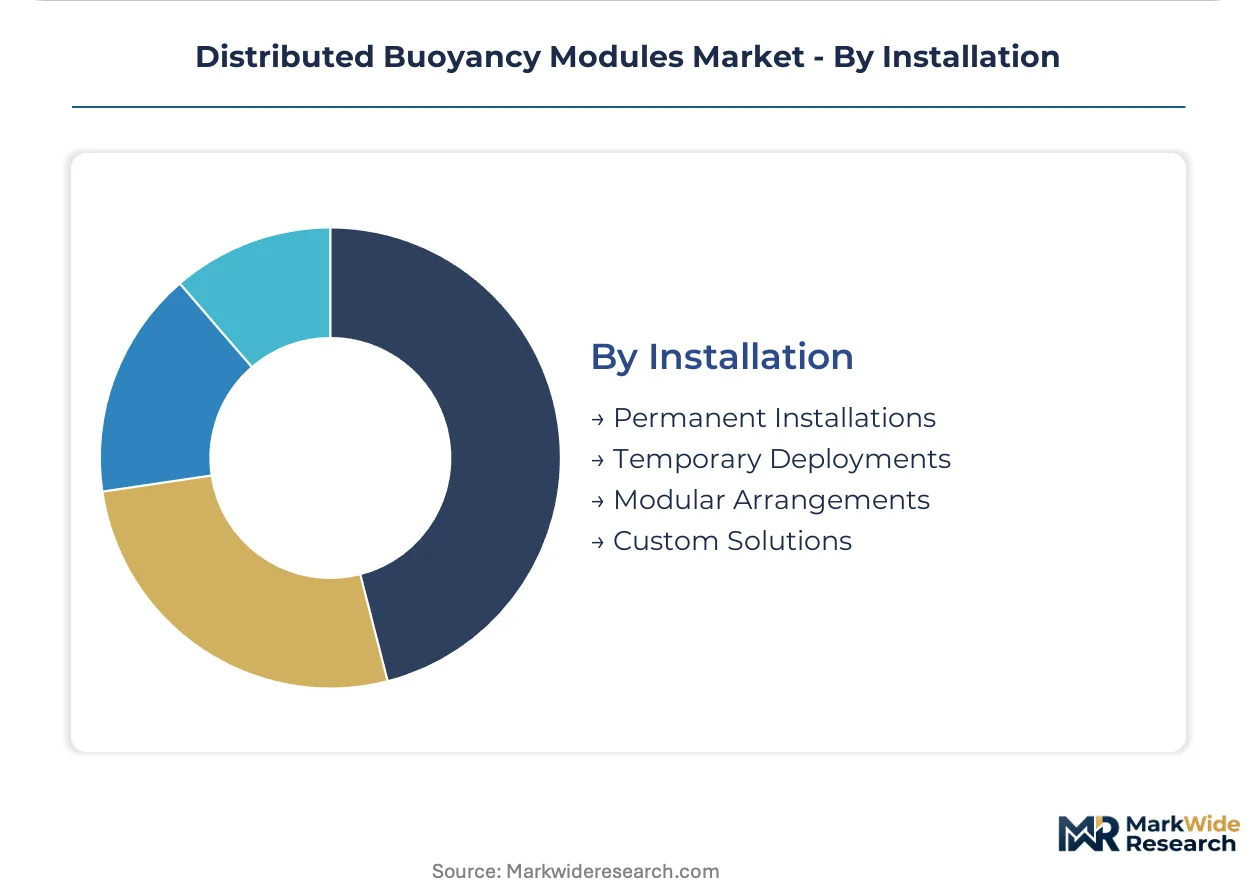
Installation:
Installation modality determines supply chain configuration, with permanent seabed anchoring requiring heavy-lift vessel spreads versus temporary deployments utilizing standard workboat fleets.
- Permanent Installations:Piled or suction-anchored systems for field-life riser support face tightening decommissioning liabilities under Norway's PSA and UK HSE protocols. Material passport requirements now mandate RFID traceability and full polymer formulation disclosure.
- Modular Arrangements:Reconfigurable segment stacks allow operators to adapt buoyancy distribution across field development phases. Standardized connection interfaces enable inventory pooling across multiple offshore assets.
- Temporary Deployments:Seasonal or campaign-based installations for exploration and appraisal drilling.
- Custom Solutions:Bespoke engineered systems for unique geometric or load constraints.
Permanent Installations dominate capital deployment, with Modular Arrangements expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf of Mexico anchors deepwater buoyancy demand through supermajor-operated subsea developments in the Lower Tertiary and Paleogene plays. Brazil's pre-salt Santos Basin drives the fastest procurement growth as ANP production-sharing frameworks accelerate steel lazy-wave riser deployments.
United States
BSEE decommissioning liability rules favor modular, retrievable buoyancy architectures over permanent seabed installations in the Gulf of Mexico. The Lower Tertiary trend concentrates demand for 3,000-meter depth-rated syntactic foam systems around Houston's subsea engineering cluster. Heavy-lift vessel scarcity in the region extends project timelines by 18-24 months.
Brazil
ANP production-sharing contracts mandate accelerated subsea tieback schedules in the Santos Basin pre-salt province. Local content requirements under the Prouni program pressure operators to source buoyancy modules through domestic fabricators. The Rio de Janeiro metropolitan area hosts the primary concentration of subsea service contractors serving Petrobras-led developments.
Norway
PSA circularity mandates enforce material passport requirements and end-of-life recovery obligations for North Sea subsea hardware. Stavanger anchors Europe's deepest expertise in composite pressure vessel engineering for ultra-deepwater applications. Operators specify recoverable buoyancy architectures to minimize decommissioning liabilities under tightening HSE protocols.
United Kingdom
HSE material traceability rules under North Sea decommissioning frameworks force RFID tagging and full polymer formulation disclosure for subsea equipment. Aberdeen's subsea engineering cluster specializes in design-for-disassembly buoyancy modules serving marginal field tiebacks. The UK Continental Shelf faces accelerating platform removal schedules that favor retrievable over permanent installations.
Angola
Domestic content requirements under Sonangol procurement rules create localization incentives for buoyancy system fabrication in West Africa. Block operators currently import 90 percent of modules from European suppliers, exposing projects to currency and logistics risk. The Luanda-Benguela corridor concentrates subsea construction activity for deepwater developments in Blocks 15, 17, and 32.
Distributed Buoyancy Modules Market Competitive Environment
Global majors compete with regional champions across integrated service capabilities and material science specialization. The vendor base clusters around three strategic tiers: full-service subsea contractors with captive installation assets, advanced polymer and composite material specialists, and custom-engineering boutiques for ultra-deepwater applications. Consolidation pressure intensifies as operators bundle multi-field supply contracts. Capacity expansion in syntactic foam compounding and strategic partnerships for heavy-lift vessel access represent dominant competitive vectors.
Among UK-based fabricators, Balmoral Offshore Engineering and Floatex occupy positions within the custom-engineering tier for harsh-environment applications. Forum Energy Technologies exemplifies the integrated service model through its combination of module supply and subsea construction capabilities. These three entities represent distinct strategic archetypes: material-forward specialization, project-specific engineering, and bundled service contracting.
| Leading Market Players |
|---|
| Advanced Insulation |
| Forum Energy Technologies |
| Trelleborg |
| ALSEAMER |
| Floatex |
| Balmoral Offshore Engineering |
| DeepWater Buoyancy |
| CRP Subsea |
| Matrix Composites and Engineering |
| Others |
Value Chain & Pricing Dynamics
Hollow glass microsphere price indices cascade through syntactic foam compounding tiers, compressing margins for mid-range module fabricators while premium depth-rated systems retain pricing power through certification scarcity and ANP-mandated local content premiums in Brazil.
Pricing Analysis
Input-cost pass-through from ceramic microsphere and thermoplastic polyurethane feedstocks stratifies pricing across certification-grade tiers. Premium-mid-economy pricing differentiation separates API RP 2RD-validated systems for sour service from unrated alternatives, with DNV-ST-F203 depth ratings commanding substantial premiums. Cost compression in standard modular units is intensifying because Brazilian fabricators face Prouni local content requirements without captive glass microsphere supply. National oil companies exhibit lowest price sensitivity due to integrated service contracting, while independent exploration operators in West Africa remain most cost-conscious.
Supply Chain Analysis
Freight cost volatility from heavy-lift vessel charter backlogs in the North Sea and Gulf of Mexico amplifies landed cost differentials for European fabricators serving Angola and Nigeria. Manufacturing concentrates in Norway, the United Kingdom, and Brazil, with syntactic foam compounding anchored in Houston and Stavanger. Raw material procurement draws from hollow glass microsphere specialists in the United States and Japan, plus thermoplastic polyurethane resin systems from German chemical producers. Single-source vulnerability in microsphere supply creates exposure to input cost spikes. Distribution runs through integrated subsea service contractors with captive installation spreads rather than discrete equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Norway's PSA circularity mandates and BSEE decommissioning rules force operators toward recoverable, traceable buoyancy architectures with 25-year service life specifications.
For Market Incumbents: Anticipate margin compression from Brazilian local content requirements by securing captive heavy-lift vessel access through long-term charter agreements or partnerships with subsea construction specialists. Deepen backward integration into syntactic foam compounding to offset hollow glass microsphere supply concentration. Prioritize RFID traceability tag integration and design-for-disassembly engineering to meet UK HSE material passport obligations ahead of competitors.
For New Entrants and Emerging Players: Research institutions deploying deep-sea observatory infrastructure present an underserved buyer archetype with lower certification barriers and longer procurement cycles than oil and gas supermajors. West African domestic content requirements under Sonangol rules create fabrication localization opportunities for modular buoyancy systems. Pursue joint development agreements with regional subsea engineering clusters in Luanda or Benguela to establish presence before European incumbents expand local capacity.
For Investors and Strategic Acquirers: Consolidation pressure builds where integrated service contracting favors vendors with captive diving spreads and multi-field installation capabilities. The five-to-ten year viability window favors material science specialists with proven depth ratings above 3,000 meters and established relationships with Petrobras, Equinor, or Chevron. Acquisition targets should demonstrate compound formulation expertise and API certification track records. Watch for inflection when ANP accelerates pre-salt production-sharing timelines or when PSA tightens end-of-life recovery liability calculations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Syntactic Foam Compounding | Hollow glass microsphere supply concentration in US and Japanese specialty chemical producers creates margin vulnerability for fabricators without captive compounding capacity. |
| Heavy-Lift Vessel Charter Partnership | Eighteen-to-twenty-four month charter backlogs in the North Sea compress project windows and favor vendors with assured installation spread access. |
| RFID Traceability Tag Integration | Norway's PSA and UK HSE material passport requirements now mandate full polymer formulation disclosure and end-of-life recovery tracking. |
| Design-for-Disassembly Engineering | Legacy bonded steel end-fittings complicate material separation under tightening circularity mandates, favoring modular recoverable architectures. |
| Research Institution Partnership Program | Deep-sea observatory infrastructure in Pacific and Atlantic basins offers lower-certification entry point with academic procurement emphasizing depth rating over cost optimization. |
Study Parameters
Coverage spans the United States Gulf of Mexico, Brazil, Norway, the United Kingdom, and Angola, with primary inputs from each basin's subsea engineering clusters. The approach combines structured interviews with subsea project engineers, procurement leads at national oil companies, composite materials R&D directors, heavy-lift vessel operators, and regulatory compliance officers with secondary validation through BSEE enforcement records, ANP production-sharing contract disclosures, PSA circularity mandate texts, and DNV certification databases. Bottom-up module deployment estimates triangulate against top-down field development capex allocations.
Granularity-level modeling distinguishes modular units from subsea buoys across oil and gas versus research institution end users, with separate treatment of permanent installation and modular arrangement modalities. Depth rating tiers, polymer shell specifications, and regional regulatory clusters constitute additional segmentation dimensions. CAGRs derive from basin-specific field development timelines and tieback architecture adoption curves. Forecast inputs include Petrobras pre-salt development schedules, Equinor decommissioning liability provisions, and floating offshore wind power cable management technology transfer rates.
Underlying measurement precision varies by segment; oil and gas procurement volumes carry tighter precision than research institution deployments due to disclosed contract values and visible installation vessel utilization. Forecasts reflect assumptions regarding ANP production-sharing acceleration, PSA circularity enforcement timing, and syntactic foam depth rating advancement trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Wind Turbine Drivetrain Market
Power
Wireless Power Receiver Market
Power
Global UPS Market
Power
Global Advanced Marine Power Supply Market
Power
Brunei Power Market
Power
Japan Power Market
Power
Europe Microturbine Market
Power
Australia Power Market
Power
Residential Portable Inverter Generator Market
Power
China Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Modular PSA Nitrogen Generator Market
Power
Canada Thermal Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Rotating Phase Converter Market
Power
Power Capacitors Market