
 HVDC Capacitor Market | 2026-2036
HVDC Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Capacitor Market Outlook
Specialized power electronics engineering talent is redrawing competitive boundaries in HVDC capacitor supply. Siemens anchors European converter station projects through captive component qualification programs. Hitachi leverages its grid infrastructure heritage to dominate Japanese offshore wind interconnections. TDK Corporation sustains margin pools via deep specialization in polypropylene film dielectrics for high-voltage DC filtering.
HVDC capacitors store and regulate electrical energy in direct-current transmission systems, typically employing metallized polypropylene film wound into cylindrical or rectangular housings with voltage ratings exceeding 10 kVDC and capacitance values from microfarads to millifarads. These components smooth voltage ripple, protect semiconductor switches from transient overvoltages, and enable efficient power transfer across submarine cables and asynchronous grid interties spanning hundreds of kilometers. Film capacitors occupy the dominant position in converter station DC-links due to their self-healing dielectric properties and extended operational life under repetitive voltage stress. Voltage Source Converter technology represents the fastest-expanding segment as point-to-point and multi-terminal HVDC schemes displace line-commutated alternatives in renewable integration applications.
FERC Order 2023 and the EU Green Deal's offshore wind targets are tightening grid-code compliance requirements for capacitor banks in US and European interconnector projects. China's GB/T standards under SAMR oversight now mandate accelerated aging tests for film capacitors deployed in ultra-high-voltage DC corridors exceeding 800 kV. Stakeholders must monitor divergence between IEC 61071 certification pathways and emerging national test protocols that could fragment supplier qualification timelines.
Market Dynamics
Voltage Source Converter technology is compressing capacitor form factors while multiplying switching frequency demands, forcing suppliers to recalibrate dielectric film thickness-to-voltage tolerance ratios across converter station procurement specifications.
Growth Catalysts
- EU Green Deal offshore wind mandates:Germany's North Sea corridor requires multi-terminal HVDC schemes that expand DC-link capacitor deployment in TenneT and 50Hertz interconnector stations.
- China's dual carbon goals:SAMR oversight of GB/T standards accelerates domestic manufacturing scale-up for ultra-high-voltage DC corridors exceeding 800 kV.
- Metallized polypropylene film self-healing properties:Extended operational life under repetitive voltage stress drives replacement of oil-impregnated alternatives in submarine cable applications.
Market Restraints
- Polypropylene resin supply concentration:Feedstock for dielectric films concentrates among petrochemical complexes in the Middle East and Southeast Asia, exposing margins to hydrocarbon volatility.
- Specialized winding equipment scarcity:Cleanroom-grade machinery for high-voltage film capacitor production remains captive to German and Japanese machine-tool suppliers with 18-month order backlogs.
- IEC 61071 certification fragmentation:Divergence between international test protocols and emerging national standards in China and India extends supplier qualification timelines by 12-18 months.
Strategic Opportunities
- US offshore wind procurement:FERC Order 2023 compliance requirements for grid-code capacitor banks create first-mover advantages in Atlantic coast converter station projects.
- Modular multi-level converter topologies:Integration of silicon carbide semiconductors with film capacitor sub-modules enables higher power density in point-to-point transmission schemes.
- Direct sales to utility consortia:Bypassing traditional distributor channels through long-term framework agreements with transmission system operators secures volume commitments and reduces price volatility exposure.
Industry Challenges
- Power electronics engineering talent scarcity:Converter station design expertise for high-voltage DC filtering applications concentrates among aging specialist cohorts in Germany and Japan with limited knowledge transfer pipelines.
- Accelerated aging test infrastructure:GB/T and IEC protocol divergence forces duplicate capital expenditure on separate test bays for Chinese and European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Capacitor Market |
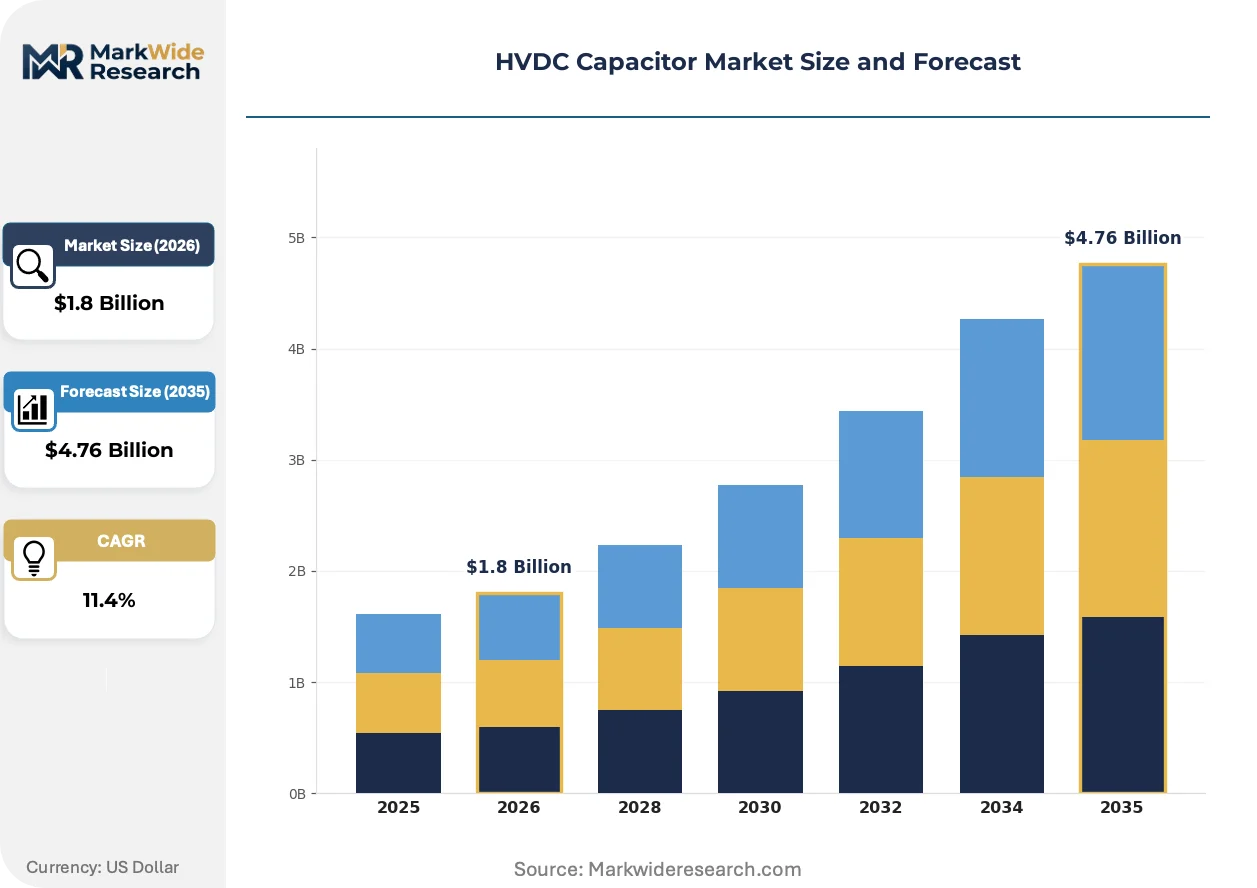
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Capacitors, Ceramic Capacitors, Electrolytic Capacitors, Paper Capacitors Technology: Modular Multilevel, Voltage Source Converter, Current Source Converter, Isolated DC/DC Converters End User: Renewable Energy, Power Utilities, Transmission Agencies, Industrial Applications Application: Wind Energy, Solar Power, Energy Storage Systems, Grid Integration |
| Companies Covered | Hitachi, General Electric, TDK Corporation, Eaton, Siemens, General Atomics, ABB, Vishay Intertechnology, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Capacitor Market Strategic Shifts
Capacitor architecture is compressing physical footprints while voltage ratings climb, creating tension between energy density targets and thermal management requirements in sealed converter housings.
Segmented electrode patterning in metallized polypropylene film is miniaturizing individual capacitor elements without sacrificing self-healing reliability. Offshore wind developers in the North Sea corridor specify these compact DC-link units for platform-constrained converter stations. The technology is compressing overall substation footprints by 30-40% compared to conventional wound constructions.
China's SAMR-mandated GB/T standards for ultra-high-voltage DC corridors now require accelerated aging tests that exceed IEC 61071 severity levels. Domestic suppliers must maintain parallel certification pathways to serve both export and captive markets. European incumbents face 18-24 month recalibration periods to align test protocols with Chinese procurement specifications.
Buyer concentration among transmission system operators is consolidating capacitor procurement into multi-year framework agreements. Traditional distributor intermediaries are losing share to direct manufacturer-utility contracting in Germany and the United Kingdom. TenneT and National Grid ESO now specify lifecycle cost guarantees that shift technical risk onto component suppliers.
HVDC Capacitor Market Segmentation
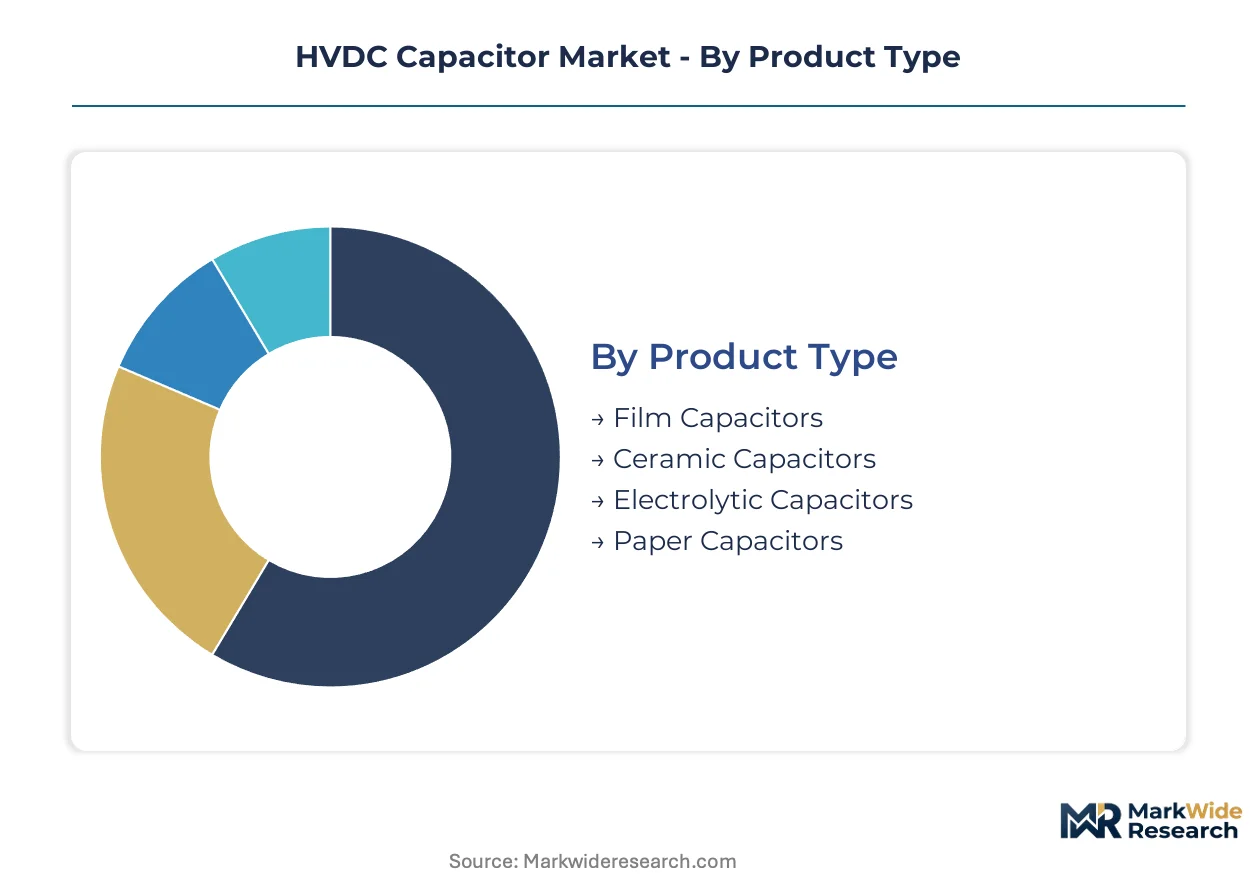
HVDC capacitor procurement specifications diverge sharply across converter station architectures and grid-code jurisdictions. Segmentation reveals where technical requirements concentrate procurement power among transmission system operators and renewable developers.
Product Type:
Regulatory differentiation in dielectric certification pathways separates qualified suppliers from commodity competitors across major procurement markets.
- Film Capacitors:Metallized polypropylene film wound into cylindrical or rectangular housings delivers self-healing dielectric properties essential for repetitive voltage stress in submarine cable applications. Germany's North Sea corridor procurement from TenneT and 50Hertz specifies these units exclusively for platform-constrained offshore converter stations.
- Ceramic Capacitors:Barium titanate-based multilayer constructions offer high capacitance density for snubber circuits and gate driver applications within modular multilevel converter sub-modules. China's SAMR-mandated GB/T standards for ultra-high-voltage DC corridors exceeding 800 kV restrict ceramic deployment to auxiliary circuits rather than primary DC-links.
- Electrolytic Capacitors:Aluminum oxide dielectric systems dominate bulk energy buffering in isolated DC/DC converter stages for industrial motor drives.
- Paper Capacitors:Oil-impregnated kraft paper constructions persist in legacy line-commutated converter retrofits where thermal cycling tolerance outweighs energy density requirements.
Established volume favors Film Capacitors; emerging adoption favors Ceramic Capacitors.
Technology:
Cost tier stratification in converter station procurement pushes Voltage Source Converter specifications toward premium capacitor grades with extended lifecycle guarantees.
- Modular Multilevel:Cascaded half-bridge sub-modules integrating film capacitors with silicon carbide semiconductors enable higher power density in point-to-point transmission schemes. Japan's METI-backed offshore wind interconnections specify these topologies for reduced harmonic filtering requirements.
- Voltage Source Converter:Self-commutated switching with insulated-gate bipolar transistors demands DC-link capacitors with microsecond-scale voltage ripple absorption. EU Green Deal offshore wind mandates in Germany and the United Kingdom concentrate procurement here for asynchronous grid interties.
- Current Source Converter:Thyristor-based line-commutated architectures require bulk capacitor banks for commutation support in legacy high-voltage DC corridors.
- Isolated DC/DC Converters:Medium-frequency transformer coupling with resonant tank capacitors serves industrial DC microgrid integration.
Modular Multilevel and Voltage Source Converter together capture the steepest expansion trajectory as point-to-point schemes displace line-commutated alternatives.
End User:
Customer type concentration among transmission system operators is consolidating procurement into multi-year framework agreements with lifecycle cost guarantees.
- Renewable Energy:Offshore wind developers in Germany's North Sea corridor specify compact DC-link units with 30-40% footprint compression versus conventional constructions. FERC Order 2023 compliance requirements in the United States are opening Atlantic coast procurement to qualified suppliers.
- Power Utilities:Vertically integrated European operators maintain captive component qualification programs that lock in preferred capacitor suppliers for converter station expansions.
- Transmission Agencies:China's State Grid and Southern Power Grid procurement under dual carbon goals accelerates domestic manufacturing scale-up for 800 kV-plus corridors.
- Industrial Applications:Steel and aluminum smelters deploy DC-link capacitors for asynchronous motor drives with regenerative braking energy recovery.
Renewable Energy leads absolute volume growth; Transmission Agencies control the largest individual procurement tickets.
Application:
Geography of installation determines thermal management specifications and accelerated aging test protocols required for market access.
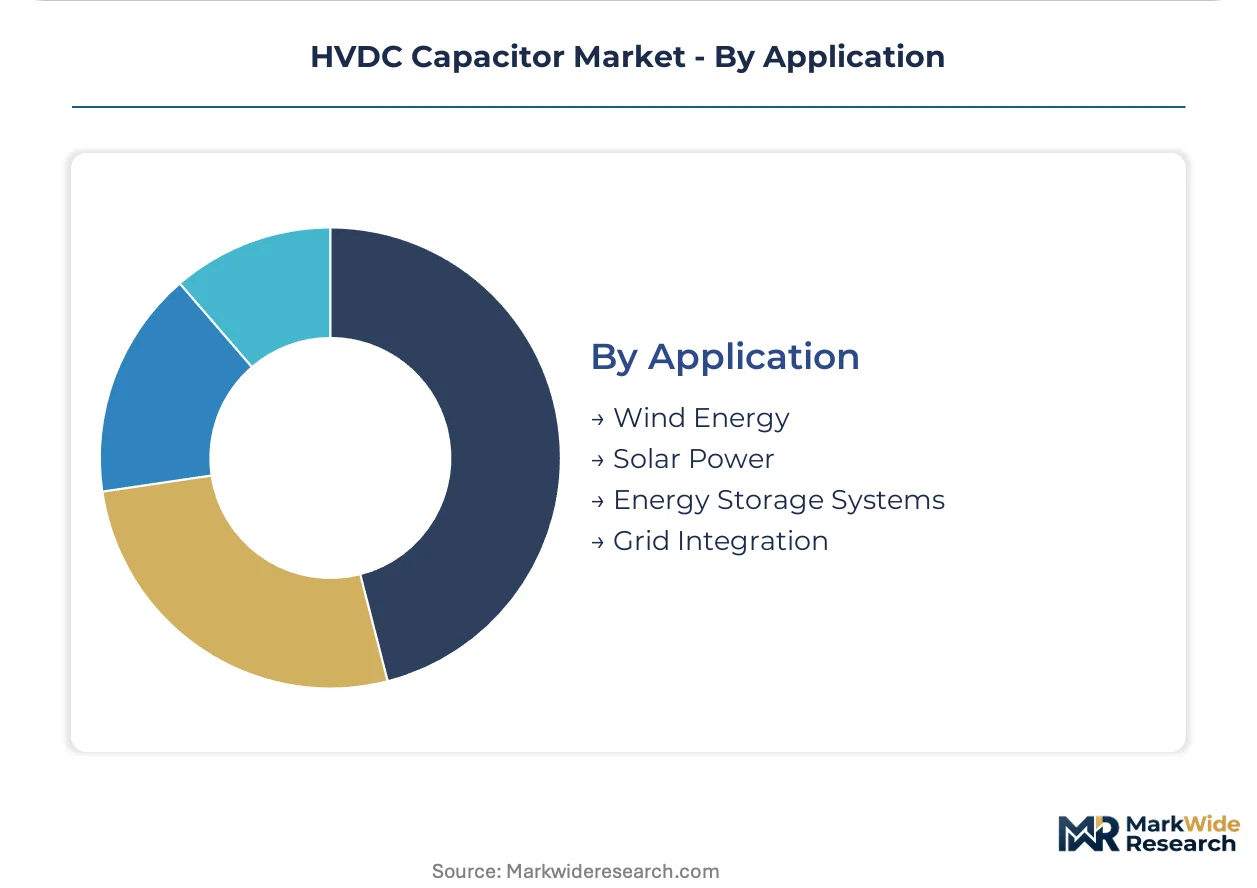
- Wind Energy:Offshore platform constraints drive demand for segmented electrode patterning in metallized film to miniaturize capacitor elements without sacrificing self-healing reliability. The United Kingdom's National Grid ESO and Germany's TenneT now specify these compact units exclusively.
- Solar Power:Utility-scale photovoltaic inverters with DC-link filtering require extended temperature range specifications for desert installations in the southwestern United States and Middle East.
- Energy Storage Systems:Battery energy storage system integration with HVDC interties demands bidirectional power flow capability in DC-link capacitor banks.
- Grid Integration:Asynchronous interconnector projects between national grids require harmonic filtering capacitors with IEC 61071 certification plus emerging national protocol alignment.
Wind Energy anchors current procurement volumes; Grid Integration offers the longest project pipelines across multi-terminal scheme developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes HVDC capacitors almost exclusively for offshore wind converter stations, whereas China deploys them across ultra-high-voltage transmission corridors spanning thousands of kilometers. This consumption-mix differential shapes procurement specifications and supplier qualification pathways in each geography.
United States
Atlantic coast offshore wind developers drive procurement of DC-link capacitors for converter platform installations. FERC Order 2023 tightens grid-code compliance requirements for capacitor banks in interconnector projects. Massachusetts and New York procurement offices now specify lifecycle cost guarantees that shift technical risk onto component suppliers.
Germany
TenneT and 50Hertz transmission system operators anchor European demand through multi-terminal HVDC schemes in the North Sea corridor. EU Green Deal offshore wind mandates accelerate converter station deployment schedules. Hamburg and Bremen industrial clusters host specialized winding equipment suppliers with 18-month order backlogs.
China
State Grid and Southern Power Grid procurement under dual carbon goals scales domestic manufacturing for 800 kV-plus DC corridors. SAMR oversight of GB/T standards mandates accelerated aging tests exceeding IEC 61071 severity levels. Xi'an and Shenyang manufacturing bases concentrate film capacitor production for captive and export markets.
Japan
METI-backed offshore wind interconnections specify modular multilevel converter topologies with reduced harmonic filtering requirements. Japanese transmission utilities favor domestic suppliers for grid infrastructure security. Nagoya and Osaka industrial districts maintain captive component qualification programs that lock in preferred capacitor vendors.
United Kingdom
National Grid ESO procurement concentrates on compact DC-link units with 30-40% footprint compression for platform-constrained North Sea installations. The country's net-zero grid commitments expand interconnector capacity to Norway and Denmark. Scottish and East Anglian offshore clusters specify segmented electrode patterning in metallized film for miniaturized capacitor elements.
HVDC Capacitor Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in HVDC capacitor supply, with converter station builders and component manufacturers occupying distinct competitive planes. Siemens and Hitachi anchor the integrated tier through captive component qualification programs tied to European and Japanese offshore wind projects. TDK Corporation occupies the specialist apex through deep concentration in polypropylene film dielectrics. Competitive moves center on backward integration into film extrusion capabilities and direct contracting frameworks with transmission system operators that bypass traditional distribution channels.
Among diversified industrial conglomerates, Hitachi and Siemens exemplify the integrated-leader archetype through grid infrastructure heritage spanning converter station engineering and component sourcing. TDK Corporation represents the deep-specialist position, with its corporate identity signaling concentrated expertise in electronic materials rather than system-level integration. These three anchors illustrate how competitive positioning in HVDC capacitors separates platform-scale project developers from materials-science purists, with each tier capturing margin pools through distinct value-chain control points.
| Leading Market Players |
|---|
| Hitachi |
| General Electric |
| TDK Corporation |
| Eaton |
| Siemens |
| General Atomics |
| ABB |
| Vishay Intertechnology |
| Murata Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Long-term framework agreements with transmission system operators lock in both polypropylene film supply access and price visibility for qualified suppliers, insulating margins from spot resin volatility while committing volumes to converter station projects across Germany and China.
Pricing Analysis
Project-based contracting dominates HVDC capacitor procurement, with lifecycle cost guarantees from TenneT and National Grid ESO shifting technical risk onto component suppliers. Price differentiation separates IEC 61071-certified premium tiers from emerging GB/T-aligned grades for Chinese corridors. Cost compression in standard film constructions is intensifying because polypropylene resin feedstock concentrates in Middle Eastern petrochemical complexes. Renewable developers exhibit highest price sensitivity, while transmission system operators prioritize reliability over unit economics.
Supply Chain Analysis
Cleanroom-grade winding equipment from German and Japanese machine-tool suppliers constitutes the critical chokepoint, with 18-month order backlogs constraining capacity expansion regardless of resin availability. Polypropylene resin extrusion concentrates in China, Germany, and Japan, while metallized film processing clusters in Xi'an, Shenyang, and Nagoya. Single-source vulnerability runs through specialized winding machinery captivity. Distribution runs through direct manufacturer-utility contracting that displaces traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as certification protocol divergence between IEC 61071 and GB/T standards creates parallel qualification niches for regionally specialized suppliers.
For Market Incumbents: Secure backward integration into polypropylene film extrusion capabilities to reduce feedstock cost exposure from Middle Eastern resin concentration. Expand accelerated aging test infrastructure in parallel Chinese and European configurations to capture dual-market access before GB/T-IEC divergence widens further. For New Entrants and Emerging Players: Lead with modular multilevel converter sub-module specialization targeting Japanese METI-backed offshore wind interconnections, where reduced harmonic filtering requirements favor compact capacitor architectures. Pursue direct sales frameworks with Atlantic coast developers facing FERC Order 2023 compliance deadlines. For Investors and Strategic Acquirers: Capital is best deployed toward dielectric materials specialists with captive film extrusion and existing IEC 61071 certification, positioned to absorb 18-24 month recalibration costs for Chinese market entry. Watch GB-T standard harmonization negotiations as the inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply reduces margin exposure to Middle Eastern resin volatility. |
| Dual Certification Infrastructure Investment | Parallel IEC 61071 and GB/T test bays unlock simultaneous European and Chinese market access. |
| Direct Utility Framework Agreements | Long-term contracts with TenneT and State Grid secure volume commitments outside distributor channels. |
| Modular Multilevel Converter Partnership | Silicon carbide integration with film capacitor sub-modules addresses Japanese offshore wind specifications. |
| Accelerated Aging Test Protocol Alignment | Harmonized GB/T-IEC testing reduces duplicate capital expenditure for multi-market suppliers. |
Study Parameters
A spread of perspectives from converter station design engineers, transmission system operator procurement officers, polypropylene film extrusion plant managers, and power electronics R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from IEC certification databases, FERC interconnection filings, SAMR GB/T standard releases, and customs trade data for metallized film imports. Bottom-up capacitor unit demand modeling triangulated against top-down HVDC project pipeline aggregation.
Segmentation dimensions modeled span product type, converter technology architecture, end-user category, and application geography across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycle analysis, and technology displacement curves for line-commutated versus voltage source converter adoption. Forecast inputs incorporated offshore wind capacity auction schedules and ultra-high-voltage DC corridor commissioning timelines from State Grid and Southern Power Grid procurement disclosures.
Underlying assumptions cover polypropylene resin supply stability, winding equipment delivery schedules, and certification protocol divergence persistence, with deviation risk concentrated in hydrocarbon price volatility and Chinese standard evolution. Practitioners should keep alternative scenarios live as GB/T-IEC harmonization negotiations and Atlantic coast offshore wind permitting velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
India Power Market
Power
Iran Power Market
Power
Power Shelf Market
Power
Malaysia Power EPC Market
Power
Temporary Load Bank Rental Market
Power
Electric Power Sports Market
Power
Global Power Line Communication (PLC) Systems Market
Power
LNG Power Barge Market
Power
Power Sled Market
Power
Europe Frequency Converter Market
Power
Water Turbine Market
Power
Portugal Power Market
Power
Global Advanced Marine Power Supply Market
Power
Russian Federation Power Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Japan Power Market