
 Europe Power Purchase Agreement Market | 2026-2036
Europe Power Purchase Agreement Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Purchase Agreement Market Analytics
Buyer concentration among European corporations is expanding as manufacturing, technology, and retail conglomerates aggregate renewable electricity demand into multi-gigawatt procurement programs. Iberdrola leverages its Iberian renewable pipeline to anchor corporate offtake agreements across Spain and Portugal. Statkraft competes through Nordic hydropower balancing services integrated with long-term PPA structures. Lightsource bp specializes in utility-scale solar origination with direct corporate buyer relationships.
A power purchase agreement constitutes a long-term contractual arrangement between an electricity generator and a buyer, specifying delivery terms, pricing mechanisms, and renewable energy certificate transfers for periods typically spanning ten to twenty-five years. Physical PPAs dominate European contract origination volume, while virtual PPAs gain traction among corporations seeking price hedging without direct energy delivery. Corporate buyer types command premium pricing flexibility due to creditworthiness and sustainability disclosure requirements under CSRD and EU Taxonomy regulations.
The EU Green Deal and REPowerEU framework shape PPA demand by mandating renewable targets and streamlining permitting for solar and wind projects. EMA and national energy regulators in Germany, Spain, and France enforce contract standardization and grid integration protocols. Stakeholders must monitor evolving electricity market design reforms and cross-border capacity allocation mechanisms to optimize PPA structuring and risk allocation across European jurisdictions.
Market Dynamics
Corporate renewable procurement mandates under the EU Green Deal are compressing PPA contract timelines and forcing standardization across previously fragmented national frameworks. This structural pressure is redrawing competitive positioning between utilities, independent generators, and energy traders.
Growth Catalysts
- REPowerEU Framework:Streamlined permitting for solar and offshore wind accelerates project development cycles across Spain, Germany, and the Netherlands.
- Corporate Sustainability Reporting Directive:Listed companies must disclose renewable electricity sourcing, creating binding demand for documented PPA contracts with certificate transfers.
- Offshore Wind Pipeline:North Sea and Baltic Sea lease auctions in Denmark, Germany, and Poland are delivering gigawatt-scale projects requiring long-term offtake structures.
Market Restraints
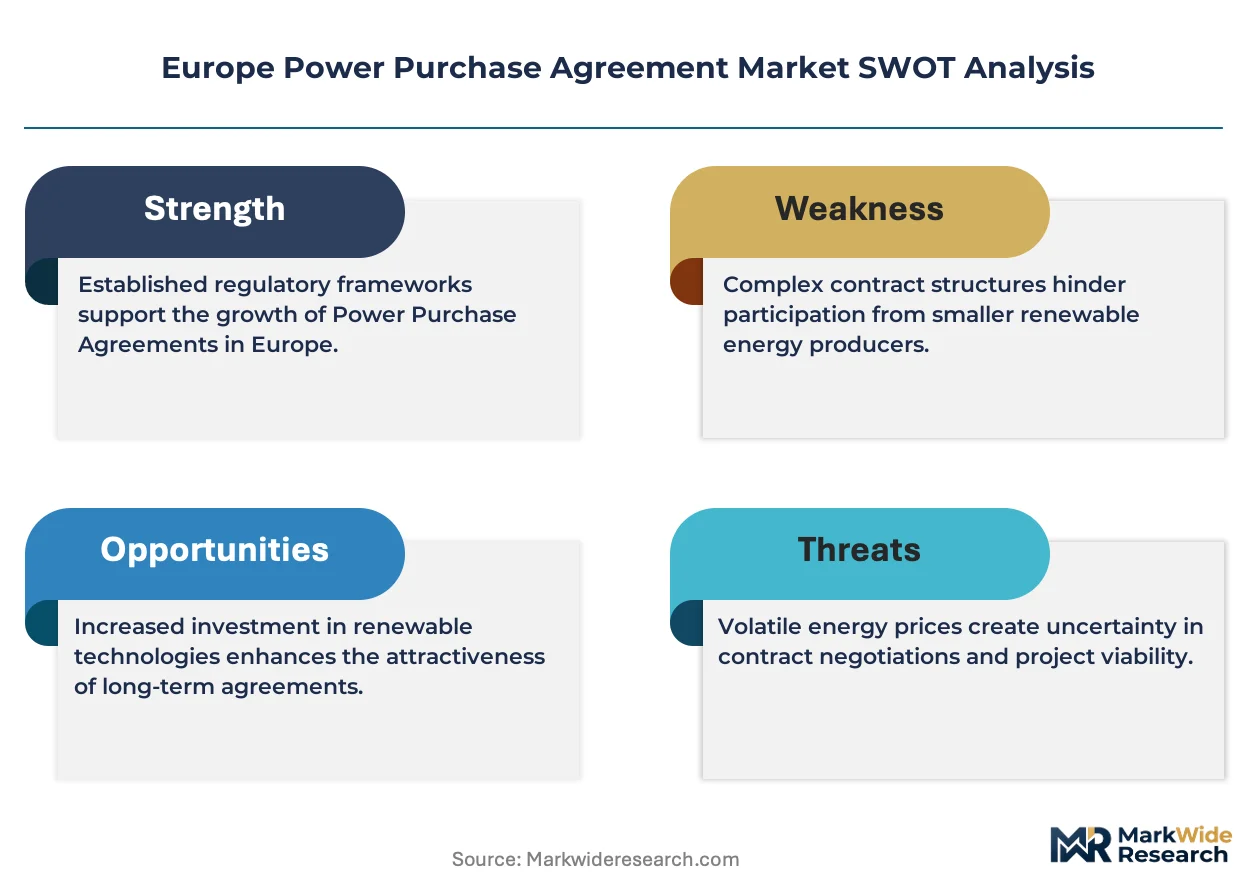
- Grid Connection Queues:Transmission system operators in Germany and Spain face multi-year backlogs for renewable project interconnection approvals.
- Baseload Mismatch:Solar PV generation profiles in southern Europe require costly battery storage or backup contracting to match corporate buyer 24/7 demand patterns.
- Credit Risk Concentration:Utility-scale projects depend on a narrow pool of investment-grade corporate buyers, limiting origination volume for mid-market developers.
Strategic Opportunities
- Central and Eastern Europe:Poland, Romania, and Hungary show underpenetrated corporate PPA adoption with improving renewable auction frameworks.
- 24/7 Carbon-Free Matching:Granular hourly certificate tracking technology enables premium pricing for exact temporal generation-consumption alignment.
- Green Hydrogen Integration:Electrolyzer projects in Iberia and Scandinavia are creating new baseload demand for dedicated renewable supply contracts.
Industry Challenges
- Structured Finance Expertise:Project developers face acute shortages of professionals capable of blending corporate offtake risk with construction debt and tax equity structures.
- Cross-Border Regulatory Arbitrage:Divergent national implementations of EU electricity market rules create compliance complexity for multi-jurisdiction PPA portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Purchase Agreement Market |
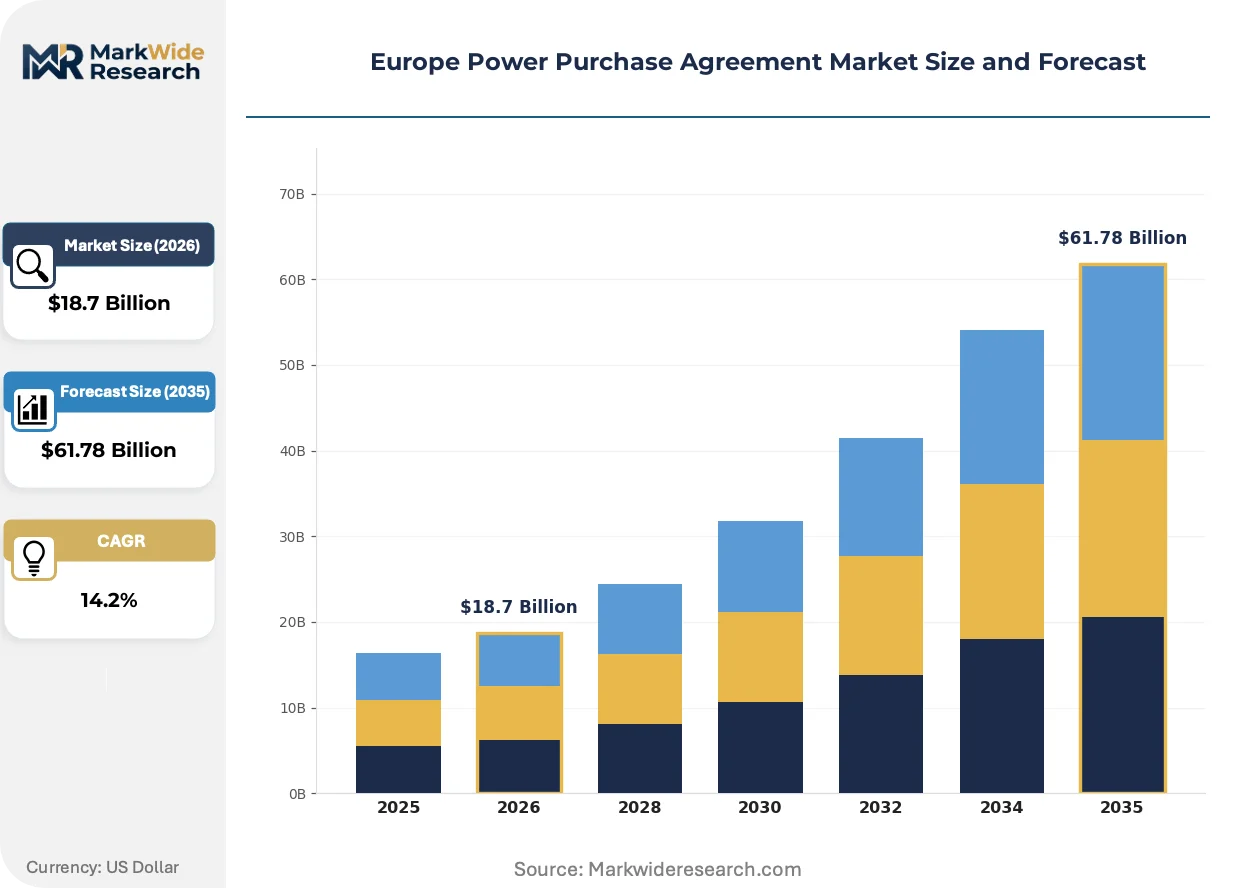
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Contract Type: Physical, Virtual, Corporate, Utility Duration: Short-term, Medium-term, Long-term, Indefinite Buyer Type: Corporations, Government, NGOs, Resellers Energy Source: Solar, Wind, Hydro, Biomass |
| Companies Covered | Lightsource bp, EDP, Iberdrola, R.Power, Renewable Power Capital, Statkraft, Pexapark, Capital Dynamics, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Purchase Agreement Market Evolving Landscape
Digital contracting infrastructure and granular carbon accounting are compressing transaction costs and enabling new PPA structures previously uneconomical at smaller scale. These innovations are expanding addressable demand beyond traditional large corporate buyers.
Blockchain-enabled certificate tracking is converging with smart contract settlement mechanisms to automate renewable energy attribute verification. Mid-sized manufacturing and logistics firms in Germany and the Netherlands are piloting these platforms for sub-10 megawatt contracts. This convergence is compressing due diligence timelines from months to weeks and reducing legal overhead for standardized PPA templates.
The EU Green Deal's delegated acts on renewable hydrogen and sustainable finance are mandating stricter additionality tests for PPA-linked claims. Industrial offtakers in steel, chemicals, and cement must now demonstrate that contracted renewables are new-build rather than existing assets. This regulatory tightening is redirecting developer pipelines toward greenfield sites and away from repowering projects.
Aggregated buyer consortia are displacing bilateral negotiations as the dominant procurement channel for European corporations. Energy-intensive clusters in Belgium's Port of Antwerp and Rotterdam's industrial complex are pooling demand through specialized intermediaries. This pooling is most visible in the Netherlands, where port authorities facilitate multi-buyer offtake from single offshore wind developments.
Europe Power Purchase Agreement Market Segmentation
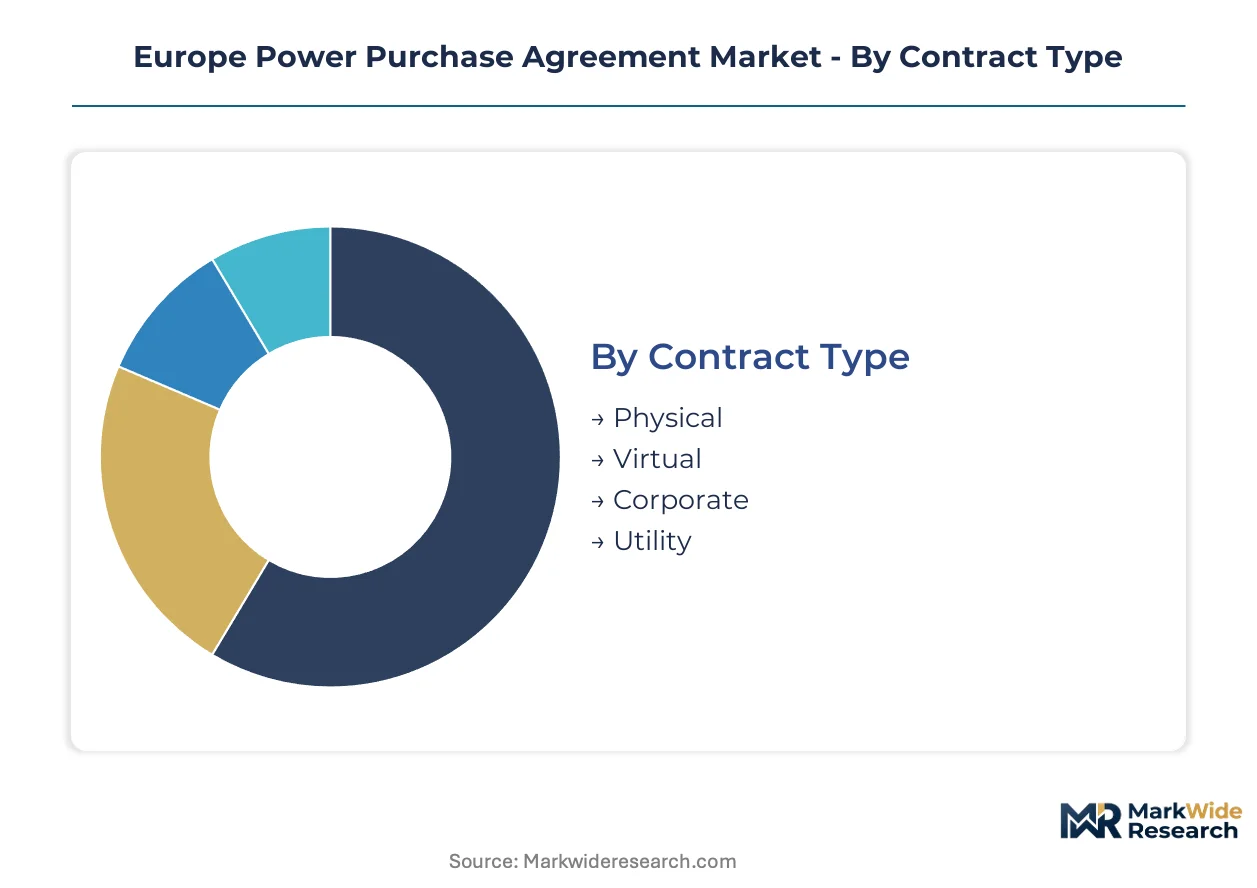
PPA segmentation reveals how contract structure, buyer identity, and generation technology interact to determine pricing, risk allocation, and regulatory treatment across European electricity markets. Distinct segment combinations command divergent credit terms, certificate transfer mechanisms, and offtake tenors.
Contract Type:
Physical PPAs dominate origination volume through direct energy delivery obligations, while virtual structures attract price-hedging buyers without grid interconnection requirements.
- Physical:Direct electricity delivery from generator to buyer via grid connection defines this structure. German industrial manufacturers and Dutch data center operators concentrate demand here due to 24/7 baseload requirements and CSRD-mandated renewable disclosure. Physical delivery enables granular hourly matching claims under EU Green Deal delegated acts.
- Virtual:Financial contracts settle price differentials against wholesale market indices without physical energy transfer. Spanish and French corporate buyers favor these instruments for portfolio hedging across multiple jurisdictions without locational constraints. Virtual structures reduce counterparty credit exposure through standardized ISDA documentation.
- Corporate:Direct bilateral agreements between renewable generators and single corporate offtakers. These contracts typically span 10-15 years with fixed or escalating pricing schedules.
- Utility:Traditional utility-led procurement structures where incumbent suppliers aggregate distributed generation for regulated retail portfolios. These arrangements persist in markets with dominant integrated utilities.
Physical contracts lead volumes today; virtual structures are gaining share fastest among technology and financial services firms.
Duration:
Tenor selection reflects the trade-off between price certainty and operational flexibility, with regulatory pressures compressing feasible contract windows for certain buyer categories.
- Long-term:Contracts exceeding 10 years lock in renewable electricity pricing for capital-intensive project financing. Offshore wind developments in the North Sea and Baltic Sea require these tenors to secure construction debt from European development banks. REPowerEU permitting reforms have shortened development timelines, making 15-20 year structures more attractive to corporate buyers previously deterred by duration risk.
- Medium-term:Three to ten year agreements balance price hedging with operational adaptability. Polish and Romanian industrial buyers favor this range as renewable auction frameworks mature and grid connection queues create delivery uncertainty. Medium-term structures accommodate corporate M&A activity and facility relocation without punitive breakage costs.
- Short-term:Agreements under three years serving tactical procurement needs or bridging construction periods. These contracts carry premium pricing due to limited bankability for project developers.
- Indefinite:Open-ended arrangements with termination clauses tied to regulatory changes or force majeure events. Rare in corporate origination, these appear in utility restructuring contexts.
Long-term contracts anchor project finance today; medium-term structures are expanding most quickly in Central and Eastern European markets.
Buyer Type:
Creditworthiness and sustainability disclosure obligations create tiered pricing across buyer categories, with investment-grade corporates commanding standard contract templates.
- Corporations:Listed companies subject to CSRD reporting requirements drive premium origination volume. Manufacturing conglomerates in Germany's Ruhr region and technology firms in Ireland's data center cluster aggregate multi-gigawatt demand through specialized procurement teams. Corporate buyers negotiate granular hourly certificate tracking and additionality guarantees under EU Taxonomy technical screening criteria.
- Government:Public sector procurement through ministries, municipalities, and state-owned enterprises. These buyers leverage sovereign credit ratings for favorable pricing but face bureaucratic contracting timelines.
- NGOs:Non-governmental organizations with mission-driven renewable sourcing mandates. Environmental advocacy groups and research institutions purchase smaller volumes with strict additionality requirements.
- Resellers:Energy traders and aggregators intermediating between generators and fragmented demand. These entities absorb credit risk and provide standardized contracting for mid-market buyers lacking direct origination capabilities.
Corporate buyers command the deepest liquidity today; reseller-intermediated channels are climbing the fastest as mid-market manufacturing demand formalizes.
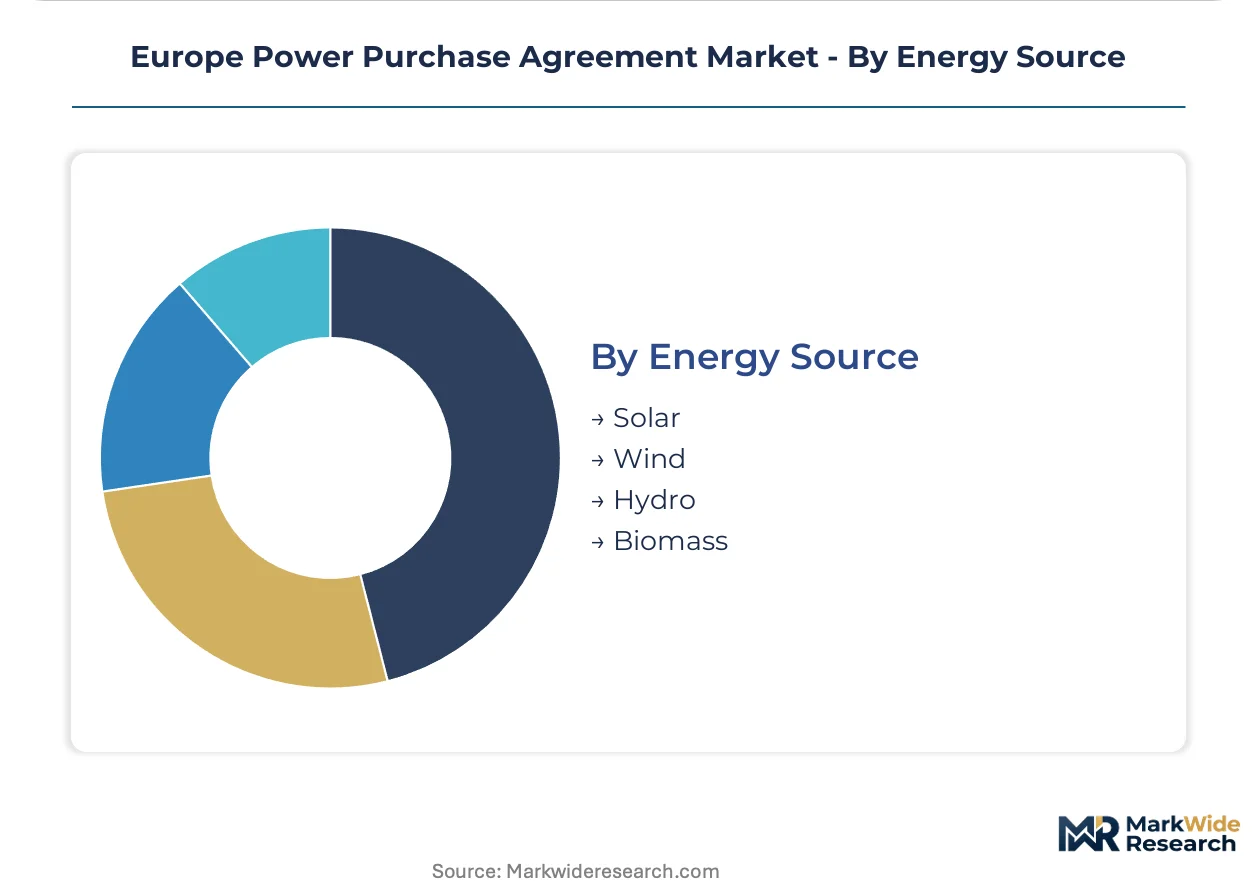
Energy Source:
Generation technology determines capacity factor profiles, geographic concentration, and grid integration costs that flow through to contract pricing and structuring complexity.
- Solar:Utility-scale photovoltaic installations dominate southern European origination in Spain, Portugal, and Italy where irradiance profiles exceed northern benchmarks. Solar PPAs require battery storage co-location or backup contracting to address diurnal generation mismatch against corporate baseload demand. Iberian projects benefit from streamlined permitting under REPowerEU implementation.
- Wind:Onshore and offshore wind assets deliver higher capacity factors with complementary generation profiles to solar. North Sea lease auctions in Denmark, Germany, and the Netherlands are delivering gigawatt-scale projects requiring 20-25 year offtake structures. Offshore wind commands construction cost premiums offset by superior capacity factors and proximity to industrial demand clusters.
- Hydro:Run-of-river and reservoir-based generation provides dispatchable renewable output with multi-decade asset lifespans. Nordic hydropower balancing services from Statkraft and others integrate with long-term PPA structures for corporate buyers seeking 24/7 carbon-free claims.
- Biomass:Combustion and anaerobic digestion facilities utilizing agricultural residues and waste streams. These sources face sustainability certification scrutiny under EU Taxonomy criteria and compete for feedstock with circular economy mandates.
Solar anchors origination volume today; offshore wind is expanding most quickly through North Sea and Baltic Sea lease auctions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial procurement volume exceeds Spain's solar origination capacity, yet both markets face similar grid interconnection bottlenecks that compress development timelines. The EU Green Deal implementation varies across member states, creating divergent PPA contract standardization and corporate buyer incentive structures.
Germany
Industrial manufacturers in the Ruhr region and data center operators in Frankfurt aggregate multi-gigawatt demand through specialized procurement teams. The Bundesnetzagentur enforces grid connection queue transparency rules under the EnWG energy industry act. Bavaria's automotive supplier clusters are finalizing 24/7 carbon-free matching contracts with hourly certificate tracking.
Spain
Utility-scale solar developers in Extremadura and Andalusia leverage superior irradiance profiles to undercut northern European pricing benchmarks. The CNMC national markets regulator streamlined permitting timelines through REPowerEU implementation decrees. Madrid-based corporate headquarters are consolidating Iberian renewable sourcing into centralized procurement programs.
Netherlands
Port of Rotterdam industrial clusters pool demand through specialized intermediaries for offshore wind offtake from North Sea lease auctions. The ACM authority monitors cross-border capacity allocation mechanisms under EU electricity market design reforms. Eindhoven's high-tech manufacturing sector is piloting blockchain-enabled certificate tracking for sub-10 megawatt contracts.
Poland
Industrial buyers in Silesia and Lower Silesia favor medium-term tenors as renewable auction frameworks mature and grid queues create delivery uncertainty. The URE energy regulator implements contract-for-difference schemes that complement corporate PPA structures. Warsaw-based energy traders are developing standardized templates for mid-market manufacturing demand.
France
Nuclear-dependent grid infrastructure creates baseload matching challenges for corporate buyers seeking 100% renewable claims. The CRE commission enforces contract standardization protocols for physical and virtual PPA structures. Lyon and Grenoble industrial clusters are negotiating hybrid solar-hydro contracts to address diurnal generation gaps.
Europe Power Purchase Agreement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract origination, risk intermediation, and balance-sheet financing functions. The vendor base spans integrated utilities with captive generation pipelines, independent developers with direct corporate relationships, and financial sponsors aggregating distributed projects. Three archetypes dominate: utility-affiliated originators leveraging proprietary asset bases, independent developers specializing in single-technology deployment, and energy traders absorbing counterparty credit risk. Geographic expansion through cross-border origination desks and technology diversification into offshore wind represent the dominant competitive moves.
Among utility-affiliated originators, Iberdrola and EDP exemplify the integrated model that anchors corporate offtake through captive renewable pipelines. Statkraft occupies a distinct position within the Nordic hydropower balancing segment, integrating long-term structures with dispatchable generation services. Lightsource bp represents the pure-play solar archetype, specializing in utility-scale origination with direct buyer relationships rather than intermediated channels.
| Leading Market Players |
|---|
| Lightsource bp |
| EDP |
| Iberdrola |
| R.Power |
| Renewable Power Capital |
| Statkraft |
| Pexapark |
| Capital Dynamics |
| TotalEnergies |
| Others |
Value Network & Pricing Analysis
Offshore wind turbine scaling in the North Sea and Baltic Sea simultaneously compresses levelized cost of energy and concentrates supplier leverage among a handful of European OEMs. This dual effect reshapes PPA pricing power as developers pass through equipment cost volatility while competing for scarce installation vessel capacity.
Pricing Analysis
Capacity additions in Iberia and Central Europe are reshaping price floors for utility-scale solar PPAs. Three-tier pricing structure across premium hourly-matching, standard annual certificate, and economy sleeved contracts reflects granularity of carbon accounting. Price differentiation hinges on additionality guarantees under EU Taxonomy and volume scale of corporate offtake. Pricing pressure stems from grid connection queue delays that extend developer carrying costs. Mid-market manufacturing buyers show highest price sensitivity; investment-grade technology firms accept premium structures for 24/7 matching claims.
Supply Chain Analysis
Refurbishment flows for offshore wind foundations and nacelle components create secondary material streams that offset raw material exposure. Component manufacturing concentrates in Denmark, Germany, and Spain. Polysilicon, rare earth magnets, and high-voltage cable insulation draw from concentrated Asian and European sources. Single-source vulnerability for installation vessels and specialized grid connection hardware feeds project delay risk. Distribution runs through EPC contractors with captive relationships to major IPPs and utility affiliates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate procurement mandates under CSRD and REPowerEU implementation are compressing development timelines and enabling premium-tier pricing for verified additionality claims. This margin-expansion dynamic rewards players with pipeline depth and standardization capabilities.
For Market Incumbents: Lock in long-term turbine supply agreements and installation vessel charters to defend against equipment cost volatility. Vertical integration into battery storage co-location addresses baseload mismatch risks from solar generation profiles. Secure grid connection queue priority through early engagement with Bundesnetzagentur and CNMC permitting reforms.
For New Entrants and Emerging Players: Energy traders and aggregators represent the most penetrable channel partner type for mid-market manufacturing demand in Poland and Romania. Target medium-term PPA structures in Central and Eastern Europe where auction frameworks mature but origination expertise remains scarce. Deploy blockchain-enabled certificate tracking platforms to differentiate on transaction cost and due diligence speed.
For Investors and Strategic Acquirers: Roll-up economics work for independent solar developers with direct corporate buyer relationships because CSRD disclosure requirements are fragmenting procurement into specialized intermediaries. Target platforms with 500+ MW pipelines in Spain and Portugal. Monitor REPowerEU permitting reform implementation timelines as inflection indicator for development velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | North Sea lease auctions in Denmark and Germany deliver gigawatt-scale projects requiring 20-25 year offtake structures. |
| Power Purchase Agreement Origination | Direct corporate buyer relationships enable premium pricing for hourly-matching and additionality guarantees under EU Taxonomy. |
| Backward Integration into Battery Storage | Co-located storage addresses diurnal generation mismatch and commands higher contract valuations from 24/7 carbon-free buyers. |
| Green Certification Program | Granular certificate tracking technology enables premium tier pricing for exact temporal generation-consumption alignment claims. |
| Technology Licensing for Digital Contracting | Blockchain-enabled settlement mechanisms compress due diligence timelines from months to weeks for standardized PPA templates. |
Research Methodology
Bottom-up corporate procurement modeling reconciled against top-down renewable project pipeline tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, utility planning officers, and corporate sustainability directors combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Cross-referencing of physical and virtual PPA origination volumes against grid interconnection queue data ensures supply-side calibration.
Historical trendline analysis of contract tenor, pricing structure, and technology mix informs projection assumptions across the modeling period. Segmentation dimensions include contract type, duration tier, buyer credit category, and generation technology. CAGRs derive from regression analysis of origination volume against regulatory implementation timelines and corporate disclosure mandate phase-ins. Forecast inputs incorporate REPowerEU permitting reform velocity and CSRD adoption curves by member state.
Revisions become necessary when grid connection queue backlogs extend beyond modeled timelines or when EU electricity market design reforms alter cross-border capacity allocation mechanisms. Practitioners should monitor Bundesnetzagentur and CNMC interconnection approval rates and EU Green Deal delegated act implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Solar Plants Controllers Market
Power
Existent Gum Steam Generator Market
Power
Portugal Power Market
Power
Robotic Power Source Market
Power
Modular PSA Nitrogen Generator Market
Power
Residential Portable Inverter Generator Market
Power
Global Power Line Communication (PLC) Systems Market
Power
United States Power Market
Power
Global Marine Power Systems Market
Power
Smart Power Market
Power
Single-Phase Microinverter Market
Power
Spain Power Market
Power
Equatorial Guinea Power Market
Power
Wind Alarm Controller Market
Power
Wireless Power Receiver Market
Power
Global Hydraulic Turbine Market