
 Europe Power Market | 2026-2036
Europe Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Market Analysis
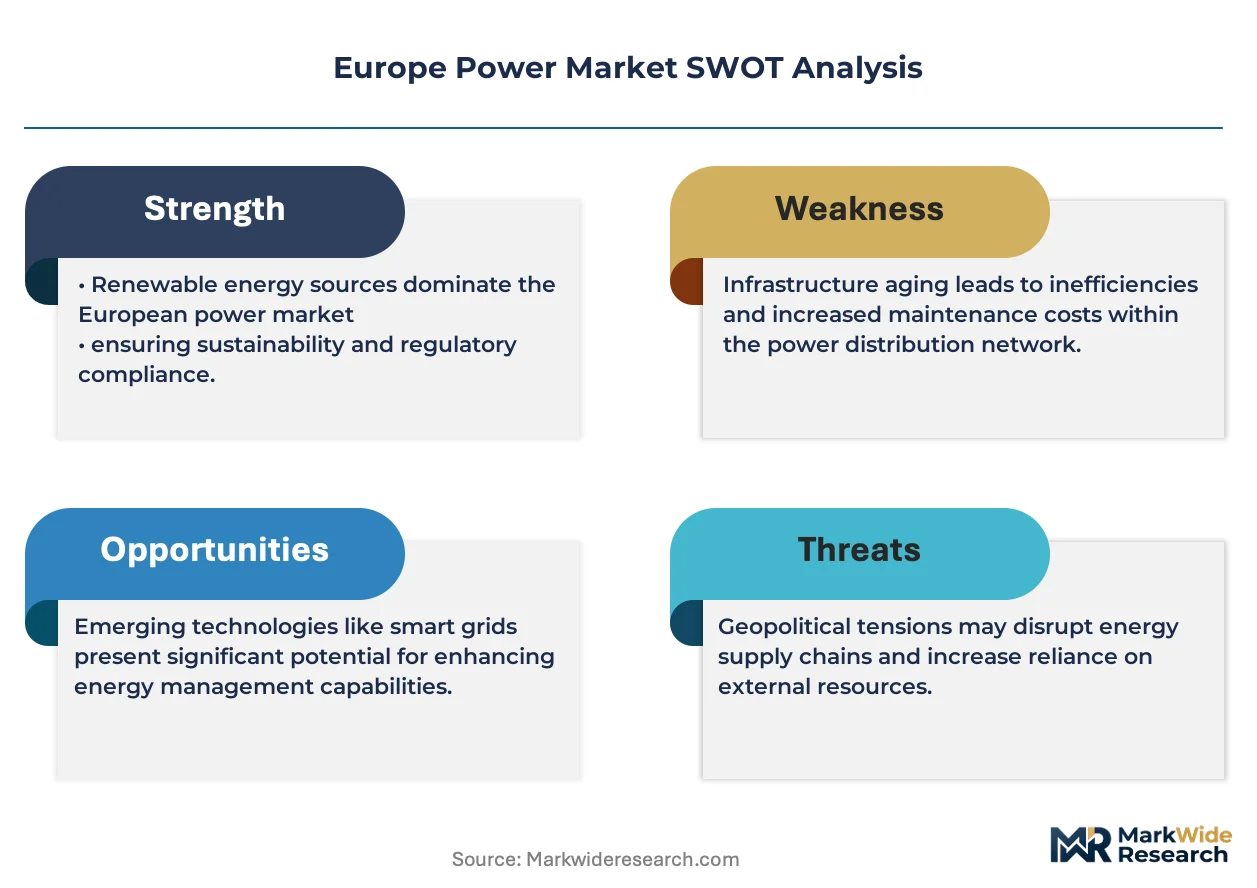
A shortage of certified grid engineers and high-voltage technicians is unwinding project timelines across the continent. EDF leverages its nuclear fleet refurbishment expertise to sustain baseload capacity in France. Enel anchors Southern European renewable expansion through integrated solar and storage development. Iberdrola dominates offshore wind auctions in the North Sea with specialized maritime construction capabilities.
Europe Power encompasses the generation, transmission, and distribution of electrical energy across national and cross-border networks operating at frequencies of 50 Hz and voltages ranging from 230 V residential to 400 kV ultra-high-voltage transmission. The system balances real-time supply and demand through interconnected synchronous grids managed by transmission system operators. Renewable Energy leads capacity additions but Transmission infrastructure captures the structural margin pool as interconnection investments lag generation buildout. Distribution networks face accelerating upgrade cycles as distributed solar PV and electric vehicle loads reverse traditional power flows. Industrial end users command the most sophisticated procurement strategies, combining long-term power purchase agreements with on-site generation.
EU Green Deal targets, REPowerEU emergency measures, and the F-Gas Regulation on fluorinated greenhouse gases collectively reshape fuel mix decisions and equipment standards. EMA and national regulators like France's ANSM do not govern this sector; instead the European Network of Transmission System Operators for Electricity coordinates cross-border grid codes while REACH restricts hazardous substances in cables and transformers. Stakeholders must monitor whether accelerated permitting reforms materially compress project development cycles before capital commitments lock in technology choices.
Market Dynamics
The Europe Power Market is fragmenting as synchronous grid interconnection requirements collide with distributed renewable generation, forcing transmission system operators to reconfigure balancing mechanisms and congestion management protocols.
Growth Catalysts
- REPowerEU Emergency Measures:The EU's accelerated permitting reforms for renewable projects compress development timelines, unlocking stranded solar and wind capacity across Poland and Romania.
- Industrial Electrification:German steel and chemical producers are replacing natural gas with direct electricity for process heat, creating baseload demand that stabilizes merchant renewable revenues.
- Offshore Wind Scale-Up:North Sea maritime zones in Danish and Dutch waters host gigawatt-scale auction rounds that attract specialized floating foundation engineering.
Market Restraints
- Critical Mineral Supply Concentration:Rare earth processing for permanent magnet generators concentrates in Chinese refining facilities, exposing European turbine manufacturers to input bottlenecks.
- Grid Code Harmonization Friction:ENTSO-E's network codes impose divergent compliance costs across member states, delaying cross-border merchant interconnectors.
- Long-Duration Storage Gap:Lithium-ion battery chemistries dominate four-hour markets but fail to cover seasonal renewable lulls, leaving hydrogen storage uneconomical at current electrolyzer capex levels.
Strategic Opportunities
- Green Hydrogen Offtake:Dutch port clusters Rotterdam and Amsterdam anchor electrolyzer buildouts tied to German chemical offtake contracts under EU Hydrogen Bank subsidies.
- Agrivoltaic Dual-Use:Italian and Spanish agricultural regions deploy elevated solar arrays that preserve arable output while generating merchant electricity.
- Building-to-Grid Integration:France's RE2020 thermal regulation mandates smart readiness in new construction, creating distributed flexibility pools for demand response aggregators.
Industry Challenges
- High-Voltage Technician Scarcity:German and Austrian utilities face twelve-month recruitment gaps for live-line certified engineers, extending substation commissioning schedules.
- Legacy SCADA Cybersecurity:Eastern European distribution operators operate serial-protocol systems vulnerable to IEC 62351 compliance mandates, requiring wholesale control room replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Market |
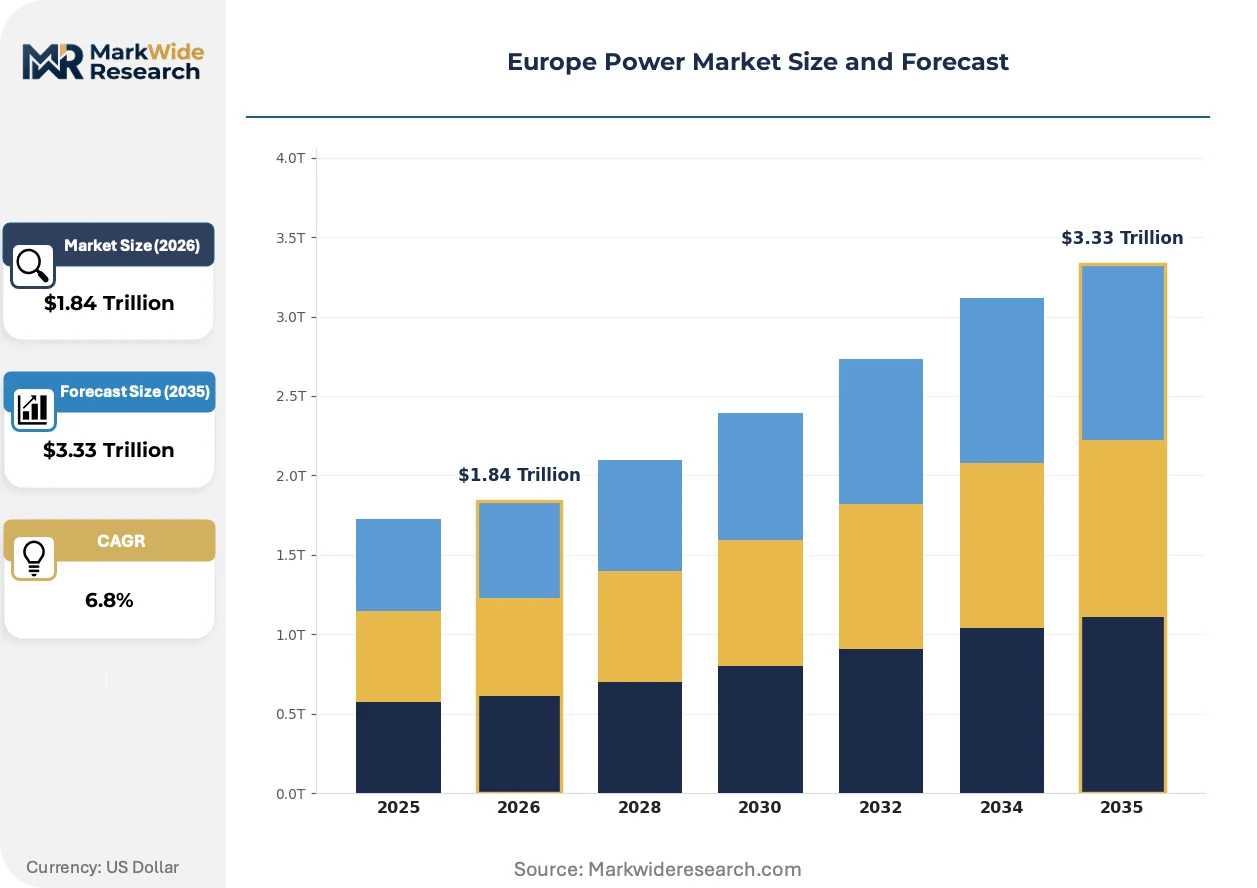
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.33 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Thermal Power, Nuclear Power, Hydropower Service Type: Generation, Transmission, Distribution, Retail Technology: Solar PV, Wind Turbines, Gas Turbines, Biomass End User: Commercial, Residential, Industrial, Utilities |
| Companies Covered | EDF, Enel, E.ON, Iberdrola, Engie, TotalEnergies, National Grid, BP, Shell, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Market Emerging Trajectories
Power system architecture is fragmenting as centralized generation yields to distributed resources, forcing incumbents to rebuild technical and commercial capabilities around bi-directional network operation.
Grid-forming inverters are fragmenting traditional frequency response markets by enabling solar and battery assets to provide synthetic inertia previously reserved for synchronous machines. German transmission operators now mandate this capability for new renewable connections, compressing procurement timelines for conventional frequency containment reserves. The technology is fragmenting ancillary service revenue pools as distributed assets capture payments once monopolized by thermal generators.
The EU F-Gas Regulation is phasing down sulfur hexafluoride in switchgear, forcing manufacturers to accelerate vacuum interrupter and fluoronitrile alternative development. Industrial consequence includes accelerated obsolescence of installed GIS infrastructure and retooling costs for European electrical equipment suppliers. High-voltage substation projects in France and Benelux face extended equipment qualification timelines as utilities validate alternative insulation media.
Corporate power purchase agreements are displacing utility-sourced contracts for industrial offtakers seeking price certainty and renewable attribute claims. Energy-intensive manufacturers in Spain and Portugal now contract directly with solar developers, bypassing incumbent retail suppliers. This behavior concentrates most visibly in Iberian Peninsula markets where merchant solar capture prices have compressed below regulated tariff benchmarks.
Europe Power Market Segmentation
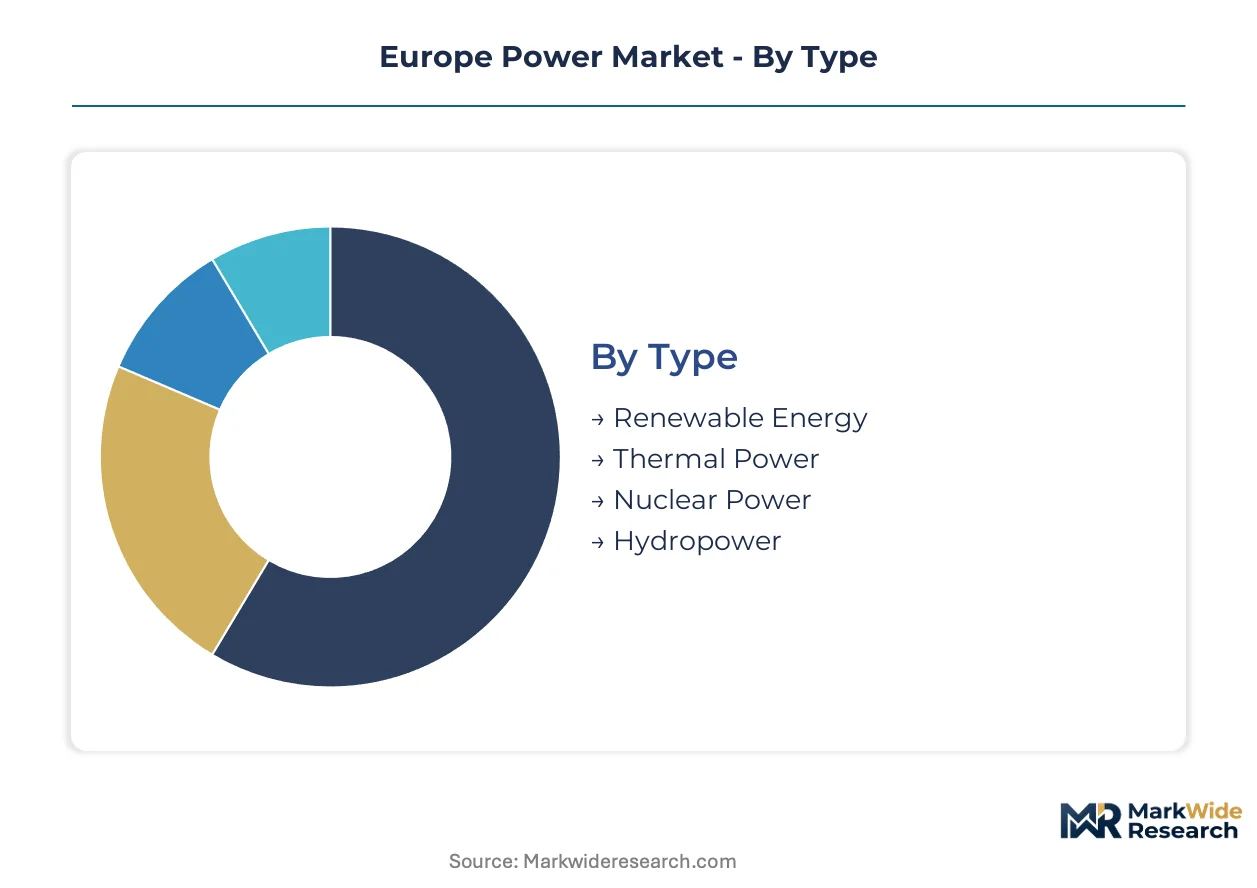
Segmentation in the Europe Power Market reveals how regulatory frameworks, grid infrastructure maturity, and end-use electrification patterns fragment procurement strategies across member states. Each dimension exposes distinct margin pools and capital allocation priorities for equipment suppliers and project developers.
Type:
EU Green Deal carbon pricing and REPowerEU targets create divergent compliance economics across generation technologies, with subsidy eligibility and grid priority access determining project returns.
- Renewable Energy:Solar and wind assets dominate capacity additions under accelerated permitting reforms. German industrial offtakers in steel and chemicals anchor long-term power purchase agreements, stabilizing merchant revenue streams against capture price volatility.
- Thermal Power:Natural gas and coal plants face F-Gas Regulation constraints on sulfur hexafluoride switchgear while providing flexibility services. Polish and Romanian utilities retain these assets for winter peak shaving as interconnector flows prove insufficient.
- Nuclear Power:France's ANSM oversees fleet refurbishment extending reactor lifespans beyond original design limits. Baseload capacity sustains grid stability as variable renewable penetration rises.
- Hydropower:Alpine reservoirs in Austria and Switzerland deliver seasonal storage and frequency containment reserves. Pumped storage projects face extended environmental permitting timelines under Water Framework Directive assessments.
Established volume favors Thermal Power; emerging adoption favors Renewable Energy.
Service Type:
Margin concentration shifts downstream as generation asset commoditization forces incumbents toward grid management and customer interface capabilities.
- Generation:Asset ownership fragments between utility incumbents, independent power producers, and corporate offtakers under direct PPA structures. Iberian solar developers now bypass traditional suppliers entirely.
- Transmission:ENTSO-E network codes mandate harmonized technical standards across synchronous zones. Interconnector investments lag generation buildout, capturing structural congestion rents on cross-border capacity.
- Distribution:Bi-directional power flows from distributed solar PV and electric vehicle loads force upgrade cycles. French Enedis and German municipal utilities face reversed flow protection coordination challenges.
- Retail:Price comparison platforms and corporate procurement teams displace incumbent supplier relationships. Energy-intensive manufacturers now combine on-site generation with wholesale market exposure.
Capital deployment concentrates in Transmission; customer interface innovation clusters in Retail.
Technology:
Equipment selection hinges on local manufacturing capabilities, rare earth supply security, and grid code compliance costs that vary by connection voltage level.
- Solar PV:Agrivoltaic dual-use installations expand across Italian and Spanish agricultural regions. Elevated array designs preserve arable output while generating merchant electricity under simplified land-use permits.
- Wind Turbines:Offshore foundations in Danish and Dutch waters require specialized maritime construction capabilities. Rare earth magnet supply concentration in Chinese refining facilities exposes European manufacturers to input bottlenecks.
- Gas Turbines:Flexible combined-cycle units provide ramping services for renewable integration. Hydrogen-ready turbine orders from German utilities anticipate future fuel switching under EU Hydrogen Bank subsidies.
- Biomass:Combined heat and power plants anchor district heating networks in Nordic and Baltic markets. Sustainability certification requirements under RED III constrain feedstock sourcing.
Deployment velocity favors Solar PV; technology maturity favors Gas Turbines.
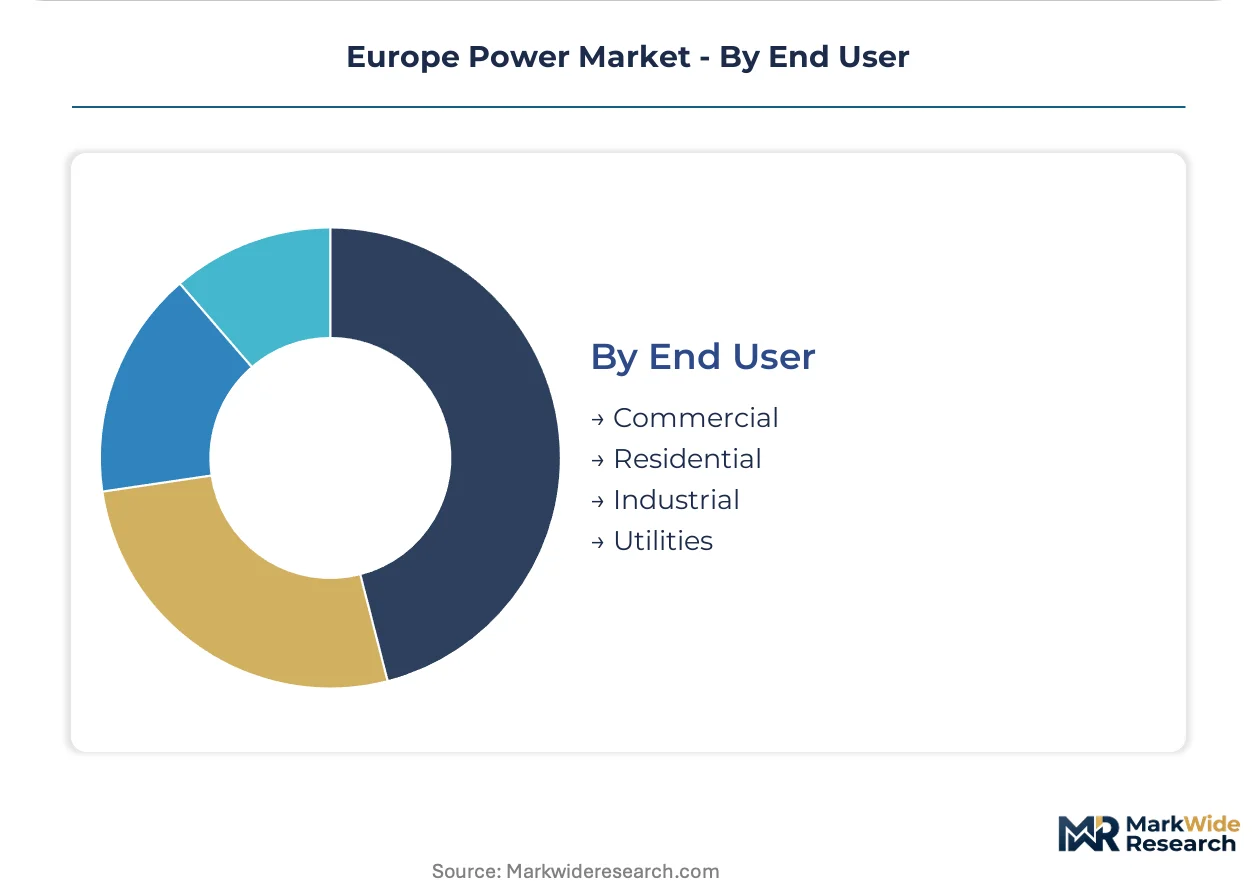
End User:
Procurement sophistication stratifies by load flexibility, credit quality, and regulatory exposure to carbon border adjustment mechanisms.
- Industrial:German steel and chemical producers replace natural gas with direct electricity for process heat. Electrification creates baseload demand stabilizing renewable merchant revenues against price cannibalization.
- Commercial:Data center operators across Frankfurt, Paris, and Amsterdam expand electricity procurement as digital infrastructure scales. Sustainability commitments drive renewable attribute tracking requirements.
- Residential:Rooftop solar and heat pump adoption accelerates under national renovation schemes. France's RE2020 thermal regulation mandates smart readiness in new construction.
- Utilities:Incumbent suppliers face customer attrition to corporate PPAs and independent aggregators. Grid balancing responsibilities concentrate with transmission system operators as distributed resources proliferate.
Contract sophistication peaks in Industrial; volume growth concentrates in Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ENTSO-E coordinates grid codes across the continent, yet national regulatory frameworks and industrial structures create distinct investment climates. Germany's nuclear phase-out and industrial electrification anchor regional demand patterns.
Germany
Steel and chemical producers in the Ruhr and Rhineland replace natural gas with direct electricity for process heat. The amended Renewable Energy Sources Act accelerates onshore wind permitting. Bavarian automotive clusters source renewable power through corporate PPAs to meet Scope 3 targets.
France
ANSM oversees EDF's nuclear fleet refurbishment extending reactor lifespans beyond original design limits. The RE2020 thermal regulation mandates smart readiness in new construction. The Dunkirk industrial corridor anchors electrolyzer buildouts tied to hydrogen offtake contracts.
Netherlands
Data center operators in Amsterdam and Rotterdam expand electricity procurement as digital infrastructure scales. The EU Hydrogen Bank subsidizes electrolyzer deployment at port clusters. North Sea maritime zones host gigawatt-scale offshore wind auctions requiring specialized floating foundations.
Spain
Iberian solar capture prices have compressed below regulated tariff benchmarks, driving corporate PPA adoption. Agrivoltaic dual-use installations expand across Castile-La Mancha and Andalusia. Elevated array designs preserve arable output while generating merchant electricity.
Poland
REPowerEU accelerated permitting reforms unlock stranded solar and wind capacity across former coal regions. Utilities retain natural gas and coal assets for winter peak shaving as interconnector flows prove insufficient. Silesian industrial clusters face carbon border adjustment exposure driving electrification investments.
Europe Power Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. State-backed incumbents with nuclear refurbishment capabilities occupy the baseload stability tier, while renewable specialists capture merchant generation margins. Integrated utilities with transmission ownership extract congestion rents, and pure-play developers compete on project execution speed. Capacity expansion and strategic partnerships dominate competitive moves as firms secure electrolyzer offtake and floating wind construction capabilities.
Within the state-backed nuclear tier, EDF exemplifies fleet refurbishment expertise sustaining baseload capacity. Among Southern European renewable specialists, Enel anchors integrated solar and storage development. At the offshore wind scale-driven end, Iberdrola occupies a position in North Sea maritime construction.
| Leading Market Players |
|---|
| EDF |
| Enel |
| E.ON |
| Iberdrola |
| Engie |
| TotalEnergies |
| National Grid |
| BP |
| Shell |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon pricing gates both equipment qualification and contract price differentiation simultaneously. REACH compliance and F-Gas Regulation certification tiers separate premium switchgear suppliers from commodity transformer vendors, while long-term power purchase agreements command spreads over merchant spot exposure.
Pricing Analysis
Iberian solar capture prices diverge sharply from German industrial tariffs, compressing developer margins in southern markets while stabilizing northern offtake premiums. Contract-based long-term offtake structures dominate procurement for data center operators and chemical producers seeking price certainty. Price differentiation rests on grid connection priority and renewable attribute certification, with unbundled guarantees of origin trading at premiums. Cost compression in merchant renewable tiers is intensifying because capture price cannibalization accelerates with capacity additions. Industrial offtakers show least price sensitivity due to carbon border adjustment exposure, while municipal utilities face acute budget constraints.
Supply Chain Analysis
Rare earth magnet processing in Chinese refining facilities creates a chokepoint for European turbine manufacturers sourcing permanent magnet generators. Component supply draws from Germany for high-voltage switchgear, China for solar PV modules, and South Korea for battery storage systems. Raw material dependencies span neodymium-dysprosium alloys, polysilicon ingots, and lithium carbonate. Single-source vulnerability concentrates in offshore wind foundation steel and HVDC converter stations. Distribution runs through EPC contractors with maritime construction capabilities for North Sea projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Power Market recovery cycles track industrial electrification capex waves, with German steel and chemical replacement demand now inflecting upward after gas price volatility peaks.
For Market Incumbents: Shield baseload revenue pools by accelerating nuclear fleet refurbishment timelines ahead of renewable intermittency costs. Secure transformer manufacturing capacity in Poland and Romania before accelerated permitting reforms unlock stranded project demand. Vertical integration into electrolyzer offtake contracts mitigates hydrogen storage margin erosion. For New Entrants and Emerging Players: CE marking fast-track for grid-forming inverters opens procurement pathways into German transmission operator tender programs. White-space concentrates in agrivoltaic project development across Castile-La Mancha, where simplified land-use permits reduce development timelines. Target corporate PPA advisory services for mid-sized Spanish manufacturers bypassing incumbent retail suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across distributed solar and storage integration as module costs compress and installation labor standardizes. Long-term viability favors developers with captive land positions and permitting expertise over pure-play hardware suppliers. Acquisition targets should display integrated development-construction capabilities with visible project pipelines. Monitor ENTSO-E network code harmonization progress as inflection signal for cross-border merchant interconnector viability.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | EDF and Enel anchor long-term offtake structures that stabilize renewable merchant revenues against capture price volatility. |
| Capacity Buildout | Iberdrola's North Sea floating foundation investments capture gigawatt-scale auction rounds in Danish and Dutch maritime zones. |
| Vertical Integration into Storage | Enel's integrated solar and battery development anchors Southern European renewable expansion with co-located flexibility. |
| Green Certification Program | France's RE2020 thermal regulation mandates smart readiness in new construction, creating distributed flexibility pools. |
| Technology Licensing | Grid-forming inverter capabilities licensed to German transmission operators compress procurement timelines for frequency containment reserves. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, independent power project developers, EPC contractors, and grid operators. Secondary validation drew from ENTSO-E network code filings, IEA electricity market reports, FERC interconnection queue data, and EU Hydrogen Bank subsidy disclosures. Bottom-up project pipeline assessments triangulated against top-down capacity deployment forecasts.
Across the analysis window, the forecasting framework modeled generation technology mix, service type margin pools, project scale tiers, and regulatory framework clusters. CAGRs were derived from capacity addition trajectories, electrification intensity curves, and grid investment cycles. Key inputs included industrial power demand elasticities, offshore wind auction clearing prices, and electrolyzer capex learning rates.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and REPowerEU permitting reform implementation; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ENTSO-E network code harmonization progress and critical mineral supply diversification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Temporary Load Bank Rental Market
Power
Asia-Pacific Microturbine Market
Power
Wireless Power Receiver Market
Power
Resonant Power Converters Market
Power
United States Power Market
Power
Global Diesel Power Engine Market
Power
HVDC Capacitor Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Brazil Power Market
Power
Germany Solar Inverter Market
Power
Single-Phase Microinverter Market
Power
Marine Thermal Fluid Heaters Market
Power
Residential Portable Inverter Generator Market
Power
Global Advanced Marine Power Supply Market
Power
Kuwait Power Market
Power
Power Capacitors Market