
 Portugal Power Market | 2026-2036
Portugal Power Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Power Market Analytics
Grid-connected renewable certification is rotating Portugal's power mix toward higher-specification dispatchable clean assets. EDP sustains Europe's largest wind-plus-hydro hybrid portfolio from its Lisbon headquarters. Finerge SA dominates onshore wind development across northern and central districts. Iberdrola SA anchors transmission-linked solar deployment through long-term offtake contracts with industrial offtakers.
Portugal power encompasses electricity generation, transmission, distribution, and retail across voltage classes from 400 kV backbone networks to 230 V consumer service, with renewable integration requiring frequency response capabilities within 0.5 Hz deviation limits. The generation segment pools margin in offshore wind concessions awarded by Portugal's environmental regulator. Transmission investment concentrates on HVDC corridor upgrades linking Alentejo solar zones to northern demand centers. Distribution service operators face capital intensity from smart meter rollout mandates under EU directives.
Portugal's Direção-Geral de Energia e Geologia enforces licensing timelines under the EU Green Deal framework, while CE marking and EU AI Act provisions govern grid automation procurement. The EU F-Gas Regulation phases down sulfur hexafluoride use in switchgear, reshaping equipment sourcing for REN - Redes Energéticas Nacionais. Stakeholders must track interconnection queue positions and capacity market auction design as Lisbon implements REPowerEU-aligned storage procurement mandates.
Market Dynamics
Portugal's power sector is restructuring around REPowerEU-aligned storage procurement mandates that force asset owners to co-locate grid-scale batteries with renewable generation, compressing merchant revenue windows and reconfiguring interconnection queue economics.
Growth Catalysts
- EU F-Gas Regulation phase-down:Sulfur hexafluoride restrictions in high-voltage switchgear are accelerating adoption of vacuum interrupter technology across REN's transmission network.
- Industrial offtake expansion:Energy-intensive manufacturers in the Porto metropolitan corridor are signing long-term power purchase agreements for dispatchable clean assets.
- Offshore wind licensing rounds:Portugal's environmental regulator is auctioning seabed concessions that concentrate development capital around Lisbon.
Market Restraints
- HVDC equipment supply concentration:Converter station manufacturing capacity clusters in Germany and China, creating procurement bottlenecks for Alentejo-to-north transmission upgrades.
- Grid code compliance costs:Frequency response requirements within 0.5 Hz deviation limits impose capital burdens on distributed solar developers.
- Interconnection queue saturation:Renewable project backlogs at transmission nodes delay commercial operation dates for hybrid wind-plus-storage assets.
Strategic Opportunities
- Smart meter data monetization:Distribution service operators can leverage EU directive-mandated rollout infrastructure to offer grid flexibility services to aggregators.
- Green hydrogen offtake corridors:Industrial buyers in Sines are contracting electrolyzer-linked renewable supply for ammonia and steel feedstock substitution.
- Cross-border capacity trading:Iberian market coupling with France and Spain enables arbitrage across day-ahead and intraday power exchanges.
Industry Challenges
- Grid automation cybersecurity certification:EU AI Act provisions for critical infrastructure are extending procurement timelines for SCADA and EMS platforms.
- Specialized technician scarcity:Offshore wind turbine maintenance and HVDC converter operation require skills concentrated in northern European labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Power Market |
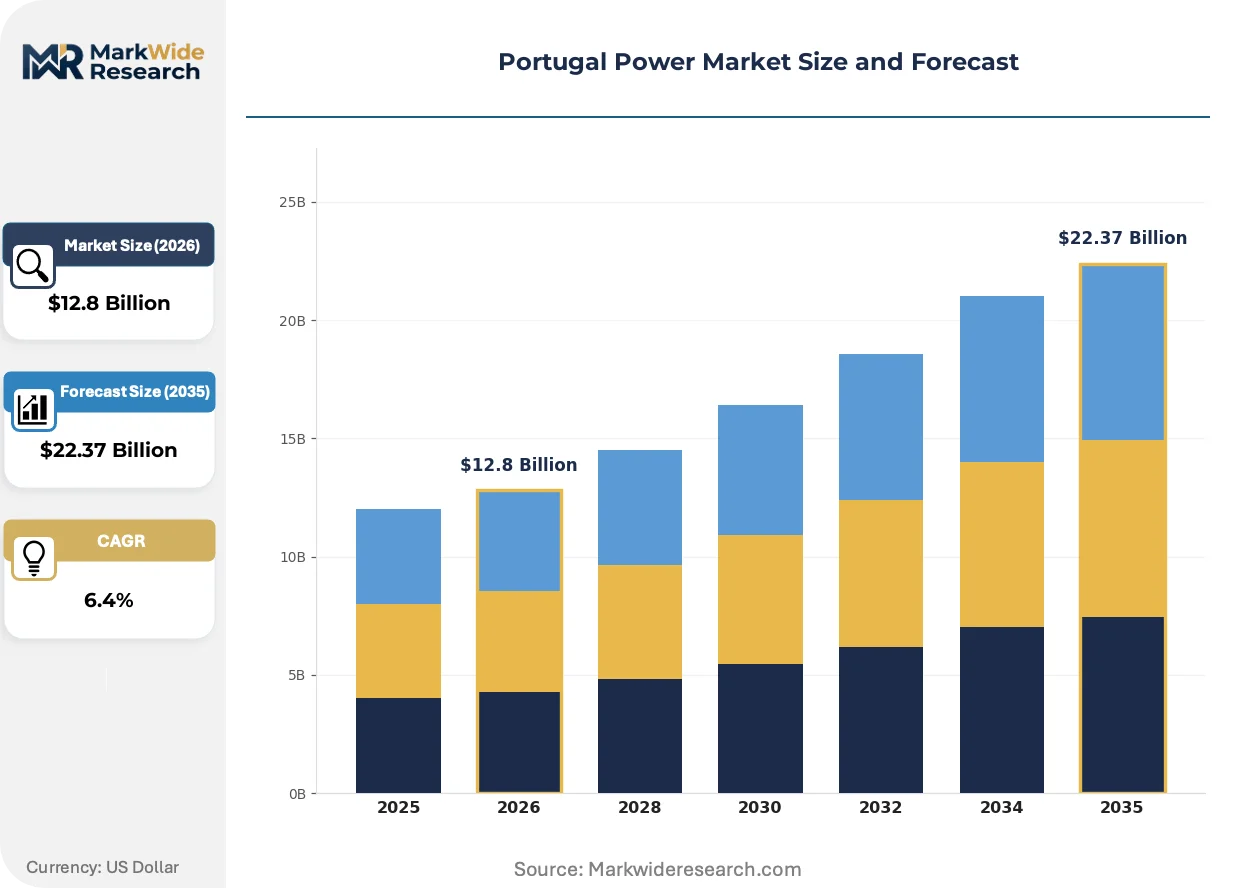
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Thermal, Nuclear, Hydropower End User: Residential, Commercial, Industrial, Government Service Type: Generation, Transmission, Distribution, Retail Technology: Photovoltaic, Wind Turbine, Gas Turbine, Biomass |
| Companies Covered | REN - Redes Energéticas Nacionais, Finerge SA, Energias de Portugal (EDP), Aquila Capital, Eni SpA, Enel SpA, Acciona SA, Galp Energia, Iberdrola SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Power Market Evolving Landscape
Asset digitization and hybrid technology configurations are compressing traditional technology boundaries in Portugal's power sector. These developments are redefining competitive positioning across generation, transmission, and distribution segments.
Solid-state battery storage is bifurcating the grid-scale market between lithium-ion dominance in 4-hour duration applications and emerging sodium-ion chemistries for longer-duration shifting. Industrial offtakers in the Lisbon corridor are piloting hybrid lithium-sodium configurations to hedge raw material exposure. This chemistry diversification is compressing supplier margins for pure-play lithium integrators while opening procurement windows for European cell manufacturers.
CE marking requirements under the EU Green Deal framework are tightening equipment qualification protocols for grid-connected inverters and switchgear. Portugal's Direção-Geral de Energia e Geologia is enforcing extended type-testing timelines that delay project commissioning. Distribution service operators are responding by pre-qualifying component suppliers against anticipated 2027 standards revisions.
Corporate renewable procurement is consolidating buyer power among energy-intensive manufacturers seeking 24/7 carbon-free energy matching. Traditional utility-led contracting is yielding to direct bilateral negotiations with hybrid asset developers. This pattern is most visible in the Porto industrial zone where cement and pulp producers are aggregating demand to anchor offshore wind-plus-battery projects.
Portugal Power Market Segmentation
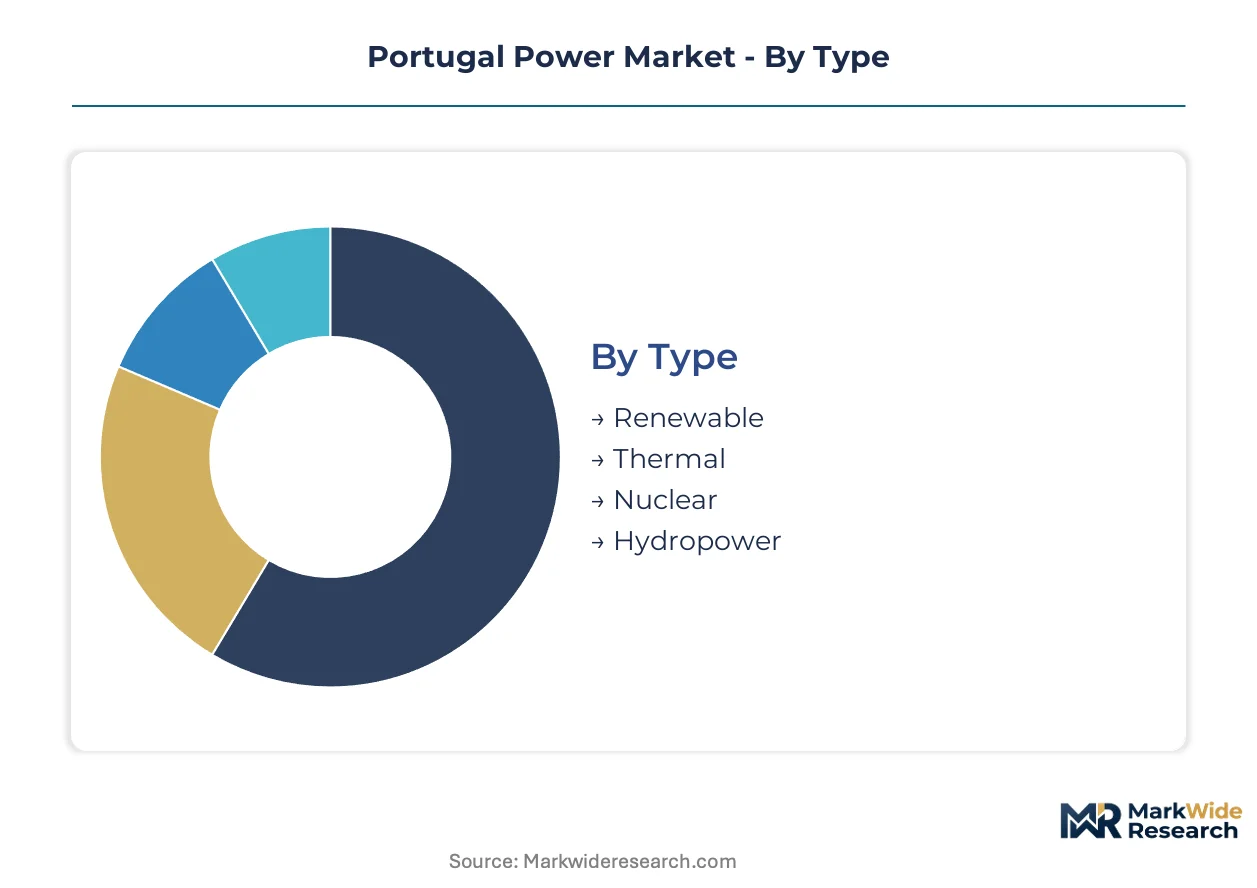
Portugal's power market segmentation reflects the country's REPowerEU-aligned transition from centralized fossil generation to distributed renewable assets with grid-scale storage co-location. Each dimension captures distinct investment flows, regulatory exposure, and margin structures across the value chain.
Type:
Generation type determines interconnection queue priority and capacity market revenue eligibility under Portugal's National Energy and Climate Plan implementation.
- Renewable:Wind and solar assets dominate new capacity additions, with offshore wind concessions awarded by Portugal's environmental regulator concentrating development capital around Lisbon and Porto corridors. Grid-scale battery co-location requirements under REPowerEU storage mandates are compressing merchant revenue windows for standalone projects.
- Thermal:Natural gas plants provide frequency response within 0.5 Hz deviation limits, though EU ETS carbon pricing and fuel import dependency are eroding dispatch economics. Sines and Matosinhos host the remaining operational fleet serving peak demand.
- Nuclear:Portugal maintains zero nuclear generation capacity, with constitutional prohibitions blocking any future development. Grid planning assumes permanent exclusion from baseload portfolios.
- Hydropower:EDP's pumped-storage facilities in the Douro and Tagus basins anchor renewable integration, providing 15-minute ramping capability for solar and wind variability absorption.
Renewable dominates installed base. Hydropower is where expansion concentrates for grid stability services.
End User:
Customer segmentation reveals divergent procurement patterns, with industrial buyers aggregating demand for direct bilateral contracts while residential loads remain captive to regulated tariffs.
- Residential:Smart meter rollout mandates under EU directives are digitizing 6.5 million connection points, enabling time-of-use pricing and distributed solar self-consumption schemes. Capital intensity for distribution service operators concentrates in rural Alentejo and Centro regions.
- Commercial:Mid-sized enterprises in Lisbon's service economy are adopting rooftop photovoltaic with battery backup to hedge against regulated tariff volatility. CE marking requirements for grid-connected inverters extend procurement timelines.
- Industrial:Energy-intensive manufacturers in Porto's cement, pulp, and chemical sectors are signing long-term power purchase agreements for dispatchable clean assets, aggregating demand to anchor offshore wind-plus-battery projects.
- Government:Public sector procurement prioritizes 24/7 carbon-free energy matching for administrative buildings and defense installations, with centralized purchasing through EPE—Empresa de Planeamento e Gestão de Energia.
Industrial offtake commands the steepest expansion trajectory. Residential represents the largest connection count.
Service Type:
Value chain position determines exposure to regulated returns versus merchant risk, with transmission and distribution operating under REN's regulated asset base framework.
- Generation:Margin pools in offshore wind concessions and Alentejo solar zones, with project developers facing grid code compliance costs for frequency response capabilities. Hybrid wind-plus-hydro configurations sustain EDP's competitive position.
- Transmission:HVDC corridor upgrades linking Alentejo solar zones to northern demand centers concentrate investment, with converter station manufacturing bottlenecks in German and Chinese supply chains delaying procurement.
- Distribution:Smart meter data monetization opportunities are emerging as EU directive-mandated rollout infrastructure enables grid flexibility services to aggregators. REN's subsidiary E-Redes manages voltage classes from 60 kV to 230 V.
- Retail:Corporate renewable procurement is displacing traditional utility-led contracting, with direct bilateral negotiations between industrial buyers and hybrid asset developers restructuring commercial terms.
Distribution commands the largest regulated asset base. Generation is where private capital deployment concentrates.
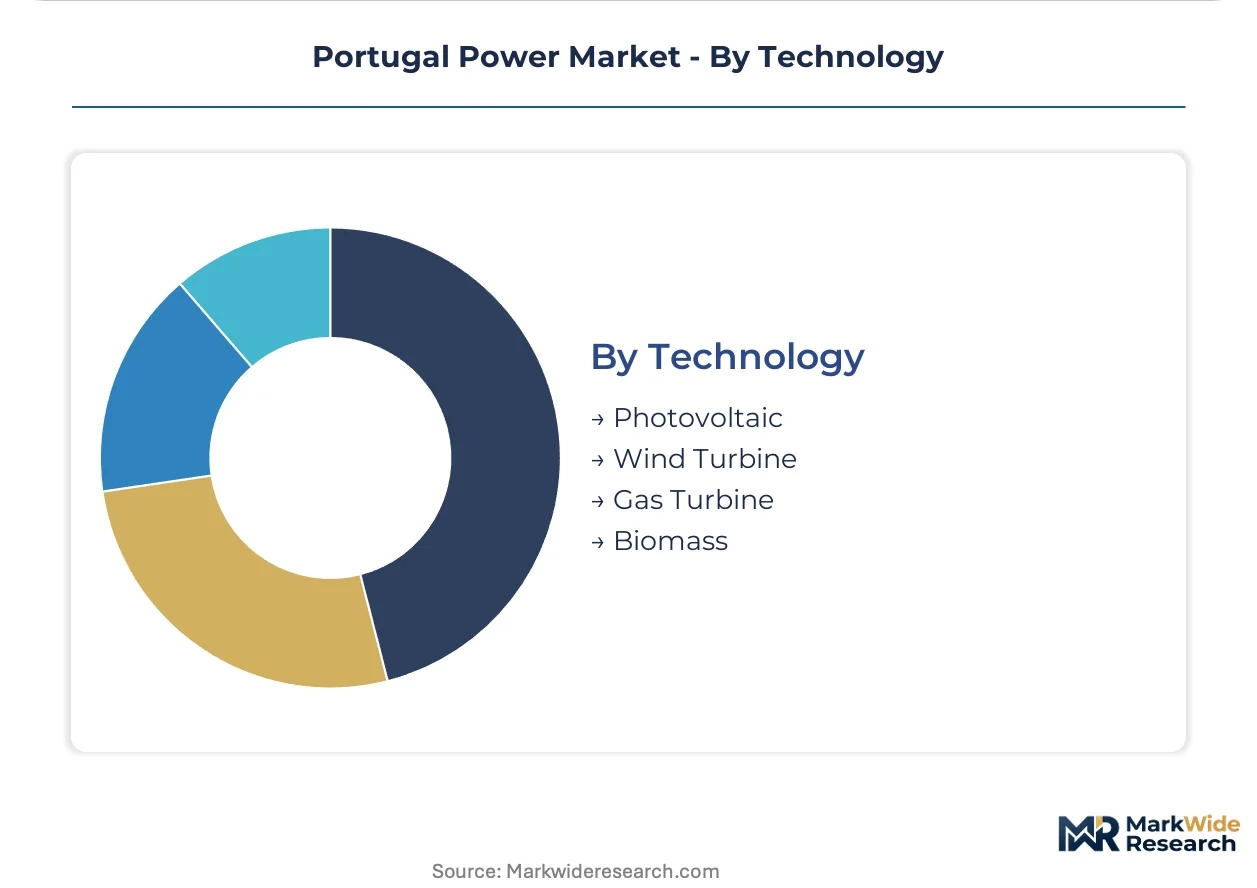
Technology:
Technology selection drives equipment sourcing geography and raw material exposure, with sodium-ion chemistries emerging to hedge lithium supply concentration.
- Photovoltaic:Alentejo's solar irradiance levels support utility-scale deployment, though grid saturation at 220 kV substations is delaying commercial operation dates for new projects. CE marking protocols under EU Green Deal framework extend type-testing timelines.
- Wind Turbine:Onshore development across northern and central districts concentrates under Finerge SA's portfolio, while offshore licensing rounds are auctioning seabed concessions with 25-year lease terms. Specialized technician scarcity for turbine maintenance constrains O&M capacity.
- Gas Turbine:Combined-cycle plants at Pego and Tapada do Outeiro provide system inertia, though EU F-Gas Regulation phase-down of sulfur hexafluoride is reshaping switchgear sourcing for grid interconnection.
- Biomass:Forest residue-fired plants in Centro and Norte regions supply dispatchable renewable generation, with feedstock logistics concentrated in pulp industry byproduct streams.
Wind turbine dominates installed renewable capacity. Photovoltaic is where capacity additions concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter station manufacturing bottlenecks in German and Chinese supply chains are constraining HVDC procurement timelines across Iberian transmission corridors. Equipment sourcing geography is reshaping project delivery schedules for solar-to-demand center linkages.
Alentejo
Solar irradiance levels support utility-scale photovoltaic deployment across the region's agricultural plains. CE marking protocols under the EU Green Deal framework extend type-testing timelines for grid-connected inverters. Grid saturation at 220 kV substations in Évora and Beja is delaying commercial operation dates for new projects.
Lisbon Metropolitan Corridor
Offshore wind licensing rounds are auctioning seabed concessions with 25-year lease terms. Portugal's Direção-Geral de Energia e Geologia enforces extended environmental impact assessments for floating turbine arrays. The Port of Sines anchors green hydrogen offtake corridors where industrial buyers contract electrolyzer-linked renewable supply.
Porto Metropolitan Corridor
Energy-intensive manufacturers in cement, pulp, and chemical sectors aggregate demand for direct bilateral power purchase agreements. EU F-Gas Regulation phase-down of sulfur hexafluoride is reshaping switchgear sourcing for transmission interconnections. Matosinhos hosts combined-cycle gas turbine capacity serving peak demand with 15-minute ramping capability.
Douro and Tagus Basins
Pumped-storage hydropower facilities provide frequency response within 0.5 Hz deviation limits for renewable integration. REN - Redes Energéticas Nacionais manages reservoir dispatch coordination with wind and solar variability absorption. EDP's hybrid wind-plus-hydro portfolio sustains competitive positioning from Lisbon headquarters.
Central and Northern Districts
Onshore wind development concentrates across forested terrain with established grid access. Specialized technician scarcity for turbine maintenance constrains O&M capacity in Viseu and Castelo Branco sub-regions. Biomass generation from pulp industry byproduct streams supplies dispatchable renewable capacity alongside wind assets.
Portugal Power Market Competitive Landscape
Concentration sits with integrated utilities controlling transmission infrastructure and hybrid renewable portfolios. The competitive structure divides between regulated transmission operators, renewable developers with offshore concessions, and industrial offtakers aggregating demand for direct bilateral contracts. Strategic archetypes include grid-scale hybrid asset builders, distribution service operators monetizing smart meter data, and corporate procurement aggregators. Dominant competitive moves encompass co-location mandates forcing battery storage pairing with generation assets, and long-term offtake contracting displacing traditional utility-led retail structures.
Among Iberian-headquartered integrated utilities, EDP and Iberdrola SA exemplify the hybrid renewable developer archetype with combined wind, solar, and hydro portfolios. REN - Redes Energéticas Nacionais occupies the regulated infrastructure position as Portugal's transmission system operator. Finerge SA represents the specialized onshore wind developer segment with concentrated northern and central district exposure. These three entities anchor the competitive landscape across generation, transmission, and distribution value chain positions.
| Leading Market Players |
|---|
| REN - Redes Energéticas Nacionais |
| Finerge SA |
| Energias de Portugal (EDP) |
| Aquila Capital |
| Eni SpA |
| Enel SpA |
| Acciona SA |
| Galp Energia |
| Iberdrola SA |
| Others |
Value Network & Pricing Analysis
Converter station lead times stretching 18-24 months from German and Chinese manufacturers concentrate procurement power among HVDC equipment suppliers, compressing margins for Portuguese transmission developers while elevating pricing leverage at the top tier. This supply bottleneck feeds directly into project cost structures, with Alentejo-to-north corridor upgrades facing cascading delays that reshape competitive positioning across the value chain.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure for high-voltage switchgear, with sulfur hexafluoride-free vacuum interrupter technology commanding premium positioning against conventional alternatives. Pricing stratifies across CE-marked certified equipment, volume-scale procurement by REN, and aftermarket service bundling for grid automation platforms. Cost compression in standard-tier inverters is intensifying because Chinese manufacturers are expanding European distribution. Industrial offtakers in Porto's cement and pulp sectors show lowest price sensitivity due to long-term power purchase agreement anchoring, while distributed solar developers face acute margin pressure from grid code compliance mandates.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and rare earth magnets characterizes procurement behavior among Portuguese hybrid asset developers seeking to hedge raw material volatility. Equipment sourcing concentrates in China for photovoltaic modules, Germany for HVDC converter stations, and Denmark for offshore wind turbine components. Raw material dependencies center on lithium carbonate, neodymium-dysprosium magnets, and high-grade silicon. Single-source vulnerability in converter station manufacturing creates systemic risk for transmission timeline adherence. Distribution runs through Lisbon-based EPC contractors coordinating with northern European OEMs for turbine delivery and Asian suppliers for battery integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portugal's power sector requires incumbents to defend against corporate renewable procurement displacing traditional utility-led retail structures, as industrial buyers aggregate demand for direct bilateral contracts with hybrid asset developers.
For Market Incumbents: Secure long-term offtake positions with energy-intensive manufacturers in the Porto metropolitan corridor before competitor developers capture anchor tenant status for offshore wind-plus-battery projects. Secure grid interconnection queue priority through early-stage co-location filings with Portugal's Direção-Geral de Energia e Geologia, leveraging regulatory familiarity against emerging entrants facing extended environmental impact timelines.
For New Entrants and Emerging Players: Smart meter data monetization represents the most penetrable service layer, as EU directive-mandated rollout infrastructure creates aggregator-facing revenue streams that E-Redes has underdeveloped. Target rural Alentejo and Centro regions for distributed solar-plus-storage deployment where grid saturation at 220 kV substations has delayed incumbent commercial operation dates, opening procurement windows for flexible smaller-scale configurations.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure-plus-merchant hybrid play because transmission and distribution assets provide contracted returns while generation exposure offers REPowerEU-aligned growth optionality. Acquisition focus should center on developers holding offshore wind seabed concessions with 25-year lease terms and established HVDC interconnection agreements. The signal to watch is capacity market auction design evolution under Lisbon's storage procurement mandate implementation.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Floating turbine arrays in Lisbon corridor leverage 25-year seabed concessions awarded by Portugal's environmental regulator. |
| Grid-Scale Battery Co-location | REPowerEU-aligned storage mandates force renewable developers to pair generation assets with frequency response capability. |
| HVDC Corridor Upgrade | Alentejo-to-north transmission links concentrate investment around Évora-Porto axis under REN's regulated asset base. |
| Corporate PPA Structuring | Direct bilateral negotiations with Porto industrial buyers displace traditional utility-led retail contracting models. |
| Smart Meter Data Monetization | EU directive-mandated rollout infrastructure enables grid flexibility services to aggregators through E-Redes distribution network. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against IEA reports, EIA data, FERC filings, and project development databases. Bottom-up capacity addition modeling triangulated with top-down regulatory framework analysis across generation type, service type, and regional grid clustering dimensions.
Variance decomposition across the projection horizon isolates technology cost trajectory, interconnection queue dynamics, and industrial offtake contracting velocity as primary forecast drivers. Segmentation modeling incorporates fuel source, generation capacity tier, regulatory framework, and regional grid type. CAGRs derive from installed base evolution, policy implementation timelines, and capital deployment patterns observed across European peer markets.
Forecasts assume regulatory continuity in EU Green Deal implementation and Portugal's National Energy and Climate Plan; material policy shifts including REPowerEU storage mandate acceleration or F-Gas Regulation phase-down tightening would require re-modeling. Revision becomes warranted when HVDC equipment procurement bottlenecks or specialized technician scarcity crosses thresholds that materially compress commercial operation date schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Canada Power Market
Power
Angola Power EPC Market
Power
India Power Market
Power
Distribution Feeder Protection System Market
Power
Power Sled Market
Power
Europe Solar Inverter Market
Power
Gas Freeing Fan Market
Power
Sudan Power EPC Market
Power
Marine Thermal Fluid Heaters Market
Power
Smart PV Inverters Market
Power
Existent Gum Steam Generator Market
Power
Global Advanced Marine Power Supply Market
Power
HVDC Capacitor Market
Power
Kuwait Power Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Asia-Pacific Turbomachinery Control Systems Market