
 Vietnam Insecticide Market | 2026-2036
Vietnam Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Insecticide Market Insights
Multi-source procurement of active ingredients is decoupling Vietnamese formulators from sole dependence on Chinese technical-grade imports. BASF SE leverages its Ludwigshafen-based R&D pipeline to supply novel pyrethroid chemistries to local distributors. Bayer AG anchors its position through backward integration into seed treatment combinations that bundle insecticide applications. Syngenta Group competes via dedicated technical service teams embedded in the Mekong Delta's rice cooperatives.
Vietnam insecticides comprise synthetic and biological agents formulated to disrupt arthropod nervous systems, metabolic pathways, or growth cycles, typically delivered as emulsifiable concentrates with active ingredient loadings between 10% and 50% for foliar application. Their primary purpose centers on protecting agricultural yield volumes and public health outcomes against vector-borne disease transmission. Neonicotinoid demand dominates agricultural crop applications despite pollinator toxicity scrutiny, while biorational insecticides represent the fastest-expanding formulation class as export-oriented farmers face EU supermarket chain residue audits. Liquid formulations capture the largest volume share due to ease of aerial and knapsack sprayer deployment across flooded paddy fields.
Vietnam's Ministry of Agriculture and Rural Development administers pesticide registration through Circular 24 revisions, while the Vietnam Environment Administration enforces ecological risk assessments that restrict organophosphate persistence in watersheds. These frameworks compel formulators to reformulate toward shorter-residue chemistries and invest in local toxicology dossier preparation. Stakeholders must monitor how the country's national pharmaceutical regulator evaluates novel RNA interference insecticides for future registration pathways.
Market Dynamics
Circular 24's tightened maximum residue limits are forcing Vietnamese formulators to abandon organophosphate chemistries and rebuild product portfolios around biorational alternatives, compressing reformulation timelines to under eighteen months.
Growth Catalysts
- Export compliance mandates:EU supermarket chain residue audits are compelling Mekong Delta rice cooperatives to adopt neonicotinoid alternatives that meet stricter phytosanitary standards.
- Neonicotinoid persistence in paddy systems:Flooded field conditions extend the efficacy window of imidacloprid-based formulations, reducing application frequency for intensive rice cultivation.
- Red River Delta vegetable intensity:Year-round greenhouse production around Hanoi generates continuous demand for pyrethroid rotation to manage thrips and whitefly resistance cycles.
Market Restraints
- Technical-grade import concentration:Chinese active ingredient suppliers control over seventy percent of technical pyrethroid and neonicotinoid feedstock, exposing Vietnamese blenders to geopolitical supply interruptions.
- Ecological risk assessment delays:Vietnam Environment Administration watershed persistence studies add fourteen to twenty-two months to novel chemistry registration timelines.
- Biorational cost premiums:Bacillus thuringiensis and spinosad formulations carry unit costs three to four times higher than synthetic equivalents, limiting smallholder adoption.
Strategic Opportunities
- RNA interference insecticides:The national pharmaceutical regulator's emerging evaluation pathway for dsRNA-based crop protection opens first-mover positioning ahead of conventional chemistry competitors.
- Drone application services:Aerial spraying cooperatives in An Giang and Long An provinces are creating bundled input-plus-application offerings that bypass traditional distributor markups.
- Seed treatment bundling:Rice seed enterprises are integrating insecticide coatings at processing facilities, capturing value upstream from foliar spray markets.
Industry Challenges
- Toxicology dossier preparation:Local manufacturers lack GLP-certified laboratories, forcing reliance on outsourced Malaysian and Thai testing facilities that extend registration cycles.
- Knapsack sprayer calibration inconsistency:Smallholder application equipment varies widely across the Central Highlands, producing uneven coverage and accelerating resistance development in coffee and pepper plantations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Insecticide Market |
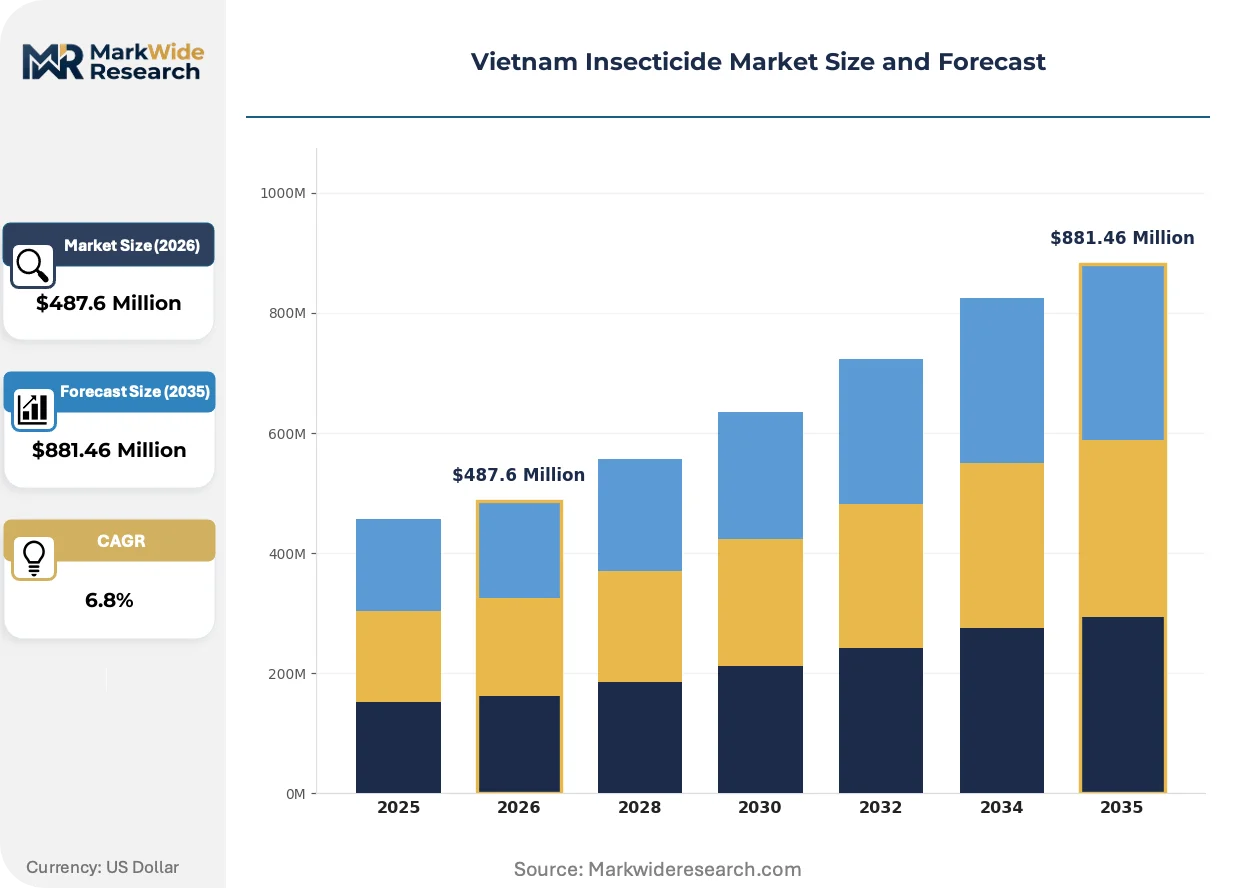
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insect Growth Regulators, Biorational Insecticides, Pyrethroids, Neonicotinoids Application: Agricultural Crops, Home & Garden, Public Health, Industrial Use Formulation: Liquid, Granule, Powder, Emulsifiable Concentrate End User: Farmers, Pest Control Companies, Government Agencies, Consumers |
| Companies Covered | ADAMA Agricultural Solutions Ltd, BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, PI Industries, Syngenta Group, UPL Limited, Wynca Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Insecticide Market Trends and Innovations
Formulation chemistry and application technology are converging to reduce environmental persistence while maintaining efficacy against resistant pest populations. Three developments are restructuring competitive positioning.
Microencapsulated pyrethroid delivery systems are electrifying field performance by extending residual activity through controlled release mechanisms. Large vegetable export operations in Lam Dong province are adopting these formulations to minimize re-entry intervals for farm laborers. The technology is compressing competitive differentiation around formulation sophistication rather than active ingredient sourcing alone.
Circular 24 revisions by Vietnam's Ministry of Agriculture and Rural Development are eliminating organophosphate registrations for watershed-adjacent cropping zones. Domestic manufacturers must submit new environmental fate studies for existing products. Rice-intensive provinces including Can Tho and Dong Thap face the steepest compliance burdens as flood irrigation systems amplify runoff concerns.
Farmer purchasing collectives in the Mekong Delta are consolidating input procurement through cooperative-owned storage facilities that aggregate volume discounts directly from formulators. Traditional district-level agrochemical retailers are losing share to these vertically integrated buying groups. The shift is most visible in An Giang province where rice cooperative membership exceeds sixty percent of cultivated area.
Vietnam Insecticide Market Segmentation
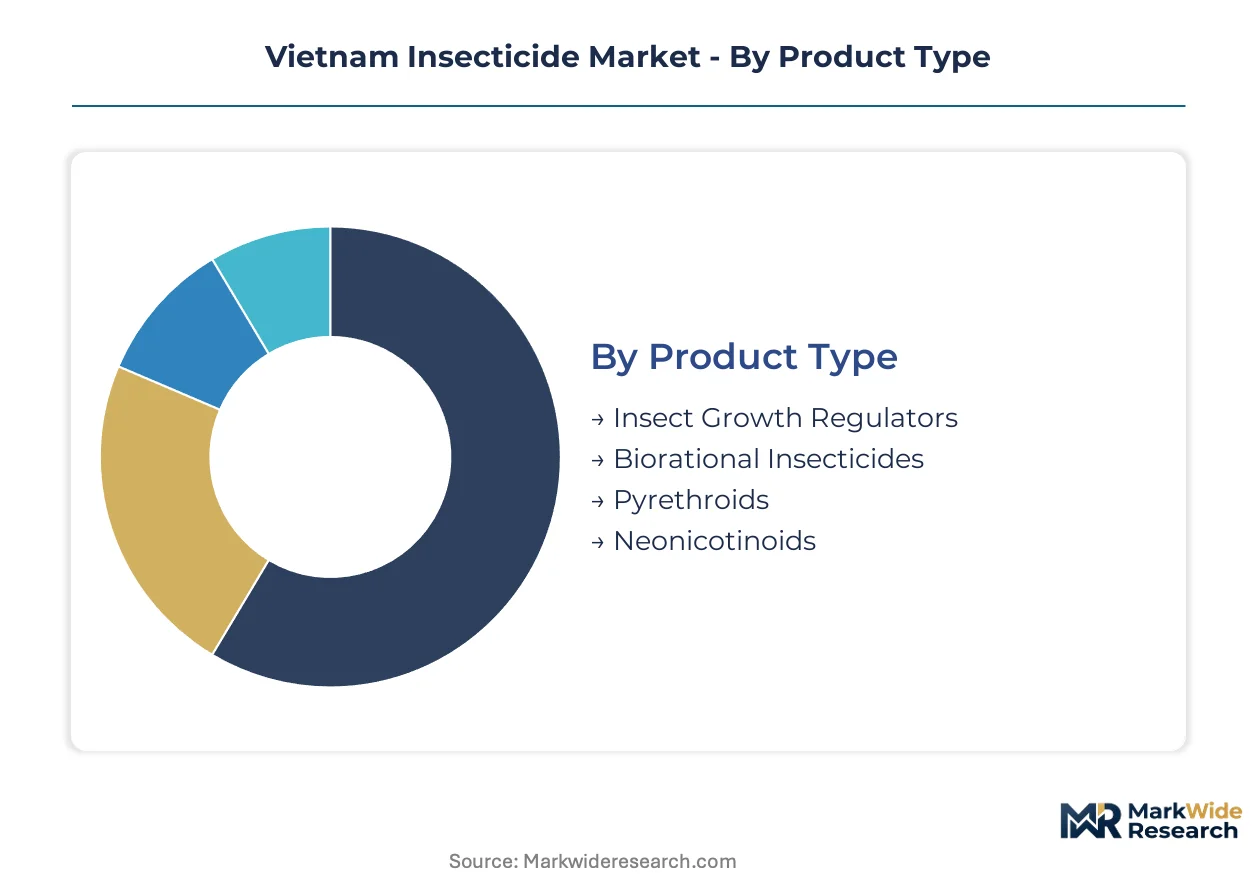
Vietnam's insecticide market fragments across formulation chemistry, application setting, and procurement channel. Each segment carries distinct regulatory burdens and capital requirements that shape competitive entry barriers and margin structures.
Product Type:
Capital intensity varies sharply across chemistry classes, with synthetic active ingredient manufacturing demanding multi-million dollar synthesis infrastructure while biological fermentation requires specialized bioreactor networks.
- Neonicotinoids:Systemic nicotine-receptor agonists formulated as seed treatments or foliar sprays dominate Mekong Delta rice protection. Demand concentrates in Can Tho and Dong Thap provinces where flood irrigation extends imidacloprid persistence against brown planthopper infestations.
- Pyrethroids:Sodium-channel modulators delivered as emulsifiable concentrates or wettable powders anchor vegetable export compliance. Red River Delta greenhouse operations around Hanoi drive rotation demand to manage thrips resistance cycles in year-round tomato and pepper production.
- Biorational Insecticides:Microbial and botanical agents including Bacillus thuringiensis and spinosad target EU supermarket chain residue limits. Lam Dong province vegetable exporters absorb three-to-four-fold cost premiums to secure phytosanitary certification.
- Insect Growth Regulators:Chitin synthesis inhibitors and juvenile hormone mimics disrupt molt cycles in Lepidopteran pests. Coffee and pepper plantations in the Central Highlands adopt IGRs for resistance management against leaf-eating caterpillars.
Most installed capacity flows through Neonicotinoids. Expansion is steepest in Biorational Insecticides.
Application:
Customer procurement patterns diverge between institutional tender processes and decentralized smallholder purchasing, creating distinct distribution economics across each setting.
- Agricultural Crops:Rice, vegetables, coffee, and fruit cultivation absorb the dominant volume share. Mekong Delta cooperatives aggregate demand through farmer-owned storage facilities that bypass traditional district retailer markups.
- Public Health:Vector control programs against dengue and malaria mosquitoes deploy organophosphate and pyrethroid space sprays. Provincial health departments tender through centralized procurement channels with multi-year supply contracts.
- Home & Garden:Urban consumers in Ho Chi Minh City and Hanoi purchase ready-to-use aerosols and coil formulations through modern trade channels. Convenience positioning commands premium pricing over agricultural equivalents.
- Industrial Use:Food processing facilities, warehouses, and logistics centers require scheduled fumigation and residual barrier treatments. Third-party pest management operators bundle chemical supply with service contracts.
Volume concentrates in Agricultural Crops. Regulatory scrutiny is tightening fastest in Public Health.
Formulation:
Manufacturing asset requirements scale with formulation complexity, from simple powder blending to microencapsulation reactors that extend residual activity through controlled release.
- Liquid:Suspension concentrates and soluble liquids enable rapid aerial and knapsack deployment across flooded paddy fields. An Giang and Long An aerial spraying cooperatives favor liquid formats for drone application compatibility.
- Emulsifiable Concentrate:Oil-in-water systems carrying 10-50% active ingredient loads remain the workhorse for foliar spraying. Formulators face Circular 24 pressure to replace aromatic hydrocarbon solvents with bio-based alternatives.
- Granule:Clay-carrier formulations deliver systemic chemistries directly to rice root zones at transplanting. Labor savings versus foliar spraying justify higher unit costs in wage-inflated Red River Delta operations.
- Powder:Wettable powders and dusts serve niche applications in stored grain protection and seed dressing. Hygroscopic stability challenges limit tropical storage shelf life without climate-controlled warehousing.
Production volume flows predominantly through Liquid. Technology investment is concentrating in Emulsifiable Concentrate reformulation.
End User:
Purchasing sophistication ranges from government technical committees evaluating toxicology dossiers to unassisted smallholders relying on retailer recommendations.
- Farmers:Rice cooperative members in the Mekong Delta and independent vegetable growers in the Central Highlands constitute the core demand base. Knapsack sprayer calibration inconsistency produces uneven coverage and accelerates resistance development.
- Pest Control Companies:Licensed operators service industrial accounts and affluent urban households with integrated pest management protocols. Technical certification requirements create barriers to informal competitor entry.
- Government Agencies:Provincial agriculture departments and plant protection stations distribute subsidized inputs and execute emergency outbreak response. Tender transparency varies across provincial administrative boundaries.
- Consumers:Urban households purchase household insecticides through supermarkets, convenience stores, and e-commerce platforms. Brand recognition and packaging convenience drive selection more than active ingredient disclosure.
Transaction volume concentrates with Farmers. Procurement formalization is advancing fastest among Pest Control Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Vietnamese provinces are redirecting formulation capacity toward sub-regions with streamlined registration pathways. Manufacturers migrate technical-grade blending operations to areas where provincial environmental clearances compress facility commissioning timelines.
Mekong Delta
Flood-irrigated rice cultivation in Can Tho and Dong Thap provinces sustains concentrated demand for systemic neonicotinoid formulations. Circular 24's watershed proximity restrictions force blenders to relocate organophosphate-dependent production to drier zones. An Giang province hosts the densest cluster of aerial spraying cooperatives bundling drone application services with bulk chemical procurement.
Red River Delta
Year-round greenhouse vegetable operations around Hanoi generate continuous pyrethroid rotation requirements for thrips and whitefly management. The Vietnam Environment Administration prioritizes ecological risk assessments in this watershed, extending novel chemistry registration timelines. Bac Ninh and Hung Yen provinces concentrate microencapsulated formulation demand from export-oriented tomato and pepper growers.
Central Highlands
Coffee and pepper plantations in Lam Dong and Dak Lak provinces drive insect growth regulator adoption for leaf-eating caterpillar resistance management. Knapsack sprayer calibration inconsistency produces uneven coverage across mountainous terrain. Provincial plant protection stations distribute subsidized biological alternatives to smallholders transitioning from synthetic chemistries.
Southeast Region
Industrial pest management contracts in Ho Chi Minh City and Binh Duong province sustain pyrethroid space spray demand for warehouse and logistics facilities. Urban household insecticide consumption concentrates in modern trade channels serving apartment-dwelling consumers. Dong Nai province anchors third-party fumigation operator networks bundling chemical supply with scheduled service protocols.
Vietnam Insecticide Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biorational specialization and drone-application bundling. The market structure stratifies across multinational technical-grade suppliers, domestic formulators with provincial distribution networks, and cooperative-owned procurement platforms. Three archetypes dominate: backward-integrated agrichemical conglomerates, fermentation-based biological specialists, and aerial service integrators. Competitive moves concentrate on seed treatment bundling and microencapsulation technology licensing.
Among global agrichemical conglomerates, BASF SE and Bayer AG occupy positions exemplifying backward-integrated supply architectures. Syngenta Group represents the technical service-embedded model with cooperative-facing field teams. Domestic manufacturers including Wynca Group and PI Industries sit within the import-dependent blending tier, sourcing technical-grade feedstock from Chinese suppliers.
| Leading Market Players |
|---|
| ADAMA Agricultural Solutions Ltd |
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| PI Industries |
| Syngenta Group |
| UPL Limited |
| Wynca Group |
| Others |
Pricing and Supply Chain Analysis
Formulation chemist concentrations in Ho Chi Minh City's industrial zones compress labor-cost differentials between premium microencapsulated pyrethroids and economy-grade emulsifiable concentrates. Pricing stratifies across three tiers as technical-grade import dependencies and Circular 24 compliance burdens reshape margin structures across Vietnamese blenders.
Pricing Analysis
Distributor margins absorb the heaviest compression as Mekong Delta cooperatives consolidate procurement through farmer-owned storage facilities. Three-tier pricing structure separates EU-export-certified biorationals from standard synthetic formulations and economy organophosphate alternatives. Price differentiation hinges on residue certification grade and volume aggregation scale. Cost compression in the economy tier intensifies because Chinese technical-grade feedstock exposes blenders to geopolitical supply interruptions. Smallholder rice farmers in the Central Highlands exhibit the highest price sensitivity, while Lam Dong vegetable exporters absorb premiums for phytosanitary compliance.
Supply Chain Analysis
Direct-to-farmer channels through cooperative-owned procurement platforms now handle the dominant volume share across An Giang and Long An provinces. Geographic supply concentration centers on China for technical pyrethroid and neonicotinoid feedstock, with secondary sourcing from India and Thailand for Bacillus thuringiensis fermentation inputs. Raw material dependencies include aromatic hydrocarbon solvents, clay carriers for granule formulations, and microencapsulation polymer shells. Single-source vulnerability from Chinese active ingredient suppliers creates structural exposure to trade policy shifts. Distribution runs through provincial agrochemical retailers losing share to vertically integrated aerial spraying cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biorational formulation upgrades and seed treatment bundling as export compliance mandates drive premium-tier adoption. Cost-down potential rests on multi-source technical-grade procurement and cooperative-direct distribution bypass.
For Market Incumbents: Acquire microencapsulation technology licenses to defend formulation sophistication advantages against generic pyrethroid competitors. Secure backward integration into seed treatment coating capacity at rice processing facilities to capture value upstream from foliar spray markets. Threat from drone-application cooperatives bundling chemical supply with aerial services demands channel control investments in An Giang and Long An provinces. For New Entrants and Emerging Players: E-commerce platforms serving Ho Chi Minh City and Hanoi urban households offer the most penetrable white-space for ready-to-use household insecticide launches. Target Central Highlands coffee cooperatives with subsidized biological alternatives distributed through provincial plant protection stations. Go-to-market execution should prioritize knapsack sprayer calibration training bundled with product trials to differentiate from established synthetic chemistry suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among import-dependent domestic blenders lacking GLP-certified toxicology capabilities. Long-term viability over the next decade hinges on Circular 24 compliance infrastructure and biorational formulation pipelines. Acquisition target archetype: fermentation-based biological specialists with existing Vietnam Environment Administration dossier experience. Signal to monitor: national pharmaceutical regulator guidance on RNA interference insecticide registration pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Treatment | Rice seed enterprises at Can Tho processing facilities capture insecticide value upstream from foliar markets. |
| Microencapsulation Technology Licensing | Lam Dong vegetable exporters minimize farm laborer re-entry intervals through controlled-release pyrethroid delivery. |
| Multi-Source Technical-Grade Procurement | Vietnamese blenders reduce Chinese supplier concentration via Indian and Thai active ingredient diversification. |
| Drone Application Service Bundling | An Giang aerial spraying cooperatives bypass traditional distributor markups through input-plus-application offerings. |
| GLP-Certified Toxicology Investment | Domestic manufacturers eliminate Malaysian and Thai testing facility reliance to compress registration cycles. |
Research Methodology
Coverage spans the Mekong Delta, Red River Delta, Central Highlands, and Southeast Region, with primary inputs from each sub-region's distinct agricultural systems. The analysis combines structured interviews with formulation chemists, cooperative procurement managers, provincial plant protection officers, and agrochemical distribution channel partners. Secondary validation draws from Vietnam Ministry of Agriculture and Rural Development Circular 24 revisions, Vietnam Environment Administration ecological risk assessments, customs import records for technical-grade feedstock, and EU phytosanitary residue audit protocols. Bottom-up demand modeling from farmer purchasing patterns triangulates against top-down capacity assessments of domestic blending facilities.
Rate-of-change decomposition separates volume growth from price-mix shifts across the projection horizon. The analytical framework models segmentation dimensions including formulation chemistry class, application setting, procurement channel structure, and provincial regulatory burden intensity. CAGRs derive from trend extrapolation of cooperative membership expansion, export compliance adoption curves, and seed treatment penetration rates. Industry-specific forecast inputs incorporate Circular 24 implementation timelines and EU supermarket chain audit frequency assumptions.
Regulatory enforcement intensity, Chinese technical-grade supply continuity, and EU phytosanitary standard revisions are the dominant revision risks for projection accuracy. Forecasts reflect assumptions regarding cooperative procurement consolidation velocity and biorational cost-premium compression timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
United States Nematicides Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Avicides Market
Crop Protection
South America Insecticide Market
Crop Protection
Fumigation Service Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Algaecides Market
Crop Protection
Soil Fumigant Market
Crop Protection
South America Fungicide Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Fogger Market