
 Global Dicalcium Phosphate (Feed Grade) Market | 2026-2036
Global Dicalcium Phosphate (Feed Grade) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dicalcium Phosphate (Feed Grade) Market Foresight
Monocalcium phosphate is recalibrating product economics across the feed phosphate complex as formulators seek higher phosphorus bioavailability in reduced inclusion rates. Mosaic leverages captive phosphate rock reserves in Florida to sustain cost leadership in North American feed-grade output. OCP anchors supply security through Moroccan rock phosphate dominance, while PhosAgro competes on sulfuric acid integration at its Russian production hubs.
Dicalcium phosphate (feed grade) is a dibasic calcium phosphate compound typically manufactured via the wet-process reaction of phosphoric acid with calcium carbonate or lime, yielding a product containing 18-21% phosphorus and 20-24% calcium on a dry basis, designed primarily as a mineral supplement to correct phosphorus deficiencies in livestock diets. The powder form occupies the largest volume share due to its ease of incorporation into premix operations, though granules are gaining traction in automated bulk handling systems for ruminant feedlots. Poultry remains the dominant animal type segment, with aquaculture representing the fastest-growing application as shrimp and finfish diets intensify mineral fortification requirements.
The FDA's Center for Veterinary Medicine oversees feed additive safety assessments in the United States, while the EU's EFSA establishes maximum permitted levels for phosphorus in complete feeds under the Feed Additives Regulation. China's Ministry of Agriculture and Rural Affairs enforces GB standard compliance for imported feed-grade phosphates, creating a fragmented compliance landscape for cross-border suppliers. Stakeholders must monitor evolving maximum inclusion limits for phosphorus in manure-sensitive watersheds, as environmental discharge regulations increasingly override purely nutritional rationing decisions.
Market Dynamics
Phosphorus bioavailability standards are tightening across major livestock jurisdictions, forcing feed compounders to recalibrate mineral inclusion rates and source from processors with certified wet-process capabilities. This regulatory compression is redrawing procurement relationships between phosphate manufacturers and integrated protein producers.
Growth Catalysts
- EU Feed Hygiene Regulation traceability mandates:Processors investing in batch-level documentation systems capture premium positioning with European compounders facing audit-intensive compliance requirements.
- Aquaculture mineral fortification intensity:Shrimp and finfish diet formulators in Southeast Asia are expanding dicalcium phosphate volumes as pond-based production systems professionalize feed management protocols.
- Brazilian vertical integration:Poultry processors operating captive feed mills source directly from phosphate producers, compressing distribution layers and locking in volume commitments.
Market Restraints
- Phosphoric acid cost volatility:Sulfuric acid integration determines processor margins, with non-integrated facilities exposed to sulfur market swings.
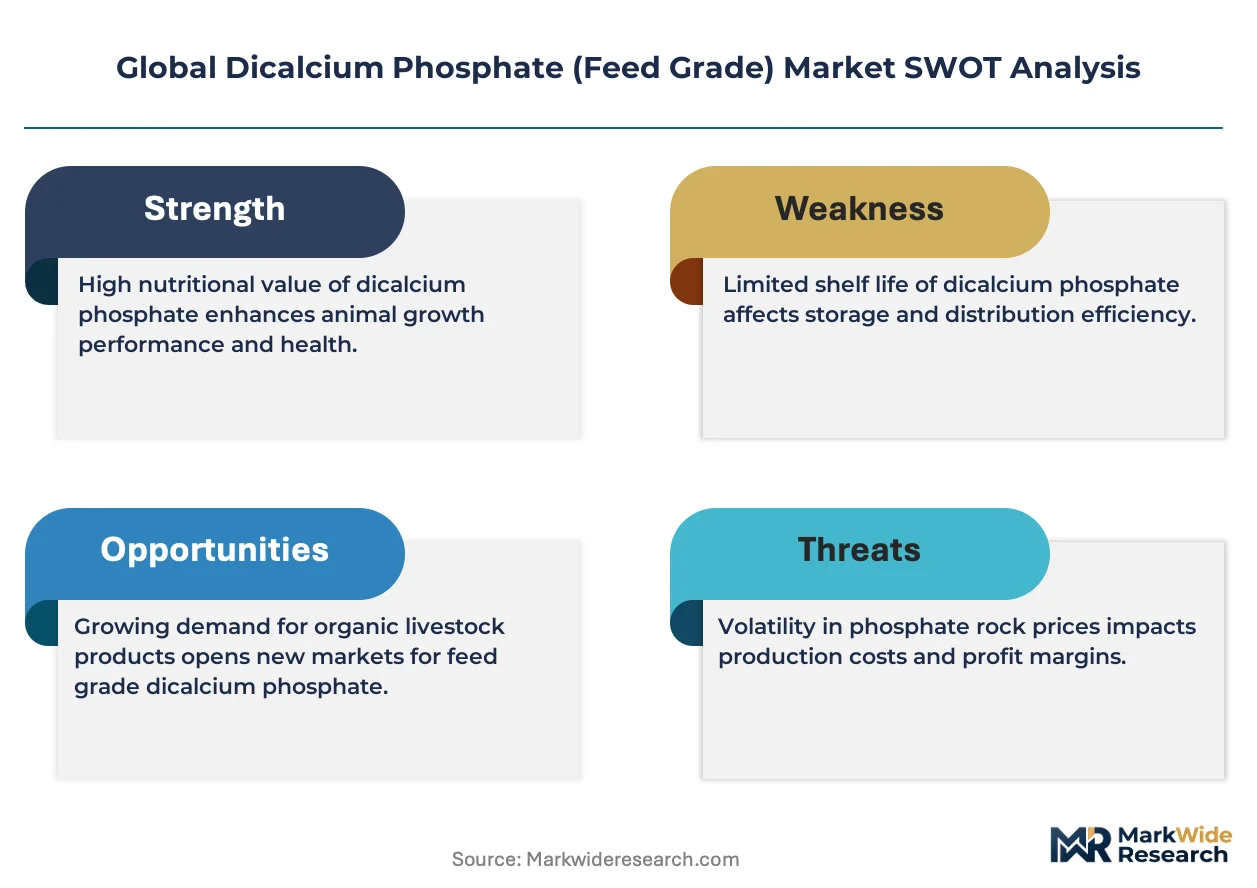
- Moroccan rock phosphate concentration:OCP's dominance over premium-grade ore reserves creates single-source vulnerability for wet-process manufacturers lacking captive mining assets.
- Monocalcium phosphate substitution:Higher bioavailability alternatives are displacing dicalcium phosphate in premium poultry formulations where phosphorus efficiency drives ration economics.
Strategic Opportunities
- Indonesia aquaculture expansion:Shrimp feed producers in Java and Sulawesi lack established phosphate supplier relationships, creating first-mover positioning for certified exporters.
- US EPA phosphorus discharge limits:Chesapeake Bay and Great Lakes watershed regulations are mandating reduced manure phosphorus loads, favoring precision-formulated mineral supplements over commodity rock phosphate.
- Automated bulk handling adoption:Granule-form dicalcium phosphate penetration into North American cattle feedlots requires redesigned particle engineering and pneumatic conveying compatibility.
Industry Challenges
- Wet-process engineering talent scarcity:Phosphoric acid reactor optimization and calcium precipitation control require specialized chemical engineering expertise concentrated at legacy production sites.
- GB standard certification timelines:China's Ministry of Agriculture and Rural Affairs import protocols impose extended laboratory validation periods for new supplier qualification.
- Legacy premix equipment incompatibility:Powder-form specifications vary across regional grinding standards, creating formulation adjustment burdens for multinational feed compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dicalcium Phosphate (Feed Grade) Market |
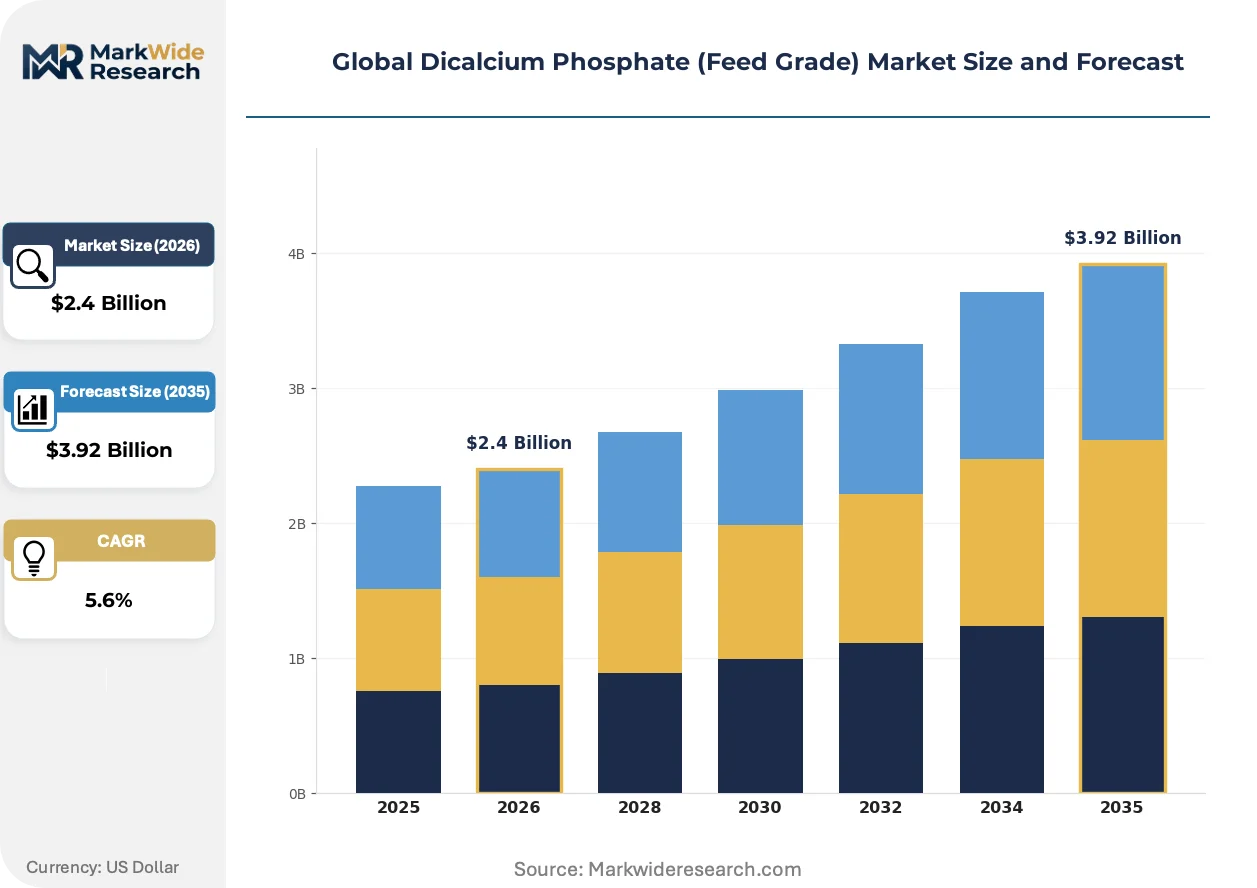
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Granules, Pellets, Crystals Animal Type: Poultry, Swine, Aquaculture, Pet Food, Ruminants Application: Premix, Concentrates, Compound Feed, Feed Supplements Procurement Channel: Direct Purchase, Distributor, Online Platform, Third-Party Vendor |
| Companies Covered | Nutrien, Mosaic, OCP, PhosAgro, Innophos, Ecophos, EuroChem Group, PotashCorp, Baotou Dongbao Bio-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dicalcium Phosphate (Feed Grade) Market Shifts & Advancements
Feed phosphate manufacturing is pivoting toward precision mineral delivery systems that align phosphorus release with animal digestive physiology. This shift is compressing commodity product margins while rewarding processors with formulation science capabilities.
Microencapsulation technology is converging with controlled-release mineral delivery. Dutch and Danish compounders serving antibiotic-free poultry operations are adopting lipid-coated phosphate granules that delay phosphorus availability until intestinal pH conditions optimize absorption. This technology is converging with precision nutrition platforms to enable ration-by-ration mineral adjustment rather than fixed inclusion rates.
EFSA's revised maximum permitted phosphorus levels in complete feeds are forcing reformulation across European swine and poultry operations. The regulation compresses allowable safety margins between nutritional minimums and environmental maximums, compelling compounders to source from processors with tighter assay consistency. German and Polish feed manufacturers are responding by qualifying suppliers through extended stability testing protocols.
Direct-procurement contracts between phosphate processors and protein integrators are displacing traditional distributor relationships. Brazilian and Thai poultry operators now negotiate annual volume agreements with sulfuric acid-integrated manufacturers, bypassing regional trading houses. This concentration is most visible in Mato Grosso and São Paulo states, where three integrated processors account for the majority of contracted phosphate volumes.
Global Dicalcium Phosphate (Feed Grade) Market Segmentation
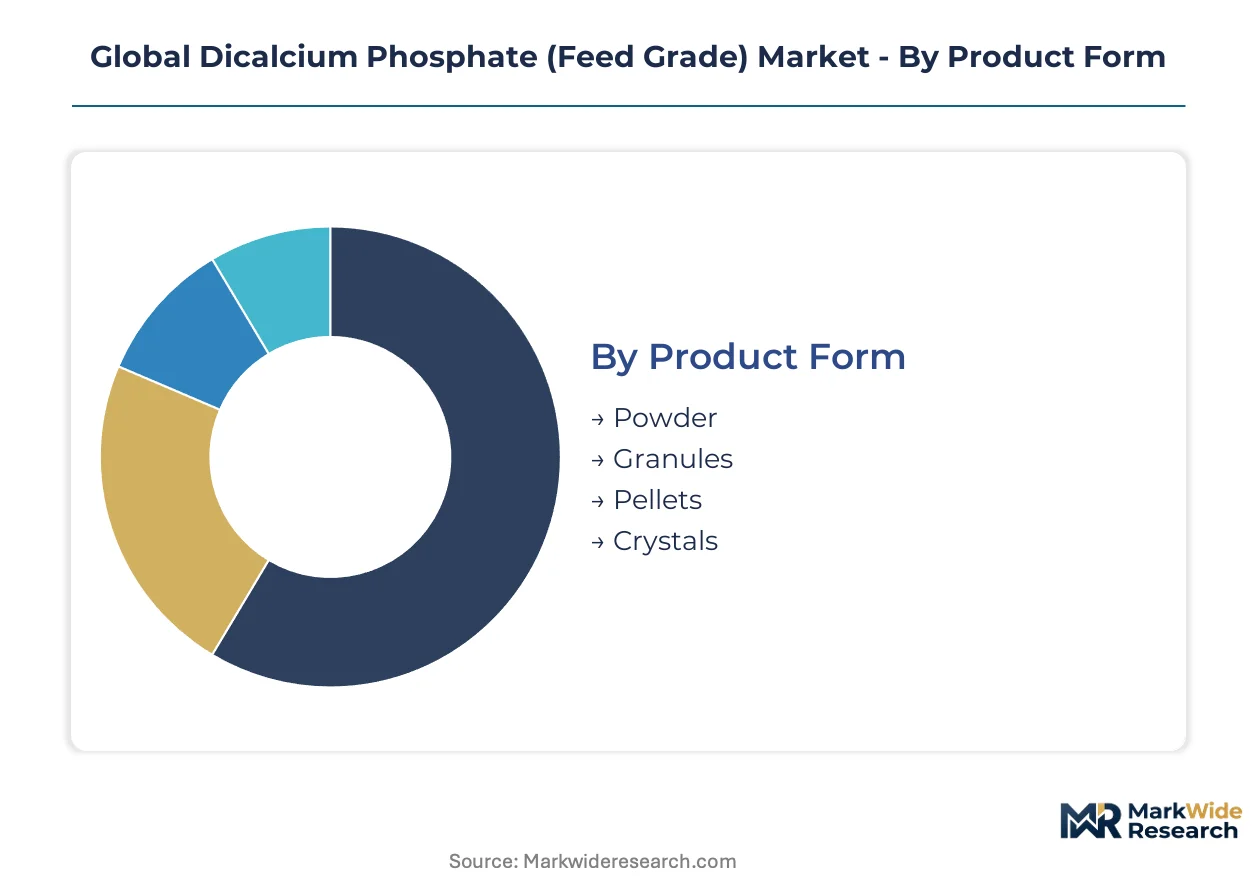
Feed phosphate procurement varies sharply by operational scale and handling infrastructure. Formulators select product forms and channels based on mixing equipment, batch consistency requirements, and regulatory documentation burdens.
Product Form:
Handling economics and dosing precision separate buyers in this category.
- Powder:Fine-ground particles with 18-21% phosphorus content dissolve rapidly in aqueous premix slurries. Southeast Asian compounders favor powder for manual bag-breaking operations at small-to-midscale feed mills lacking pneumatic systems.
- Granules:Spheroidized particles engineered for bulk pneumatic conveyance reduce dust exposure and improve flowability in automated ruminant feedlot operations. North American cattle operations in Texas and Nebraska are retrofitting handling lines to accommodate granule specifications.
- Pellets:Compressed cylindrical forms suit on-farm mineral feeders where weather resistance matters.
- Crystals:High-purity precipitated forms serve laboratory-grade feed trials and specialty pet food formulations.
Powder leads volumes today; granules are gaining share fastest.
Animal Type:
Nutritional phosphorus density requirements and regulatory scrutiny intensity vary by species.
- Poultry:Broiler and layer operations consume the largest phosphate volumes due to rapid flock turnover and mineral-intensive starter diets. Brazilian integrators in São Paulo state negotiate direct processor contracts to secure batch-certified material for antibiotic-free production lines.
- Aquaculture:Shrimp and finfish diets demand highly bioavailable phosphorus forms to minimize water-column discharge. Indonesian producers in Java and Sulawesi are professionalizing mineral fortification as intensive pond systems replace extensive production.
- Swine:Phytase-supplemented diets reduce phosphate inclusion rates in European operations facing manure phosphorus caps.
- Ruminants:Beef and dairy operations use lower-inclusion mineral premixes with slower turnover than monogastric species.
- Pet Food:Premium kibble and wet food formulations drive small-batch demand for certified-low-cadmium phosphate sources.
Poultry dominates tonnage; aquaculture shows the steepest expansion trajectory.
Application:
Formulation complexity and regulatory traceability obligations differentiate buyers.
- Compound Feed:Complete rations manufactured at industrial scale require consistent phosphorus assay for label compliance. German and Polish compounders subject phosphate suppliers to extended stability testing under EFSA's tightened maximum permitted levels.
- Premix:Concentrated mineral blends for on-farm dilution demand precise particle size distribution to prevent segregation during transport. Dutch premix specialists specify powder-form dicalcium phosphate with narrow granulometric bands.
- Concentrates:Protein-mineral blends for farm-level mixing serve smaller operations lacking full compound feed access.
- Feed Supplements:Free-choice mineral blocks and liquid drenches target pasture-based livestock systems.
Compound feed absorbs the largest share; premix is climbing the fastest as integrators internalize formulation control.
Procurement Channel:
Volume scale and supply security priorities determine channel selection.
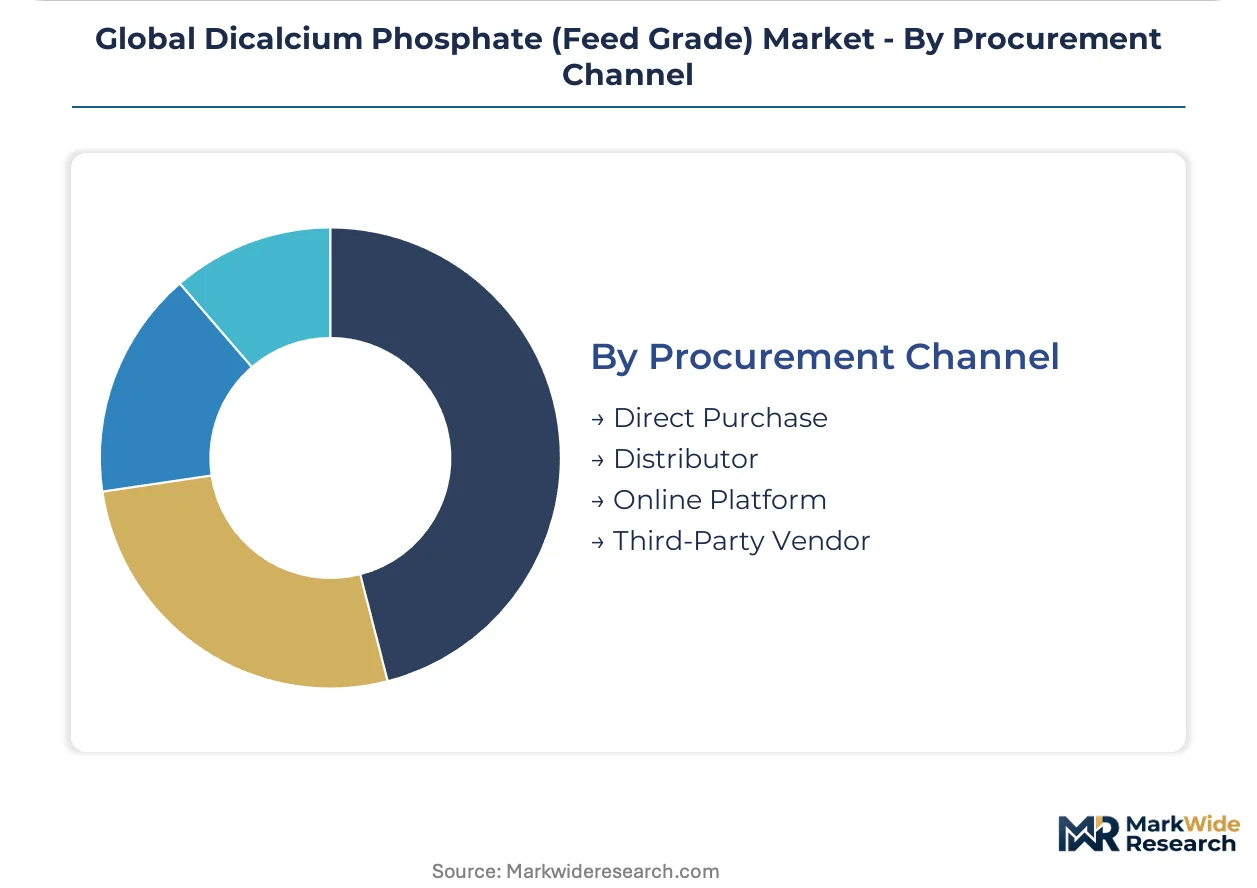
- Direct Purchase:Annual volume agreements between phosphate processors and protein integrators eliminate distributor margins. Thai poultry operators in the Eastern Economic Corridor now contract directly with sulfuric acid-integrated manufacturers.
- Distributor:Regional trading houses serve midscale compounders lacking procurement scale for processor-direct negotiations.
- Third-Party Vendor:Spot market purchases address emergency shortages or trial quantities for new formulation development.
- Online Platform:Digital procurement portals facilitate price discovery for small-volume buyers in fragmented markets.
Direct purchase commands the largest contract value; online platforms are expanding most quickly among emerging-market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's integrated poultry corridor anchors the most concentrated phosphate procurement cluster worldwide, where vertical feed milling operations negotiate directly with sulfuric acid-integrated processors. This Brazilian concentration exemplifies how supply security priorities are restructuring procurement geography across livestock-intensive regions.
United States
Chesapeake Bay watershed poultry integrators in Maryland and Delaware face EPA phosphorus discharge mandates that favor precision-formulated mineral supplements. The EPA's Chesapeake Bay Total Maximum Daily Load program enforces manure phosphorus caps that override purely nutritional rationing. Texas Panhandle cattle feedlots in Amarillo and Lubbock are retrofitting pneumatic handling systems for granule-form phosphate compatibility.
Brazil
Mato Grosso soybean-poultry integration creates captive demand for feed-grade phosphate as protein processors internalize feed milling capacity. The country's national agricultural regulator enforces traceability requirements for mineral additives under sanitary inspection protocols. São Paulo state processors in Campinas and Sorocaba account for the majority of direct-procurement contract volumes with phosphate manufacturers.
China
Guangdong and Fujian aquaculture intensification drives mineral fortification demand as shrimp pond systems professionalize feed management. The Ministry of Agriculture and Rural Affairs enforces GB standard compliance for imported feed phosphates with extended laboratory validation timelines. Yangtze River Delta premix compounders in Jiangsu province specify narrow granulometric bands for powder-form specifications.
Germany
Lower Saxony swine operations recalibrate mineral inclusion rates under EFSA's tightened maximum permitted phosphorus levels in complete feeds. The EFSA Feed Additives Regulation compresses allowable safety margins between nutritional minimums and environmental maximums. Bavarian compounders in Munich and Nuremberg subject phosphate suppliers to extended stability testing protocols for antibiotic-free production lines.
Indonesia
Java and Sulawesi shrimp feed producers lack established phosphate supplier relationships as intensive pond systems replace extensive production. The country's national feed regulatory agency enforces mineral additive registration requirements for imported products. Surabaya and Makassar processing clusters represent first-mover positioning opportunities for certified exporters with wet-process capabilities.
Global Dicalcium Phosphate (Feed Grade) Market Competitive Landscape
Backward integration into captive phosphate rock reserves dominates the current landscape as manufacturers secure ore supply security against Moroccan concentration risk. The vendor base stratifies between sulfuric acid-integrated processors with cost leadership and specialized wet-process engineering firms with formulation science capabilities. Three archetypes define competitive positioning: North American fertilizer conglomerates with captive Florida rock reserves, Moroccan state-backed producers with premium-grade ore dominance, and Russian manufacturers with sulfuric acid integration at production hubs. Capacity expansion and direct-procurement contracting represent the two dominant competitive moves reshaping procurement relationships.
Within the integrated fertilizer conglomerate tier, Nutrien and Mosaic exemplify North American producers leveraging captive mining assets for feed-grade output cost leadership. OCP anchors the state-backed producer archetype with Moroccan rock phosphate reserve dominance, while PhosAgro occupies a position within the sulfuric acid-integrated manufacturing tier at Russian production hubs. These three company groupings represent the structural concentration of wet-process engineering capabilities and ore supply security that defines procurement relationships with protein integrators.
| Leading Market Players |
|---|
| Nutrien |
| Mosaic |
| OCP |
| PhosAgro |
| Innophos |
| Ecophos |
| EuroChem Group |
| PotashCorp |
| Baotou Dongbao Bio-Tech |
| Others |
Supply & Pricing Matrix
Sulfuric acid integration at Moroccan and Russian production hubs cascades through contract pricing tiers as captive ore reserves anchor cost leadership against spot-market exposed processors. Brazilian poultry integrators leverage direct-procurement volume commitments to compress distributor margins, while Southeast Asian compounders absorb freight premiums for certified wet-process material.
Pricing Analysis
Input-cost pass-through from phosphoric acid reactor operations determines processor margin structures across the feed phosphate complex. Three-tier pricing stratifies across sulfuric acid-integrated premium, standard wet-process, and spot-market economy levels. EFSA's tightened maximum permitted phosphorus levels in complete feeds compress allowable safety margins, intensifying cost pressure on non-integrated facilities. Small-to-midscale compounders in Indonesia and Vietnam exhibit highest price sensitivity due to manual bag-breaking operations and limited pneumatic infrastructure, whereas Brazilian vertical integrators prioritize batch certification consistency over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification feed phosphate batches remain underdeveloped, with most processors landfilling rejected material rather than reprocessing through wet-process reactors. Geographic supply concentrates in Morocco, Russia, and the United States as OCP, PhosAgro, and Mosaic control captive phosphate rock reserves. Production draws from sulfuric acid, calcium carbonate, and premium-grade ore inputs. Single-source vulnerability to Moroccan rock phosphate concentration threatens wet-process manufacturers lacking captive mining assets. Distribution runs through direct-procurement annual volume agreements between processors and protein integrators, displacing traditional regional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as shrimp and finfish diet formulators shift toward certified-low-cadmium phosphate sources with documented batch traceability. Premium specification demand from antibiotic-free poultry operations in Europe and Brazil rewards processors with extended stability testing capabilities.
For Market Incumbents: Extend backward integration into captive sulfuric acid production to defend margin position against Moroccan ore concentration risk. Mosaic and Nutrien exemplify this archetype through Florida phosphate rock reserve control. Lock in direct-procurement contracts with Brazilian integrators in São Paulo and Mato Grosso before regional trading houses consolidate remaining spot volumes. Certification investment for EFSA and FDA compliance represents the critical defensive lever as traceability mandates tighten. For New Entrants and Emerging Players: Capture first-mover positioning in Indonesia's Java and Sulawesi shrimp feed corridors where established phosphate supplier relationships remain absent. Surabaya and Makassar processing clusters lack wet-process engineering expertise concentrated at legacy production sites. Target aquaculture mineral fortification intensity as the most penetrable application segment, leveraging GB standard certification timelines as a barrier against established competitors. A technical sales approach emphasizing pond-based feed management protocol integration offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for sulfuric acid-integrated mid-cap specialists because Moroccan rock phosphate concentration creates persistent supply security premiums for captive reserve holders. The five-to-ten year viability window favors processors with wet-process engineering capabilities and direct-procurement contract portfolios. Acquisition target archetype: Brazilian or Southeast Asian regional manufacturers with distributor relationships convertible to processor-direct structures. Watch EPA phosphorus discharge limit expansion beyond Chesapeake Bay and Great Lakes watersheds as the signal for precision-formulated mineral supplement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid Production | Captive acid supply insulates Mosaic and PhosAgro from sulfur market volatility. |
| Direct-Procurement Contracting with Protein Integrators | Brazilian poultry operators in São Paulo bypass distributors to lock volume commitments. |
| EFSA and FDA Certification Investment | Extended stability testing protocols qualify suppliers for antibiotic-free production lines. |
| Granule-Form Particle Engineering for Pneumatic Systems | Texas Panhandle cattle feedlots retrofit handling lines for automated bulk compatibility. |
| Indonesia Aquaculture Market Entry | Java and Sulawesi shrimp producers lack established phosphate supplier relationships. |
Research Methodology
Bottom-up aquaculture and poultry feed modeling reconciled against top-down phosphate processor capacity tracking forms the analytical core of this study. Primary interviews with feed mill procurement managers, wet-process plant engineers, regulatory compliance officers at EFSA and FDA, and shrimp farm operations directors in Southeast Asia combined with secondary validation from customs trade data, SEC 10-K filings, and EU Feed Additives Regulation documentation. Triangulation between demand-side consumption patterns and supply-side production economics ensures cross-verified volume estimates.
Input-output matrix framing connects sulfuric acid reactor utilization rates, calcium carbonate sourcing costs, and protein integrator feed formulation specifications to generate segment-level projections across the analysis window. Segmentation dimensions modeled include product form, animal type, application, and procurement channel with regional production hub overlays. CAGRs derive from reconciled bottom-up demand build and top-down capacity expansion tracking, with phosphorus bioavailability standards and environmental discharge regulations as key forecast sensitivity inputs.
Regulatory revision, Moroccan ore supply disruption, and monocalcium phosphate substitution acceleration are the dominant revision risks to base case projections. Forecasts reflect documented assumptions regarding EFSA maximum permitted level enforcement timelines and Brazilian vertical integration pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Impact Modifier Market
Additives
United Kingdom Feed Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
LAMEA Driveline Additives Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Binding Agents Market
Additives
Organic Dispersants Market
Additives
Tackifier Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Global Pour Point Depressant Market
Additives
Monocalcium Phosphate Market
Additives
Green Polymer Additive Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Ruminant Feed Additive Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Lubricating Oil Additives Market