
 Organic Dispersants Market | 2026-2036
Organic Dispersants Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dispersants Market Analytics
Specialty coatings formulators is rotating share from commodity paint producers as architectural and automotive refinishing specifications tighten. BASF SE leverages its integrated pigment-dispersant platform to anchor supply relationships with European industrial coatings compounders. Arkema Group differentiates through high-performance polymeric dispersant architectures designed for waterborne UV-curable systems. Clariant AG sustains position in agrochemical suspension concentrates where particle stabilization demands exceed standard surfactant performance.
Organic dispersants are surface-active compounds, typically polymeric or oligomeric in structure with molecular weights ranging from 1,000 to 30,000 g/mol, engineered to adsorb at solid-liquid or liquid-liquid interfaces and reduce interfacial tension to prevent particle aggregation or phase separation. Their primary industrial purpose centers on stabilizing pigments, fillers, and active ingredients within continuous phases to maintain uniform distribution, color strength, and functional performance throughout manufacturing, storage, and end-use application. Water-based formulations lead volume consumption as environmental compliance redirects solvent-borne capacity, while emulsion-type dispersants capture expanding margin pools in pharmaceutical nanosuspension applications. Powder formats retain niche dominance in plastics masterbatch production where moisture sensitivity and transportation economics favor solid delivery systems.
EPA regulations on volatile organic compound emissions under the Clean Air Act reshape product development priorities for solvent-based dispersant suppliers serving North American coatings manufacturers. REACH registration requirements and the EU Green Deal chemical sustainability criteria compel reformulation investments across European supply chains, with ECHA substance evaluation driving substitution timelines for persistent or bioaccumulative chemistries. Stakeholders must monitor regulatory divergence between jurisdictions where compliance costs fragment competitive positioning and determine whether regional product variants or unified global platforms deliver superior returns.
Market Dynamics
Waterborne formulation mandates across major industrial coatings jurisdictions are compressing solvent-borne dispersant capacity while concentrating procurement among formulators with compliant technical service capabilities. This regulatory pivot favors suppliers with integrated pigment-dispersant platforms and regional regulatory affairs infrastructure.
Growth Catalysts
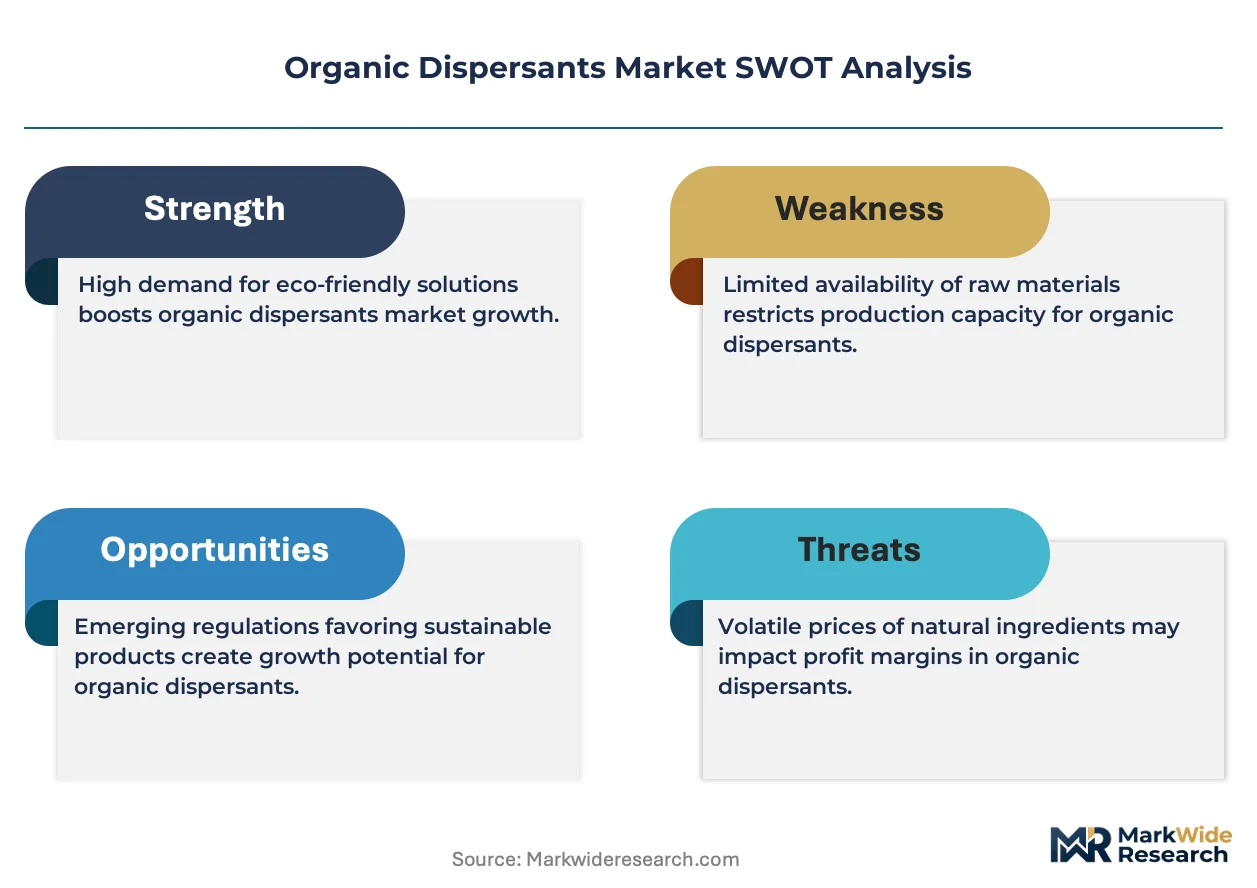
- EPA Clean Air Act VOC limits:North American architectural coatings manufacturers accelerate water-based system conversions, expanding demand for compatible polymeric dispersant architectures.
- Agrochemical suspension concentrate growth:Precision agriculture adoption in Brazil and India drives particle stabilization requirements beyond standard surfactant performance thresholds.
- UV-curable waterborne coatings:Automotive refinishing specifications in Germany and Japan incorporate these systems, requiring dispersants with dual photoinitiator compatibility and hydrolytic stability.
Market Restraints
- Ethylene oxide derivative feedstock volatility:Polyether backbone raw materials expose dispersant producers to petrochemical price swings and supply allocation disruptions.
- Specialty polymeric dispersant supply concentration:Controlled radical polymerization capacity clusters among integrated European and Japanese chemical conglomerates, limiting second-source options.
- REACH substance evaluation timelines:ECHA persistent and bioaccumulative chemistry reviews force reformulation investments before revenue recovery from substituted product lines.
Strategic Opportunities
- Pharmaceutical nanosuspension applications:Injectable drug delivery systems require emulsion-type dispersants with narrow particle size distribution control and biocompatibility certification pathways.
- China GB standard enforcement:SAMR industrial chemical safety mandates accelerate substitution toward compliant organic dispersant systems in domestic coatings production.
- Bio-based dispersant feedstocks:EU Green Deal chemical sustainability criteria create preferential procurement status for dispersants with certified renewable carbon content.
Industry Challenges
- Regulatory affairs specialist scarcity:Multi-jurisdiction substance registration expertise concentrates among senior professionals, constraining mid-tier supplier expansion timelines.
- Legacy solvent-borne equipment stranded asset risk:Coatings manufacturers face write-downs on mixing and grinding infrastructure incompatible with water-based dispersant rheology profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dispersants Market |
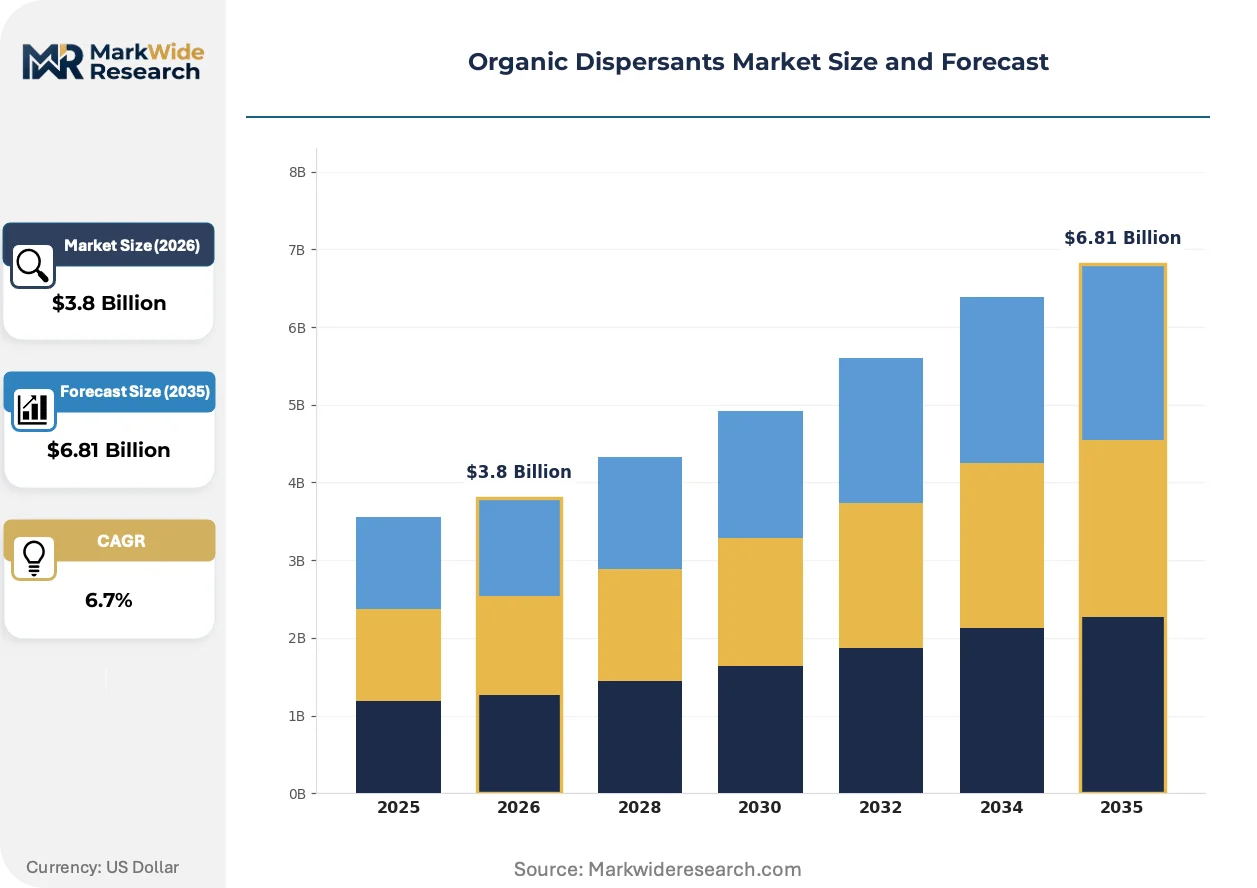
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder, Emulsion End Use Industry: Paint & Coatings, Plastics, Pharmaceuticals, Agrochemicals Formulation Type: Single Component, Multi-Component, Concentrated, Ready-to-Use Application Method: Spray, Brush, Roller, Dip |
| Companies Covered | BASF SE, Clariant AG, Arkema Group, Evonik Industries, Ashland Inc., The Lubrizol Corporation, The Dow Chemical Company, Air Products & Chemicals Inc., Altana AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dispersants Market Evolving Landscape
Polymeric dispersant molecular architecture is evolving toward block-copolymer designs that simultaneously anchor to pigment surfaces and provide steric stabilization in polar continuous phases. This shift compresses the performance gap between commodity and specialty grades.
Hyperbranched polyester dispersant technology is supplanting linear polyacrylate architectures in high-performance industrial coatings. European automotive OEM clearcoat specifications now incorporate these structures for improved metallic flake orientation. The technology is compressing margin pools for conventional dispersant suppliers lacking controlled branching synthesis capabilities.
REACH registration requirements and EU Green Deal chemical sustainability criteria are compelling reformulation investments across European supply chains. ECHA substance evaluation protocols now drive substitution timelines for persistent or bioaccumulative chemistries. Agrochemical suspension concentrate formulators face compressed product registration windows as regulatory data requirements expand.
Coatings manufacturers now consolidate dispersant procurement through integrated pigment-dispersant platform suppliers rather than sourcing components separately. This bundling pattern displaces independent dispersant distributors in North American architectural coatings channels. German and Japanese industrial coatings compounders exhibit the most concentrated procurement consolidation behavior.
Organic Dispersants Market Segmentation
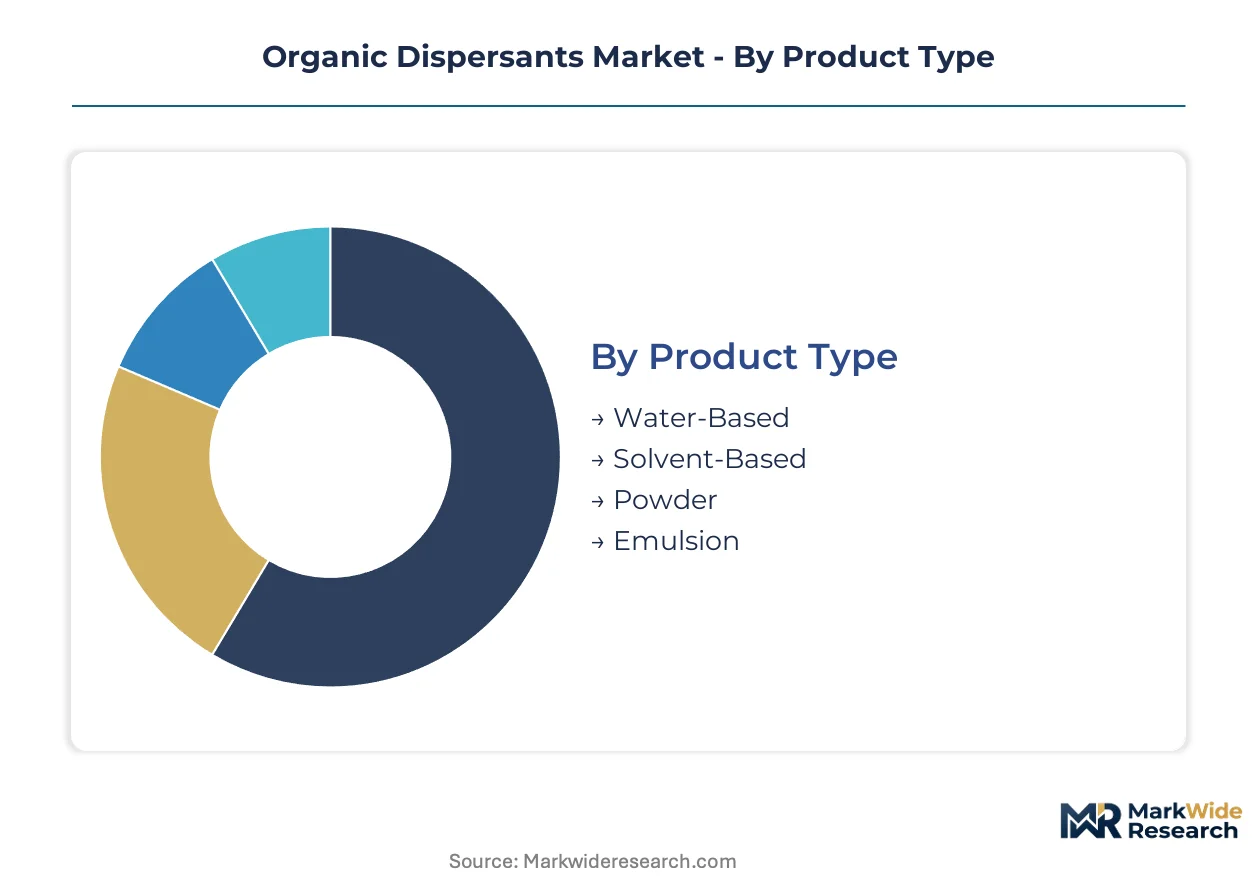
Segmentation in organic dispersants reveals how formulation chemistry and delivery format determine channel access. Procurement patterns diverge sharply between industrial compounders seeking integrated pigment-dispersant platforms and specialty formulators requiring application-specific stabilization architectures.
Product Type:
Channel mix varies by physical state: liquid formats flow through coatings distributors with technical service capabilities, while powder grades move through plastics masterbatch compounders with dry handling infrastructure.
- Water-Based:Polymeric architectures engineered for polar continuous phases anchor supply relationships with architectural coatings manufacturers converting solvent-borne capacity. EPA Clean Air Act VOC enforcement and REACH compliance timelines in Germany and France accelerate procurement concentration among formulators with compliant technical service capabilities.
- Solvent-Based:Hydrocarbon-compatible dispersant chemistries retain niche dominance in automotive refinishing clearcoats where drying speed and substrate wetting specifications exceed waterborne performance thresholds. Stranded asset risk on legacy mixing infrastructure constrains conversion timelines among North American job-shop refinishers.
- Powder:Solid delivery systems serve plastics masterbatch production in China and India where moisture sensitivity and transportation economics favor dry formats.
- Emulsion:Injectable-grade emulsion dispersants with narrow particle size distribution control access pharmaceutical nanosuspension channels requiring biocompatibility certification pathways.
Water-based formulations dominate installed base. Emulsion-type architectures are where expansion concentrates.
End Use Industry:
Application requirements dictate margin structure: coatings demand integrated pigment-dispersant platforms, while agrochemicals require particle stabilization beyond standard surfactant performance.
- Paint & Coatings:Architectural and automotive refinishing specifications drive procurement consolidation through integrated platform suppliers. German and Japanese industrial coatings compounders exhibit the most concentrated bundling behavior, displacing independent distributors.
- Agrochemicals:Suspension concentrate formulators in Brazil and India face compressed product registration windows as regulatory data requirements expand, concentrating demand among suppliers with established regulatory affairs infrastructure.
- Plastics:Masterbatch production favors powder dispersant formats with dry handling compatibility and thermal stability during extrusion processing.
- Pharmaceuticals:Injectable drug delivery systems require emulsion-type dispersants with biocompatibility certification and narrow particle size distribution control.
Paint and coatings commands revenue concentration. Pharmaceuticals is climbing the fastest on margin expansion.
Formulation Type:
Customer scale determines format preference: large compounders source concentrated intermediates for in-house dilution, while smaller formulators purchase ready-to-use systems to avoid capital investment in blending infrastructure.
- Single Component:Pre-optimized dispersant-pigment systems streamline procurement for mid-tier coatings manufacturers lacking formulation expertise. Brazilian and Indian agrochemical formulators favor these formats to accelerate product registration timelines.
- Multi-Component:Separated stabilizer and wetting agent packages allow custom ratio adjustment for specialty industrial coatings with unique substrate or climate requirements.
- Concentrated:High-active-content dispersants reduce transportation costs for large-volume coatings compounders with in-house let-down capabilities.
- Ready-to-Use:Diluted dispersant systems target small-batch formulators and job-shop refinishers seeking to minimize inventory complexity and mixing equipment investment.
Concentrated formats dominate volume throughput. Ready-to-use systems are gaining share fastest among small-batch specialists.
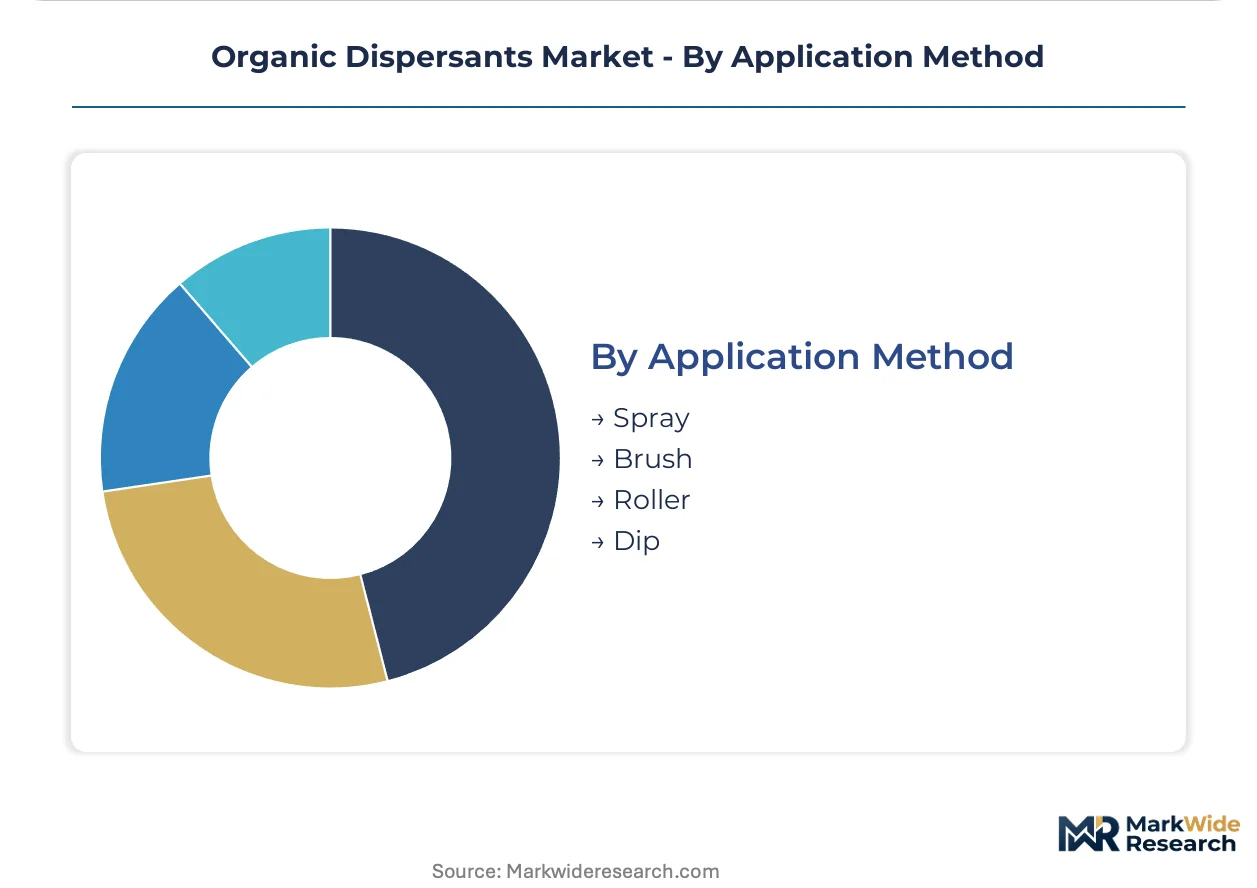
Application Method:
Spray applications demand low-viscosity dispersant rheology profiles incompatible with legacy solvent-borne equipment, while brush and roller tolerates higher viscosity ranges.
- Spray:Low-viscosity waterborne dispersant systems serve automotive OEM and refinish applications where transfer efficiency and film build specifications require precise atomization control.
- Brush:Higher viscosity tolerance accommodates thicker dispersant architectures in maintenance coatings and DIY architectural segments.
- Roller:Intermediate viscosity profiles balance sag resistance and flow-out in residential and commercial architectural applications.
- Dip:Immersion coating systems for industrial components require dispersants with exceptional bath stability and foam control during agitated dipping cycles.
Spray applications anchor premium pricing. Dip coating is where technology investment concentrates for industrial component protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architectural coatings manufacturers in China, Germany, and the United States drive procurement concentration through integrated pigment-dispersant platform requirements. Regulatory enforcement timelines in these markets compress supplier qualification windows and favor incumbents with established compliance infrastructure.
China
Domestic coatings production concentrates procurement among formulators with SAMR-certified GB standard compliance. The country's dual carbon goals accelerate waterborne system conversions in Yangtze River Delta manufacturing clusters. Shanghai and Jiangsu province industrial parks host the densest agrochemical suspension concentrate formulation capacity.
Germany
Automotive OEM clearcoat specifications in Stuttgart and Munich manufacturing corridors demand hyperbranched polyester dispersant architectures. ECHA substance evaluation protocols under REACH force reformulation investments before revenue recovery from substituted chemistries. Bavarian industrial coatings compounders exhibit the most concentrated procurement bundling behavior in Europe.
United States
EPA Clean Air Act VOC limits compress solvent-borne dispersant capacity while expanding water-based system procurement among architectural coatings manufacturers. The Gulf Coast petrochemical corridor supplies polyether backbone raw materials, exposing dispersant producers to ethylene oxide derivative price volatility. Midwestern automotive refinish job-shops face stranded asset risk on legacy mixing infrastructure.
Brazil
Precision agriculture adoption in São Paulo and Mato Grosso drives suspension concentrate particle stabilization requirements beyond standard surfactant performance. ANVISA registration data requirements compress product approval timelines for agrochemical formulators. The country's national chemical safety regulator enforces industrial chemical handling standards that accelerate substitution toward compliant dispersant systems.
Japan
Automotive refinishing specifications in Nagoya and Osaka industrial corridors incorporate UV-curable waterborne systems requiring dual photoinitiator compatibility. METI industrial standards guide reformulation investments toward low-VOC architectures. Chubu region coatings compounders consolidate procurement through integrated platform suppliers with established JIS certification pathways.
Organic Dispersants Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive pigment-dispersant platforms and specialized polymeric dispersant architects. Market structure concentrates among European and Japanese conglomerates controlling controlled radical polymerization capacity. Two strategic archetypes dominate: integrated pigment-dispersant platform suppliers anchoring supply relationships, and high-performance polymeric dispersant specialists capturing margin pools in waterborne UV-curable systems. Competitive moves center on regulatory affairs infrastructure expansion and bio-based feedstock certification pathways.
Among European-based integrated suppliers, BASF SE and Clariant AG occupy positions anchoring supply relationships with industrial coatings compounders through compliant technical service capabilities. Arkema Group exemplifies the high-performance specialist archetype, with its S.A. structure indicating French corporate origins and positioning within waterborne UV-curable system architectures.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Arkema Group |
| Evonik Industries |
| Ashland Inc. |
| The Lubrizol Corporation |
| The Dow Chemical Company |
| Air Products & Chemicals Inc. |
| Altana AG |
| Others |
Value Network & Pricing Analysis
REACH registration requirements and ECHA substance evaluation protocols gate supply qualification while simultaneously stratifying price tiers across compliant and non-compliant chemistries. Buyers face dual certification burdens that compress procurement pools to integrated suppliers commanding premium positioning.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide derivative benchmarks dominate raw material pass-through arrangements between polyether backbone suppliers and dispersant manufacturers. Three-tier pricing structure across pharmaceutical-grade, industrial coatings-grade, and commodity masterbatch-grade separates certified biocompatible emulsions from standard waterborne architectures. Pricing pressure stems from stranded solvent-borne capacity write-downs forcing distressed sales among job-shop refinishers. Small-batch formulators exhibit highest price sensitivity due to limited volume leverage, while pharmaceutical nanosuspension buyers prioritize certification over cost.
Supply Chain Analysis
Port congestion on Asia-Europe container routes elevates inbound logistics costs for polyether polyol feedstocks originating from South Korean and Singaporean petrochemical hubs. Manufacturing concentration clusters in Germany, China, and Japan where controlled radical polymerization capacity anchors specialty dispersant production. Raw material dependencies draw from ethylene oxide derivatives, acrylic acid monomers, and hyperbranched polyester intermediates. Single-source vulnerability concentrates around European controlled polymerization reactor assets. Distribution runs through integrated pigment-dispersant platform suppliers displacing independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Japanese industrial coatings compounders bundling procurement through integrated platform suppliers, fragmenting options for independent dispersant distributors.
For Market Incumbents: Consolidate regulatory affairs infrastructure across multiple jurisdictions to compress supplier qualification timelines for agrochemical and pharmaceutical formulators. Deepen backward integration into ethylene oxide derivative supply through captive polyether production or long-term offtake arrangements with Gulf Coast petrochemical operators. Arkema Group's specialist positioning in UV-curable architectures demonstrates how high-performance differentiation defends margin pools against commodity substitution. For New Entrants and Emerging Players: Lead with bio-based feedstock certification pathways targeting EU Green Deal preferential procurement criteria in European architectural coatings channels. Brazilian agrochemical suspension concentrate formulation offers the most penetrable white-space given compressed ANVISA registration timelines favoring suppliers with established regulatory data packages. Partner with regional masterbatch compounders in India and China for powder format distribution without capital-intensive liquid handling infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade emulsion dispersant manufacturing due to biocompatibility certification infrastructure requirements. Target acquisition archetypes include mid-tier European polymeric dispersant architects with REACH-compliant product portfolios and established ECHA regulatory relationships. Watch for inflection signals in SAMR enforcement intensity across Yangtze River Delta manufacturing clusters indicating accelerated substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Feedstocks | Gulf Coast ethylene oxide derivative supply anchors cost stability for waterborne dispersant architectures. |
| Pharmaceutical Biocompatibility Certification | Injectable-grade emulsion dispersants access premium nanosuspension channels with narrow particle size specifications. |
| Regional Regulatory Affairs Expansion | SAMR, ECHA, and EPA compliance infrastructure compresses qualification windows for integrated platform suppliers. |
| Bio-Based Feedstock Certification | EU Green Deal renewable carbon criteria creates preferential procurement status in European architectural coatings. |
| Controlled Radical Polymerization Capacity Addition | Hyperbranched polyester synthesis capabilities capture automotive OEM clearcoat specifications in Stuttgart and Munich corridors. |
Research Methodology
A standing panel of coatings formulators, agrochemical suspension concentrate technical directors, pharmaceutical nanosuspension development leads, and plastics masterbatch procurement managers provided ongoing calibration across primary interview rounds. Secondary validation drew from ECHA substance evaluation databases, EPA Clean Air Act enforcement records, SAMR GB standard filings, and SEC 10-K disclosures from integrated chemical conglomerates. Bottom-up volume modeling across product type, end-use industry, and formulation format segments triangulated against top-down value estimates from trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include physical state, application chemistry, customer scale, and regional regulatory cluster. CAGRs derived from regression analysis of historical consumption patterns and forward-looking substitution timelines. Industry-specific inputs incorporated REACH registration completion schedules, SAMR enforcement intensity trajectories, and precision agriculture adoption curves in Brazil and India.
Underlying assumptions cover sustained EPA VOC limit enforcement, ECHA persistent chemistry evaluation timelines, and SAMR GB standard compliance acceleration, with deviation risk concentrated in ethylene oxide derivative price volatility and regulatory divergence between jurisdictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Supplemental Coolant Additives Market
Additives
Glycol Acetate Market
Additives
Plasticizers Market
Additives
Anti-Slip Additives Market
Additives
Global Scale Inhibitors Market
Additives
Europe Choline Chloride Market
Additives
Impact Modifier Market
Additives
Global PVC Additives Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Sorbitan Laurate Market
Additives
Competitive Inhibitors Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Indonesia Feed Additives Market
Additives
Nucleotide Premix Market
Additives
Micronized Powder Market