
 Plastic Medicine Spoons Market | 2026-2036
Plastic Medicine Spoons Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Medicine Spoons Market Analytics
Custom dosing service layers is shifting how plastic medicine spoons move through pharmaceutical supply chains, bundling calibrated spoons with liquid drug protocols rather than selling standalone units. Comar leverages backward integration into medical-grade resin compounding to secure material consistency across North American hospital networks. Stiplastics Healthcaring anchors European demand through ISO 13485-certified cleanroom production in France. Medi-Dose Group dominates institutional procurement channels in the United States through direct sales relationships with integrated health systems.
Plastic medicine spoons are single-use or limited-use dosing devices molded from polypropylene, polyethylene, or BPA-free polymers, typically graduated in milliliters or teaspoons to ensure accurate oral liquid medication administration in clinical and home settings. Wall thickness, snap-fit durability, and chemical resistance to common pharmaceutical solvents determine functional performance during patient use. Angled spoons and mini spoons capture expanding share in pediatric and geriatric segments where swallowing geometry and reduced volume precision matter most, while straight spoons remain the mature default for standard adult dosing in high-volume hospital formularies. Polypropylene leads material selection for its autoclave tolerance and cost structure, though BPA-free plastics and recyclable plastics segments accelerate as European F-Gas Regulation pressures and US state-level plastic bans reshape procurement specifications.
FDA 21 CFR Part 820 quality system requirements and EMA medical device classification rules govern material biocompatibility and lot traceability for spoons classified as ancillary medicinal devices across major markets. India's CDSCO and China's NMPA impose parallel but non-harmonized testing protocols that fragment certification burdens for exporters. REACH substance restrictions and evolving EU Green Deal packaging mandates push converters toward post-consumer recycled content verification. Stakeholders must monitor whether pharmacovigilance regulators reclassify dosing spoons as standalone medical devices, which would trigger clinical evidence requirements and reshape competitive economics for molded-plastic suppliers.
Market Dynamics
Pharmacovigilance regulators across major economies are reclassifying dosing spoons from commodity packaging to ancillary medicinal devices, triggering material traceability mandates that reshape procurement specifications and supplier qualification protocols.
Growth Catalysts
- Pediatric dosing protocols:Liquid medication formulations for children require calibrated delivery devices, driving hospital formulary standardization on graduated spoons.
- EMA medical device classification:Tighter ancillary device rules force pharmaceutical packagers to source from ISO 13485-certified molders, consolidating qualified supplier pools.
- Contract manufacturing expansion:India and China scale pharmaceutical packaging capacity, creating captive demand for regionally produced dosing tools.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene and polyethylene feedstock prices fluctuate with crude oil indices, compressing converter margins on fixed-price hospital contracts.
- REACH substance restrictions:ECHA candidate list expansions limit plasticizer and additive options, forcing reformulation cycles that delay product launches.
- Reusable dosing alternatives:Oral syringes and smart pump systems capture share in institutional settings where precision trumps disposability economics.
Strategic Opportunities
- Post-consumer recycled content mandates:EU Green Deal packaging rules create first-mover advantage for converters verifying PCR plastic chains of custody.
- Geriatric mini-spoon formats:Japan's aging demographic drives demand for reduced-volume, angled-geometry devices that accommodate swallowing difficulties.
- Direct-to-patient pharmacy channels:Retail pharmacies bundle calibrated spoons with liquid prescriptions, bypassing traditional distributor markups.
Industry Challenges
- Lot traceability system integration:FDA 21 CFR Part 820 quality system requirements demand serialization infrastructure that small molders lack capital to deploy.
- Multi-jurisdiction certification timelines:India's CDSCO and China's NMPA impose non-harmonized biocompatibility testing, fragmenting approval pathways for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Medicine Spoons Market |
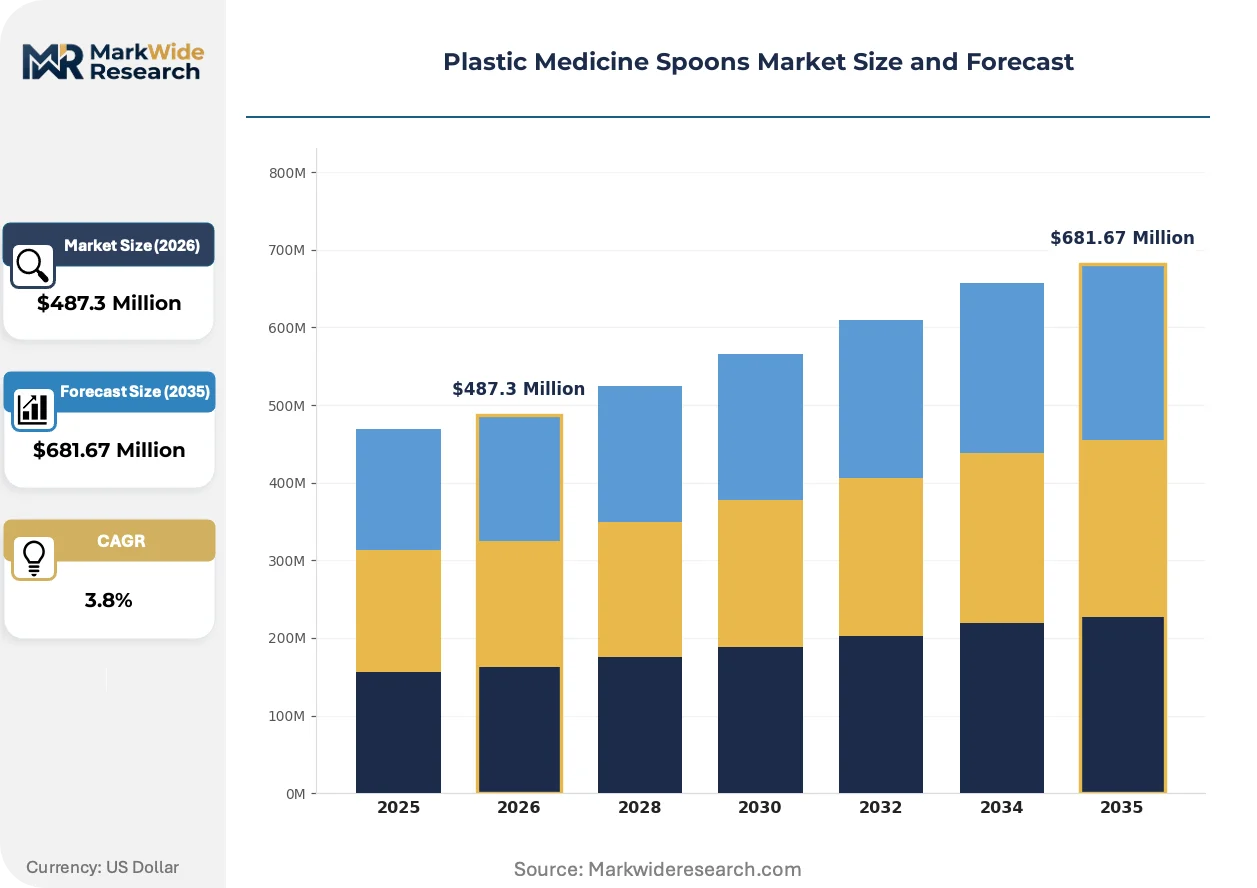
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Spoons, Angled Spoons, Mini Spoons, Large Spoons Material: Polypropylene, Polyethylene, BPA-Free Plastics, Recyclable Plastics End User: Hospitals, Pharmacies, Homecare, Nursing Facilities Distribution Channel: Online Retail, Direct Sales, Wholesale, Medical Supply Stores |
| Companies Covered | Comar, Stiplastics Healthcaring, Medi-Dose Group, Arpita Enterprises, Modern Plasmold, Falit Plastics Private Limited, Bormioli Pharma, Parekhplast India, Shako Plastick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Medicine Spoons Market Evolving Landscape
Material science advances and regulatory reclassification are converging to transform plastic medicine spoons from undifferentiated commodities into certified ancillary devices with verified supply chains and specialized geometries.
Biopolymer formulations derived from sugarcane ethanol and other renewable feedstocks are unifying sustainability credentials with autoclave tolerance. European hospital networks pilot these materials in pediatric wards where parental sensitivity to petroleum-based plastics runs highest. The shift is compressing the competitive set to converters with in-house polymer science capabilities.
REACH substance restrictions and evolving F-Gas Regulation pressures are forcing rapid reformulation of legacy polymer additives. Compounders must eliminate phthalate plasticizers and heavy-metal stabilizers while maintaining dimensional stability across sterilization cycles. Pediatric dosing applications face the tightest compliance windows as EMA pharmacovigilance rules tighten scrutiny of child-exposed materials.
Retail pharmacy chains are consolidating supplier relationships around bundled dosing device programs that attach calibrated spoons to liquid medication protocols. Hospital procurement teams resist this model, maintaining direct contracts with molded-plastic specialists for formulary standardization. The tension is most visible in the United States, where integrated health systems negotiate enterprise pricing while independent pharmacies seek turnkey compliance solutions.
Plastic Medicine Spoons Market Segmentation
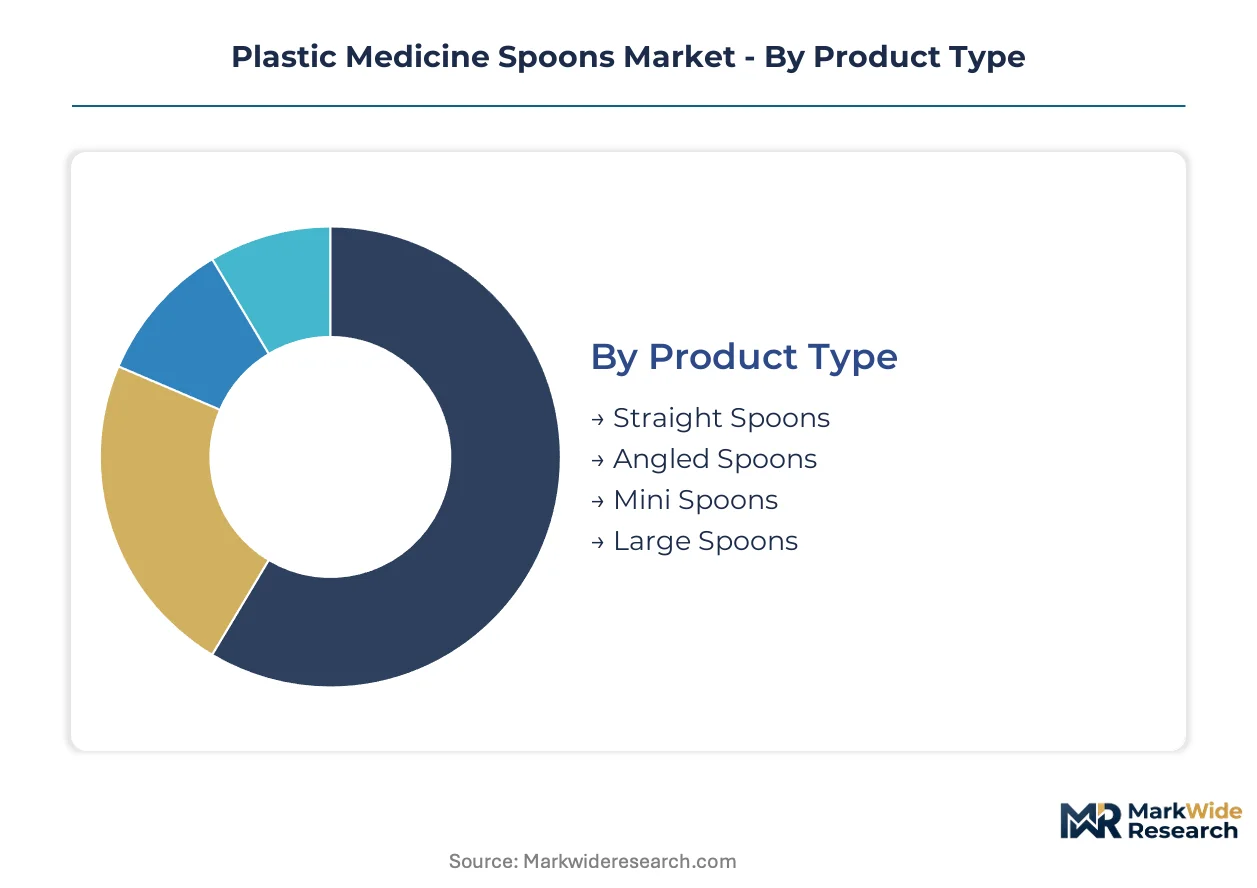
Product architecture in plastic medicine spoons responds to distinct dosing protocols across patient populations. Material specifications and channel configurations further stratify procurement patterns between institutional buyers and retail dispensers.
Product Type:
Upgrade cycles in pediatric and geriatric wards are displacing legacy straight-spoon inventories with geometry-optimized alternatives that reduce spillage and improve swallowing compliance.
- Straight Spoons:Standard cylindrical shafts with flat bowls dominate high-volume hospital formularies. Procurement concentrates in India and China where contract manufacturers supply integrated health systems under fixed-price multi-year agreements.
- Angled Spoons:Offset bowl geometry accommodates patients with limited neck mobility. Demand clusters in Japan's geriatric wards and European rehabilitation centers where swallowing-assist protocols mandate specialized device shapes.
- Mini Spoons:Reduced-volume bowls calibrated for precise pediatric dosing.
- Large Spoons:Expanded capacity for adult liquid formulations and nutritional supplements.
Straight spoons sit at the top of the volume ranking, with angled spoons climbing the fastest as aging demographics reshape ward equipment specifications.
Material:
Cost tiering separates commodity polypropylene from certified medical-grade alternatives that command procurement premiums in regulated markets.
- Polypropylene:Autoclave-tolerant homopolymer dominates institutional procurement for its sterilization cycle durability. CDSCO and NMPA certification requirements in India and China favor established compounders with documented biocompatibility testing.
- BPA-Free Plastics:Alternative polymer formulations eliminate bisphenol-A content for pediatric-sensitive applications. REACH substance restrictions and EMA pharmacovigilance rules are accelerating hospital network transitions in France and Germany.
- Polyethylene:Lower-density option for single-use disposable protocols.
- Recyclable Plastics:Post-consumer content verification aligns with EU Green Deal packaging mandates.
Polypropylene maintains the broadest installed base, though BPA-free alternatives are expanding most quickly as regulatory scrutiny tightens on child-exposed materials.
End User:
Application intensity varies sharply between acute care settings with standardized formularies and dispersed homecare environments with individual purchasing authority.
- Hospitals:Centralized procurement through materials management departments enforces formulary compliance. FDA 21 CFR Part 820 quality system requirements drive supplier consolidation toward ISO 13485-certified molders with serialization infrastructure.
- Pharmacies:Retail dispensers bundle calibrated spoons with liquid prescriptions. Direct-to-patient channels in the United States bypass traditional distributor markups through pharmacy chain consolidation.
- Homecare:Individual consumers purchase through retail and online channels.
- Nursing Facilities:Long-term care operators balance cost controls with regulatory compliance.
Hospitals command the largest procurement volumes, while pharmacies are gaining share fastest as bundled dosing device programs expand.
Distribution Channel:
Channel configuration determines margin capture between manufacturers and end users, with direct sales relationships yielding superior pricing control in institutional segments.
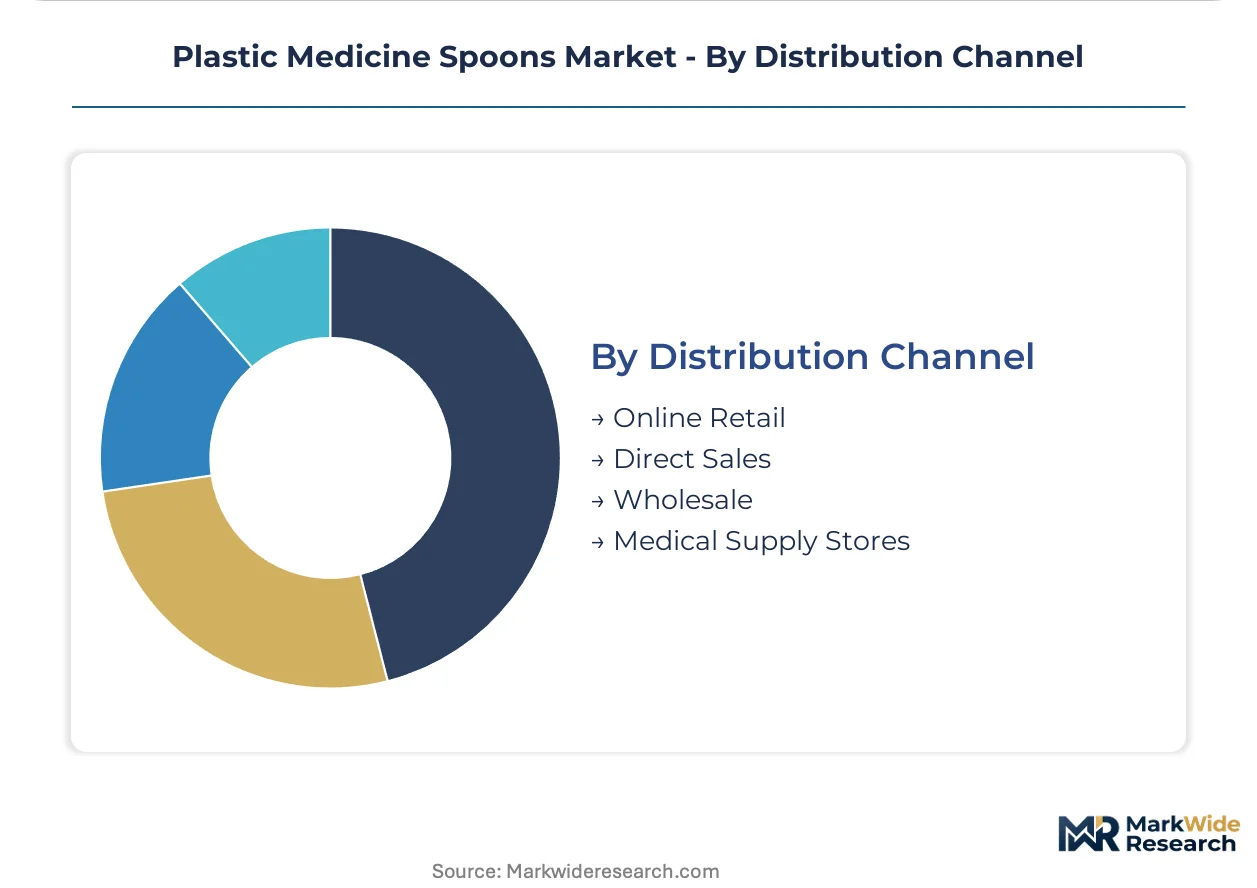
- Direct Sales:Manufacturer relationships with integrated health systems and pharmaceutical packagers eliminate intermediary costs. Medi-Dose Group and similar specialists dominate United States institutional procurement through enterprise pricing agreements.
- Wholesale:Medical supply distributors aggregate demand from fragmented nursing facilities and independent pharmacies. India's regional distributor networks channel volume to CDSCO-compliant converters.
- Online Retail:E-commerce platforms serve homecare and small-practice buyers.
- Medical Supply Stores:Physical retail points for immediate-need purchases.
Direct sales anchor the highest volume flows, with wholesale channels showing the steepest expansion trajectory as regional distributor networks deepen in Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India diverge in regulatory maturity despite shared contract manufacturing dominance, with China's NMPA enforcing stricter serialization mandates than India's CDSCO. Germany and Japan maintain premium-tier demand through aging-population protocols, while the United States consolidates procurement through integrated health systems.
United States
Pediatric dosing standardization and hospital formulary consolidation drive procurement volumes. FDA 21 CFR Part 820 quality system requirements force supplier consolidation toward ISO 13485-certified molders. Midwest integrated health systems negotiate enterprise pricing agreements directly with molded-plastic specialists.
Germany
Geriatric ward equipment upgrades and REACH substance restrictions accelerate BPA-free plastic transitions. EMA pharmacovigilance rules tighten scrutiny of ancillary medicinal devices. Bavarian hospital networks pilot biopolymer spoons in pediatric wards under EU Green Deal packaging pilots.
China
Pharmaceutical packaging capacity expansion creates captive demand for regionally produced dosing tools. NMPA medical device classification rules impose biocompatibility testing requirements that favor established compounders. Yangtze River Delta contract manufacturers scale medical-grade resin compounding operations.
India
CDSCO certification requirements and cost-competitive molding attract multinational pharmaceutical packagers. Regional distributor networks channel volume to compliant converters. Maharashtra and Gujarat pharmaceutical clusters drive domestic sourcing of calibrated dosing devices.
Japan
Aging demographics and swallowing-assist protocols generate demand for angled-geometry mini spoons. METI standards and PMDA oversight enforce material traceability in geriatric care settings. Kansai region rehabilitation centers standardize on specialized device shapes for long-term care.
Plastic Medicine Spoons Market Competitive Landscape
Top-tier vendors anchor institutional procurement channels, while mid-tier converters compete on CDSCO and NMPA certification speed. The vendor base stratifies across three archetypes: resin-integrated compounders with backward control over medical-grade polymer supply, ISO 13485-certified cleanroom specialists serving European hospital networks, and regional contract manufacturers leveraging pharmaceutical packaging proximity. Dominant competitive moves include captive resin compounding investments and direct sales relationship building with integrated health systems.
Within the resin-integrated tier, Comar exemplifies backward integration into medical-grade polymer compounding. Stiplastics Healthcaring occupies a position among European cleanroom production specialists. Medi-Dose Group anchors United States institutional procurement through direct health system relationships. These three represent distinct strategic archetypes: upstream material control, regulatory-certified manufacturing, and channel-integrated distribution.
| Leading Market Players |
|---|
| Comar |
| Stiplastics Healthcaring |
| Medi-Dose Group |
| Arpita Enterprises |
| Modern Plasmold |
| Falit Plastics Private Limited |
| Bormioli Pharma |
| Parekhplast India |
| Shako Plastick |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates gate qualified supply and premium-tier pricing access, forcing converters to verify post-consumer recycled content chains before hospital networks will award contracts. Pharmaceutical packagers now bundle certified spoons with liquid drug protocols, tightening procurement specifications and compressing margin structures for non-compliant molders.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard polypropylene spoons, forcing incumbent converters in North America and Europe toward ISO 13485-certified premium tiers. Three-tier pricing structure across premium certified, standard medical-grade, and economy contract-manufactured levels separates hospital formulary contracts from retail pharmacy bundles. Price differentiation hinges on lot traceability infrastructure and CDSCO/NMPA certification speed. Cost compression in economy tiers is intensifying because crude-linked resin volatility squeezes fixed-price hospital agreements. Retail pharmacy chains show highest price sensitivity, while integrated health systems prioritize compliance over unit cost.
Supply Chain Analysis
India's PLI scheme for pharmaceutical manufacturing and China's NMPA localization rules are reshaping sourcing, pushing multinational packagers toward regionally captive molding operations. Supply concentrates in Maharashtra and Gujarat pharmaceutical clusters, the Yangtze River Delta contract manufacturing belt, and Midwest US resin compounding facilities. Medical-grade polypropylene, polyethylene feedstock, and biopolymer formulations from sugarcane ethanol draw from petrochemical and agricultural processing streams. Single-source vulnerability runs through Yangtze River Delta molders serving global pharmaceutical accounts. Distribution runs through direct sales relationships with integrated health systems, wholesale medical supply distributors, and pharmacy chain consolidation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA pharmacovigilance reclassification of dosing spoons as ancillary medicinal devices triggers material traceability mandates that consolidate demand around certified suppliers.
For Market Incumbents: Extend backward integration into medical-grade resin compounding to secure material consistency against feedstock volatility, and deepen direct sales relationships with integrated health systems before pharmacy chain bundling captures patient-facing channels. Oral syringes and smart pump systems threaten share in precision-critical institutional settings. ISO 13485 certification investment remains the priority lever for European hospital network retention.
For New Entrants and Emerging Players: Biopolymer formulations derived from renewable feedstocks offer a technology-first wedge into pediatric-sensitive hospital wards where parental pressure drives petroleum-plastic displacement. Geriatric mini-spoon formats in Japan's aging demographic and BPA-free transitions in Germany's REACH-regulated markets represent the most penetrable white-space targets. Partner with retail pharmacy chains on bundled dosing device programs to bypass distributor markups and establish volume footholds.
For Investors and Strategic Acquirers: Roll-up economics work for ISO 13485-certified cleanroom specialists because EMA and FDA pharmacovigilance rules are consolidating qualified supplier pools faster than organic certification timelines permit. Five-to-ten year viability hinges on converters with in-house polymer science capabilities and serialization infrastructure. Target acquisition archetype: mid-cap molders with documented biocompatibility testing and hospital formulary relationships. Watch for NMPA reclassification signals that would trigger clinical evidence requirements and reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin Compounding | Comar's captive polymer science capabilities secure material consistency across North American hospital networks. |
| ISO 13485 Cleanroom Certification Investment | Stiplastics Healthcaring anchors European demand through regulatory-certified production in France. |
| Direct Sales Relationship Building with Integrated Health Systems | Medi-Dose Group dominates United States institutional procurement through enterprise pricing agreements. |
| Biopolymer Formulation Development | Bavarian hospital networks pilot sugarcane-derived spoons under EU Green Deal packaging pilots. |
| Retail Pharmacy Bundled Dosing Device Programs | United States pharmacy chain consolidation bypasses traditional distributor markups for turnkey compliance solutions. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pharmaceutical packaging executives, hospital procurement managers, regulatory affairs specialists, and medical device quality officers alongside secondary validation. FDA 21 CFR Part 820 filings, EMA medical device classification databases, CDSCO and NMPA submission records, and pharmaceutical customs trade data anchor quantitative triangulation. Bottom-up modeling of converter capacity and top-down demand estimation from liquid medication prescription volumes cross-validate volume outputs.
Granularity-level framing applies product type, material specification, end-user segment, and distribution channel dimensions at the country-regulator cluster level across the analysis window. CAGRs derive from regression-weighted historical trajectory analysis and scenario-adjusted elasticity modeling. Forecast inputs include pharmaceutical packaging capacity expansion timelines, REACH substance restriction phase-in schedules, and pediatric dosing protocol standardization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacovigilance reclassification decisions, resin feedstock volatility, and EU Green Deal packaging mandate enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Skin Tac Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Casting and Splints Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Medical Liners Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Global Enema Based Products Market