
 Global Absorbent Dressings Market | 2026-2036
Global Absorbent Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Absorbent Dressings Market Foresight
Advanced biopolymer engineering is rewriting how absorbent dressings manage exudate and moisture balance. Smith & Nephew leverages hydrofiber technology to sustain premium positioning in surgical wound applications. Medline Industries anchors volume production through extensive hospital supply contracts across North America. Molnlycke Health Care differentiates via silicone-adhesive interfaces that reduce trauma during dressing changes.
Absorbent dressings are multi-layer wound care materials—typically comprising hydrophilic fibers, superabsorbent polymers, or hydrocolloid matrices—engineered to capture exudate while maintaining a moist healing environment conducive to granulation tissue formation. Foam dressings dominate current volume due to their versatility across moderate-to-heavy exudate wounds and established reimbursement codes. Alginate dressings represent the fastest-expanding category as clinicians adopt them for infected or heavily draining wounds where hemostatic properties prove clinically valuable. Hydrocolloid and hydrogel segments occupy stable niche positions in partial-thickness wounds and donor sites where minimal disruption matters.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking market access. ISO 13485 quality management standards and biocompatibility testing under ISO 10993 further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving reimbursement thresholds for advanced dressings versus standard gauze as payors recalibrate value-based wound care protocols.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines as manufacturers rebuild clinical evidence portfolios for legacy wound care lines. This regulatory recalibration is redistributing competitive advantage toward firms with established biocompatibility databases and ISO 10993 testing infrastructure.
Growth Catalysts
- Chronic wound epidemiology:Aging demographics in Germany, Japan, and the United States are expanding the addressable patient pool for advanced moisture-management dressings. Hospital discharge protocols increasingly mandate moist wound healing standards.
- Biopolymer innovation:Superabsorbent polymer integration into alginate matrices is extending wear time and reducing dressing change frequency. Clinicians in surgical and burn units are adopting these hybrid formats for moderate-to-heavy exudate management.
- MDR transition:The EU Medical Device Regulation's stricter clinical evidence requirements are accelerating consolidation among manufacturers with robust quality management systems. This is concentrating contract awards toward ISO 13485-certified suppliers.
Market Restraints
- Raw material concentration:Superabsorbent polymer supply concentrates among petrochemical producers in the US Gulf Coast and Northeast Asia. Price volatility in acrylic acid derivatives directly compresses dressing margins.
- Technical limitation:Current hydrofiber technology struggles with simultaneous antimicrobial integration without compromising absorbency kinetics. Silver-ion loading above therapeutic thresholds degrades structural integrity during fluid uptake.
- Regulatory friction:FDA 510(k) clearance pathways for novel material combinations require predicate device matching that slows innovation cycles. Substantial equivalence determinations for biopolymer modifications face extended review timelines.
Strategic Opportunities
- Underpenetrated home care:Brazil's expanding private insurance networks and aging population create demand for self-administered advanced dressings. Local distributors lack technical training infrastructure to support product adoption.
- Technology convergence:Biosensor integration with absorbent substrates enables real-time exudate monitoring and infection signaling. Early pilots in German university hospitals demonstrate clinical workflow integration potential.
- Regulatory tailwind:Japan's PMDA has streamlined approval pathways for combination products incorporating drug-eluting layers. This accelerates market entry for antimicrobial-integrated dressing formats.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at accredited laboratories. Manufacturers report 6-9 month delays for complete test batteries.
- Legacy system integration:Hospital electronic health record platforms lack standardized wound documentation fields. Dressing performance data cannot flow into predictive analytics without custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Absorbent Dressings Market |
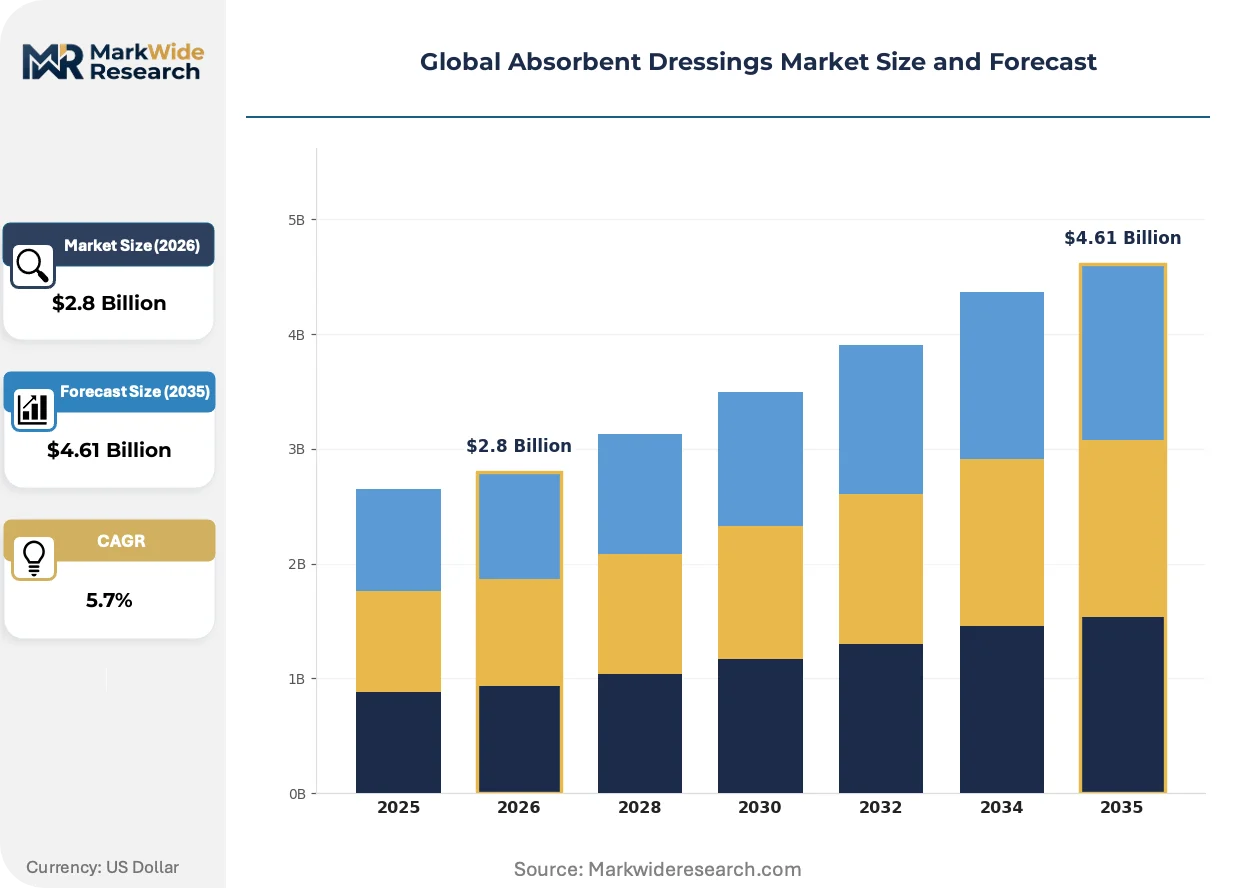
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Dressings, Alginate Dressings, Hydrocolloid Dressings, Hydrogel Dressings, Composite Dressings Therapy Area: Chronic Wounds, Surgical Wounds, Pressure Ulcers, Diabetic Foot Ulcers, Traumatic Injuries End User: Hospitals, Ambulatory Care Centers, Wound Care Clinics, Home Healthcare, Long-Term Care Facilities Application Type: Moisture Management, Infection Control, Exudate Absorption, Wound Protection, Tissue Repair |
| Companies Covered | 3M, Smith & Nephew, Medline Industries, ConvaTec, Molnlycke Health Care, Coloplast, Baxter, Johnson & Johnson Services, Hartmann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Absorbent Dressings Market Shifts & Advancements
Material science breakthroughs are collapsing the functional boundaries between passive absorbency and active therapeutic intervention. Three convergent developments are restructuring how wound care products capture value and clinical acceptance.
Electrospun nanofiber matrices functionalized with chitosan and hyaluronic acid are collapsing the distinction between mechanical exudate management and biological signaling. Burn centers in the United States and trauma units in South Korea are piloting these substrates for partial-thickness wound coverage where granulation acceleration matters. The technology is compressing SKU proliferation by consolidating moisture balance, hemostasis, and biocompatibility into single-layer formats.
REACH restrictions on persistent organic pollutants are forcing reformulation of silicone adhesives and polymer backings used in occlusive dressing designs. The European Chemicals Agency's 2023 updates to substance authorization lists have triggered raw material substitution programs across wound care manufacturers. German and French suppliers are accelerating bio-based adhesive development to preempt supply discontinuation risks.
Hospital purchasing cooperatives are consolidating vendor panels and demanding outcome documentation for advanced dressing categories. Group purchasing organizations in the United States now require peer-reviewed evidence of reduced dressing change frequency or healing acceleration versus standard gauze. This behavioral shift is marginalizing manufacturers lacking clinical trial infrastructure and favoring suppliers with dedicated health economics teams.
Global Absorbent Dressings Market Segmentation
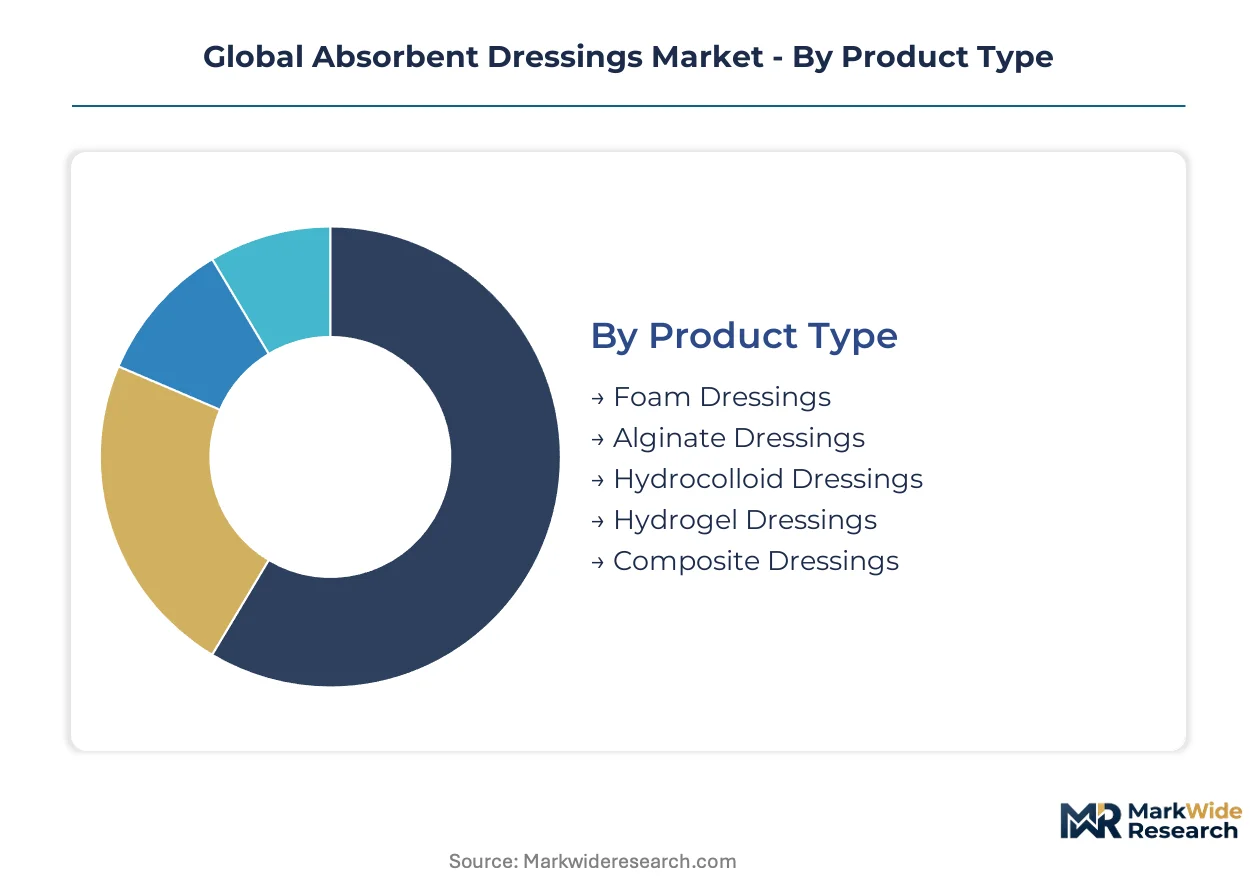
Segmentation in absorbent dressings reveals how material properties, clinical settings, and wound etiology intersect to determine product selection. Manufacturers configure portfolio breadth across these dimensions to capture volume in high-turnover hospital segments while building margin in specialized therapeutic niches.
Product Type:
Foam, alginate, hydrocolloid, hydrogel, and composite formats span a use-case spectrum from routine postoperative coverage to complex exudate management in infected wounds.
- Foam Dressings:Multi-layer polyurethane or silicone-faced constructions manage moderate-to-heavy exudate across diverse wound bed conditions. Demand concentrates in United States hospital surgical units where established reimbursement codes and nursing familiarity sustain high-volume procurement. Medicare's outpatient wound management expansion reinforces this positioning.
- Alginate Dressings:Calcium or sodium alginate fibers derived from brown seaweed form gel matrices upon contact with wound fluid, delivering hemostatic and absorbent properties simultaneously. German and Japanese burn centers are adopting these formats for heavily draining wounds where infection control protocols demand frequent assessment. Clinicians value the clean one-piece removal that minimizes trauma.
- Hydrocolloid Dressings:Gelatin, pectin, and carboxymethylcellulose matrices adhere to intact skin surrounding partial-thickness wounds.
- Hydrogel Dressings:Cross-linked polymer networks donate moisture to dry wound beds and facilitate autolytic debridement.
- Composite Dressings:Multi-function laminates combine absorbent layers with adhesive borders and bacterial barriers in single units.
Established volume favors foam formats; emerging adoption favors alginate variants in infection-prone applications.
Therapy Area:
Wound etiology determines dressing performance requirements, reimbursement pathways, and care setting economics across chronic, surgical, and acute traumatic indications.
- Chronic Wounds:Venous leg ulcers, arterial insufficiency ulcers, and pressure injuries demand sustained moisture balance over extended healing timelines. United States long-term care facilities and home health agencies concentrate procurement for aging patient populations with comorbid diabetes and vascular disease. CMS reimbursement incentives for healing outcomes are reshaping product selection criteria.
- Surgical Wounds:Incisional and excisional wound management requires predictable absorbency profiles aligned with closure techniques and drainage tube configurations. Japanese and South Korean hospital systems prioritize low-adherence interfaces that preserve suture lines during dressing changes. Postoperative length-of-stay reduction targets amplify demand for extended-wear formats.
- Pressure Ulcers:Device-related and position-related tissue injuries in immobilized patients require redistribution surfaces combined with appropriate dressings.
- Diabetic Foot Ulcers:Neuropathic wounds with high amputation risk demand offloading integration with moisture management.
- Traumatic Injuries:Abrasions, lacerations, and burns in emergency settings require rapid application and hemostatic support.
Surgical applications anchor current revenue; chronic wound management is climbing the fastest as population aging deepens addressable prevalence.
End User:
Care setting determines product form factor, packaging configuration, and support service requirements from acute inpatient through community-based delivery.
- Hospitals:Central supply and operating room procurement drives standardized formulary decisions across high-volume surgical, emergency, and inpatient wound services. United States health systems are consolidating vendor panels under group purchasing organization contracts that demand outcome documentation and inventory management integration.
- Ambulatory Care Centers:Same-day surgical and wound care procedures require compact packaging and rapid application training for rotating clinical staff.
- Wound Care Clinics:Specialized outpatient facilities manage complex non-healing wounds with advanced dressing protocols and sharp debridement capabilities.
- Home Healthcare:Self-administered or nurse-visited wound care in residential settings demands intuitive application and extended wear intervals to reduce visit frequency.
- Long-Term Care Facilities:Skilled nursing and assisted living environments manage pressure injury prevention and treatment for mobility-limited residents.
Hospital contracts lock in baseline volume; home healthcare expansion offers the steepest trajectory as payors shift site of care.
Application Type:
Functional purpose—moisture balance, infection prevention, fluid handling, physical protection, and tissue regeneration—drives material selection and layering architecture.
- Moisture Management:Maintaining optimal wound bed hydration without maceration of surrounding intact tissue requires vapor-permeable backings and controlled gelling action. German university hospitals are piloting biosensor-integrated substrates that signal moisture saturation levels to clinical staff, enabling just-in-time dressing changes.
- Infection Control:Antimicrobial integration through silver, iodine, or polyhexamethylene biguanide loading addresses bioburden in contaminated or colonized wounds.
- Exudate Absorption:Fluid retention capacity and lock-away properties prevent strike-through and periwound maceration in heavily draining wounds.
- Wound Protection:Physical barrier function against mechanical trauma, thermal injury, and environmental contamination supports healing in exposed anatomical locations.
- Tissue Repair:Biologically active dressings incorporating collagen, hyaluronic acid, or extracellular matrix components signal cellular proliferation and angiogenesis.
Absorption and moisture functions dominate unit volume; tissue repair modalities are gaining share fastest as regenerative medicine converges with wound care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers and long-term care administrators concentrate purchasing power across five national markets where chronic wound prevalence and reimbursement policy create differentiated demand profiles.
United States
Medicare's outpatient wound management expansion and hospital discharge protocol reforms drive demand for extended-wear dressing formats. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking market access. Texas Medical Center in Houston anchors surgical wound care innovation with integrated supply chain contracts.
Germany
Aging demographics and statutory health insurance coverage for advanced moisture-management dressings expand the addressable patient pool. EU Medical Device Regulation compliance requirements compress timelines for legacy product recertification. Berlin-Brandenburg hosts concentrated wound care research clusters piloting biosensor-integrated substrates.
Japan
Postoperative length-of-stay reduction targets amplify demand for low-adherence interfaces in hospital surgical units. PMDA streamlined approval pathways accelerate market entry for combination products with drug-eluting layers. Kansai region burn centers adopt alginate formats for heavily draining wounds.
United Kingdom
NHS procurement frameworks favor suppliers with ISO 13485 certification and health economics documentation. NICE technology appraisals increasingly require outcome evidence for advanced dressing categories versus standard gauze. Greater Manchester wound care clinics consolidate vendor panels under outcome-based contracts.
Brazil
Private insurance network expansion and aging population demographics create demand for self-administered advanced dressings in home care settings. ANVISA regulatory pathways for imported medical devices influence market entry strategies. São Paulo distributors lack technical training infrastructure to support product adoption.
Global Absorbent Dressings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by procurement scale and clinical evidence depth. Hospital group purchasing organizations in the United States and centralized NHS frameworks in the United Kingdom concentrate contract awards toward suppliers with dedicated health economics teams. Three archetypes dominate: diversified medical technology conglomerates with wound care divisions, pure-play advanced wound management specialists, and private-label contract manufacturers serving distributor brands. Consolidation through strategic acquisitions and vertical integration into raw material supply chains represent the dominant competitive moves reshaping vendor relationships.
Among diversified conglomerates with wound care portfolios, 3M and Smith & Nephew exemplify archetypes combining materials science expertise with hospital supply chain access. Medline Industries occupies a position as a channel-controlling distributor with captive manufacturing capabilities. These three entities anchor the competitive structure by representing scale-driven procurement leverage, technology-led premium positioning, and integrated supply chain control respectively.
| Leading Market Players |
|---|
| 3M |
| Smith & Nephew |
| Medline Industries |
| ConvaTec |
| Molnlycke Health Care |
| Coloplast |
| Baxter |
| Johnson & Johnson Services |
| Hartmann Group |
| Others |
Supply & Pricing Matrix
Acrylic acid derivative volatility on the US Gulf Coast compresses margin structures across absorbent dressing tiers while simultaneously forcing geographic diversification of superabsorbent polymer sourcing. This input cost instability widens price spreads between premium hydrofiber formats and standard foam alternatives, reshaping procurement patterns among hospital group purchasing organizations.
Pricing Analysis
Cost-plus contracts with acrylic acid indexation dominate raw material purchasing agreements between dressing manufacturers and petrochemical suppliers. Price differentiation rests on ISO 13485 certification tier and clinical evidence depth, with FDA 510(k)-cleared formats commanding sustained premiums over CE-marked equivalents. Pricing pressure stems from Medicare reimbursement compression favoring standard gauze in outpatient settings. Home healthcare agencies exhibit highest price sensitivity; burn centers and surgical units demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentrates among specialized wound care converters in Germany, Ireland, and the Dominican Republic serving branded OEMs. Production draws from superabsorbent polymers sourced from US and Northeast Asian petrochemical complexes, alginate fibers from Scottish and Norwegian seaweed processors, and silicone adhesives from German specialty chemical suppliers. Single-source vulnerability in acrylic acid derivatives creates exposure to force majeure disruptions. Distribution runs through hospital group purchasing organizations in the United States and centralized NHS frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Absorbent dressings are approaching a platform-economics inflection where biosensor-integrated substrates and electronic health record interoperability create winner-take-most dynamics among suppliers with health analytics capabilities.
For Market Incumbents: Build clinical evidence moats through randomized controlled trials demonstrating reduced dressing change frequency versus standard care. Consolidate contract manufacturing capacity in Ireland and the Dominican Republic to secure ISO 13485-certified supply. Deepen backward integration into alginate fiber production to offset petrochemical input volatility. For New Entrants and Emerging Players: Establish a beachhead in Brazil's private insurance home care segment where technical training gaps among distributors create partnership opportunities. Target alginate-superabsorbent polymer hybrid formats for infection-prone wound applications. Pursue ANVISA regulatory consulting partnerships to accelerate market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors health economics-capable mid-caps over pure manufacturing plays. Long-term viability hinges on reimbursement strategy execution and biosensor integration pipelines. Acquisition targets should demonstrate ISO 10993 testing infrastructure and established hospital system relationships. Monitor EU MDR recertification timelines as inflection signals for competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerates competitive displacement toward ISO 13485-certified suppliers with robust clinical evidence portfolios. |
| Biosensor Integration Development | Creates platform differentiation through real-time exudate monitoring and electronic health record connectivity. |
| Backward Integration into Alginate Supply | Reduces petrochemical input exposure while securing hemostatic fiber supply for infection-control formats. |
| Hospital System Partnership | Locks in volume through group purchasing organization contracts demanding outcome documentation and inventory integration. |
| Reimbursement Strategy Investment | Captures Medicare outpatient expansion through coding expertise and health economics evidence generation. |
Research Methodology
The analysis maps foam, alginate, hydrocolloid, hydrogel, and composite dressing categories, each validated through wound care clinicians, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers. Primary interview insights triangulate against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation.
Forecast assumptions hold regulatory transition timelines and chronic wound epidemiology trajectories fixed while varying biopolymer innovation adoption curves and reimbursement policy shifts across the projection horizon. Segmentation dimensions include product format, wound etiology, care setting, application function, and regional regulatory cluster. CAGRs derive from patient volume projections, procedure frequency modeling, and average selling price trend analysis incorporating superabsorbent polymer cost pass-through patterns.
Sensitivities concentrate around EU MDR implementation delays, acrylic acid supply disruptions, and Medicare reimbursement recalibrations. Forecasts reflect documented assumptions regarding clinical adoption timelines and competitive consolidation patterns. Quarterly review of regulatory submission backlogs, raw material price indices, and hospital contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Safety Needles Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Specimen Collection Cards Market