
 Dissolvable Stitches Market | 2026-2036
Dissolvable Stitches Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolvable Stitches Market Analytics
China is tilting toward expanded medical-grade polymer production capacity to serve domestic surgical supply chains. Ethicon leverages backward integration into polyglycolic acid resin production to secure raw material consistency across its suture portfolio. Medtronic anchors its position through R&D intensity in antimicrobial-coated absorbable threads. B. Braun SE competes on manufacturing scale, operating multi-site sterile suture production across European and Asian facilities.
Dissolvable stitches are absorbable wound closure devices manufactured from synthetic polymers such as polyglycolic acid or lactide copolymers, designed to degrade through hydrolysis within 60 to 90 days post-implantation and eliminate the need for removal procedures. Polymer-based sutures command the broadest clinical acceptance due to predictable tensile strength retention profiles and minimal tissue reaction, while catgut segments face structural decline as synthetic alternatives displace collagen-derived materials in developed markets. The application dimension shows general surgery representing the mature volume base, whereas orthopedic procedures generate premium pricing tied to high-strength braided configurations required for musculoskeletal loading.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market access, with both agencies intensifying scrutiny of degradation byproduct toxicology data. ISO 10993 biocompatibility testing series serves as the harmonized baseline for cytotoxicity and sensitization validation across jurisdictions. Stakeholders must monitor evolving polymer purity standards and sterilization method restrictions, as regulatory divergence between the United States and European Union threatens to fragment product registration strategies and complicate global portfolio planning.
Market Dynamics
FDA and EMA biocompatibility standards are tightening polymer purity requirements for absorbable sutures, forcing manufacturers to validate degradation byproduct toxicology and sterilization methods across multi-jurisdictional portfolios.
Growth Catalysts
- ISO 10993 harmonization:The biocompatibility testing series creates unified cytotoxicity and sensitization baselines, reducing redundant validation costs for suppliers operating across the United States and European Union.
- Ambulatory surgical centers:Medicare reimbursement alignment for minimally invasive procedures in the United States pulls dissolvable stitch demand into outpatient settings previously dominated by removable closure methods.
- Polyglycolic acid resin production:Backward integration into medical-grade polymer manufacturing secures raw material consistency and shields suppliers from pharmaceutical-grade feedstock competition.
Market Restraints
- Catgut displacement lag:Collagen-derived sutures retain residual demand in cost-constrained healthcare systems, delaying full synthetic conversion despite inferior tensile strength retention profiles.
- Degradation byproduct scrutiny:FDA 510(k) pathways now require extended toxicology datasets for hydrolysis metabolites, extending regulatory timelines for novel polymer formulations.
- High-strength braided input costs:Orthopedic-grade multifilament configurations depend on specialized lactide copolymer feedstocks subject to pharmaceutical packaging demand competition.
Strategic Opportunities
- China domestic supply chain expansion:Medical-grade polymer production capacity growth targets import substitution for surgical sutures, creating partnership openings for validated Western manufacturers.
- Antimicrobial coating convergence:Integration of triclosan or ionic silver into absorbable threads addresses surgical site infection protocols in orthopedic and cardiovascular applications.
- Same-day discharge protocols:United States ambulatory surgery center expansion rewards closure materials that eliminate return visits for suture removal, favoring predictable 60-90 day hydrolysis profiles.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for lactide-glycolide copolymer ratio optimization concentrates at legacy medical device firms, constraining new entrant R&D velocity.
- Gamma sterilization validation:EMA Medical Device Regulation restrictions on ethylene oxide residues force capital-intensive conversion to electron beam or gamma irradiation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolvable Stitches Market |
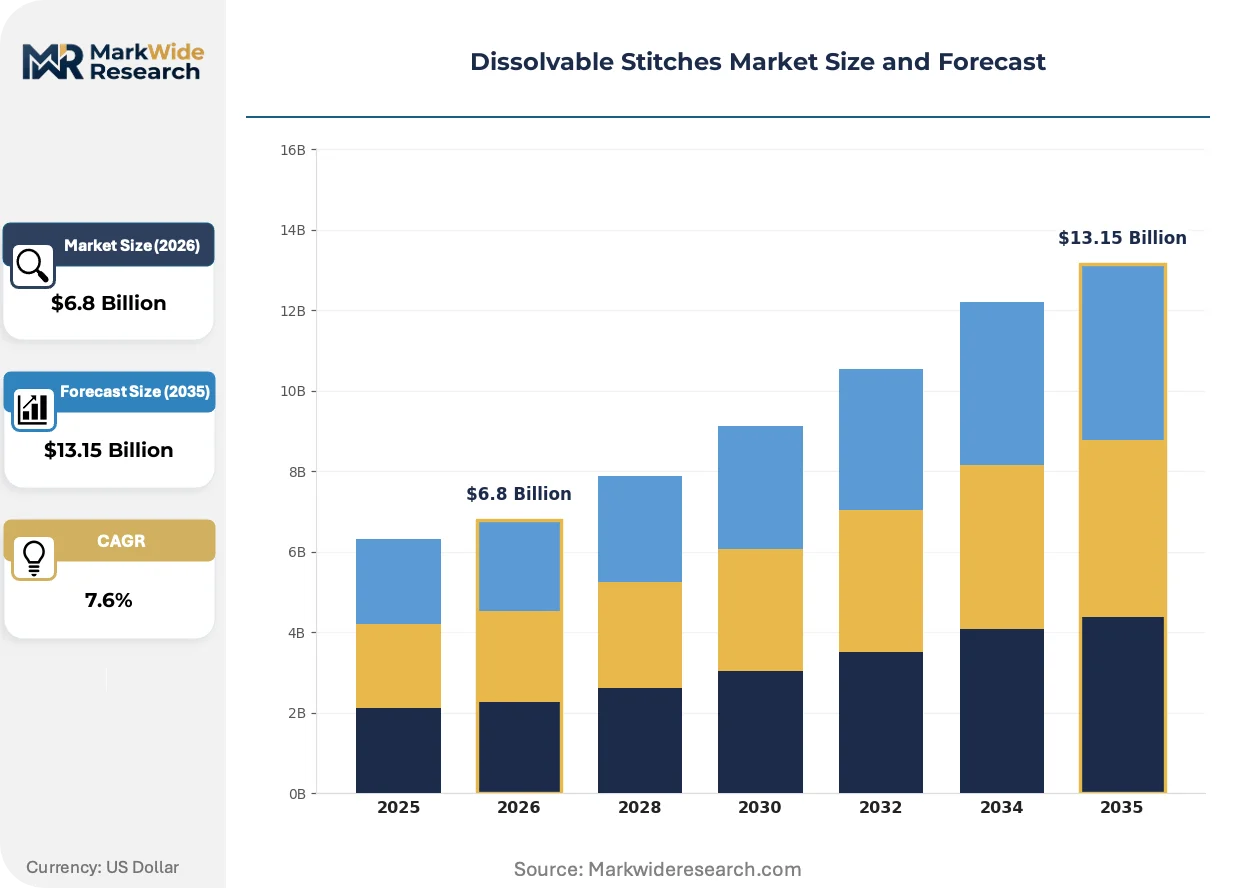
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Surgical Threads, Biodegradable Stitches, Polymer-based Sutures End User: Hospitals, Outpatient Clinics, Surgical Centers, Dental Facilities Application: General Surgery, Orthopedic Procedures, Cardiac Surgery, Gynecological Surgery Material: Polyglycolic Acid, Polypropylene, Catgut, Lactide |
| Companies Covered | Ethicon, Medtronic, B. Braun SE, DemeTECH Corporation, Teleflex Incorporated, Smith & Nephew, Advanced Medical Solutions Group, Corza Medical, SERAG-WIESSNER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolvable Stitches Market Evolving Landscape
Digital simulation of hydrolysis kinetics and molecular modeling of tissue-suture interfaces are compressing development cycles for next-generation absorbable closures. Three forces dominate current innovation trajectories.
Antimicrobial-coated absorbable threads are virtualizing traditional infection control protocols in orthopedic and cardiovascular suites. Hospitals in the United States are adopting these configurations for joint replacement and sternal closure procedures where surgical site infection carries catastrophic cost exposure. The technology is virtualizing the boundary between wound closure and prophylactic antimicrobial delivery, collapsing separate product categories into single-procedure solutions.
REACH polymer registration requirements in the European Union are forcing reformulation of legacy glycolide-lactide copolymers to eliminate residual monomer contaminants. Suppliers must resubmit technical files under MDR conformity assessment procedures, diverting regulatory affairs resources from new product development. High-volume braided suture lines face the steepest compliance burden due to their complex multi-filament construction and extended degradation profiles.
Hospital purchasing consortiums in the United States are consolidating suture procurement under standardized formularies that privilege suppliers with broad absorbable portfolios. This concentration compresses vendor counts at individual health systems from six or seven manufacturers to two or three strategic partners. The shift is most visible in integrated delivery networks spanning multiple states, where formulary harmonization across dozens of facilities creates winner-take-all contract dynamics.
Dissolvable Stitches Market Segmentation
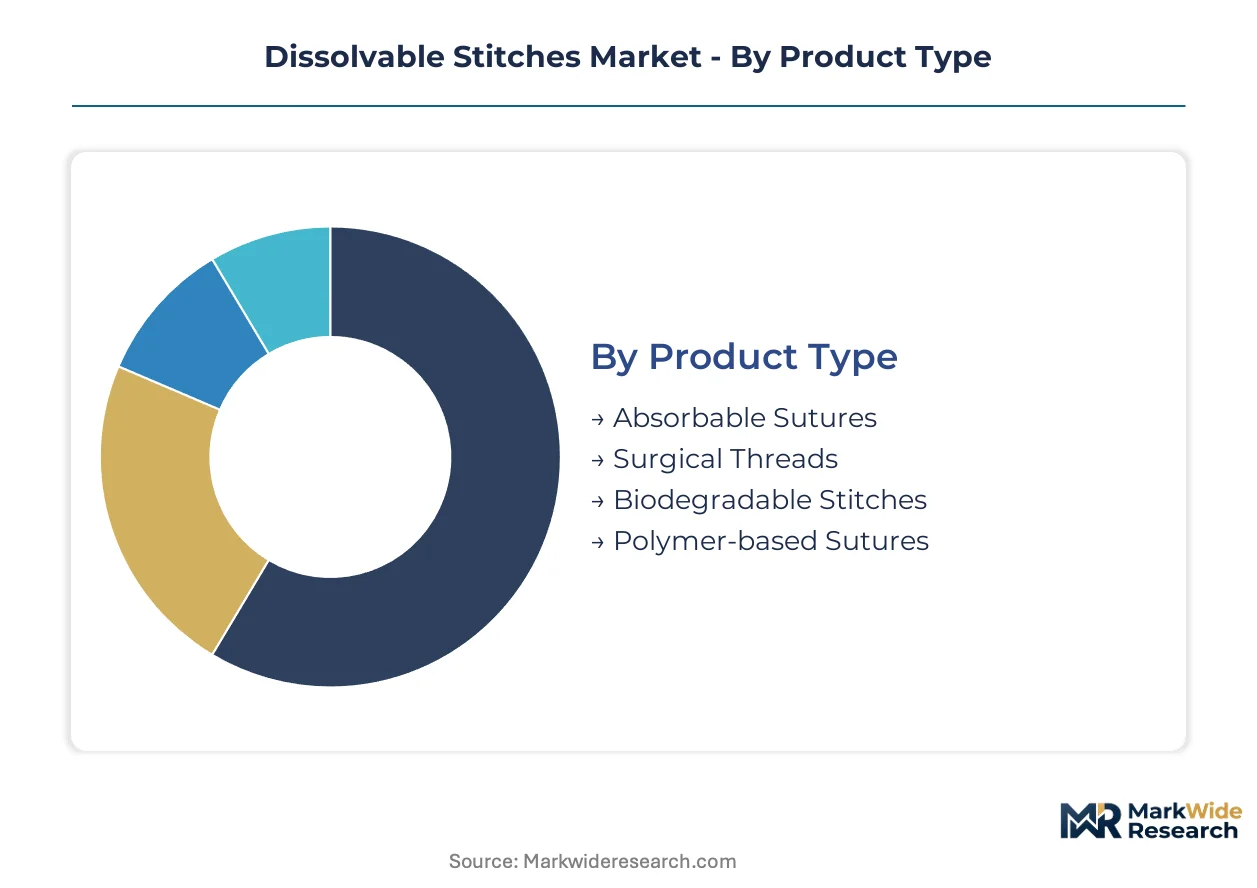
Dissolvable stitches segment along four dimensions that determine procurement patterns and margin structures. Product type and material composition drive technical specifications, while end-user channel and application dictate pricing power and volume concentration.
Product Type:
Cycle times vary dramatically across product categories, with commodity threads turning inventory fastest and specialized configurations requiring extended validation periods.
- Absorbable Sutures:Synthetic polymer monofilaments and braided configurations dominate hospital formularies through predictable hydrolysis profiles. General surgery departments in the United States anchor demand as procedural volumes recover and Medicare reimbursement alignment favors same-day discharge protocols.
- Surgical Threads:Multifilament braided constructions serve orthopedic loading requirements with extended tensile strength retention. Premium pricing attaches to high-strength lactide copolymer formulations required for musculoskeletal applications.
- Biodegradable Stitches:Engineered degradation timelines match tissue healing windows in cardiovascular and soft-tissue procedures.
- Polymer-based Sutures:Standardized glycolide-lactide copolymers offer cost-efficient alternatives for high-volume general surgery.
Absorbable sutures anchor the volume base while biodegradable stitches gain share at the steepest rate.
End User:
Channel cost tiers stratify sharply, with integrated delivery networks extracting volume discounts unavailable to independent surgical facilities.
- Hospitals:Inpatient surgical departments maintain broad absorbable portfolios across general, cardiac, and orthopedic service lines. Formulary consolidation under purchasing consortiums compresses vendor counts from six or seven manufacturers to two or three strategic partners.
- Outpatient Clinics:Dermatology and minor procedure settings favor rapid-absorption monofilaments that eliminate return visits.
- Surgical Centers:Ambulatory facilities in the United States drive fastest expansion as Medicare reimbursement alignment pulls minimally invasive procedures from hospital settings.
- Dental Facilities:Oral surgery applications require specialized sizes and needle configurations with shorter degradation timelines.
Hospitals retain the deepest volume concentration while surgical centers expand most quickly.
Application:
Procedure maturity determines specification intensity, with established general surgery tolerating standard configurations and emerging minimally invasive techniques demanding customized performance profiles.
- General Surgery:Appendectomy, hernia repair, and gastrointestinal procedures consume the highest suture volumes through standardized absorbable configurations. Hospital systems in the United States represent the mature demand base with predictable seasonal patterns.
- Orthopedic Procedures:Joint replacement and tendon repair require high-strength braided lactide copolymers with extended strength retention. Antimicrobial-coated threads are virtualizing infection control protocols in these high-stakes surgical environments.
- Cardiac Surgery:Sternal closure and vascular anastomosis demand precision-engineered degradation timelines matched to tissue healing.
- Gynecological Surgery:Laparoscopic and open procedures favor rapid-absorption monofilaments that minimize foreign body reaction.
General surgery holds the volume anchor while orthopedic procedures command the steepest pricing escalation.
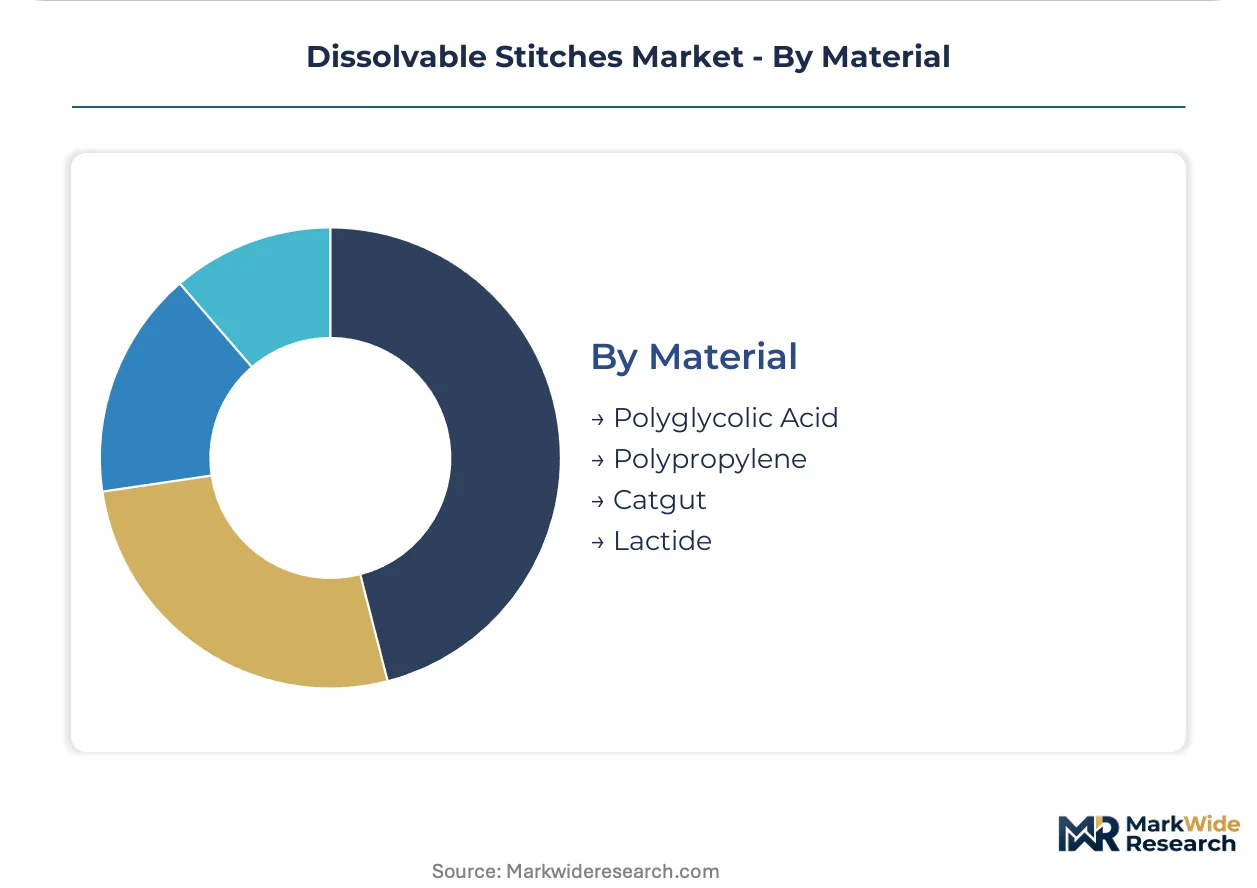
Material:
Supply concentration varies by feedstock chemistry, with polyglycolic acid enjoying captive production at major manufacturers and catgut facing structural displacement.
- Polyglycolic Acid:Synthetic polyester degrades through hydrolysis within predictable 60-90 day windows. Ethicon leverages backward integration into resin production to secure raw material consistency across its suture portfolio.
- Polypropylene:Non-absorbable monofilament serves temporary tissue approximation with subsequent removal, limiting penetration in dissolvable stitch markets.
- Catgut:Collagen-derived material retains residual demand in cost-constrained healthcare systems despite inferior tensile strength retention and higher tissue reaction rates.
- Lactide:Lactide-glycolide copolymers enable tunable degradation profiles through ratio optimization, though formulation expertise concentrates at legacy medical device firms.
Polyglycolic acid anchors material volume while lactide formulations climb the fastest in premium orthopedic and cardiovascular segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical logistics corridor underwrites European distribution efficiency for polymer-based surgical supplies. Shanghai Pudong International Airport's cold-chain pharmaceutical terminals anchor Asia-Pacific import flows of medical-grade feedstocks.
United States
Ambulatory surgical center expansion and Medicare reimbursement alignment for minimally invasive procedures concentrate demand in outpatient settings. FDA 510(k) clearance pathways govern market access with intensifying scrutiny of degradation byproduct toxicology. The Dallas-Fort Worth medical device corridor hosts sterile suture production facilities serving integrated delivery networks across the Southwest.
Germany
Hospital purchasing consortiums consolidate procurement under standardized formularies that privilege suppliers with broad absorbable portfolios. EMA Medical Device Regulation conformity assessments require resubmission of technical files for legacy glycolide-lactide copolymers. The Tuttlingen surgical instrument cluster anchors multi-site sterile suture production serving European and Asian facilities.
China
Medical-grade polymer production capacity expansion targets import substitution for domestic surgical supply chains. NMPA biocompatibility standards for polymer-based sutures tighten material purity requirements. The Yangtze River Delta concentration of chemical manufacturing feeds downstream medical device fabrication in Suzhou and Shanghai.
Japan
Aging demographics and procedural volume growth in orthopedic applications drive premium pricing for high-strength braided configurations. PMDA regulatory harmonization with ISO 10993 biocompatibility testing series reduces redundant validation costs. The Kansai region's precision polymer processing capabilities support specialized lactide copolymer formulation.
India
Cost-constrained healthcare systems retain residual demand for catgut sutures despite synthetic conversion trends. CDSCO medical device regulations align with international standards while permitting phased compliance timelines. The Maharashtra pharmaceutical manufacturing belt concentrates polymer resin production for regional surgical supply chains.
Dissolvable Stitches Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on the material science vector. The vendor base organizes around three strategic archetypes: backward-integrated polymer producers, antimicrobial coating innovators, and manufacturing-scale operators. Consolidation pressures intensify as hospital purchasing consortiums compress vendor counts from six or seven manufacturers to two or three strategic partners. Dominant competitive moves include capacity expansion in medical-grade resin production and technology licensing for degradation profile optimization.
Among legacy medical device conglomerates, Ethicon and Medtronic occupy positions that exemplify divergent strategic orientations toward material control versus clinical application engineering. B. Braun SE anchors the manufacturing-scale archetype through multi-site sterile production networks. These three entities represent the competitive spectrum: captive polymer supply, R&D-intensive functional coatings, and distributed manufacturing footprint.
| Leading Market Players |
|---|
| Ethicon |
| Medtronic |
| B. Braun SE |
| DemeTECH Corporation |
| Teleflex Incorporated |
| Smith & Nephew |
| Advanced Medical Solutions Group |
| Corza Medical |
| SERAG-WIESSNER |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese medical-grade polymer production is pressuring glycolide-lactide copolymer feedstock margins and forcing Western suppliers into defensive pricing postures across hospital purchasing consortiums.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across antimicrobial-coated, high-strength braided, and standard monofilament configurations. Three-tier pricing separates premium antimicrobial threads from standard synthetic absorbables from economy catgut alternatives. Price differentiation hinges on ISO 10993 biocompatibility certification tier and backward integration into polyglycolic acid resin production. Cost compression in standard monofilament segments is intensifying because of Chinese domestic supply chain expansion. Independent outpatient clinics exhibit highest price sensitivity; integrated delivery networks wield volume leverage that compresses premium-tier premiums.
Supply Chain Analysis
Extended payment terms from United States hospital purchasing consortiums are squeezing working capital across European and Asian component suppliers. Raw material concentration rests on China for medical-grade polymer resin, Germany for precision extrusion equipment, and India for pharmaceutical-grade lactide feedstocks. Specialized lactide-glycolide copolymer formulations, antimicrobial coating chemistries, and gamma-sterilization packaging represent critical input dependencies. Single-source vulnerability in polyglycolic acid resin production threatens supply continuity for non-integrated manufacturers. Distribution runs through sterile medical device logistics networks anchored at regional distribution centers serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States hospital purchasing consortiums compress vendor counts from six or seven manufacturers to two or three strategic partners, extracting formulary commitments that lock out secondary suppliers.
For Market Incumbents: Pre-empt antimicrobial coating convergence by accelerating triclosan and ionic silver integration programs before regulatory restrictions on ethylene oxide sterilization force capital-intensive infrastructure conversions. Defend position through backward integration into medical-grade polymer manufacturing in the Yangtze River Delta to offset Chinese domestic supply chain expansion. Secure GPO contracts with multi-year exclusivity provisions that block entrant access to high-volume general surgery departments.
For New Entrants and Emerging Players: India's cost-constrained healthcare systems retain residual catgut demand despite synthetic conversion trends, creating white-space opportunity for hybrid natural-synthetic product portfolios priced below premium lactide formulations. Target oral surgery and dental facility channels where specialized needle configurations and shorter degradation timelines face less entrenched incumbent relationships. Pursue technology licensing partnerships with legacy polymer chemists to bypass formulation expertise scarcity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gamma sterilization and electron beam infrastructure as EMA Medical Device Regulation restrictions on ethylene oxide residues force equipment replacement cycles. Long-term viability favors platform integrators with captive polymer supply and distributed sterile manufacturing footprints over component specialists exposed to feedstock price volatility. Target acquisition candidates with validated FDA 510(k) portfolios and established hospital formulary positions. Monitor NMPA biocompatibility standard tightening as inflection signal for Chinese market access barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Integration | Triclosan and ionic silver incorporation collapses separate infection control and closure product categories into single-procedure solutions. |
| Backward Integration into Polymer Resin | Captive polyglycolic acid production shields margins from pharmaceutical packaging demand competition for lactide copolymer feedstocks. |
| Sterilization Infrastructure Conversion | Gamma irradiation and electron beam capacity builds compliance runway against EMA MDR ethylene oxide residue restrictions. |
| Hospital System Partnership | Integrated delivery network formulary consolidation rewards suppliers with broad absorbable portfolios spanning general, orthopedic, and cardiac service lines. |
| China Domestic Supply Chain Expansion | Medical-grade polymer production capacity growth in the Yangtze River Delta targets import substitution for regional surgical suture fabrication. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged hospital purchasing committee directors, biomedical engineers responsible for suture formulary decisions, GPO contracts managers, and regulatory affairs leads at polymer manufacturers. Secondary validation drew from ISO 10993 biocompatibility testing records, CMS Medicare reimbursement alignment documentation, and customs data tracking medical-grade polymer resin trade flows. Bottom-up demand modeling from procedural volume data and top-down market sizing from manufacturer revenue disclosures were cross-referenced for triangulation.
Forecast inputs span absorbable suture, surgical thread, biodegradable stitch, and polymer-based suture product categories across general surgery, orthopedic, cardiac, and gynecological applications. Segmentation dimensions include material composition, end-user channel, and geographic regulatory cluster. CAGRs were derived from regression analysis against procedural volume recovery trajectories and Medicare reimbursement policy alignment. Industry-specific inputs incorporate hydrolysis kinetics modeling for degradation timeline predictability and antimicrobial coating adoption curves in joint replacement protocols.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed polymer producers or accelerated EMA sterilization method restrictions would shift outcomes. Macroeconomic contraction affecting elective procedure volumes, regulatory divergence between FDA and EMA biocompatibility standards, or breakthrough non-suture wound closure technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Micro Vials Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Global IV Bags Market