
 Asia-Pacific Human Fibrin Glue Market | 2026-2036
Asia-Pacific Human Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Human Fibrin Glue Market Outlook
Chinese plasma fractionation capacity is decoupling from historical import dependence as domestic collection networks mature. Shanghai RAAS leverages its vertically integrated plasma supply chain to dominate hospital tenders in eastern China. Baxter International sustains premium positioning through cryoprecipitate sourcing protocols that meet Japan's PMDA purity thresholds. Hualan Biological Engineering anchors its competitive stance on scaled albumin co-extraction economics that subsidize fibrinogen recovery costs.
Human fibrin glue comprises concentrated human fibrinogen and thrombin components that polymerize into a biodegradable mesh upon tissue contact, achieving hemostasis within seconds through simulated clot cascade mechanics. The product serves primarily as a surgical sealant in procedures where suture lines bleed or air leaks persist. Liquid formulations occupy the largest volume share due to compatibility with laparoscopic delivery systems, while spray applicator delivery modes command margin premiums in cardiothoracic suites where precise tissue coating determines outcomes. Patch formats remain nascent in Asia-Pacific but attract development capital from Japanese wound-care specialists targeting diabetic foot ulcer protocols.
Japan's PMDA, Australia's TGA, and India's CDSCO enforce divergent viral inactivation documentation standards that fragment registration pathways and extend product launch timelines by eighteen to thirty-six months across jurisdictions. China's NMPA now mandates domestic plasma traceability for Class III hemostat approvals, effectively screening out suppliers lacking captive collection infrastructure. Stakeholders must monitor regulatory reciprocity negotiations between ASEAN member states, as mutual recognition agreements would collapse current multi-country filing burdens into centralized assessment routes.
Market Dynamics
Plasma supply chain regionalization is fragmenting procurement patterns across Asia-Pacific, as China's NMPA domestic traceability mandates and Japan's PMDA purity protocols force suppliers to choose between captive collection infrastructure or market exclusion.
Growth Catalysts
- Cardiovascular surgery volume:Tertiary hospital expansion in China's eastern seaboard clusters is absorbing fibrin glue volumes at rates exceeding other national markets in the region.
- CDSCO biocompatibility tightening:India's accelerated hemostat registration timelines are compressing product approval cycles and rewarding early regulatory investment.
- Laparoscopic delivery compatibility:Liquid formulation standardization is unifying surgical sealant protocols across minimally invasive procedure suites.
Market Restraints
- Plasma input cost volatility:Fractionation economics hinge on albumin co-extraction yields, exposing fibrinogen recovery margins to plasma collection network disruptions.
- Regulatory fragmentation:Divergent viral inactivation documentation between Japan's PMDA, Australia's TGA, and India's CDSCO extends multi-jurisdiction launch timelines by eighteen to thirty-six months.
- Synthetic sealant substitution:Polyethylene glycol-based alternatives are capturing price-sensitive procurement tenders where human-derived sourcing carries premium liability.
Strategic Opportunities
- ASEAN regulatory reciprocity:Mutual recognition agreement negotiations between member states could collapse multi-country filing burdens into centralized assessment routes.
- Diabetic foot ulcer protocols:Patch format development by Japanese wound-care specialists targets underpenetrated chronic wound management segments.
- Spray applicator premium tier:Cardiothoracic suites in Australian and South Korean tertiary hospitals are absorbing margin-premium delivery systems for precise tissue coating.
Industry Challenges
- Viral inactivation documentation:CDSCO, TGA, and PMDA each enforce non-harmonized validation standards, forcing redundant clinical dossier preparation.
- Cryoprecipitate sourcing capex:Japan's purity threshold compliance requires dedicated cold-chain infrastructure investment that screens out capital-constrained entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Human Fibrin Glue Market |
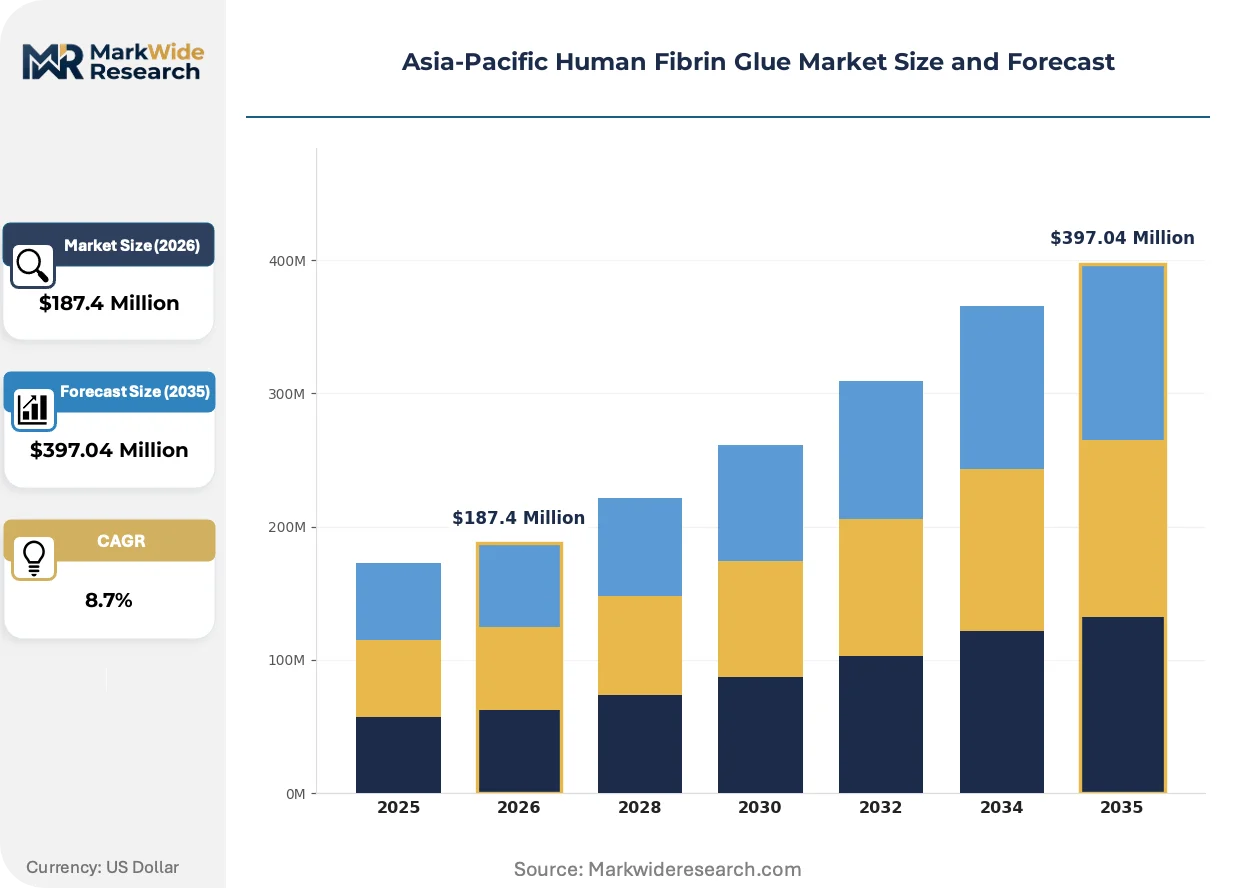
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Film, Patch, Spray Application: Wound Healing, Surgical Procedures, Tissue Repair, Hemostasis End User: Hospitals, Clinics, Research Labs, Outpatient Facilities Delivery Mode: Syringe, Spray Applicator, Adhesive Patch, Open Pouch |
| Companies Covered | Shanghai RAAS, Hualan Biological Engineering, Reliance Life Sciences, Takeda Pharmaceutical Company, GC Pharma, Zhejiang Medicine, CSL Behring, Baxter International, Johnson & Johnson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Human Fibrin Glue Market Strategic Shifts
Formulation convergence and regulatory data harmonization are compressing competitive differentiation in Asia-Pacific surgical sealants, while procurement centralization in Chinese hospital clusters is redistributing bargaining power toward domestic plasma fractionators.
Spray applicator technology is unifying delivery precision standards in cardiothoracic procedures. Tertiary hospitals in Japan and South Korea are adopting these systems at accelerating pace for air leak management. The technology is unifying outcome metrics across previously fragmented surgical sealant evaluation protocols, compressing brand loyalty windows.
China's NMPA Class III hemostat traceability mandates are restructuring supplier qualification criteria. Domestic plasma collection infrastructure has become a non-negotiable approval precondition. Foreign manufacturers lacking captive collection networks in China face effective market exclusion regardless of clinical performance.
Hospital procurement consolidation in China's eastern seaboard is displacing distributor-mediated purchasing. Direct tender participation by plasma fractionators is replacing multi-tier distribution. Shanghai and Jiangsu province hospital clusters exhibit the most visible compression of intermediary margins.
Asia-Pacific Human Fibrin Glue Market Segmentation
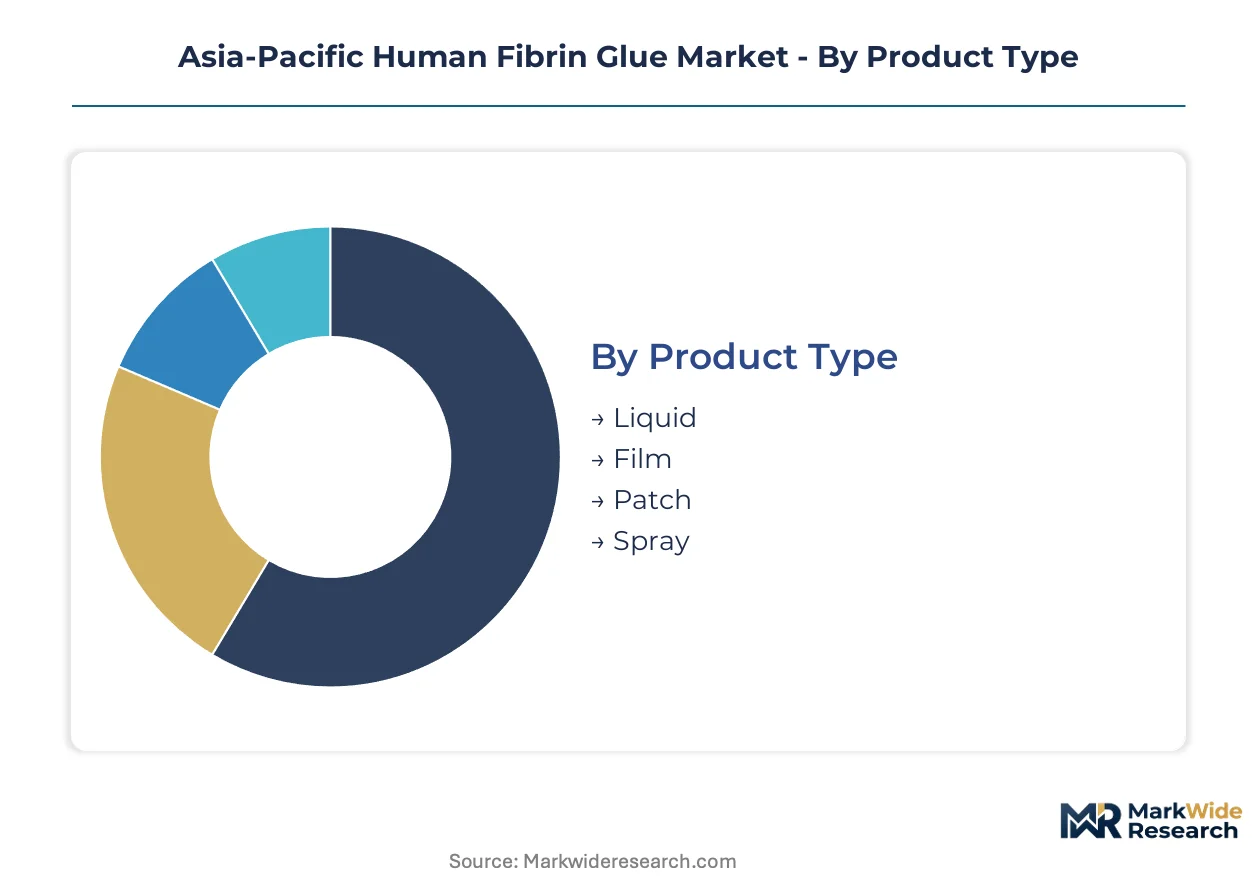
Human fibrin glue segmentation in Asia-Pacific reflects divergent capital requirements across manufacturing modalities and clinical delivery systems. Product format selection determines plasma fractionation infrastructure needs, while delivery mechanism choice shapes hospital procurement tier positioning.
Product Type:
Liquid formulations demand the heaviest upfront investment in sterile filling lines and cold-chain distribution networks, while patch formats require specialized polymer grafting equipment and extended stability testing protocols.
- Liquid:Standard aqueous fibrinogen-thrombin suspensions compatible with laparoscopic ports and endoscopic channels. Demand concentrates in China's eastern seaboard tertiary hospitals where cardiovascular surgery volume expansion outpaces other national markets. The format dominates procurement tenders due to versatility across open and minimally invasive procedures.
- Spray:Atomized delivery systems achieving controlled droplet dispersion for large surface coverage. Australian and South Korean cardiothoracic suites absorb these systems at margin premiums where precise tissue coating determines air leak management outcomes. NMPA traceability mandates favor domestic suppliers with captive plasma infrastructure.
- Film:Pre-formed fibrin matrices requiring lyophilization capacity and humidity-controlled packaging. Japanese wound-care specialists target diabetic foot ulcer protocols with this format.
- Patch:Reinforced composite structures integrating fibrin with collagen or synthetic backings. CDSCO biocompatibility tightening accelerates registration timelines for patch developers with validated viral inactivation documentation.
Most installed capacity flows through Liquid. Expansion is steepest in Spray.
Application:
Application segmentation tracks procedure reimbursement tiers and outcome measurement sophistication, with surgical subspecialties commanding premium pricing over chronic wound management.
- Surgical Procedures:Sealing suture lines and anastomoses in cardiothoracic, hepatic, and spinal operations. China's hospital procurement consolidation in Jiangsu province directly tenders fractionators, compressing distributor margins.
- Hemostasis:Active bleeding control in trauma and coagulopathic patients. Tertiary hospital expansion across the region absorbs volumes at rates exceeding other application segments.
- Wound Healing:Chronic ulcer management and burn surface coverage. Patch format development attracts capital from Japanese specialists targeting underpenetrated segments.
- Tissue Repair:Nerve graft adherence and dural sealing. PMDA purity thresholds in Japan screen out suppliers lacking cryoprecipitate sourcing protocols.
Surgical Procedures captures the largest revenue pool. Hemostasis is gaining share fastest.
End User:
End-user segmentation mirrors healthcare infrastructure hierarchy, with capital equipment requirements and regulatory compliance burdens escalating from outpatient settings to research laboratories.
- Hospitals:Tertiary centers with in-house blood banks and surgical volume scale. Eastern China clusters exhibit the most visible procurement centralization, displacing multi-tier distribution.
- Clinics:Ambulatory surgical centers and specialty practices. CDSCO accelerated timelines reward early regulatory investment in this channel.
- Outpatient Facilities:Same-day procedure centers with limited storage infrastructure. Liquid formulation standardization unifies protocols across these settings.
- Research Labs:Preclinical and clinical trial supply. TGA viral inactivation documentation requirements extend product launch timelines for investigational formats.
Hospitals anchor volume absorption. Outpatient Facilities are expanding most quickly.
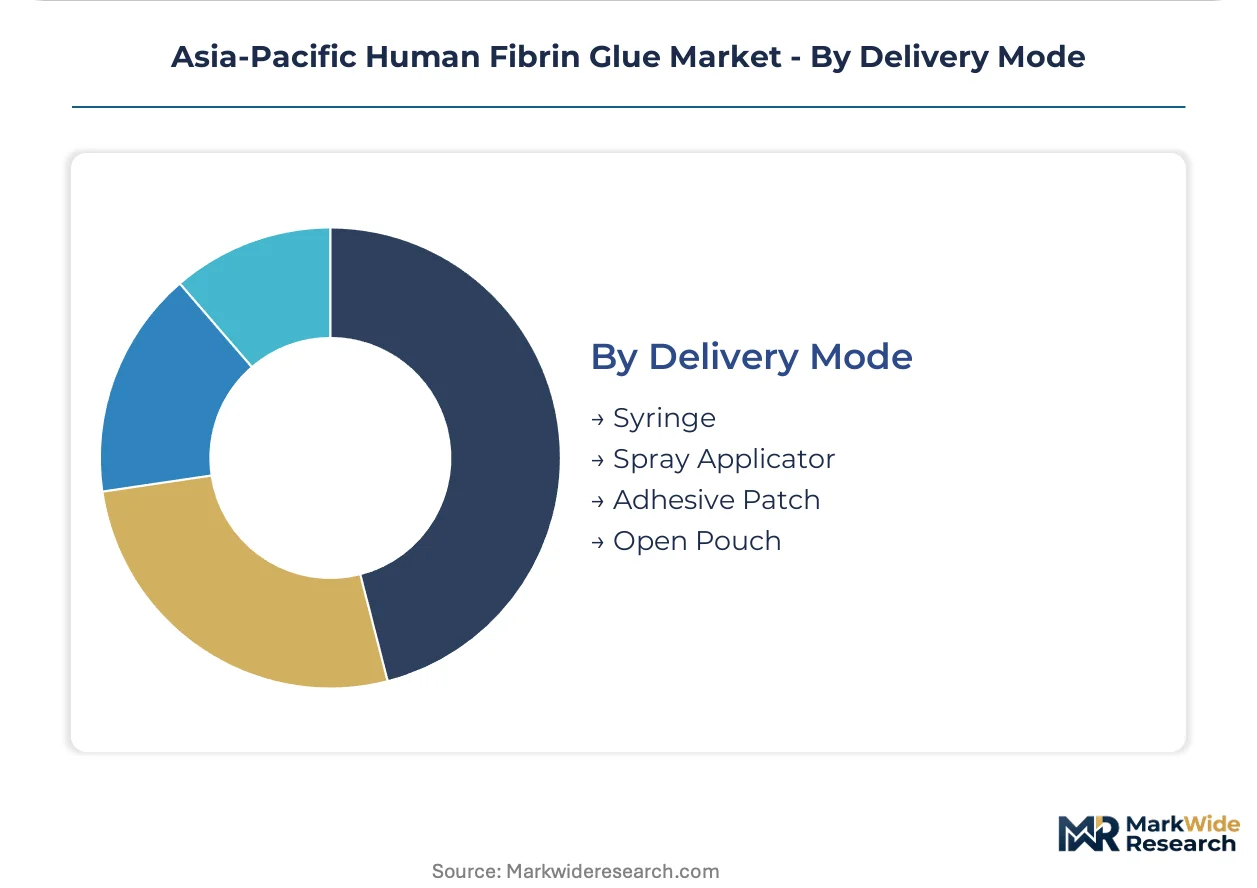
Delivery Mode:
Delivery mode selection determines unit economics and clinical training requirements, with precision applicators commanding manufacturing complexity premiums over conventional syringe systems.
- Syringe:Dual-barrel manual injection systems with mixing chambers. Price-sensitive procurement tenders in India favor this format where human-derived sourcing carries premium liability.
- Spray Applicator:Gas-pressurized or mechanical atomization devices. Cardiothoracic suites adopt these at accelerating pace, unifying outcome metrics across previously fragmented evaluation protocols.
- Adhesive Patch:Pre-activated fibrin matrices with backing removal. Japanese wound-care specialists develop this format for diabetic foot ulcer protocols.
- Open Pouch:Pourable formulations for topical application. Research labs utilize this format for experimental tissue engineering constructs.
Syringe retains the broadest installed base. Spray Applicator shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography across Asia-Pacific, as domestic plasma traceability mandates in China and purity thresholds in Japan create divergent cost-of-compliance landscapes that favor localized fractionation infrastructure over centralized supply.
China
Eastern seaboard hospital clusters in Shanghai and Jiangsu province absorb fibrin glue volumes at rates exceeding other national markets in the region. NMPA Class III hemostat approvals now mandate domestic plasma traceability, effectively screening out suppliers lacking captive collection networks. Vertically integrated domestic fractionators dominate direct hospital tenders, displacing multi-tier distribution channels.
Japan
Cardiothoracic suites in tertiary hospitals adopt spray applicator systems at accelerating pace for air leak management. PMDA enforces stringent viral inactivation documentation and cryoprecipitate purity thresholds that extend product launch timelines. Tokyo and Osaka medical centers drive premium-tier absorption where precise tissue coating determines surgical outcomes.
India
Tertiary hospital expansion absorbs hemostat volumes across cardiovascular and hepatic surgery suites. CDSCO has tightened biocompatibility requirements and accelerated registration timelines for hemostat developers with validated documentation. Mumbai and Delhi-NCR clusters concentrate procurement demand, rewarding early regulatory investment with compressed approval cycles.
Australia
South Korean and Australian cardiothoracic units absorb margin-premium spray delivery systems. TGA viral inactivation standards fragment registration pathways relative to other Asia-Pacific jurisdictions. Sydney and Melbourne tertiary centers exhibit outcome-metric unification across previously fragmented surgical sealant evaluation protocols.
South Korea
Minimally invasive procedure volume expansion drives liquid formulation standardization across Seoul Capital Area hospital networks. MFDS regulatory frameworks align with broader regional trends toward traceability documentation. Busan-Ulsan medical clusters contribute secondary demand concentration for precision delivery systems.
Asia-Pacific Human Fibrin Glue Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue patch-format specialization and chronic wound management adjacencies. Market structure exhibits moderate consolidation around plasma fractionators with captive collection infrastructure, while synthetic sealant developers erode price-sensitive procurement segments. Three archetypes dominate: vertically integrated domestic plasma collectors, multinational cryoprecipitate specialists, and diversified wound-care developers. Competitive moves concentrate on regulatory pre-positioning ahead of NMPA traceability mandates and spray applicator technology licensing.
Within the domestic integrated tier, Shanghai RAAS and Hualan Biological Engineering exemplify archetype positioning through geographic naming conventions and corporate structure. Baxter International anchors the multinational specialist segment. These named entities represent strategic positioning patterns rather than operational specifics, with each occupying distinct regulatory-compliance cost tiers across the regional landscape.
| Leading Market Players |
|---|
| Shanghai RAAS |
| Hualan Biological Engineering |
| Reliance Life Sciences |
| Takeda Pharmaceutical Company |
| GC Pharma |
| Zhejiang Medicine |
| CSL Behring |
| Baxter International |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Cryoprecipitate sourcing costs cascade through three distinct pricing tiers as plasma fractionators balance Japan's PMDA purity thresholds against China's NMPA domestic traceability mandates. Distributor margins compress where Shanghai RAAS and Hualan Biological Engineering displace multi-tier channels through direct hospital tender participation in Jiangsu province.
Pricing Analysis
Distributor margin compression in China's eastern seaboard clusters is restructuring procurement economics as vertically integrated domestic fractionators bypass intermediary layers. Three-tier pricing structure across premium, standard, and economy levels reflects viral inactivation documentation completeness, with spray applicator systems commanding cardiothoracic suite premiums. Cost compression in standard liquid formulations is intensifying because synthetic polyethylene glycol alternatives capture price-sensitive tenders. Indian procurement committees exhibit highest price sensitivity where human-derived sourcing carries premium liability, while Japanese tertiary hospitals show lowest sensitivity for air leak management outcomes.
Supply Chain Analysis
CE marking equivalence and NMPA Class III traceability documentation function as non-negotiable qualification gates for market participation. Manufacturing concentration rests on China, Japan, and South Korea as plasma collection infrastructure and fractionation capacity cluster around regulatory compliance cost differentials. Raw material dependencies center on source plasma volumes, cryoprecipitate yields, and thrombin purification grades. Single-source vulnerability emerges where captive collection networks face disruption from domestic health policy shifts. Distribution runs through hospital procurement consolidation in eastern China, displacing traditional distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific human fibrin glue market compounds steadily as cardiovascular surgery volume expansion across tertiary hospital networks sustains procedural demand growth regardless of cyclical pressures.
For Market Incumbents: Extend regulatory pre-positioning ahead of ASEAN mutual recognition agreement finalization to collapse multi-country filing burdens. Deepen cryoprecipitate sourcing protocols that satisfy Japan's PMDA purity thresholds while accelerating spray applicator technology licensing to cardiothoracic suites. Synthetic sealant substitution threats demand defensive certification investment in premium-tier positioning. For New Entrants and Emerging Players: CDSCO accelerated registration timelines in India open a window for patch-format developers with validated viral inactivation documentation to capture compressed approval cycle rewards. Target diabetic foot ulcer protocols as the most penetrable chronic wound segment, leveraging TGA documentation standards as a transferable compliance foundation. Pursue direct tender participation models that mirror Shanghai RAAS distribution displacement in Chinese hospital clusters. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma collection infrastructure scarcity meets escalating NMPA traceability mandates, favoring targets with captive supply networks. Five-to-ten year viability hinges on backward integration depth rather than formulation differentiation alone. Watch ASEAN regulatory reciprocity negotiations as the signal indicating centralized assessment route viability and multi-jurisdiction launch timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Traceability Compliance Investment | Domestic plasma collection infrastructure becomes non-negotiable for China market access. |
| Spray Applicator Technology Licensing | Cardiothoracic suites in Japan and South Korea absorb precision delivery systems at margin premiums. |
| CDSCO Early Registration Investment | Accelerated hemostat timelines reward developers with validated biocompatibility documentation. |
| Patch Format Development Partnership | Japanese wound-care specialists target underpenetrated diabetic foot ulcer protocols. |
| ASEAN Regulatory Reciprocity Positioning | Mutual recognition agreements would collapse multi-country filing burdens into centralized routes. |
Study Parameters
Coverage spans China, Japan, India, Australia, and South Korea, with primary inputs from each market's plasma fractionation executives, hospital procurement managers, regulatory affairs leads, and cardiovascular surgeons. Secondary validation draws from NMPA filings, PMDA submission databases, CDSCO approval records, and hospital tender documentation. Bottom-up volume modeling triangulates against top-down plasma collection network capacity assessments.
Rate-of-change decomposition separates procedural volume growth from pricing tier shifts and format mix evolution across the projection horizon. Segmentation dimensions include product type, application, end user, and delivery mode, with regulatory cluster and plasma sourcing origin as cross-cutting variables. CAGRs derive from surgical procedure forecasting and fractionation capacity expansion timelines, incorporating laparoscopic adoption curves and spray applicator penetration rates as industry-specific inputs.
Revisions become necessary when NMPA traceability mandates expand beyond current Class III scope or when ASEAN regulatory reciprocity negotiations conclude with unexpected mutual recognition exclusions. A model refresh is warranted upon material change in plasma collection network disruption frequency or synthetic sealant substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Global Swab Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Blood Preparation Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Custom Procedure Packs (CPT) Market