
 Coconut Derivatives Market | 2026-2036
Coconut Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Derivatives Market Intelligence
Value-added processing for consumer-facing products is reconfiguring profit pools previously centered on bulk commodity exports. The Vita Coco Company, Inc. leverages brand strength in the ready-to-drink beverage category. Marico Limited dominates the Indian market with its extensive distribution network for coconut oil. Theppadungporn Coconut specializes in a broad portfolio of food-grade coconut products for international markets.
Coconut derivatives are materials processed from the fruit of the Cocos nucifera palm, including the endosperm, water, and husk. Manufacturing methods like cold-pressing for virgin coconut oil or carbonization for activated charcoal determine the final product's characteristics. These derivatives serve as key inputs across multiple sectors. Within product types, virgin coconut oil commands a premium over standard coconut oil, while the Food & Beverage application remains the largest segment and Cosmetics & Personal Care represents the fastest-growing area.
Regulatory frameworks from the US FDA, the EU's EFSA, and India's FSSAI govern product quality and labeling standards. These rules on contaminants, organic certification, and health claims directly influence international trade and consumer trust. Consequently, navigating disparate regional compliance requirements is a critical operational focus for exporters. Future competitiveness will hinge on securing transparent and verifiably sustainable supply chains.
Market Dynamics
The central force shaping the coconut derivatives market is the consumer-driven pivot to plant-based and clean-label products. This demand is compelling a structural shift in the supply chain, moving from a focus on bulk commodity exports toward higher-margin, value-added processing for food and cosmetic applications.
Growth Catalysts
- Plant-Based Diet Adoption:The Food & Beverage sector's use of coconut milk, cream, and yogurt as dairy-free alternatives is expanding, driven by rising consumer interest in vegan and flexitarian lifestyles in North America and Europe.
- Organic Certification Premiums:Regulatory frameworks like the USDA National Organic Program and the EU organic logo create distinct, higher-value market segments, incentivizing producers to invest in certified farming and processing to capture price premiums.
- Processing Infrastructure Growth:Investment in modern processing facilities within key producing nations, including Indonesia and the Philippines, is improving product quality, reducing post-harvest losses, and increasing the global supply of processed derivatives.
Market Restraints
- Climate Vulnerability:Supply chains are highly exposed to weather-related disruptions, such as typhoons and droughts in Southeast Asia, which can damage harvests and cause significant volatility in raw coconut prices.
- Substitution from Other Plant Sources:Coconut derivatives face intense competition from other plant-based alternatives, such as oat milk, almond oil, and soy proteins, which vie for the same consumer base and retail shelf space.
- Logistical Complexities:The perishable nature of fresh derivatives like coconut water necessitates a robust and expensive cold chain infrastructure, limiting market access in regions with less developed logistics networks.
Strategic Opportunities
- Nutraceutical and Functional Foods:The extraction of medium-chain triglycerides (MCTs) from coconut oil presents a significant opportunity in the sports nutrition and dietary supplement markets, where demand for functional ingredients is high.
- Fermented Product Innovation:Combining coconut milk and cream with advanced fermentation cultures allows for the creation of novel, plant-based yogurts and cheeses with enhanced flavor profiles, appealing to sophisticated consumer palates.
- Geographic Market Expansion:Underpenetrated markets in Eastern Europe and Latin America, where plant-based food trends are nascent, offer growth opportunities for exporters of finished coconut-based consumer products.
Industry Challenges
- Regulatory Compliance Burden:Exporters face the operational challenge of aligning product formulations and labeling with the divergent and evolving standards of bodies like the US FDA, the EU's EFSA, and India's FSSAI.
- Supply Chain Transparency:Establishing and documenting fully traceable and sustainable supply chains to satisfy corporate ESG mandates and consumer demand for ethical sourcing remains a significant cost and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Derivatives Market |
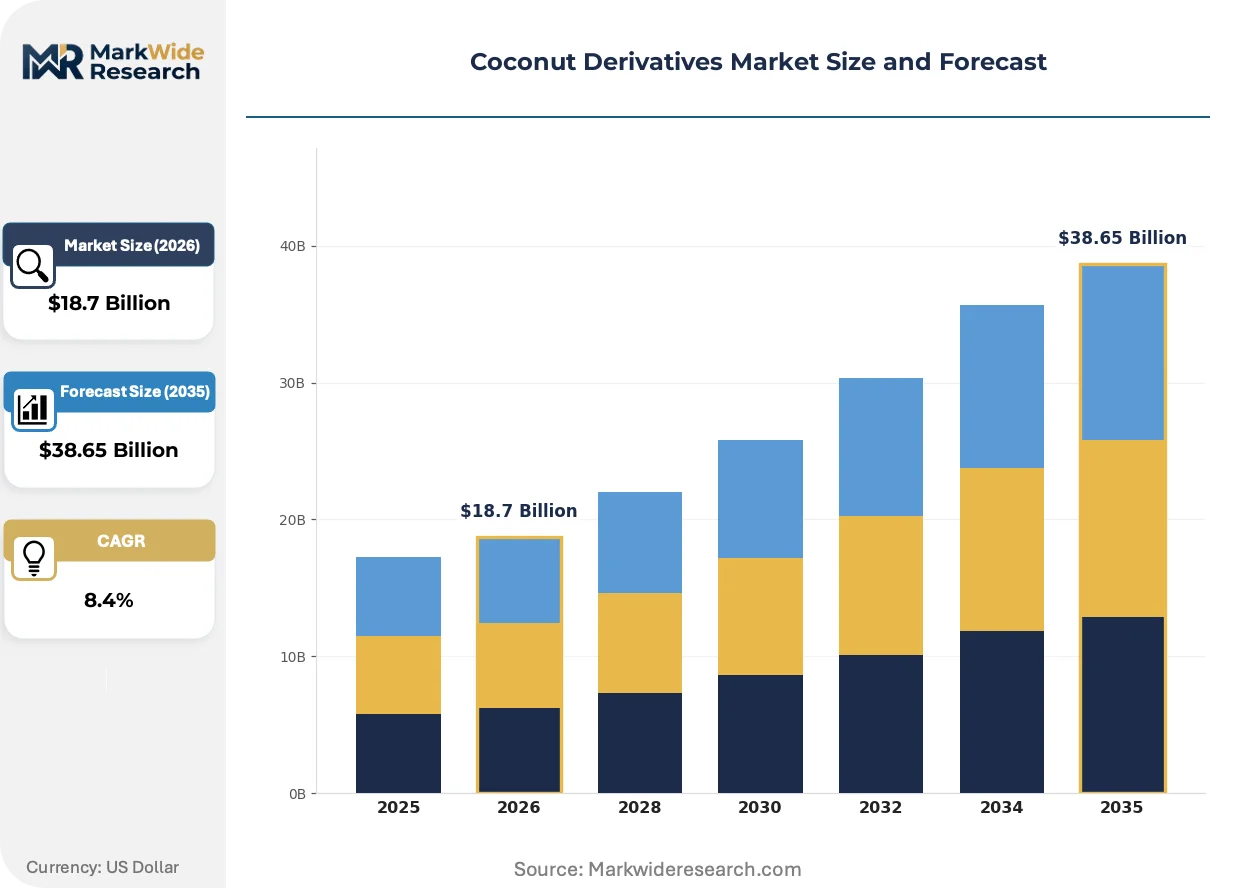
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Coconut Flour, Virgin Coconut Oil, Activated Charcoal, Desiccated Coconut Application: Food & Beverage, Cosmetics & Personal Care, Pharmaceuticals, Animal Feed, Industrial End User Industry: Food Processing Units, Beauty & Wellness Centers, Pharmacies, Pet Food Manufacturers, Chemical Plants Packaging Type: Plastic Bottles, Glass Jars, Sachets, Cans, Bulk Containers |
| Companies Covered | The Sambu Group, Superstar Coconut Products Co., Inc., The Vita Coco Company, Inc., Renuka Holdings PLC, Theppadungporn Coconut, Marico Limited, Celebes Coconut Corporation, PT Global Coconut, Thai Coconut Public Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Derivatives Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward ingredient functionality and verifiable sustainability. This movement is driven by health-conscious consumer segments and regulatory pressures on food system transparency, compelling innovation in both processing and sourcing practices.
Advanced extraction technologies are enabling the isolation of high-value compounds. For instance, supercritical CO2 extraction produces highly pure, solvent-free oils and functional ingredients. Nutraceutical and premium cosmetic formulators are the primary adopters of these methods. Product development is migrating from crude mechanical pressing toward these precise fractionation techniques to unlock specific bioactive components from the coconut endosperm.
European Union regulations on corporate responsibility are altering procurement requirements. The Corporate Sustainability Reporting Directive (CSRD) compels large companies to disclose supply chain environmental and social impacts. This forces major food and cosmetics importers to demand verifiable proof of sustainable agriculture and fair labor practices from their coconut suppliers. The derivatives segment most affected is bulk coconut oil, where traceability has historically been limited.
A notable behavioral shift is occurring in buyer specifications, particularly within the cosmetics sector. Formulators are increasingly moving beyond generic bulk coconut oil, instead demanding certified-origin products like fair-trade virgin coconut oil for clean-beauty applications. This trend disrupts the traditional commodity trading model, favoring suppliers who can provide detailed provenance documentation. The shift is most pronounced in North American and Western European consumer markets.
Coconut Derivatives Market Segmentation
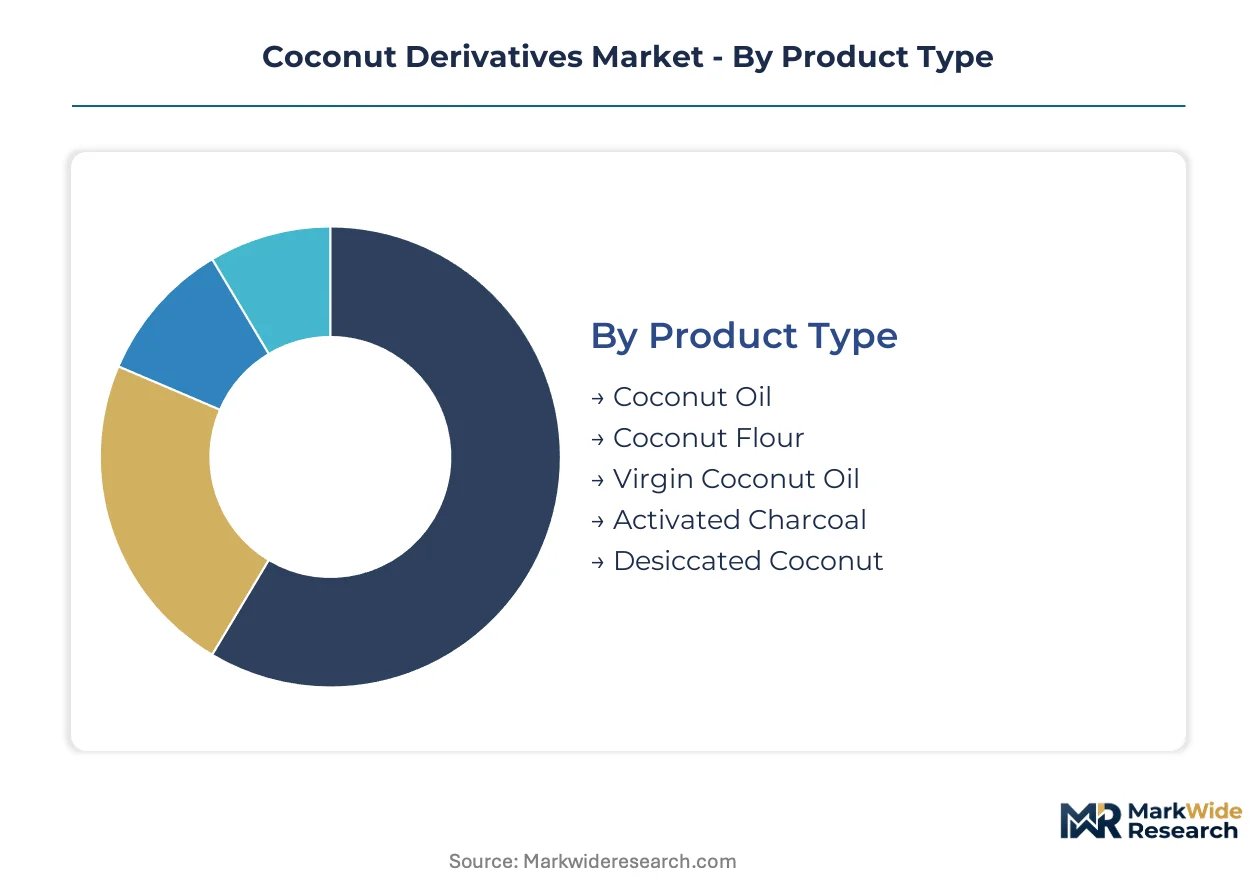
The Coconut Derivatives Market exhibits diverse segmentation across its various forms and applications, reflecting the fruit's extensive utility. Understanding these distinct market segments provides clarity on demand drivers and competitive dynamics, enabling strategic focus for stakeholders.
Product Type:
The varied cost tiers within product types highlight distinct processing methods and market values.
- Virgin Coconut Oil:This product is cold-pressed and unrefined, extracted from fresh coconut meat, preserving its natural aroma and nutrients. Demand is concentrating in North America and Europe for clean-beauty applications and health-conscious food consumers, driven by perceived purity and minimal processing.
- Coconut Oil:This refined, bleached, and deodorized (RBD) oil is typically derived from dried copra, offering a neutral flavor and higher smoke point. Demand is robust in India and Southeast Asia for traditional cooking and industrial applications, supported by its cost-effectiveness and versatile use.
- Coconut Flour:This fine powder is produced from dried coconut meat after oil extraction, serving as a popular gluten-free alternative in various baking and culinary applications.
- Activated Charcoal:Highly porous carbon derived from carbonized coconut husks, valued for its adsorptive properties in water filtration, cosmetics, and detoxification products.
- Desiccated Coconut:This product consists of shredded, dried coconut meat, widely utilized as an ingredient in confectionery, baked goods, and breakfast cereals globally.
Coconut Oil commands the established base. The steepest expansion runs through Virgin Coconut Oil.
Application:
The diverse application spectrum demonstrates the versatility of coconut derivatives across various industries.
- Food & Beverage:This segment extensively utilizes coconut milk, cream, oil, and flour in dairy alternatives, baked goods, savory dishes, and beverages. The global plant-based food movement, particularly in North America and Western Europe, drives consumption of coconut milk and cream products.
- Cosmetics & Personal Care:This sector incorporates virgin coconut oil, activated charcoal, and coconut water for moisturizing, cleansing, and anti-aging formulations across skin and hair care products. Clean beauty trends and natural ingredient preferences in the US and EU boost product development within this category.
- Pharmaceuticals:Coconut oil derivatives, such as medium-chain triglycerides (MCTs), find utility in drug delivery systems and nutritional supplements due to their unique metabolic properties.
- Animal Feed:Coconut meal, a byproduct of oil extraction, is incorporated as a protein and energy source in livestock and poultry diets.
- Industrial:Coconut shell charcoal is employed in the production of activated carbon for various industrial filtration processes and other chemical applications.
Food & Beverage remains the largest application area. Cosmetics & Personal Care exhibits the fastest growth trajectory.
End User Industry:
Customer type segmentation reveals distinct procurement patterns and specific product requirements.
- Food Processing Units:These units procure bulk coconut derivatives like oil, milk, and flour as essential ingredients for manufacturing packaged foods, beverages, and confectionery products. There is high volume demand from large-scale food manufacturers in Asia and Europe for developing plant-based product lines.
- Beauty & Wellness Centers:These centers utilize coconut oil, activated charcoal, and other derivatives in spa treatments, hair care, and skin care services offered directly to consumers. Growing consumer preference for natural ingredient-based personal care services in urban centers globally fuels this segment.
- Pharmacies:These establishments distribute pharmaceutical-grade coconut oil and MCT supplements, catering to health and wellness-conscious consumers seeking dietary aids.
- Pet Food Manufacturers:These companies incorporate coconut meal and oil into pet diets, leveraging their nutritional benefits for animal health and well-being.
- Chemical Plants:These industrial facilities utilize coconut shell derivatives for activated carbon production and as raw materials for various other specialized industrial chemicals.
Food Processing Units represent the primary end-user segment. Beauty & Wellness Centers are expanding most quickly.
Packaging Type:
Volume considerations heavily influence the selection of appropriate packaging types across the supply chain.
- Bulk Containers:This category includes large-volume packaging solutions such as drums, intermediate bulk containers (IBCs), and tanker trucks, designed for industrial and food service clients. There is high-volume procurement by food processing units and cosmetic manufacturers in Southeast Asia and Europe.
- Plastic Bottles:This common retail packaging choice for coconut oil, milk, and water offers convenience, affordability, and ease of handling for consumers. Widespread consumer adoption in North America and Asia-Pacific is due to product visibility and shelf appeal.
- Glass Jars:This premium packaging option is frequently used for virgin coconut oil and gourmet coconut products, appealing to eco-conscious consumers and those seeking higher quality.
- Sachets:Single-serve or small-portion packaging for coconut milk powder or oil, these are popular in developing markets due to their affordability and convenience.
- Cans:Hermetically sealed packaging for coconut milk and cream, cans ensure extended shelf life and product integrity for retail distribution across various climates.
Bulk Containers dominate industrial procurement. Sachets are gaining traction in emerging consumer markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for coconut derivatives shows varying elasticity across global markets, with premium segments in developed economies exhibiting lower price sensitivity for specialty products like virgin coconut oil. Conversely, bulk commodity markets in producing regions remain highly susceptible to price fluctuations driven by supply-side dynamics. This divergence shapes investment and distribution strategies for market participants.
United States
Consumer demand for plant-based dairy alternatives and clean-label cosmetics drives consumption of coconut milk and virgin coconut oil. The US FDA regulations on food additives and labeling ensure product safety and transparency for consumers. California's health-conscious consumer base and numerous natural food retailers lead product innovation and market penetration.
India
Traditional culinary uses and the extensive distribution network for coconut oil sustain significant market volume. The FSSAI's food safety and organic certification standards influence product quality and market access for producers. Kerala and Tamil Nadu, major coconut-producing states, are centers for both raw material supply and processing activities.
Indonesia
Investment in modern processing infrastructure is expanding the capacity for producing various coconut derivatives, reducing post-harvest losses. Government initiatives, such as those promoting sustainable agriculture, aim to enhance the competitiveness of coconut farmers. Sumatra and Sulawesi host growing numbers of facilities specializing in coconut milk and desiccated coconut production.
Germany
European consumer preferences for vegan products and natural cosmetic ingredients fuel the import of high-quality coconut derivatives. EFSA guidelines on novel foods and organic certification dictate market entry requirements for suppliers. Berlin and Hamburg serve as key distribution hubs for plant-based food and clean beauty product manufacturers across Europe.
Philippines
This nation's strategic focus on value-added processing is shifting exports from raw copra to higher-margin products like virgin coconut oil. The Department of Agriculture supports programs to improve coconut productivity and processing efficiency. Davao and Quezon provinces are significant areas for coconut cultivation and advanced processing operations.
Coconut Derivatives Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a distinct market structure. The coconut derivatives market exhibits a tiered competitive landscape, with large integrated players coexisting with specialized niche producers. Strategic archetypes include commodity processors, consumer brand owners, and ingredient specialists focusing on specific applications. Portfolio diversification and capacity expansion are dominant competitive moves among market participants.
Within the branded consumer goods segment, The Vita Coco Company, Inc. exemplifies a player leveraging strong brand recognition in the ready-to-drink beverage category, targeting health-conscious consumers in developed economies. Marico Limited, an India-based entity, anchors the regional market with its extensive distribution network for coconut oil, catering to traditional and industrial demand across a vast consumer base. Theppadungporn Coconut, a Thai-based producer, represents a specialist in broad-portfolio, food-grade coconut products for international export markets, emphasizing product quality and diverse applications. These companies collectively illustrate the varied approaches to market penetration and value creation within the industry.
| Leading Market Players |
|---|
| The Sambu Group |
| Superstar Coconut Products Co., Inc. |
| The Vita Coco Company, Inc. |
| Renuka Holdings PLC |
| Theppadungporn Coconut |
| Marico Limited |
| Celebes Coconut Corporation |
| PT Global Coconut |
| Thai Coconut Public Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Indonesia's expanding processing infrastructure, driven by government incentives, increases the global supply of processed derivatives, influencing supplier behavior and overall pricing stability.
Pricing Analysis
Premium product segments, such as certified virgin coconut oil, drive higher value capture within the market. Pricing operates on a hybrid model, combining commodity spot rates for bulk products with contract-based pricing for specialized derivatives. Quality grade, organic certification, and brand premium act as key differentiation drivers. Pricing pressure stems from raw material supply volatility due to climate vulnerability in Southeast Asia. Developed economy consumers purchasing specialty products exhibit lower price sensitivity compared to bulk buyers in producing regions.
Supply Chain Analysis
Extended payment terms for bulk commodity orders influence cash flow management for many coconut derivative suppliers. Geographic supply concentration centers on Indonesia and the Philippines, which are major raw material sources. The market draws from fresh coconut meat and copra as primary inputs. Supply chain risk arises from climate vulnerability, particularly typhoons and droughts in Southeast Asia. Distribution runs through both large industrial buyers and consumer-facing retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coconut derivatives market presents a high-growth disruption, driven by evolving clean-label food regulations from bodies like the US FDA and EFSA. This regulatory inflection compels innovation in ingredient sourcing and product formulation.
For Market Incumbents: Pre-empt market share erosion by investing in advanced extraction technologies for high-value compounds, countering substitution from other plant sources like oat and almond. Consolidate processing infrastructure in key producing nations such as Indonesia to reduce post-harvest losses. Leverage organic certification investment to capture higher-margin segments in North America and Europe. This strategy mitigates margin pressure from bulk commodity price volatility.
For New Entrants and Emerging Players: Underpenetrated markets in Eastern Europe and Latin America represent a significant entry point for finished coconut-based consumer products. Focus on developing novel, plant-based yogurts and cheeses through fermentation, appealing to sophisticated consumer palates. The cosmetics sector offers penetrable white space for certified-origin virgin coconut oil, aligning with clean-beauty trends. A direct-to-consumer online sales model can establish brand presence quickly.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainable agriculture and functional ingredients play because of persistent consumer demand for plant-based and clean-label products. Target acquisition profiles include mid-sized processors specializing in value-added derivatives or companies with strong brand recognition in the nutraceutical space. The expansion of certified sustainable supply chains, driven by regulations like the EU's CSRD, is a critical signal to watch. This indicates maturing ethical sourcing practices.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | This move optimizes production efficiency and reduces post-harvest losses in key producing nations like Indonesia. |
| Organic Certification Program Investment | Securing organic certifications captures premium pricing segments in North American and European consumer markets. |
| Product Portfolio Diversification (Fermented Coconut) | Innovation in fermented coconut products appeals to sophisticated palates and expands plant-based dairy alternatives. |
| Direct-to-Consumer Channel Development | Establishing D2C channels bypasses traditional retail, improving margin capture for consumer-facing brands. |
| Supply Chain Traceability Technology Adoption | Implementing traceability solutions meets corporate ESG mandates and satisfies consumer demand for ethical sourcing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA reports, EFSA publications, and customs trade data. Primary interviews engaged food processing executives, cosmetics formulators, and agricultural cooperative leaders. This approach ensured comprehensive data validation through both bottom-up and top-down triangulation. Logistics managers also provided critical insights into distribution challenges.
Forecast inputs considered include evolving consumer preferences, regulatory changes, and infrastructure development over the projection horizon. The analytical framework models market dynamics across product type, application, end-user industry, and regional demand patterns. Compound annual growth rates were derived from historical data analysis and projected market drivers. Coconut yield per hectare and processing capacity utilization rates serve as key industry inputs.
Practitioners should monitor climate-related supply disruptions and new plant-based alternative introductions for early signals. Forecasts reflect assumptions regarding market evolution and consumer adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Tuberose Extract Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Diastatic Malt Market
Ingredients
Agar Market
Ingredients
Fermentation Ingredient Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
US Choline Bitartrate Market
Ingredients
Pea Starch Market
Ingredients
Global Dry Yeast Market
Ingredients
Europe Corn Glucose Market
Ingredients
US Vegetable Oil Market
Ingredients
Asia-Pacific Carrageenan Market
Ingredients
Interesterified CBE Market
Ingredients
Bean Flour Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Olive Leaf Extract Market