
 Cheese Cultures Market | 2026-2036
Cheese Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Cultures Market Analytics
EU F-Gas Regulation is consolidating refrigeration-dependent culture supply chains around lower-carbon alternatives. Chr. Hansen leverages its Copenhagen R&D hub to anchor thermophilic strain development for industrial mozzarella. Lactalis Group sustains backward integration into culture propagation through its dairy cooperative network across France and Italy. FrieslandCampina competes on mesophilic bulk supply to Northern European cheddar operations.
Cheese cultures comprise defined-strain microbial preparations of lactic acid bacteria, including Lactococcus, Streptococcus, and Lactobacillus species, formulated at concentrations between 10^6 and 10^12 CFU per gram for controlled fermentation of milk proteins into curd. Their primary function is to standardize acidification rates, texture development, and flavor compound formation across batch-scale and continuous cheese manufacturing. Mesophilic cultures dominate volume in cheddar and Gouda production where moderate temperature ranges reduce energy input, while thermophilic strains capture margin pools in stretched-curd and hard-grating segments requiring elevated cooking temperatures. Probiotic-enhanced cultures are gaining traction in functional positioning for soft cheese and fresh dairy, though aroma-type specialty blends remain niche due to formulation complexity and shorter shelf life.
FDA standards for GRAS self-determination and USDA organic certification shape strain documentation requirements for US market access, while EFSA QPS lists and EMA guidelines govern culture safety assessments across European dairy operations. Compliance with ISO 22000 and FSSC 22000 food safety management systems has become a baseline procurement filter for industrial cheese manufacturers auditing culture suppliers. Stakeholders must monitor evolving strain patent landscapes and CRISPR-edited culture regulatory pathways to anticipate which fermentation technologies will secure commercial clearance ahead of competitor filings.
Market Dynamics
EU F-Gas Regulation is forcing refrigeration-dependent culture supply chains toward lower-carbon alternatives, compressing margins for cold-chain-intensive suppliers while advantaging thermophilic strain developers with ambient-stable formulations. This regulatory pressure intersects with tightening protected designation of origin rules that require documented culture provenance for artisanal cheese labeling.
Growth Catalysts
- EFSA QPS List Expansion:The European Food Safety Authority's qualified presumption of safety framework accelerates novel strain approval timelines, reducing regulatory friction for culture innovators targeting European mozzarella and hard-grating segments.
- Artisanal PDO Compliance:Protected designation of origin rules in France and Italy mandate traceable culture sourcing, creating captive demand for documented strain heritage among small-batch producers.
- Thermophilic Strain Premiumization:Elevated cooking temperatures in stretched-curd production drive specification upgrades, with industrial mozzarella operations in Wisconsin and Lombardy paying sustained premiums for high-temperature-stable cultures.
Market Restraints
- Refrigeration Cost Volatility:Cold-chain-dependent mesophilic cultures face margin erosion from energy price spikes and F-Gas phase-down compliance costs across European distribution networks.
- Strain Patent Concentration:Intellectual property holdings cluster among Copenhagen-based R&D hubs and Dutch cooperative networks, limiting independent culture house access to thermophilic performance traits.
- Probiotic Shelf-Life Limitation:Functional culture formulations with enhanced microbial viability sacrifice stability, constraining geographic reach and inventory holding periods for soft cheese applications.
Strategic Opportunities
- USDA Organic Certification Pathway:American artisanal producers seek compliant culture alternatives as organic dairy acreage expands, creating white space for documented non-GMO strain suppliers.
- CRISPR-Edited Strain Pipeline:Precise genome editing unifies acidification control with aroma compound engineering, though regulatory clearance timelines remain uncertain under FDA GRAS self-determination pathways.
- Direct-to-Producer Digital Channels:Small-batch creameries in Vermont and Normandy bypass traditional distributor markups through strain-specific e-procurement platforms with batch-traceability documentation.
Industry Challenges
- ISO 22000 Audit Burden:Food safety management certification requirements strain quality assurance staffing at mid-size culture houses, extending customer onboarding timelines.
- Legacy Dairy Cooperative Integration:Backward-integrated dairy groups with in-house culture propagation resist third-party strain switching, locking out independent suppliers from established supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Cultures Market |
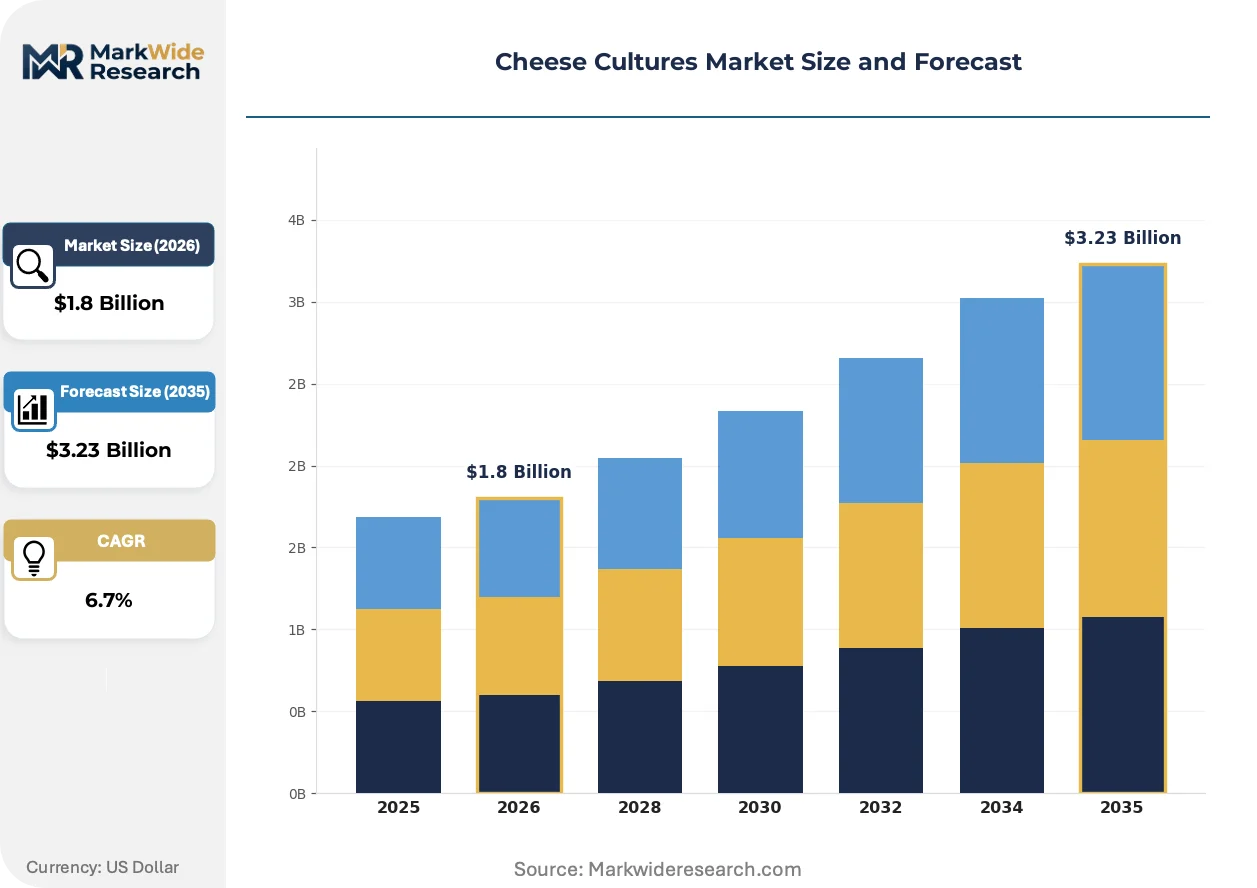
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Culture Type: Mesophilic, Thermophilic, Probiotics, Aroma Product Form: Liquid, Powder, Granular, Paste End Use: Artisanal Cheese, Industrial Cheese, Soft Cheese, Hard Cheese Packaging Type: Bulk, Sachets, Pouches, Jars |
| Companies Covered | Lactalis Group, Fonterra Co-operative Group, Arla Foods, The Kraft Heinz Company, Saputo Inc., FrieslandCampina, Bel Group, Dairy Farmers of America, Savencia SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Cultures Market Evolving Landscape
Active fermentation technologies and regulatory compliance architectures are compressing traditional culture development cycles while fragmenting procurement authority across cheese manufacturing tiers. These shifts favor suppliers with documented strain characterization and rapid regulatory response capabilities.
CRISPR-Cas9 editing platforms are unifying multiple functional traits—accelerated acidification, phage resistance, and targeted proteolysis—within single-strain chassis designs. Industrial mozzarella producers in the US upper Midwest and Italian Lombardy region are piloting these edited cultures under confidential supply agreements. The technology is unifying previously separate starter and adjunct culture purchases into consolidated strain contracts, reducing supplier count per plant.
F-Gas Regulation phase-down mandates are restructuring European cold-chain infrastructure, with EMA-aligned safety assessments now incorporating refrigeration carbon intensity into culture transport documentation. Cheese manufacturers in the Netherlands and Denmark face compressed timelines to qualify ambient-stable thermophilic alternatives. The regulation most affects soft cheese and fresh dairy segments with short production cycles and temperature-sensitive probiotic additions.
Buyer consolidation among private-label retailers is fragmenting strain specification authority, with procurement teams at centralized dairy groups now dictating culture choices previously made by individual plant microbiologists. Direct strain sourcing from culture houses is replacing traditional distributor intermediation in the cheddar belt of England and Ireland. This disintermediation is most visible in mature cheese categories where standardized performance specifications dominate over artisanal heritage claims.
Cheese Cultures Market Segmentation
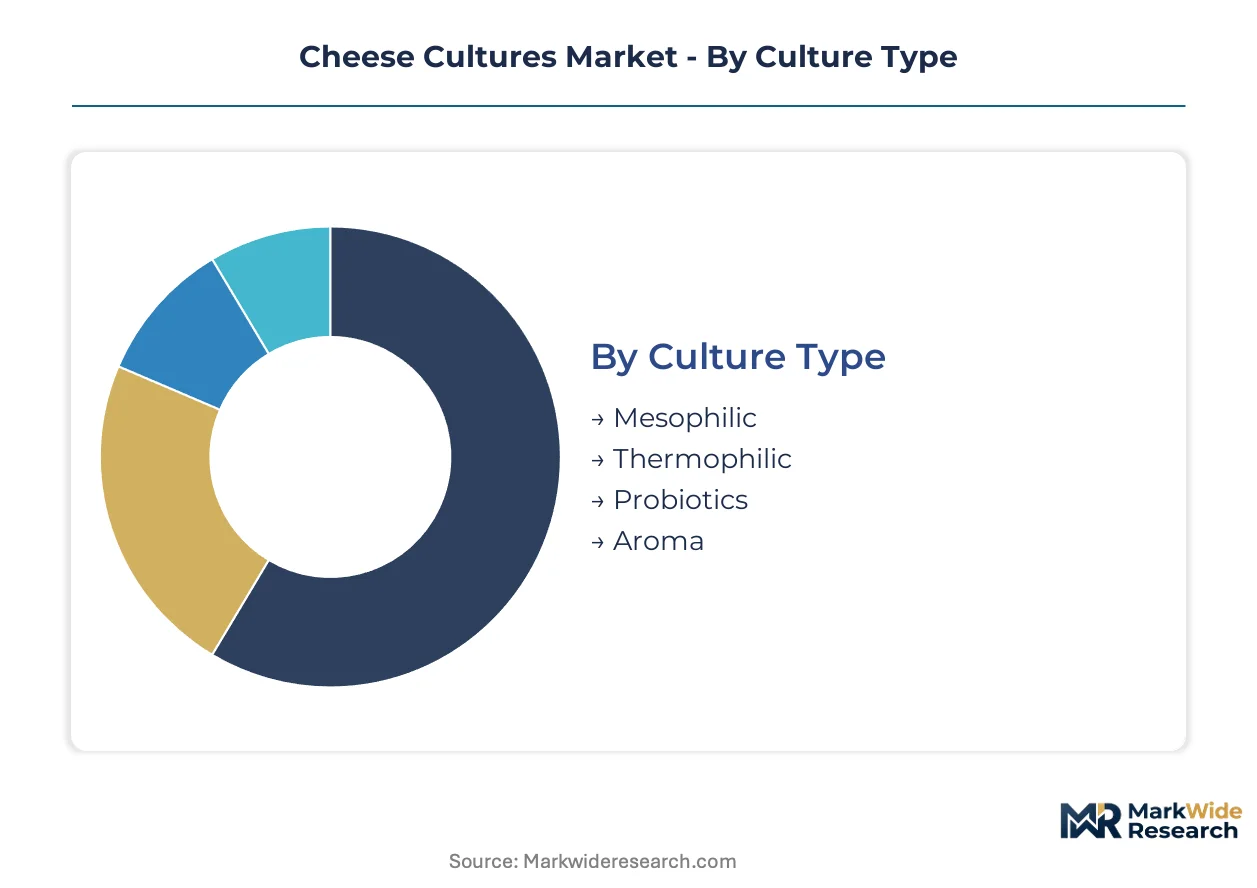
Cheese culture suppliers must align strain portfolios against divergent capital requirements across fermentation infrastructure, formulation complexity, and end-use certification demands. Segmentation reveals where margin pools concentrate versus where volume scales.
Culture Type:
Thermophilic strains demand the heaviest R&D capitalization due to high-temperature stability engineering and phage resistance development.
- Mesophilic:Defined-strain preparations of Lactococcus lactis and Leuconostoc species operate at 20-30°C, dominating cheddar and Gouda acidification. Demand concentrates in Northern European cooperative dairies where energy-efficient moderate-temperature processing reduces operational expenditure.
- Thermophilic:Streptococcus thermophilus and Lactobacillus delbrueckii subspecies engineered for 45-50°C performance command specification premiums. Wisconsin mozzarella plants and Lombardy pasta filata operations sustain premium procurement for high-temperature-stable cultures with documented phage resistance.
- Probiotics:Lactobacillus rhamnosus and Bifidobacterium-enhanced formulations target functional soft cheese positioning with viability maintenance challenges.
- Aroma:Adjunct cultures with targeted diacetyl and ester production remain niche due to formulation complexity and shorter distribution windows.
Mesophilic strains absorb the bulk of installed fermentation capacity; thermophilic cultures are expanding most quickly in specification-driven mozzarella segments.
Product Form:
Form selection tracks customer scale, with large processors favoring bulk liquid delivery and artisanal operators prioritizing shelf-stable convenience.
- Liquid:Concentrated frozen suspensions at 10^11-10^12 CFU per milliliter serve industrial continuous-processing lines with calibrated dosing infrastructure. Major cheddar manufacturers in England and Ireland specify liquid delivery for automated inoculation systems.
- Powder:Lyophilized preparations with 12-24 month ambient stability dominate distributor inventories and small-batch procurement. French PDO creameries in Normandy and Auvergne rely on powder formats for intermittent production scheduling.
- Granular:Free-flowing dried preparations with reduced dust generation suit intermediate-scale operations without liquid nitrogen storage.
- Paste:Refrigerated concentrated slurries with 4-8 week shelf life serve regional fresh cheese producers with short production cycles.
Liquid formulations anchor industrial throughput; powder formats are gaining share fastest in direct-to-producer digital channels.
End Use:
Application segmentation separates heritage-documented artisanal requirements from performance-standardized industrial specifications.
- Artisanal Cheese:Small-batch producers require strain provenance documentation for PDO compliance, with EFSA QPS-listed heritage cultures commanding sourcing premiums. French Comté and Italian Parmigiano-Reggiano consortia mandate traceable culture genealogy.
- Industrial Cheese:High-volume cheddar and mozzarella operations prioritize acidification consistency and phage resistance over heritage claims. US upper Midwest plants specify standardized performance metrics with batch-to-batch coefficient of variation below 5%.
- Soft Cheese:Fresh and bloomy-rind categories with short aging cycles favor rapid acidification strains with minimal proteolytic activity.
- Hard Cheese:Extended aging segments require controlled autolysis and amino acid metabolism for flavor precursor development.
Industrial cheese production concentrates volume procurement; artisanal segments are climbing the fastest as EU labeling rules tighten.
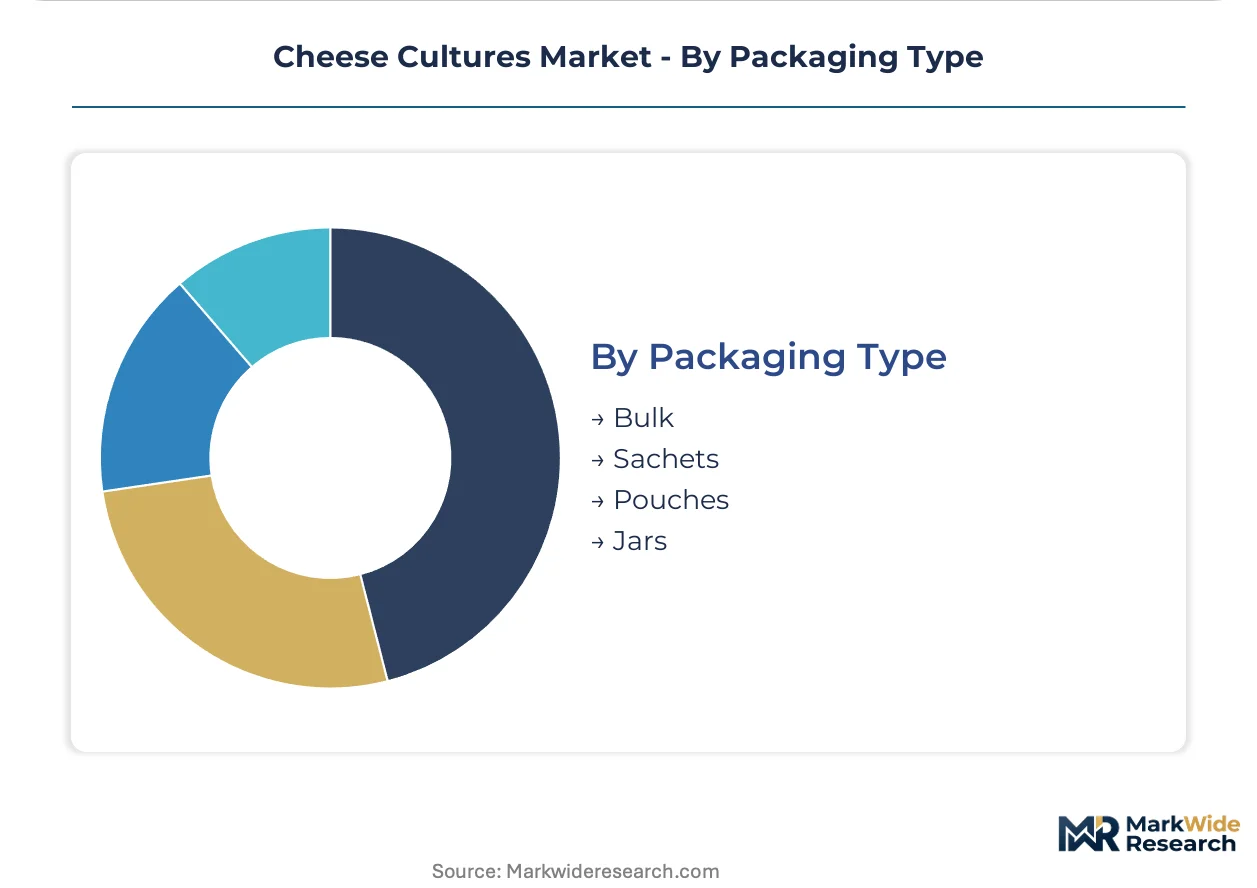
Packaging Type:
Packaging configuration reflects inventory velocity, customer scale, and cold-chain dependency tradeoffs across distribution networks.
- Bulk:20-200 liter containers or 10-25 kilogram bags serve large manufacturers with dedicated culture storage and rapid consumption turnover. Dutch cheddar cooperatives specify bulk delivery with ISO 22000 documentation.
- Sachets:Single-use aluminum-laminate packets with nitrogen flush protect viability for artisanal producers with intermittent demand. Vermont farmstead creameries favor sachet formats for strain variety without inventory risk.
- Pouches:Multi-dose flexible packaging with resealable closures suits mid-size operations balancing convenience with unit economics.
- Jars:Glass or HDPE containers with desiccant inserts target retail hobbyist and educational markets outside commercial dairy.
Bulk packaging dominates tonnage movement; sachet formats are expanding most quickly in specialty and direct-shipment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Wisconsin and Lombardy concentrate thermophilic strain demand through mozzarella processing incentives. EU F-Gas Regulation phase-downs redirect cold-chain investment toward ambient-stable formulations. Artisanal cluster development in Vermont and Normandy accelerates direct-procurement platform adoption.
United States
USDA organic certification expansion drives non-GMO culture sourcing across upper Midwest cheddar operations. FDA GRAS self-determination pathways accommodate CRISPR-edited strain pilot programs. Wisconsin mozzarella plants sustain premium thermophilic procurement through cooperative processing infrastructure.
France
Protected designation of origin enforcement tightens culture genealogy documentation for Comté and Roquefort consortia. ANSM safety assessments align with EMA guidelines for probiotic-enhanced formulations. Auvergne creameries expand backward integration into cooperative culture propagation networks.
Italy
PDO rules for Parmigiano-Reggiano mandate traceable Streptococcus thermophilus sourcing from documented strain banks. EFSA QPS list compliance accelerates novel culture approvals for pasta filata segments. Lombardy mozzarella clusters invest in high-temperature-stable culture qualification.
Netherlands
Energy price volatility compresses margins for cold-chain-dependent mesophilic distribution across cooperative cheddar networks. F-Gas Regulation compliance timelines force ambient-stable alternative qualification. FrieslandCampina's in-house propagation locks out independent suppliers from established dairy relationships.
Denmark
Copenhagen-based R&D hubs anchor thermophilic strain patent concentration for industrial mozzarella applications. ISO 22000 certification requirements strain quality assurance staffing at mid-size culture houses. Chr. Hansen leverages domestic fermentation infrastructure for phage-resistant culture development.
Cheese Cultures Market Competitive Landscape
Danish and Dutch producers anchor the consolidated tier; French and American specialists hold differentiated positions in heritage-documented segments. The vendor base clusters around three strategic archetypes: backward-integrated dairy cooperatives with captive culture propagation, independent strain houses with EFSA QPS-listed portfolios, and diversified ingredients conglomerates with thermophilic R&D concentration. Dominant competitive moves include cooperative network expansion locking out third-party suppliers and direct-to-producer digital channel development bypassing traditional distribution.
Within the cooperative-integrated tier, Lactalis Group and FrieslandCampina occupy positions exemplifying backward integration into culture propagation through dairy network control. Chr. Hansen anchors the specialized strain development archetype with Copenhagen-based thermophilic R&D infrastructure. These three entities represent distinct competitive positions: captive supply assurance, bulk mesophilic volume leadership, and premium thermophilic specification dominance respectively.
| Leading Market Players |
|---|
| Lactalis Group |
| Fonterra Co-operative Group |
| Arla Foods |
| The Kraft Heinz Company |
| Saputo Inc. |
| FrieslandCampina |
| Bel Group |
| Dairy Farmers of America |
| Savencia SA |
| Others |
Value Network & Pricing Analysis
Backward integration into culture propagation anchors supply position and pricing power for cooperative dairy networks across France, Italy, and the Netherlands, locking independent strain houses out of established procurement relationships while compressing margins for third-party suppliers competing on specification alone.
Pricing Analysis
Short lead-time premiums apply to thermophilic strains with documented phage resistance for Wisconsin and Lombardy mozzarella plants, while spot inventory discounts emerge for standardized mesophilic preparations in Northern European cheddar operations. Three-tier pricing structure across premium, standard, and economy levels separates heritage-documented PDO cultures from industrial performance specifications and commodity bulk formulations. Price differentiation hinges on EFSA QPS certification tier and ISO 22000 documentation completeness. Cost compression in mesophilic bulk supply is intensifying because F-Gas Regulation compliance adds cold-chain overhead. Small-batch artisanal producers show least price sensitivity due to captive PDO compliance requirements.
Supply Chain Analysis
ISO 22000 and FSSC 22000 certification gating filters supplier qualification before strain procurement contracts execute, extending onboarding timelines for mid-size culture houses lacking dedicated quality assurance staffing. Supply concentrates in Denmark, the Netherlands, and France, with Copenhagen-based R&D hubs anchoring thermophilic strain patent concentration. Raw material dependencies include milk-derived nutrient media, cryoprotectant formulations, and nitrogen storage infrastructure. Single-source vulnerability runs through concentrated intellectual property holdings among Dutch cooperative networks. Distribution runs through direct-to-producer digital channels bypassing traditional distributor markups in Vermont and Normandy artisanal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-edited strain development is displacing legacy starter culture formulations, unifying acidification control with aroma compound engineering within single-strain chassis designs that reduce supplier count per plant.
For Market Incumbents: Anchor thermophilic R&D concentration through Copenhagen-based fermentation infrastructure to defend against CRISPR-edited strain patent filings from competitor hubs. Deepen backward integration into dairy cooperative networks across France and Italy to lock out independent suppliers from PDO-compliant procurement relationships. Prioritize ISO 22000 certification investment to accelerate customer onboarding timelines strained by quality assurance staffing gaps. For New Entrants and Emerging Players: CRISPR-Cas9 platform licensing offers a technology-first wedge into industrial mozzarella segments in Wisconsin and Lombardy where specification premiums sustain new entrant margins. Target USDA organic certification pathway for American artisanal producers seeking non-GMO culture alternatives as organic dairy acreage expands. Deploy direct-to-producer digital channels with batch-traceability documentation to bypass entrenched distributor relationships in Vermont and Normandy creamery clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by backward-integrated dairy cooperatives seeking captive culture supply assurance, with Copenhagen-based thermophilic specialists commanding premium multiples. Long-term viability favors strain houses with EFSA QPS-listed portfolios and documented regulatory response capabilities rather than commodity mesophilic bulk suppliers. Watch CRISPR regulatory clearance timelines under FDA GRAS self-determination pathways as inflection indicator for fermentation technology commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Strain Pipeline Development | Unifies acidification and aroma engineering to consolidate supplier contracts per plant. |
| PDO Compliance Documentation Investment | Captures heritage-premium positioning among French Comté and Italian Parmigiano-Reggiano consortia. |
| Direct-to-Producer Digital Channel Launch | Bypasses distributor markups in Vermont and Normandy artisanal procurement relationships. |
| Ambient-Stable Thermophilic Formulation | Reduces F-Gas Regulation cold-chain compliance costs across European distribution networks. |
| Cooperative Network Backward Integration | Locks out independent suppliers through captive culture propagation in France and Italy. |
Research Methodology
EFSA QPS list databases, EMA safety assessment filings, and dairy cooperative procurement records formed the secondary backbone for strain characterization and regulatory pathway mapping. Primary interviews with culture house R&D directors, dairy plant microbiologists, PDO consortium technical officers, and food safety certification auditors combined with secondary validation across ISO 22000 audit documentation and customs trade data. Bottom-up strain volume estimates triangulated against top-down cheese production statistics across the analysis window.
Historical trendline analysis of thermophilic strain specification premiums and mesophilic bulk pricing tracked across Wisconsin, Lombardy, and Northern European cooperative networks. Segmentation dimensions modeled include culture type, product form, end-use application, and packaging configuration alongside regional regulatory cluster differentiation. CAGRs derived from installed fermentation capacity expansion rates and PDO compliance-driven procurement shifts. Forecast inputs incorporated F-Gas Regulation phase-down timelines and CRISPR regulatory clearance pathway uncertainty.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CRISPR approval or delayed EFSA QPS list expansion scenarios. Projections reflect assumptions around cooperative network integration stability and artisanal cluster digital procurement adoption velocity. A model refresh is warranted upon material change in FDA GRAS self-determination pathway clarity for edited strains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Textured Soy Protein Market
Ingredients
PHO Oils Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Encapsulated Salt Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Malted Wheat Flour Market
Ingredients
Liquid Feed Market
Ingredients
Specialty Yeast Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
North America Soybean Oil Market
Ingredients
North America Vegetable Oils Market
Ingredients
Shortening Fats Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Rose Extract Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Coconut Derivatives Market