
 Trait Enhanced Oils Market | 2026-2036
Trait Enhanced Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Trait Enhanced Oils Market Analytics
Commodity oil procurement channels are rewriting how processors secure supply with defined trait specifications. Cargill Incorporated leverages its origination network to sustain identity-preserved supply chains from farm to refinery. Bunge Limited anchors its position through crushing assets located near major North American oilseed production zones. Archer Daniels Midland Company competes by extending its elevator system to handle segregated enhanced grain streams.
Trait enhanced oils are vegetable or seed oils modified through breeding, biotechnology, or processing to achieve specific fatty acid profiles, oxidative stability, or functional properties such as elevated oleic acid content above 75 percent. These oils serve industrial buyers seeking heat stability, extended fry life, or renewable feedstock compatibility. Edible oils command the largest volume position within product type segmentation due to food manufacturer reformulation demand. Biofuels represent the fastest-expanding end use industry as renewable diesel producers seek lower-carbon intensity feedstocks with improved cold-flow properties. Fuel grade classification sits at the margin-intensive frontier where technical specifications command price premiums over commodity benchmarks.
The FDA nutrition labeling framework and EPA renewable fuel standards shape product development pathways and market access conditions for trait enhanced oils in the United States. EFSA novel food assessments and REACH registration requirements in Europe create parallel compliance obligations for exporters and multinational blenders. Stakeholders must monitor evolving low-carbon fuel standards across multiple state jurisdictions and the trajectory of EU deforestation-free supply chain regulations.
Market Dynamics
CRISPR-edited oilseed breeding is collapsing trait development timelines from a decade to roughly five years, forcing processors to rebuild procurement contracts around identity-preserved supply chains rather than commodity spot markets.
Growth Catalysts
- US FDA trans fat regulations:Food processors across North America and Europe must reformulate with high-oleic alternatives to meet compliance deadlines, creating contract acreage demand for enhanced soybeans and canola.
- Renewable diesel expansion:Biofuel producers seek lower-carbon intensity feedstocks with improved cold-flow properties, pulling trait enhanced oils into fuel-grade specifications.
- Midwest processing hub concentration:Iowa, Illinois, and Indiana crushing assets anchor identity-preserved supply chains from farm to refinery.
Market Restraints
- Input cost volatility:Fertilizer and energy price swings compress margins for contract growers committed to identity-preserved protocols.
- Supply concentration risk:North American germplasm development and seed production creates geographic dependency for proprietary trait stacks.
- EFSA novel food assessments:European regulatory friction delays market access for CRISPR-edited varieties not grandfathered under conventional breeding exemptions.
Strategic Opportunities
- EU deforestation-free supply chain regulations:Traceability mandates favor identity-preserved North American origin oils over South American commodity alternatives.
- Aviation renewable fuel:Sustainable aviation fuel specifications create emerging demand for hydroprocessed esters with specific fatty acid profiles.
- Blockchain-enabled provenance tracking:Digital supply chain verification unlocks premium channel access for verified low-carbon intensity feedstocks.
Industry Challenges
- Segregation infrastructure capex:Elevator system modifications and dedicated crushing lines require capital deployment at farm-gate processors.
- CRISPR IP licensing complexity:Stacked trait development requires navigation of multiple germplasm and editing tool patent estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trait Enhanced Oils Market |
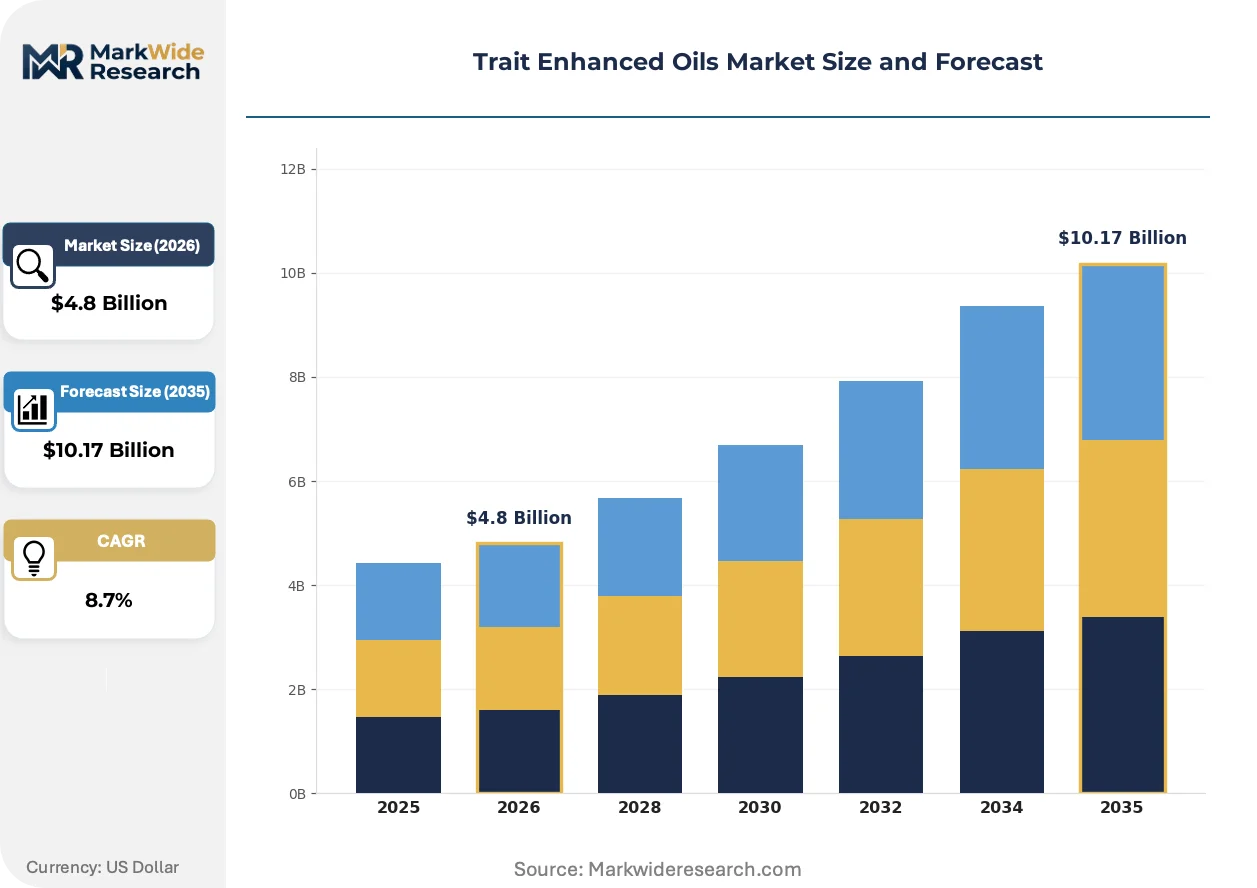
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oils, Essential Oils, Edible Oils, Fuel Oils End Use Industry: Food & Beverage, Cosmetics, Pharmaceutical, Biofuels Grade: Food Grade, Cosmetic Grade, Industrial Grade, Fuel Grade Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, DuPont, Perdue AgriBusiness, Wilmar International Limited, Bunge Limited, Louis Dreyfus Company, BASF SE, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trait Enhanced Oils Market Evolving Landscape
Gene editing platforms are compressing breeding cycles while regulatory frameworks scramble to classify novel varieties, and procurement contracts are hardcoding trait specifications into multi-year supply agreements.
CRISPR-Cas9 and base editing platforms are collapsing the economic barrier between commodity and specialty oilseeds. Renewable diesel producers in the US Midwest are locking in five-year offtake agreements for high-oleic soybeans. The technology is collapsing the premium gap between identity-preserved and commodity benchmarks.
EU Green Deal deforestation-free supply chain regulations are mandating geolocation verification for imported oilseeds. European food manufacturers are shifting sourcing toward North American origin oils with farm-level traceability. The regulation is most affecting bakery and confectionery segments reformulating for clean label positioning.
Direct contracting between end-users and grower cooperatives is displacing elevator-mediated spot purchases. Food processors are establishing captive acreage programs with defined fatty acid specifications. This pattern concentrates in the United States Corn Belt where crushing assets align with production zones.
Trait Enhanced Oils Market Segmentation
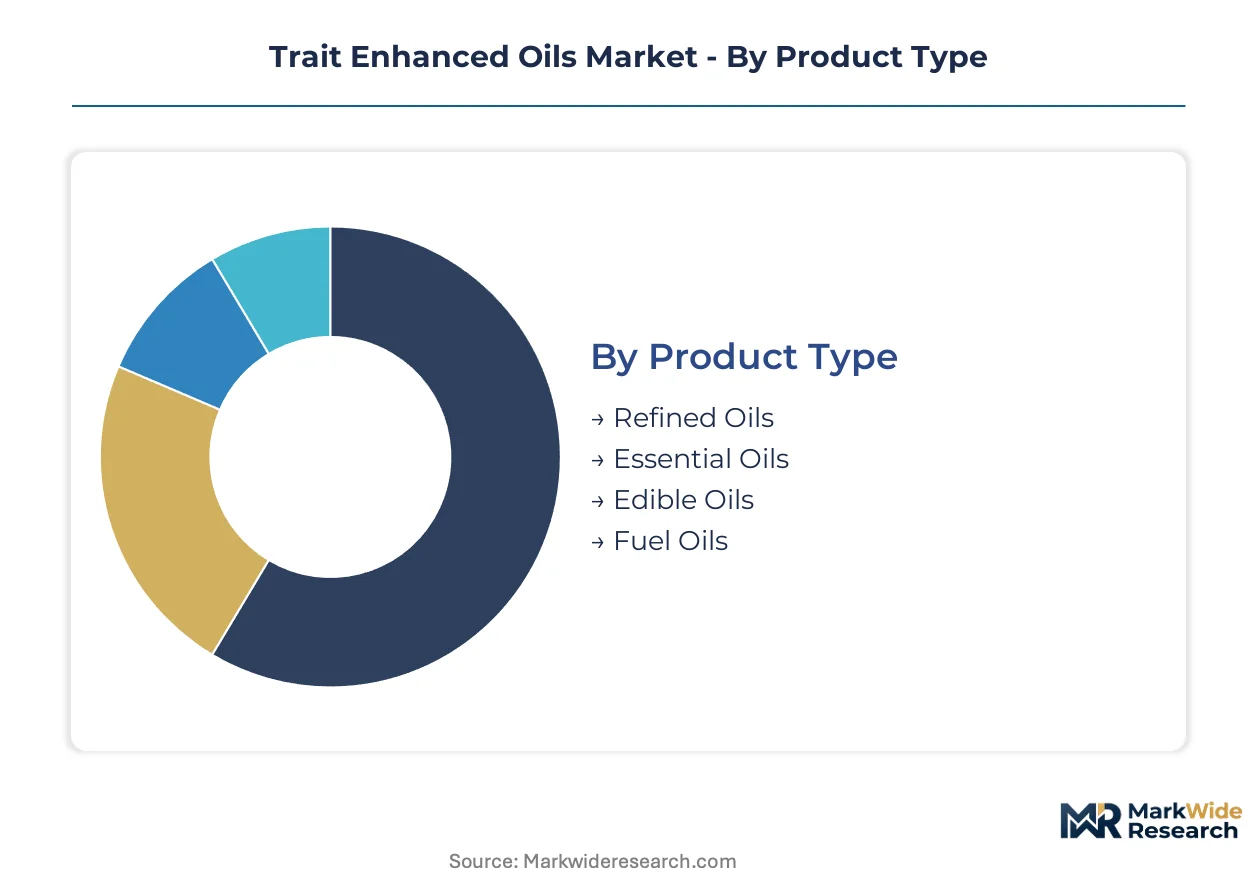
Trait specifications in enhanced oils create distinct procurement channels where identity-preserved supply chains command structural premiums over commodity benchmarks. Segmentation reveals how fatty acid profiles, regulatory classifications, and distribution infrastructure align buyer requirements with supplier capabilities across food, fuel, and industrial applications.
Product Type:
After-sales technical support intensity varies sharply across product types, with fuel and edible oils demanding sustained specification compliance versus refined commodity grades.
- Edible Oils:High-oleic soybean and canola varieties with oleic acid content exceeding 75 percent serve reformulating food manufacturers seeking heat stability and extended fry life. FDA trans fat regulations in the United States and EFSA compliance deadlines across Germany, France, and Italy are concentrating contract acreage demand in Iowa, Illinois, and Indiana processing corridors.
- Fuel Oils:Hydrotreated renewable diesel feedstocks with tailored cold-flow properties and reduced carbon intensity scores attract biofuel producers in the US Midwest. Renewable fuel standard obligations and state-level low-carbon fuel programs in California, Oregon, and Washington are pulling identity-preserved supply into long-term offtake agreements.
- Refined Oils:Processed base stocks for industrial lubricants and chemical intermediates.
- Essential Oils:Concentrated aromatic extracts for flavor, fragrance, and therapeutic applications with premium positioning.
Edible oils holds the largest share; momentum sits with fuel oils.
End Use Industry:
Application-driven cost tiers separate commodity procurement from premium identity-preserved contracting, with biofuels and pharmaceuticals occupying opposite ends of the specification-value spectrum.
- Biofuels:Renewable diesel and sustainable aviation fuel producers require hydroprocessed esters with defined fatty acid saturation levels and traceable carbon intensity scores. US EPA renewable fuel standards and emerging sustainable aviation fuel mandates in California, Netherlands, and Singapore are accelerating demand for verified low-carbon feedstocks with farm-level geolocation data.
- Food & Beverage:Bakery, snack, and foodservice operators reformulate with high-oleic alternatives to eliminate partially hydrogenated oils. Reformulation deadlines tied to FDA nutrition labeling in the United States and EFSA novel food assessments for CRISPR-edited varieties in Germany, France, and Spain are reshaping procurement toward North American origin oils with segregated supply chains.
- Cosmetics:Functional emollients and active ingredients for skincare and personal care formulations.
- Pharmaceutical:Excipients and active pharmaceutical ingredients requiring USP-grade purity certifications.
Food and beverage dominates volume; biofuels climbs the fastest.
Grade:
Margin concentration follows certification rigor, with fuel and food grades capturing value through regulatory compliance while industrial grades compete on volume throughput.
- Fuel Grade:Technical specifications for renewable diesel and sustainable aviation fuel command the steepest premiums over commodity benchmarks, with cold-flow properties and carbon intensity scores hardcoded into procurement contracts. State-level low-carbon fuel standards in California, Oregon, and Washington create jurisdictional price differentiation for verified feedstocks.
- Food Grade:Identity-preserved oils meeting FDA food safety modernization and EFSA hygiene package requirements support clean label positioning for European bakery and confectionery manufacturers. EU deforestation-free supply chain regulations favor North American origin oils with blockchain-enabled provenance verification over South American commodity alternatives.
- Cosmetic Grade:Refined specifications for dermal compatibility and stability in personal care formulations.
- Industrial Grade:Base stocks for lubricants, coatings, and chemical manufacturing with less stringent purity requirements.
Food grade maintains the largest position; fuel grade gains share fastest.
Distribution Channel:
Customer type and purchase scale determine channel selection, with direct contracting displacing traditional elevator-mediated spot markets for specification-critical buyers.
- Wholesalers:Bulk handlers and distributors manage identity-preserved inventory segregation from farm-gate intake through refinery delivery, with dedicated elevator modifications and crushing lines in Iowa, Illinois, and Indiana supporting contract acreage programs. Direct relationships between wholesalers and grower cooperatives are replacing spot market transactions for enhanced oilseeds.
- Specialty Stores:Niche retailers serve artisan food producers and small-batch cosmetic formulators requiring precise fatty acid profiles and organic certifications. Regional concentration in California, New York, and Texas metropolitan areas supports premium positioning for identity-preserved and CRISPR-edited varieties.
- Online Retail:Digital platforms connecting specialty buyers with certified producers for smaller lot sizes.
- Supermarkets:Mass-market retail channels for consumer-packaged edible oils with limited trait differentiation.
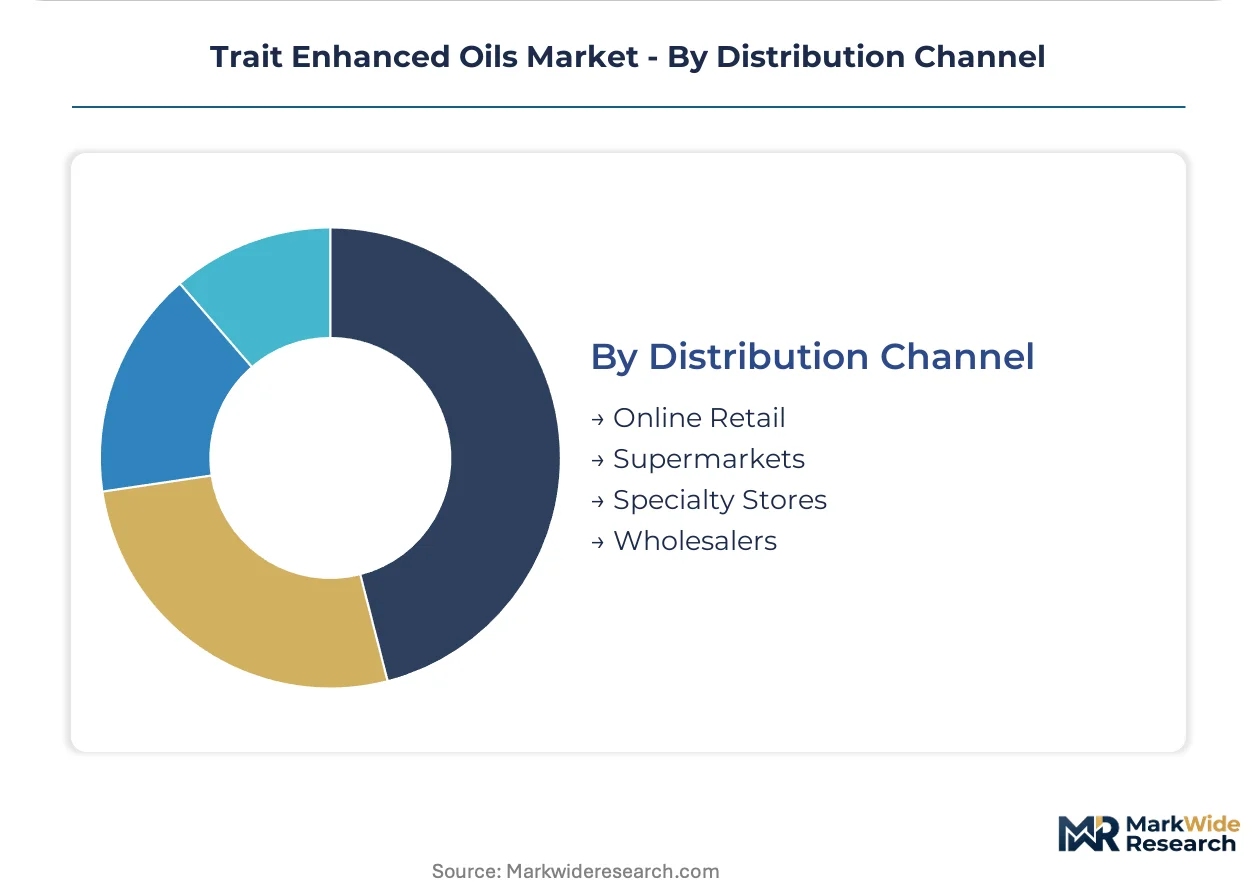
Wholesalers holds the largest share; specialty stores shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest United States processors command price premiums over European counterparts due to concentrated crushing infrastructure and streamlined identity-preserved logistics. Regulatory divergence between FDA trans fat deadlines and EFSA novel food assessment timelines creates procurement timing asymmetries across Atlantic supply chains.
United States
Renewable diesel producers in Iowa and Illinois are locking five-year offtake agreements for high-oleic soybeans with defined carbon intensity scores. EPA renewable fuel standards and California's low-carbon fuel program mandate traceable feedstock provenance from farm to refinery. The Corn Belt processing corridor stretching through Indiana anchors North American identity-preserved supply chain concentration.
Germany
Bakery and confectionery manufacturers reformulate with high-oleic alternatives to meet EFSA hygiene package compliance deadlines. REACH registration requirements for novel oilseed varieties delay market access for CRISPR-edited imports not grandfathered under conventional breeding exemptions. The Rhine-Ruhr industrial cluster hosts major oil refining and food processing facilities driving regional demand.
Netherlands
Port of Rotterdam biofuel terminals source North American origin oils with blockchain-enabled geolocation verification to satisfy EU deforestation-free supply chain regulations. EFSA novel food assessments create regulatory friction for gene-edited varieties lacking conventional breeding exemptions. Amsterdam-based trading houses coordinate European distribution of identity-preserved enhanced oilseeds.
Brazil
Soybean crushers in Mato Grosso and Paraná face margin compression as European buyers pivot toward traceable North American origin oils. ANVISA regulatory alignment with EFSA novel food frameworks limits CRISPR-edited variety commercialization. The São Paulo state industrial corridor maintains traditional commodity oil processing dominance despite traceability-driven demand shifts.
Canada
Canola processors in Saskatchewan and Manitoba expand identity-preserved acreage programs to capture EU deforestation-free regulatory premiums. Health Canada and PMRA coordinated assessments accelerate gene-edited variety approvals relative to European timelines. The Prairie Provinces crushing infrastructure supports segregated enhanced oilseed streams for export markets.
Trait Enhanced Oils Market Competitive Landscape
Agricultural processors and integrated agribusiness conglomerates split the market between identity-preserved supply chain operators and commodity-scale crushers. Three archetypes dominate: elevator-network operators with segregated grain handling capabilities, seed-to-refinery integrated players with proprietary trait stacks, and trading houses with origination reach into contract acreage programs. Competitive moves concentrate on strategic partnerships for CRISPR licensing access and backward integration into captive seed production.
Among North American agricultural processors, Cargill Incorporated, Bunge Limited, and Archer Daniels Midland Company exemplify the elevator-network archetype with crushing assets positioned near Midwest production zones. These entities occupy positions where identity-preserved infrastructure investments separate premium-channel access from commodity spot market participation.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| DuPont |
| Perdue AgriBusiness |
| Wilmar International Limited |
| Bunge Limited |
| Louis Dreyfus Company |
| BASF SE |
| DSM-Firmenich |
| Others |
Value Network & Pricing Analysis
Rail freight corridors from Iowa and Illinois to Gulf Coast refineries impose cost dynamics that amplify supply concentration effects, with identity-preserved shipment premiums widening as downstream biofuel processors hardcode fatty acid specifications into long-term contracts.
Pricing Analysis
The customization-premium spread between identity-preserved contract pricing and commodity spot benchmarks widened as CRISPR-edited variety development shortened breeding timelines. Contract-based long-term offtake agreements dominate, with price differentiation driven by carbon intensity certification tiers and volume scale commitments. Pricing pressure stems from fertilizer and energy input cost volatility compressing grower margins. Biofuel producers show lowest price sensitivity due to renewable fuel standard compliance premiums, while industrial lubricant buyers remain most cost-responsive.
Supply Chain Analysis
Upstream feedstock development centers on United States, Canada, and Brazil germplasm programs, with proprietary trait stacks creating geographic dependency. The supply chain draws from CRISPR-edited seed stocks, segregated elevator infrastructure, and dedicated crushing assets. Single-source vulnerability concentrates around North American proprietary germplasm estates. Distribution runs through processor-controlled contract acreage programs displacing traditional spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against plant-based oil alternatives and synthetic lipid technologies, with incumbents navigating reformulation demand that could pivot toward fermentation-derived or algae-based feedstocks.
For Market Incumbents: Pre-empt proprietary germplasm obsolescence by securing CRISPR licensing access across multiple editing tool patent estates. Build captive seed production capacity in Saskatchewan and Manitoba to reduce single-source dependency. Channel control through direct grower cooperative contracts defends margin position against trading house intermediation. For New Entrants and Emerging Players: Build out blockchain-enabled provenance verification services for EU deforestation-free compliance premiums, targeting Netherlands-based biofuel terminals as the most penetrable entry point. Sustainable aviation fuel specifications offer white-space positioning with less entrenched incumbent relationships. A certification-first go-to-market angle unlocks premium channel access before volume scale. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors elevator-network operators with segregated infrastructure already deployed. Long-term viability rests on identity-preserved supply chain control rather than commodity crushing scale. Watch for sustainable aviation fuel mandate acceleration as the inflection signal for feedstock specification tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Production | Captive germplasm control reduces IP licensing friction and secures trait stack exclusivity. |
| Blockchain Provenance Implementation | EU deforestation-free regulations mandate geolocation verification for premium market access. |
| Long-term Offtake Agreements | Renewable diesel producers in Iowa and Illinois lock supply visibility across breeding cycle compression. |
| Segregated Infrastructure Expansion | Dedicated elevator modifications in Indiana support identity-preserved volume scaling. |
| CRISPR Licensing Partnership | Stacked trait development requires navigation of multiple editing tool patent estates. |
Research Methodology
Desk research of USDA crop reports, EPA renewable fuel standard filings, and EFSA novel food assessment databases preceded structured interviews with oilseed breeding directors, biofuel procurement managers, and grain elevator operations heads. Primary fieldwork with processor supply chain planners and grower cooperative leaders combined with secondary validation against customs trade data and crushing capacity disclosures. Bottom-up contract acreage modeling triangulated against top-down end-use demand segmentation.
Assumptions held fixed include EPA renewable volume obligations and EU deforestation-free regulatory timelines, while CRISPR variety approval trajectories and sustainable aviation fuel mandate scope were varied across sensitivity scenarios. Segmentation dimensions spanned product type, end-use industry, grade certification, and distribution channel complexity. CAGRs derived from volume trajectory modeling incorporating crush margin forecasts and identity-preserved premium persistence assumptions. Industry-specific inputs included renewable diesel capacity buildout pipelines and EFSA novel food assessment queue status.
Sensitivities concentrate around regulatory approval timelines for gene-edited varieties and renewable fuel standard volume obligation modifications. Forecasts reflect assumptions regarding contract acreage expansion rates and crush margin sustainability. Cross-checking against USDA prospective plantings reports and EPA renewable fuel standard compliance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hexane-Free Protein Market
Ingredients
Microencapsulated Oil Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Pomace Olive Oil Market
Ingredients
Liquid Feed Market
Ingredients
Bread Flour Market
Ingredients
Yeast Derivatives Market
Ingredients
Virgin Coconut Oil Market
Ingredients
United States Corn Glucose Market
Ingredients
South America Vegetable Oil Market
Ingredients
Global Starch Derivatives Market
Ingredients
Carotenoids Market
Ingredients
Carob Powder Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Sesame Oil Market