
 South America Dairy Protein Market | 2026-2036
South America Dairy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dairy Protein Market Analytics
Precision membrane filtration and enzymatic hydrolysis is tilting production economics toward higher-value protein fractions across South American processing lines. Saputo Inc. leverages its Argentine whey processing footprint to serve regional sports nutrition formulators. Fonterra Co-operative Group anchors ocean freight logistics for bulk concentrate flows into Brazilian ports. Arla Foods Ingredients Group P/S differentiates through specialized casein variants for clinical nutrition applications.
South America dairy protein encompasses milk-derived fractions—whey, casein, and total milk proteins—separated through ultrafiltration, diafiltration, or acid precipitation, typically standardized to protein contents ranging from 34% in concentrates to 90% in isolates. These ingredients function as emulsifiers, gelling agents, and complete amino acid sources across food manufacturing and specialized nutrition. Whey protein dominates volume flows due to its superior leucine profile and rapid absorption kinetics favored by sports nutrition brands. Casein retains structural importance in clinical nutrition and bakery matrices where sustained amino acid release or moisture retention matters. The dietary supplements channel shows the steepest growth trajectory as direct-to-consumer protein powders penetrate middle-income households in Brazil and Chile.
ANVISA governs food supplement registration and labeling standards in Brazil, while Argentina's national food code authority enforces dairy protein identity specifications for cross-border trade. Both frameworks elevate compliance costs for imported concentrates but simultaneously create preference windows for locally verified processors. Stakeholders must track how MERCOSUR harmonization negotiations reshape technical barriers to intra-regional protein concentrate movements.
Market Dynamics
ANVISA's updated food supplement labeling requirements are compressing formulation transparency timelines, forcing Brazilian processors to accelerate purity verification investments while tightening procurement standards for imported whey concentrates.
Growth Catalysts
- Sports Nutrition Expansion:Brazilian, Argentine, and Colombian fitness brands are scaling direct-to-consumer protein powder distribution, creating sustained pull for whey protein isolate with superior leucine profiles.
- ANVISA Labeling Mandates:Brazil's tightened disclosure standards for food supplements are elevating demand for locally verified processors capable of batch-level traceability documentation.
- Precision Membrane Filtration:Ultrafiltration and diafiltration advances are enabling São Paulo-state processors to command premium supply contracts through higher-value protein fraction yields.
Market Restraints
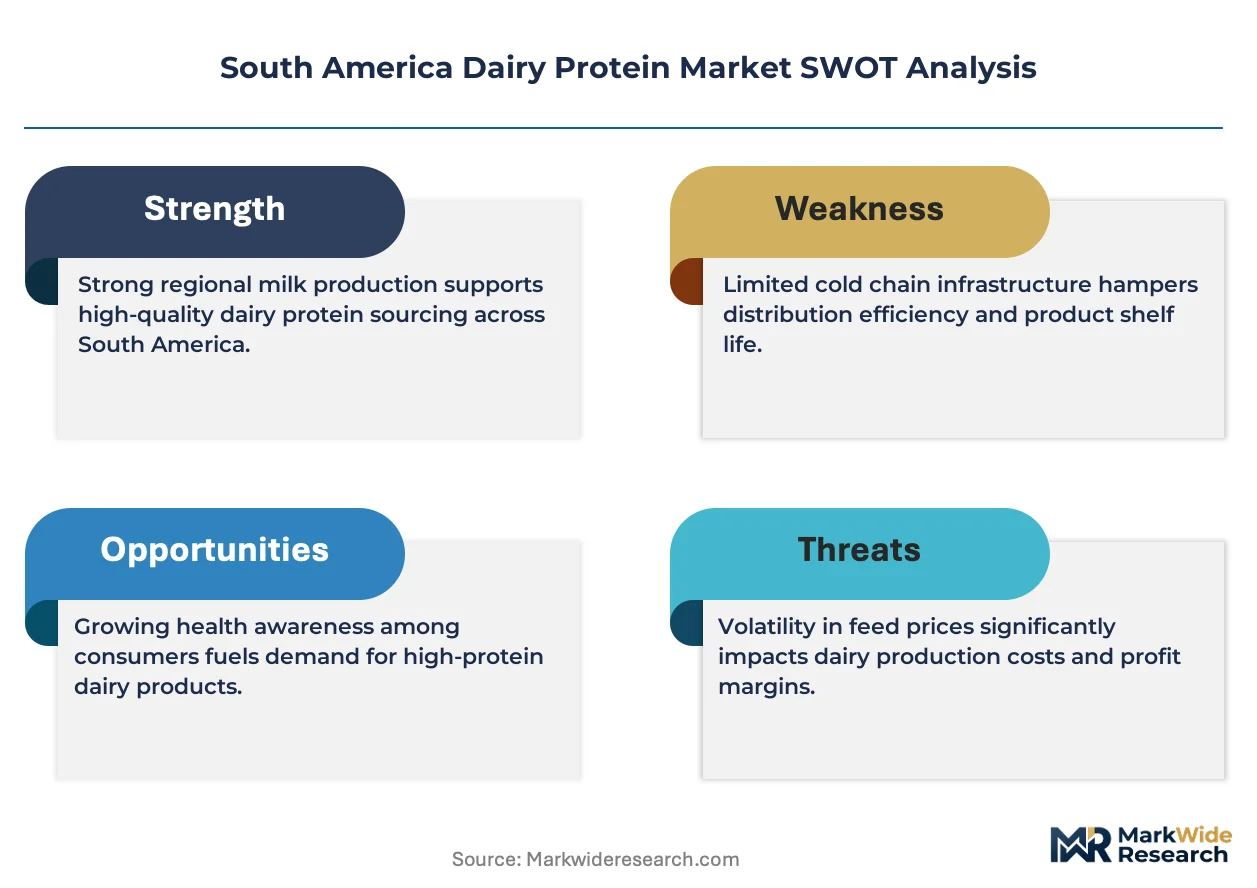
- Input Cost Volatility:Raw milk price swings in Argentina's Pampas dairy belt destabilize whey concentrate production economics for regional processors.
- Supply Concentration Risk:Brazil's southeastern dairy belt controls disproportionate fractionation capacity, creating geographic vulnerability for buyers outside São Paulo state.
- Cross-Border Regulatory Friction:MERCOSUR harmonization gaps between Brazilian ANVISA and Argentina's national food code authority generate compliance duplication costs for intra-regional concentrate movements.
Strategic Opportunities
- Colombian Market Underpenetration:Bogotá and Medellín sports nutrition channels remain underserved by specialized casein variants for clinical nutrition applications, offering first-mover positioning.
- Enzymatic Hydrolysis Convergence:Combining targeted protease systems with precision membrane filtration is opening peptide-specific product lines for medical nutrition formulators.
- Direct-to-Consumer Channel Innovation:Subscription-based protein powder models in Chilean middle-income households are bypassing traditional pharmaceutical retail distribution.
Industry Challenges
- Specialized Technician Scarcity:Diafiltration system operation and membrane maintenance expertise remains concentrated among veteran operators in São Paulo's dairy belt, constraining capacity expansion.
- ANVISA Certification Timelines:New food supplement registration protocols are extending product launch windows by 8-14 months for imported concentrate formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dairy Protein Market |
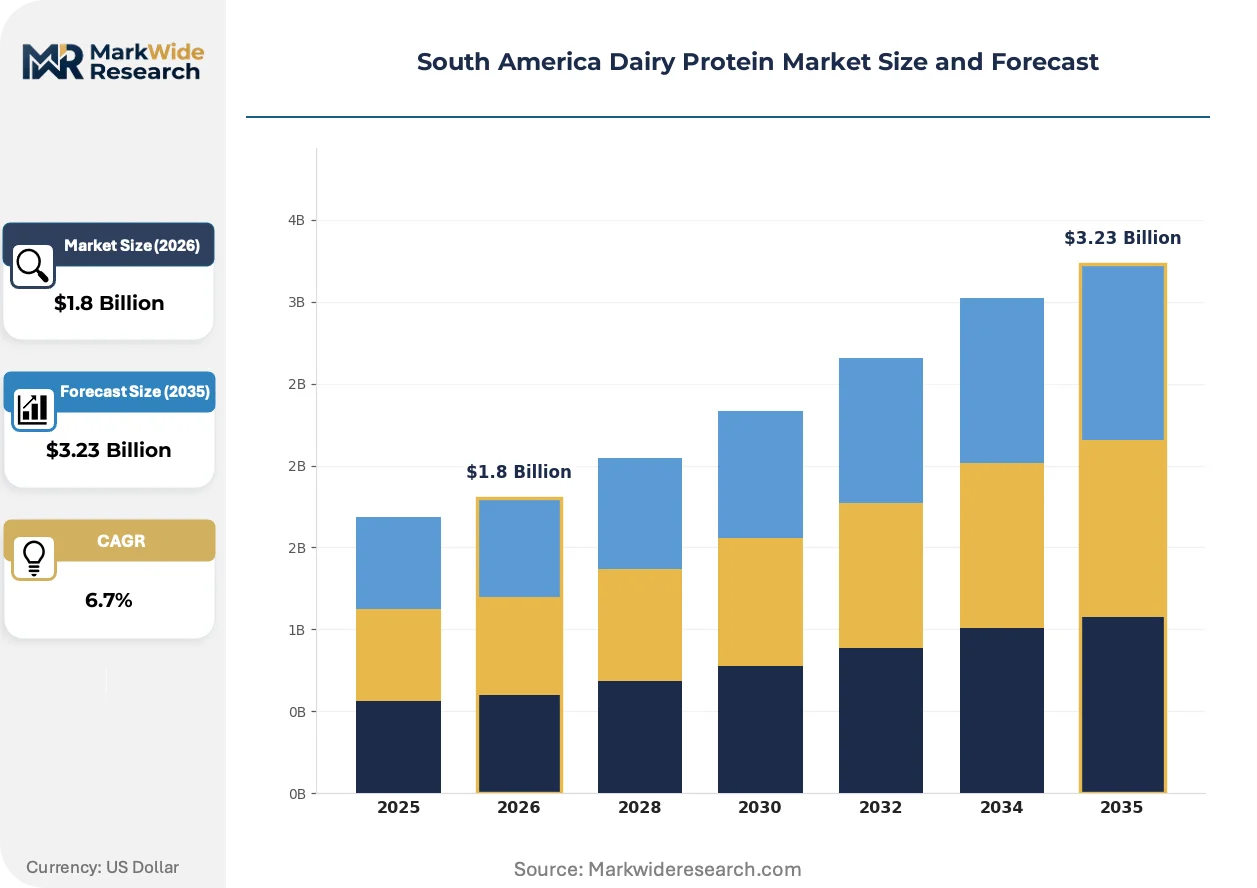
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Proteins, Concentrates End User: Food & Beverage, Sports Nutrition, Clinical Nutrition, Dietary Supplements Application: Functional Foods, Protein Enrichment, Bakery, Snacks Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Retailers |
| Companies Covered | Saputo Inc., Hoogwegt, Arla Foods Ingredients Group P/S, Nestlé S.A., Interfood Group, Dairy Farmers of America, Tangara Foods, Danone S.A., Fonterra Co-operative Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dairy Protein Market Evolving Landscape
Membrane technology advances and regulatory disclosure mandates are converging to reshape South American dairy protein value creation, with processing economics and procurement patterns undergoing simultaneous recalibration.
Precision enzymatic hydrolysis is collapsing the cost gap between standard whey concentrates and bioactive peptide fractions. Argentine processing lines serving regional sports nutrition formulators are adopting targeted protease systems at accelerating rates. This technology compression is enabling mid-tier processors to compete on specialized clinical nutrition ingredients previously reserved for multinational suppliers.
ANVISA's purity disclosure framework is mandating batch-level protein content verification and contaminant screening documentation. Brazilian supplement manufacturers must now maintain auditable supply chain records from raw milk sourcing through finished product release. The regulatory pressure falls most heavily on imported concentrate users, who face extended customs clearance protocols while domestic verified processors gain preferential market access.
Chilean middle-income households are pivoting from pharmacy-retail protein purchases toward direct-to-consumer subscription models. E-commerce platforms and specialized nutrition brands are disintermediating traditional distribution, compressing price markups and accelerating consumption cycle frequency. This channel restructuring is most pronounced in Santiago's metropolitan zone, where urban logistics density supports same-day delivery economics for protein powder replenishment.
South America Dairy Protein Market Segmentation
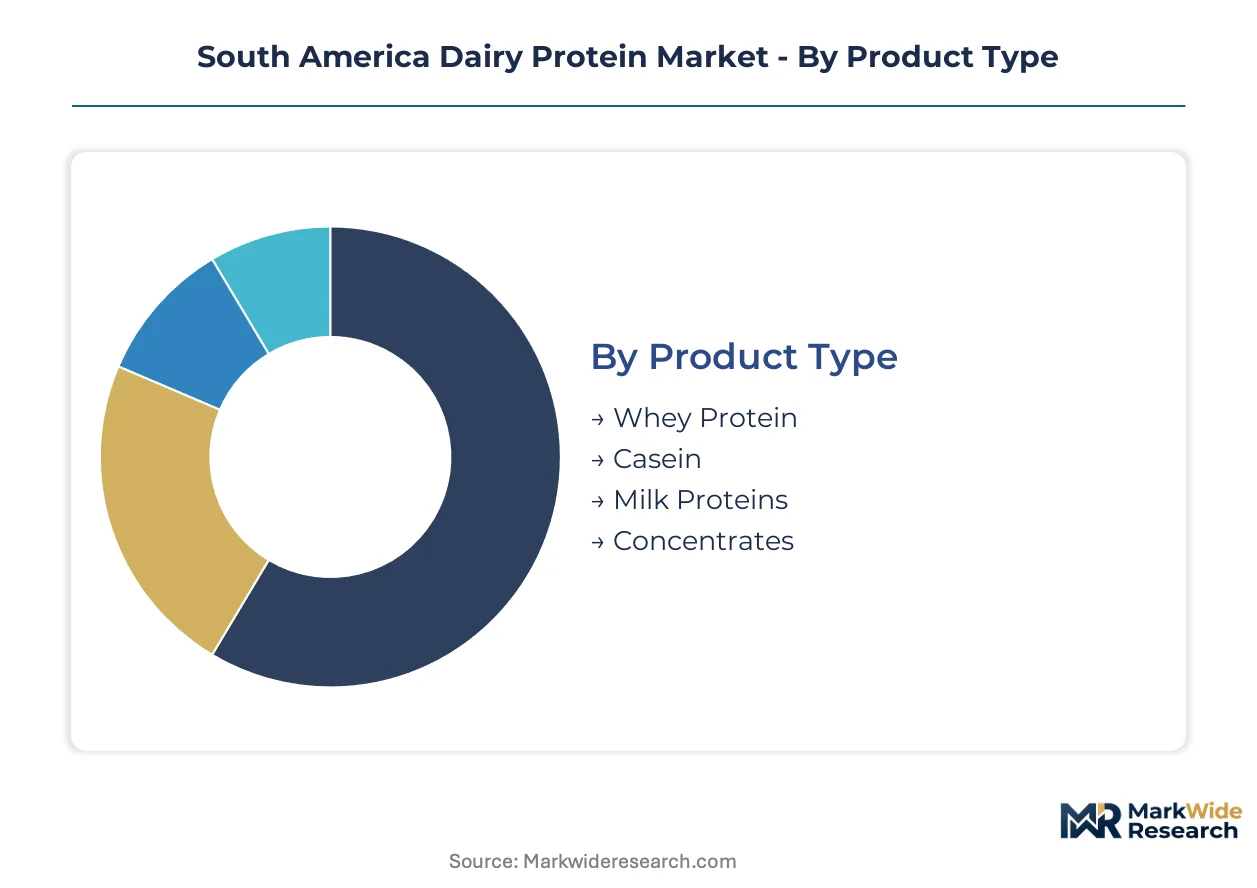
South American dairy protein procurement patterns diverge sharply across product chemistry, end-use formulation requirements, and channel access economics. ANVISA's batch-level verification mandates and São Paulo-state processing concentration reshape how buyers navigate these segment boundaries.
Product Type:
Membrane filtration capabilities separate commodity concentrates from premium isolates across Argentine and Brazilian processing lines.
- Whey Protein:Rapid-absorption kinetics and superior leucine density position this fraction as the default for sports nutrition formulators. São Paulo-state processors command premium supply contracts from Brazilian fitness brands scaling direct-to-consumer distribution.
- Casein:Sustained amino acid release kinetics and gelation stability serve clinical nutrition and bakery matrices. Argentine whey processing lines leverage existing membrane infrastructure to produce micellar variants for regional medical nutrition applications.
- Milk Proteins:Combined whey-casein fractions offer cost-efficient complete amino acid profiles for mass-market food manufacturing.
- Concentrates:Lower-purity grades (34-80% protein) anchor commodity bakery and snack applications where functional properties outweigh premium nutrition claims.
Established volume favors Concentrates; emerging adoption favors Whey Protein.
End User:
Regulatory disclosure timelines and formulation complexity create tiered entry barriers across customer categories.
- Sports Nutrition:Direct-to-consumer protein powder brands in Brazil, Argentina, and Colombia drive isolate procurement. ANVISA's tightened labeling requirements compress formulation transparency timelines for these manufacturers.
- Dietary Supplements:Capsule and tablet formats for pharmacy retail channels require batch-level traceability documentation that domestic verified processors supply more readily than importers.
- Food & Beverage:Mass-market manufacturers prioritize cost-stable concentrates for protein enrichment without premium positioning.
- Clinical Nutrition:Medical nutrition formulators in Santiago and Bogotá seek specialized casein variants with documented purity profiles for enteral feeding applications.
Volume concentrates in Food & Beverage; steepest expansion trajectory runs through Sports Nutrition.
Application:
Functional requirements determine protein fraction selection and processing investment levels.
- Functional Foods:Emulsification and texture modification demands drive whey protein incorporation into formulated dairy beverages across Brazil's southeastern dairy belt.
- Protein Enrichment:Neutral-flavor concentrates enable calorie-dense fortification of staple foods targeting middle-income household nutrition gaps in Chile and Colombia.
- Bakery:Casein's moisture retention and Maillard browning control serve artisan and industrial bread producers in Buenos Aires and São Paulo metropolitan zones.
- Snacks:Extruded protein crisps and bars absorb whey concentrate flows from Argentine processing lines serving regional contract manufacturers.
Current procurement patterns favor Protein Enrichment; product development pipelines prioritize Functional Foods.
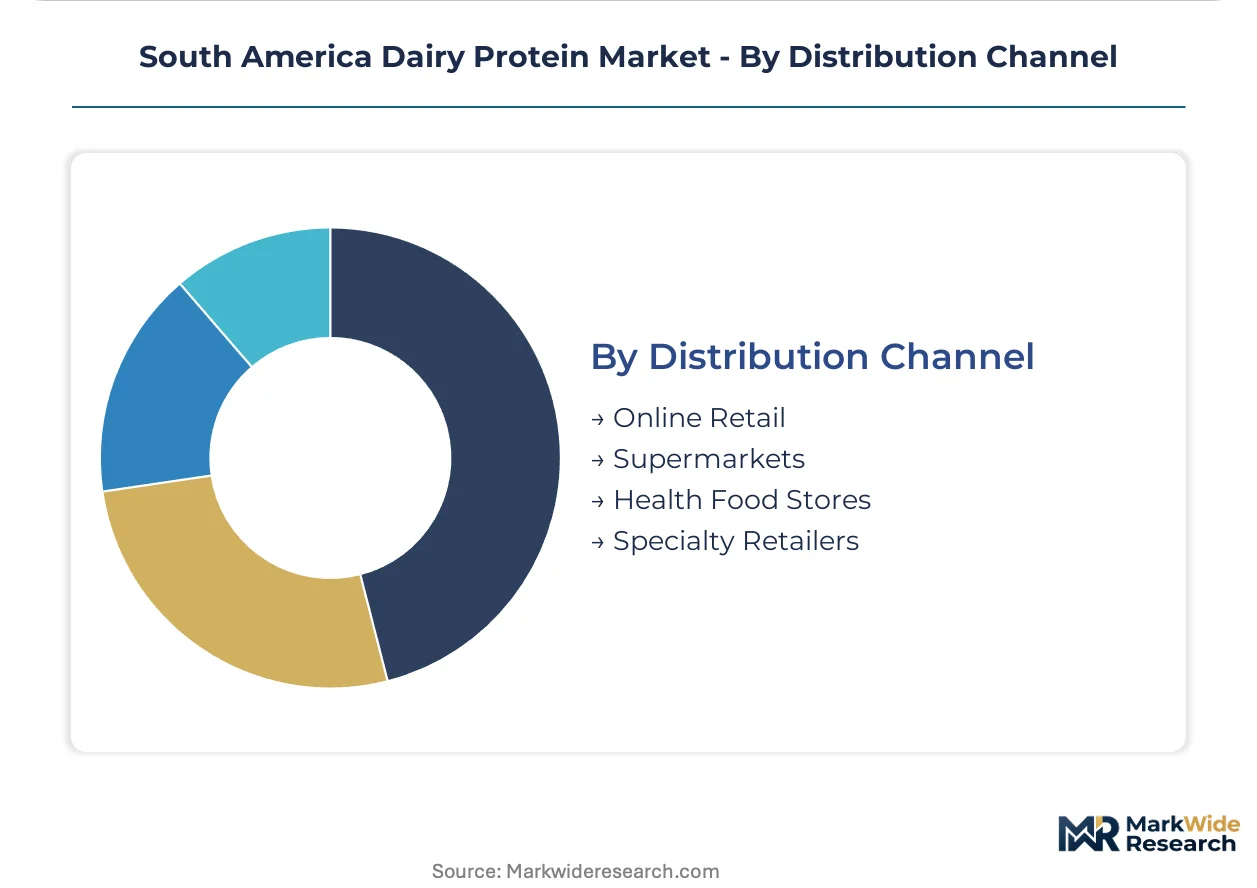
Distribution Channel:
Channel selection determines margin capture and customer data access for protein powder brands.
- Online Retail:Subscription-based replenishment models in Santiago's metropolitan zone bypass traditional pharmaceutical retail markups. Same-day delivery economics accelerate consumption cycle frequency for Chilean middle-income households.
- Supermarkets:Mass-market concentrate SKUs reach price-sensitive Brazilian consumers through São Paulo-state retail density.
- Health Food Stores:Specialty retailers in Bogotá and Medellín curate premium isolate assortments for underserved sports nutrition channels.
- Specialty Retailers:Gym-adjacent and clinical nutrition-focused outlets provide formulation guidance that justifies premium pricing for casein variants.
Volume flows through Supermarkets; margin expansion concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian sports nutrition brands dominate procurement volumes, while Argentine processors leverage existing whey infrastructure. Chilean direct-to-consumer channels and Colombian clinical nutrition gaps create divergent expansion paths across the continent.
Brazil
São Paulo-state fitness brands scale direct-to-consumer protein powder distribution, pulling isolate volumes through southeastern processing clusters. ANVISA's batch-level verification mandates compress formulation timelines for domestic manufacturers. Campinas and Ribeirão Preto membrane filtration facilities command premium supply contracts from verified regional buyers.
Argentina
Buenos Aires-based sports nutrition formulators source whey fractions from Pampas dairy belt processors. The national food code authority enforces identity specifications that elevate compliance costs for cross-border concentrate movements. Rosario and Santa Fe membrane infrastructure serves regional contract manufacturers with micellar casein variants.
Chile
Santiago metropolitan zone households pivot from pharmacy retail toward subscription-based protein replenishment models. Same-day delivery economics accelerate consumption cycles for middle-income direct-to-consumer channels. Valparaíso logistics corridors support e-commerce platform distribution for specialized nutrition brands.
Colombia
Bogotá and Medellín sports nutrition channels remain underserved by clinical-grade casein suppliers. Import-dependent concentrate flows face customs clearance friction from regional verification requirements. Cali emerging as a distribution hub for Andean medical nutrition formulators seeking documented purity profiles.
South America Dairy Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Brazilian and Argentine supply corridors. The vendor base clusters around three archetypes: multinational dairy cooperatives with ocean freight logistics, regional processors with ANVISA-verified membrane infrastructure, and ingredient specialists with clinical nutrition formulations. Dominant competitive moves include backward integration into raw milk sourcing and technology licensing for enzymatic hydrolysis capabilities.
Among cooperative-structured multinationals, Fonterra Co-operative Group and Dairy Farmers of America occupy positions anchoring bulk concentrate flows into Brazilian port infrastructure. Saputo Inc. exemplifies the regional processor archetype with Argentine whey processing footprints serving sports nutrition formulators. Arla Foods Ingredients Group P/S represents the clinical specialization vector through casein variant development for medical nutrition applications.
| Leading Market Players |
|---|
| Saputo Inc. |
| Hoogwegt |
| Arla Foods Ingredients Group P/S |
| Nestlé S.A. |
| Interfood Group |
| Dairy Farmers of America |
| Tangara Foods |
| Danone S.A. |
| Fonterra Co-operative Group |
| Others |
Value Network & Pricing Analysis
São Paulo-state membrane filtration clusters concentrate fractionation capacity for whey isolate and casein variants, translating geographic supply dominance into pricing power for verified domestic processors serving ANVISA-compliant supplement manufacturers.
Pricing Analysis
Cost-plus contracts indexed to raw milk futures from Argentina's Pampas dairy belt dominate procurement between Brazilian sports nutrition brands and São Paulo-state processors. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade milk protein separates ANVISA-verified batches from import-dependent alternatives. Price differentiation hinges on batch-level traceability documentation and leucine content certification. Cost compression in standard concentrate tiers is intensifying because Argentine raw milk volatility transmits directly into whey production economics.
Supply Chain Analysis
Export-control restrictions on precision membrane filtration equipment from European and North American suppliers limit capacity expansion for mid-tier Argentine and Colombian processors. Geographic supply concentration centers on Brazil's southeastern dairy belt, Argentina's Pampas region, and emerging Colombian distribution hubs around Cali. Raw material flows draw from seasonal Pampas milk production, imported whey permeate, and enzymatic hydrolysis catalysts. Single-source vulnerability permeates the diafiltration membrane replacement parts pipeline. Distribution runs through verified processor-direct contracts for premium tiers and commodity spot markets for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based protein powder replenishment models in Chilean and Brazilian direct-to-consumer channels are expanding recurring revenue streams faster than hardware-equivalent bulk concentrate sales, positioning ongoing formulation services as the value-capture layer.
For Market Incumbents: Harden ANVISA verification infrastructure against emerging regional competitors by captive control over São Paulo-state raw milk sourcing. Expand membrane filtration capacity in Campinas and Ribeirão Preto to preempt supply constraints from import-dependent challengers facing extended customs clearance timelines. For New Entrants and Emerging Players: Pursue Bogotá and Medellín clinical nutrition channels where specialized casein variants for enteral feeding applications remain underserved by existing suppliers. Target health food store curation partnerships as the lowest-friction go-to-market path for premium isolate penetration. For Investors and Strategic Acquirers: Long-term, this sits as a processing-capability consolidation play because enzymatic hydrolysis expertise and ANVISA-verified membrane infrastructure are accumulating scarcity premiums. Monitor MERCOSUR harmonization negotiation progress as the signal indicating whether intra-regional regulatory friction will compress or sustain import-dependent processor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Milk Sourcing | São Paulo-state processors secure supply stability against Argentine Pampas price volatility. |
| Enzymatic Hydrolysis Technology Licensing | Argentine mid-tier producers access bioactive peptide product lines previously reserved for multinationals. |
| ANVISA Certification Investment | Domestic verified processors gain preferential customs clearance and batch-level traceability premiums. |
| Direct-to-Consumer Channel Expansion | Chilean subscription models bypass pharmaceutical retail markups and accelerate consumption cycles. |
| Clinical Nutrition Partnership Development | Specialized casein suppliers capture Bogotá medical nutrition gaps with documented purity profiles. |
Research Methodology
Operator-level perspectives from membrane filtration plant managers, ANVISA regulatory affairs specialists, sports nutrition brand procurement directors, and clinical nutrition formulators anchored the qualitative base. Secondary validation drew from ANVISA registration databases, Argentine national food code filings, MERCOSUR trade flow records, and São Paulo-state dairy processor customs declarations. Bottom-up capacity assessments and top-down consumption estimates were triangulated to constrain variance.
Scenario-bracketing around raw milk price volatility bands and MERCOSUR harmonization outcomes framed the analytical approach across the projection horizon. Segmentation dimensions modeled include protein fraction chemistry, end-use application requirements, distribution channel economics, and regional regulatory cluster alignment. CAGRs were derived from installed capacity trajectories and per-capita protein powder penetration curves. Forecast inputs incorporated ANVISA certification timeline distributions and enzymatic hydrolysis adoption rates.
Sensitivities concentrate around Argentine Pampas milk production shocks, ANVISA disclosure mandate enforcement intensity, and membrane equipment import licensing delays. Forecasts reflect assumptions about sustained sports nutrition brand expansion and stable MERCOSUR intra-regional trade protocols. Material shifts in Brazilian regulatory stringency or Argentine input cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Crumbles Market
Dairy Products
North America Sour Cream Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Emmental Cheese Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
North America Milk Powder Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Japan Casein Market