
 Vegetable Fats Market | 2026-2036
Vegetable Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Fats Market Analysis
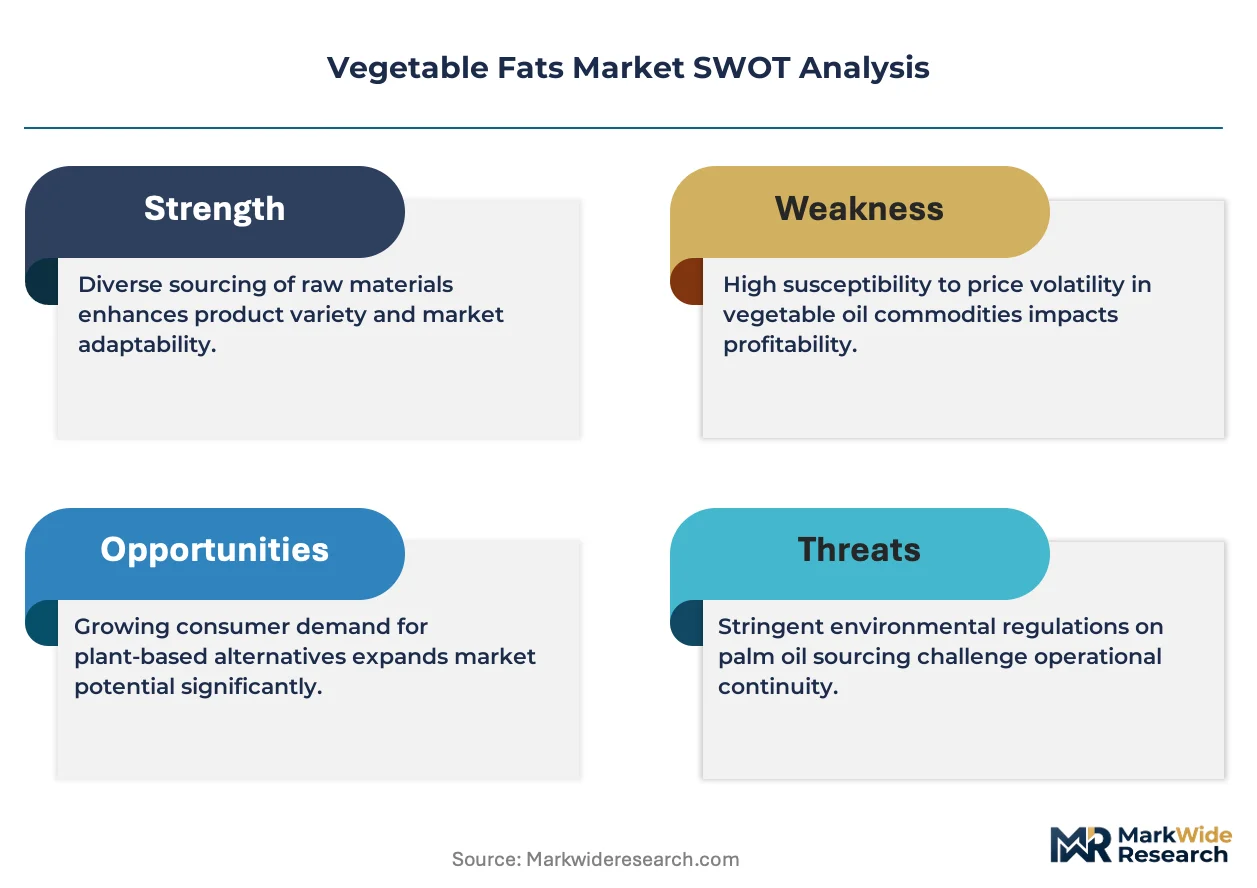
Project finance tied to certified sustainable plantation assets is tilting competitive access toward capital-rich operators. Cargill, Incorporated leverages backward integration into Brazilian soybean crushing to secure feedstock cost visibility. Wilmar International Ltd anchors its position through plantation ownership in Indonesia and downstream refinery networks across Asia. Bunge Limited competes via origination strength in North American oilseed supply chains and export logistics.
Vegetable fats comprise triglyceride mixtures extracted from oilseed, fruit, or nut biomass through mechanical pressing or solvent extraction, typically refined to achieve specified free fatty acid content, color, and oxidative stability for food or industrial use. Palm oil dominates volume flows due to its high yield per hectare and versatile fractionation into olein and stearin grades for baking and confectionery applications. Soybean oil leads in North American food service channels, while sunflower oil captures premium positioning in European retail and cosmetics formulations where cold-press extraction and high oleic variants command price premiums.
EFSA sets maximum levels for 3-MCPD esters and glycidyl esters in refined vegetable oils sold within Europe, forcing processors to adopt modified deodorization or enzymatic interesterification. REACH governs chemical substances used in oil processing aids and packaging migration, while FDA enforces Food Safety Modernization Act rules for imported fats entering US food manufacturing. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates and decide whether to invest in satellite-verified supply chain certification or shift sourcing geography.
Market Dynamics
Integrated plantation-to-refinery operations in Indonesia and Malaysia are capturing cost advantages and squeezing merchant processors who lack upstream feedstock control, reshaping competitive access to working capital and certified sustainable assets.
Growth Catalysts
- EFSA contaminant limits:Tightened maximum levels for 3-MCPD esters and glycidyl esters are forcing processors to adopt modified deodorization, creating technology differentiation among refiners.
- Processed food manufacturing:Food industry buyers are expanding procurement of palm and soybean oils for bakery, confectionery, and convenience food applications.
- Indonesia-Malaysia concentration:Demand is concentrating in these markets as operators with captive plantation assets secure volume and price visibility unavailable to spot-market buyers.
Market Restraints
- Input cost volatility:Crude palm oil and soybean prices fluctuate with weather patterns in Southeast Asia and South America, compressing margin predictability for non-integrated refiners.
- Supply concentration risk:Overreliance on Indonesian and Malaysian plantation output exposes buyers to El Niño disruptions and export policy shifts.
- REACH compliance friction:Chemical substances used in oil processing aids face registration and migration testing requirements that extend product approval timelines.
Strategic Opportunities
- EU Deforestation Regulation traceability:Satellite-verified supply chain certification creates a compliance services market for verification technology providers and audit firms.
- High-oleic sunflower oil:European retail and cosmetics formulations command price premiums for cold-press extraction variants, opening specialty positioning.
- Enzymatic interesterification:Convergence of biocatalysis and refining technology enables cleaner-label fat structuring without chemical processing.
Industry Challenges
- Certification timeline compression:RSPO and ISCC certification audits require 12-18 month implementation cycles that lag behind customer procurement mandates.
- Deodorization asset reconfiguration:Modified processing hardware to meet EFSA ester limits demands capital deployment that strains mid-scale refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Fats Market |
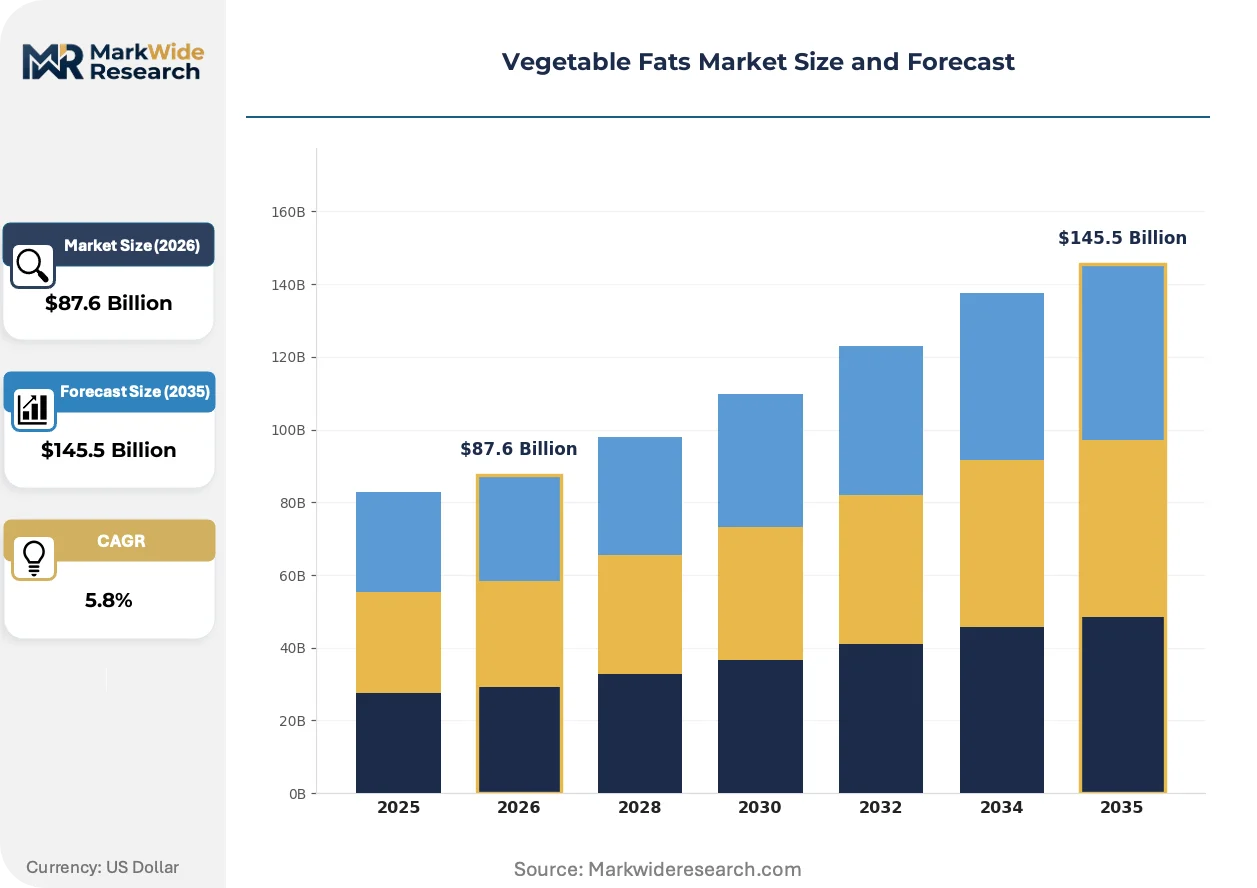
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Palm Oil, Olive Oil, Soybean Oil, Sunflower Oil Application: Baking, Cooking, Confectionery, Sauces End User: Food Industry, Cosmetics, Personal Care, Biofuels Distribution Channel: Online Sales, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Archer-Daniels-Midland Company, Cargill, Incorporated, Wilmar International Ltd, Bunge Limited, Louis Dreyfus Company BV, Fuji Oil Holdings Inc., Kuala Lumpur Kepong Berhad, Mewah Group, Olam Agri Holdings Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Fats Market Emerging Trajectories
Processing technology and compliance architecture are actively reshaping how vegetable fats move from plantation to formulated end-use, with implications for capital deployment and competitive positioning across the value chain.
Enzymatic interesterification is migrating from niche specialty applications to mainstream baking and confectionery fat production. European and North American food manufacturers are adopting biocatalytic restructuring to achieve specified melting profiles without chemical interesterification. This technology is migrating from premium positioning toward cost-competitive deployment as enzyme costs decline and regulatory pressure on chemical processing intensifies.
REACH and EFSA standards are tightening in parallel, creating overlapping compliance burdens for European market access. Processors must now document processing aid substances under REACH while simultaneously meeting EFSA maximum contaminant levels for finished oils. Refined vegetable oils sold within Europe face the strictest combined regulatory load, pushing some suppliers toward enzymatic or physical refining alternatives.
Buyer concentration among multinational food manufacturers is consolidating procurement decisions into fewer sustainability and technical specification teams. Large processed food manufacturers are unbundling commodity purchasing from certified sustainable sourcing, creating separate supplier tiers. This pattern is most visible in European retail and North American food service channels where ESG disclosure requirements drive specification divergence.
Vegetable Fats Market Segmentation
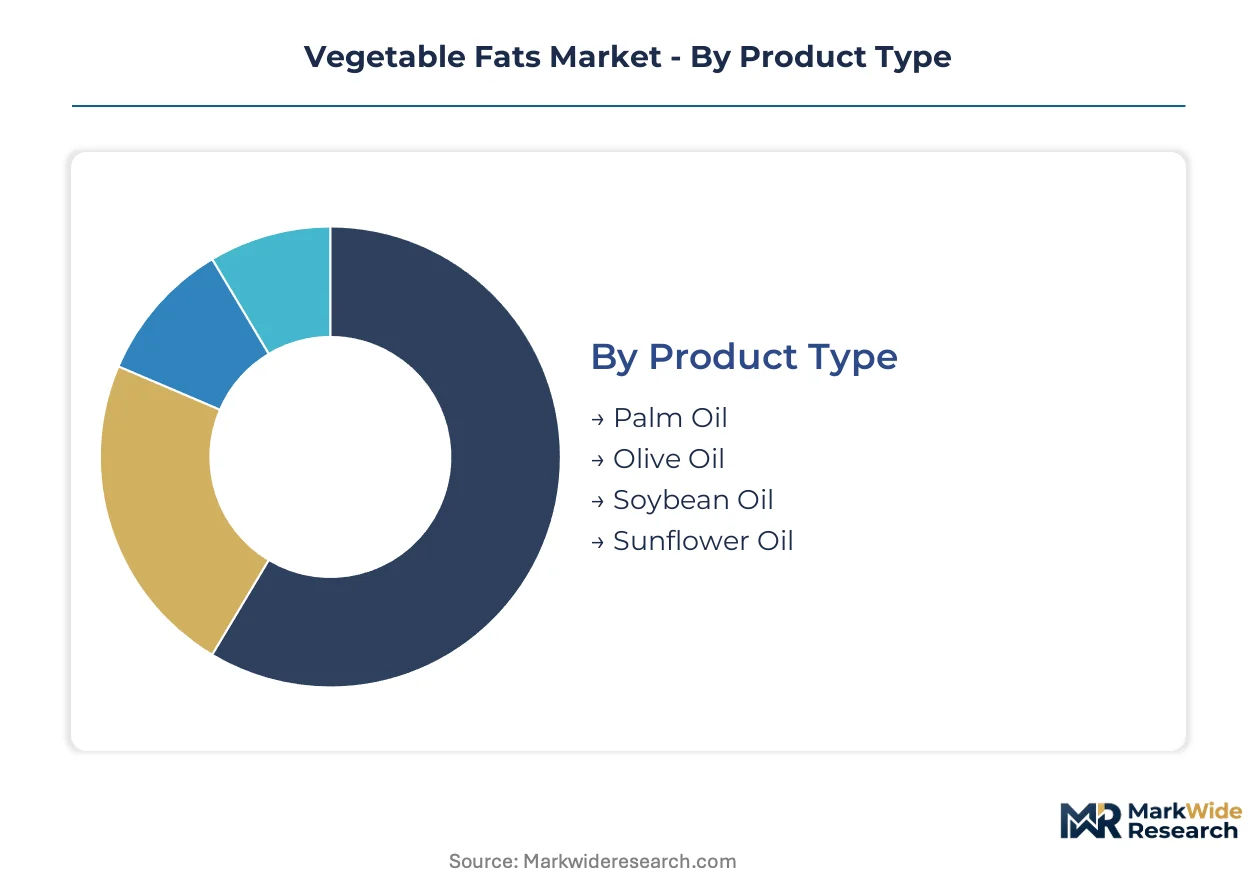
Segmentation in vegetable fats determines capital allocation across refining assets, certification investments, and geographic procurement strategies. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across oil types, with palm and soybean requiring extensive technical support for fractionation and contamination compliance while olive and sunflower demand sensory validation and cold-chain integrity programs.
- Palm Oil:Triglyceride mixture with high saturated fat content enabling fractionation into olein and stearin grades for consistent baking performance. Demand concentrates in Indonesian and Malaysian integrated refinery networks where plantation-to-port infrastructure captures cost visibility unavailable to spot buyers. EFSA glycidyl ester limits are forcing deodorization hardware upgrades that favor capital-rich operators with captive feedstock.
- Soybean Oil:Polyunsaturated oil extracted through solvent extraction and degumming, dominant in North American food service channels for frying stability and neutral flavor. Procurement is expanding among processed food manufacturers seeking non-palm alternatives for clean-label formulations, though crushing margin volatility strains non-integrated refiners.
- Olive Oil:Monounsaturated oil with distinctive organoleptic profiles graded by acidity and polyphenol content, commanding premium positioning in European retail and Mediterranean export markets.
- Sunflower Oil:High-oleic variants extracted through cold-press or solvent methods, capturing specialty margins in cosmetics formulations and health-positioned retail channels.
Palm oil holds the largest share; momentum sits with high-oleic sunflower oil as European cosmetics manufacturers accelerate clean-label procurement.
Application:
Application-driven segmentation reveals diverging technical specifications and certification requirements across food manufacturing channels.
- Baking:Structured fats requiring precise melting profiles and oxidative stability for laminated doughs and shortenings, driving interesterification technology adoption among industrial suppliers.
- Cooking:High smoke-point oils for frying applications where thermal stability and cost efficiency dominate procurement criteria in food service and retail private label.
- Confectionery:Cocoa butter equivalents and coatings demanding sharp melting characteristics and bloom resistance, with enzymatic interesterification displacing chemical processes for clean-label positioning.
- Sauces:Emulsion-stable oils with neutral flavor profiles for mayonnaise and dressing manufacturing, where oxidative stability during shelf life determines supplier selection.
Baking commands the greatest volume; confectionery is expanding most quickly as clean-label restructuring technologies mature.
End User:
End-user segmentation separates commodity-scale food manufacturing from premium-positioned specialty channels with diverging sustainability verification demands.
- Food Industry:Industrial-scale baking, frying, and processing applications where RSPO and ISCC certification is becoming a procurement gate, particularly among European and North American multinational manufacturers.
- Cosmetics:High-purity grades for emollient and formulation applications where cold-press extraction and organic certification command substantial price premiums in European retail.
- Personal Care:Refined fractions for soap, surfactant, and skincare applications with specific iodine value and color specifications.
- Biofuels:Technical-grade oils and waste streams for biodiesel and renewable diesel feedstock, subject to EU Renewable Energy Directive sustainability criteria and indirect land-use change regulations.
Food industry absorbs the greatest tonnage; cosmetics is gaining share fastest as clean-beauty positioning accelerates ingredient transparency requirements.
Distribution Channel:
Channel segmentation reflects the unbundling of commodity procurement from certified sustainable sourcing among large buyers.
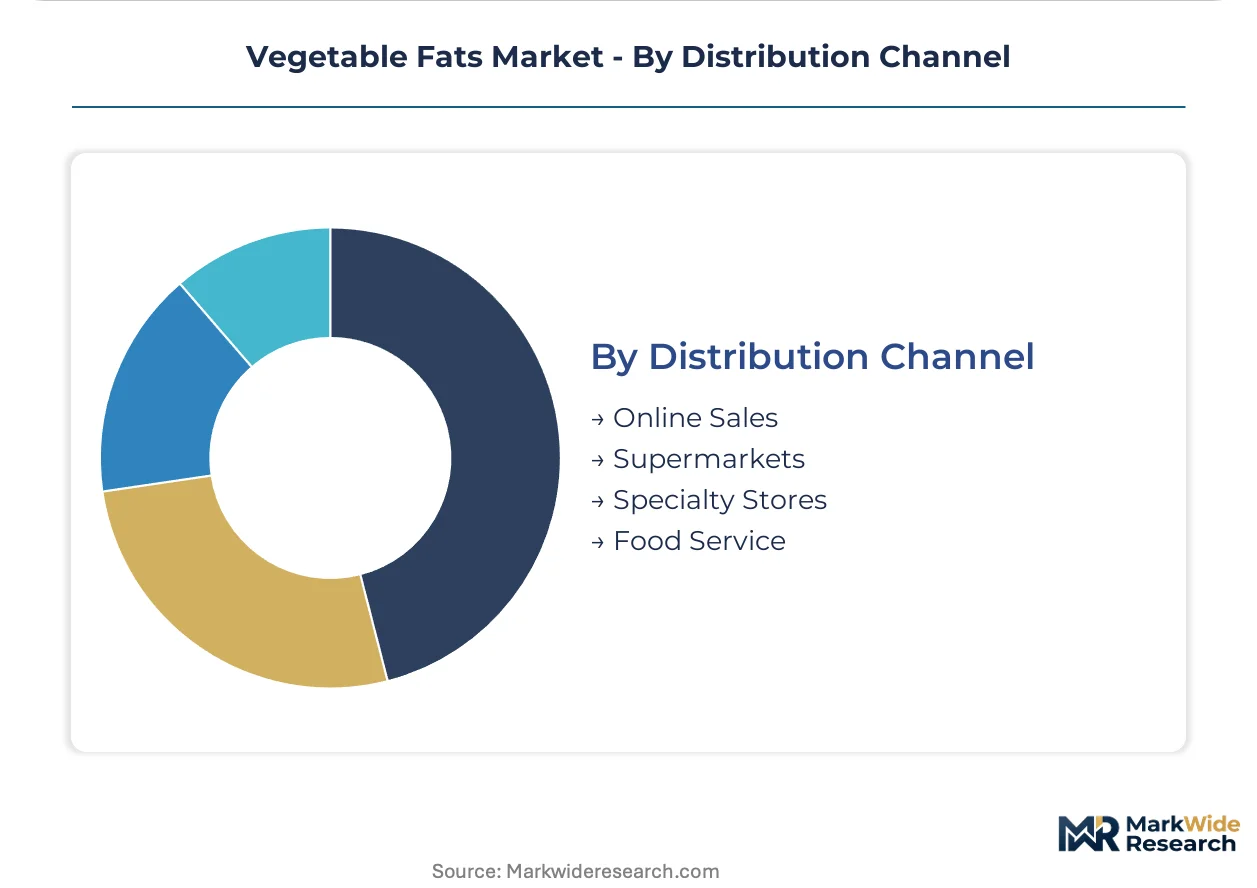
- Online Sales:Direct-to-consumer and B2B platform channels for specialty and organic grades where traceability storytelling and subscription logistics create differentiation.
- Supermarkets:Volume retail for private label and branded packaged oils where shelf placement and promotional programming drive manufacturer negotiation leverage.
- Specialty Stores:Premium and ethnic retail channels for cold-press, single-origin, and appellation-designated oils with sensory validation requirements.
- Food Service:Bulk supply to restaurants, institutions, and contract catering where cost efficiency and supply reliability outweigh certification premiums.
Supermarkets dominate volume throughput; online sales are climbing the fastest as direct sourcing platforms consolidate specialty buyer demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Deforestation Regulation traceability mandates are redrawing procurement geography, while Indonesia and Malaysia tighten plantation licensing to capture downstream value. National food safety regimes diverge on contaminant thresholds and sustainability verification timelines.
Indonesia
Integrated plantation-to-refinery operators dominate export volumes through captive feedstock control and port-adjacent processing infrastructure. The Ministry of Agriculture's sustainable palm oil certification program (ISPO) mandates compliance timelines that favor capital-rich incumbents with audit-ready estate management systems. North Sumatra and Riau provinces concentrate refining capacity where plantation groups operate dedicated oleochemical and fractionation facilities.
Malaysia
Peninsular Malaysia's Johor and Port Klang corridors anchor specialty fat production for European confectionery and cosmetics channels demanding RSPO-segregated supply chains. The Malaysian Palm Oil Board enforces MSPO certification standards that align with EU market access requirements. Refinery clusters in Pasir Gudang leverage deep-water terminals for direct bulk shipment to Rotterdam and Hamburg.
United States
Midwest soybean crushing capacity serves North American food service and biofuel channels with origination strength across Illinois and Iowa grain belts. FDA Food Safety Modernization Act rules enforce preventive controls for imported refined oils entering baking and frying applications. Gulf Coast export terminals in Louisiana and Texas handle soybean oil shipments to Latin American and Asian buyers.
Germany
Hamburg and Rotterdam-adjacent refining operations face the strictest combined EFSA and REACH compliance burden for European food manufacturing supply. ECHA registration requirements for oil processing aids extend product approval timelines beyond eighteen months for novel extraction technologies. The country's margarine and bakery fat processors drive specification divergence between commodity and certified-sustainable procurement tiers.
Brazil
Matopiba and Mato Grosso soybean production zones feed crushing assets with expanding capacity for Asian export markets and domestic biodiesel blending mandates. ANVISA food safety standards govern contaminant limits for refined oils entering processed food manufacturing. Santos port infrastructure supports bulk oil shipments competing with Argentine and US origination on global spot markets.
Vegetable Fats Market Vendor Landscape
Channel-controlling players compete with product-specialist players across upstream plantation ownership, midstream refining, and downstream formulation supply. The market structures around three tiers: integrated plantation-refinery operators with captive feedstock, merchant processors dependent on spot procurement, and specialty oil blenders serving cosmetics and premium food channels. Dominant competitive moves include backward integration into crushing assets and satellite-verified supply chain certification to meet EU procurement mandates.
Among Singapore-based integrated operators, Wilmar International Ltd and Olam Agri Holdings Pte Ltd exemplify plantation-to-port control structures that secure volume visibility unavailable to merchant competitors. Archer-Daniels-Midland Company and Cargill, Incorporated represent North American origination-heavy archetypes with crushing networks across US Midwest and Brazilian supply basins. These players occupy positions where logistics scale and sustainability certification capacity determine access to multinational food manufacturer procurement panels.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Cargill, Incorporated |
| Wilmar International Ltd |
| Bunge Limited |
| Louis Dreyfus Company BV |
| Fuji Oil Holdings Inc. |
| Kuala Lumpur Kepong Berhad |
| Mewah Group |
| Olam Agri Holdings Pte Ltd |
| Others |
Supply Flow & Price Mechanics
North Sumatra's integrated plantation-refinery corridor concentrates fractionation capacity for European confectionery buyers, translating captive feedstock control into pricing power that spot-dependent merchants cannot match. EFSA glycidyl ester compliance costs are compressing margins for non-integrated processors while reinforcing premium capture by operators with in-house deodorization assets.
Pricing Analysis
Certification level creates the primary spread between commodity spot and RSPO-segregated supply tiers, with MSPO and ISCC premiums widening as EU Deforestation Regulation traceability mandates harden procurement specifications. Three-tier pricing structure across certified-sustainable, mass-balance, and conventional grades reflects divergent compliance investment recovery timelines. Pricing pressure stems from El Niño-driven crude palm oil volatility that strains refiners lacking upstream plantation hedges. Food service channels exhibit highest price sensitivity, while European cosmetics manufacturers absorb certification premiums for cold-press sunflower grades.
Supply Chain Analysis
Wilmar International and Kuala Lumpur Kepong operate the dominant integrated plantation-to-port infrastructure across Indonesia and Malaysia, anchoring global refined oil flows. Feedstock draws from Southeast Asian palm estates and Brazilian soybean crushing networks, with enzymatic interesterification enzymes sourced from European biocatalysis specialists. Single-source vulnerability concentrates in the Malacca Strait logistics chokepoint where tanker congestion disrupts bulk shipments to Rotterdam and Hamburg. Distribution runs through deep-water terminals at Port Klang and Pasir Gudang serving European food manufacturers, with specialty cosmetics channels bypassing commodity wholesalers via direct plantation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegetable fats markets are cycling through a recovery phase as El Niño disruptions ease and plantation output normalizes across Indonesian and Malaysian supply basins.
For Market Incumbents: Entrench plantation-to-refinery control by accelerating MSPO and RSPO certification audits ahead of EU Deforestation Regulation enforcement deadlines. Deploy modified deodorization capital at Johor and North Sumatra facilities to capture EFSA-compliant volume from merchant competitors stranded by hardware upgrade timelines. Defensive priority rests on locking long-term offtake with European confectionery manufacturers before specialty fat blenders consolidate procurement panels. For New Entrants and Emerging Players: Build out cold-press extraction capacity for high-oleic sunflower oil serving European cosmetics channels where clean-beauty positioning commands 40-60% price premiums over commodity grades. White-space concentrates in satellite-verified supply chain audit services and blockchain traceability platforms enabling EU compliance without plantation ownership. Go-to-market leverage partners with existing organic certification networks to bypass 12-18 month RSPO implementation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core oilseed processing assets amid portfolio rationalization pressures. Long-term viability favors operators with captive plantation hectares and downstream oleochemical integration that captures value beyond commodity refining cycles. Monitor Indonesian export duty policy shifts and EU Renewable Energy Directive indirect land-use change rulings as inflection signals for biodiesel feedstock demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Cargill's Brazilian soybean crushing network secures feedstock cost visibility unavailable to spot-market refiners. |
| Enzymatic Interesterification Scale-Up | Fuji Oil Holdings displaces chemical restructuring for clean-label confectionery fat production in European channels. |
| RSPO-Segregated Supply Chain Certification | Malaysian refinery clusters capture premium access to EU retail procurement panels demanding traceability verification. |
| Modified Deodorization Hardware Deployment | Capital-rich operators meet EFSA glycidyl ester limits while mid-scale competitors face margin compression. |
| Direct-to-Manufacturer Distribution Platforms | Online B2B channels consolidate specialty buyer demand for organic and cold-press oil grades. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plantation estate managers, refinery technical directors, European food manufacturer procurement leads, cosmetics formulation chemists, and sustainability certification auditors. Secondary validation drew from EFSA contaminant limit publications, EU Deforestation Regulation implementation guidance, RSPO and ISCC certification databases, and customs trade flow records. Bottom-up volume modeling across palm, soybean, sunflower, and olive oil segments was triangulated against top-down macroeconomic indicators and agricultural commodity price series.
Calibration anchored segment-level projections to historical crushing and refining capacity utilization patterns across the analysis window, with growth trajectories stress-tested against El Niño frequency distributions and regulatory implementation timelines. Segmentation dimensions modeled included oil type, application channel, end-user industry, certification tier, and geographic production cluster. CAGRs were derived from regression-weighted capacity expansion announcements and substitution elasticity estimates between palm and alternative oils in food manufacturing formulations.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by North American grain traders or accelerated EU traceability enforcement would shift volume and margin outcomes materially. Quarterly review of Indonesian export licensing changes, Malaysian MSPO audit completion rates, and EFSA processing aid substance registrations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Olive Leaf Extract Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Oak Extract Market
Ingredients
Codonopsis Extract Market
Ingredients
Carotenes Market
Ingredients
Sunflower Meal Market
Ingredients
Wort Concentrate Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Europe Edible Oil Market
Ingredients
Pet Food Premix Market
Ingredients
Vegetable Concentrates Market
Ingredients
Grape Skin Extract Market
Ingredients
Protein Ingredients Market
Ingredients
Rose Extract Market
Ingredients
Sea Salt Market
Ingredients
Volatile Fatty Acids Market