
 Halal and Kosher Empty Capsules Market | 2026-2036
Halal and Kosher Empty Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Halal and Kosher Empty Capsules Market Analysis
Specialty gelatin producers in South Korea is pivoting toward pharmaceutical-grade halal certification to capture Middle East pharmaceutical outsourcing. Suheung Co. Ltd. leverages its integrated collagen supply chain to sustain kosher capsule exports across North American nutraceutical channels. Lonza Group anchors European demand through its Swissmedic-audited facilities, while ACG Associated Capsules competes on cost-optimized vegetarian capsule platforms for Indian contract manufacturers.
Halal and kosher empty capsules are dosage-form shells manufactured from bovine or porcine gelatin, hydroxypropyl methylcellulose, or pullulan, meeting religious dietary laws and typically sized from 000 to 5 for oral drug delivery. Gelatin capsules dominate current volume but face displacement from vegetarian capsules as Hindu and vegan populations reject animal-derived inputs across India and Southeast Asia. Contract manufacturers represent the fastest-growing end-user channel, absorbing bulk volumes through direct sales relationships that bypass wholesale markups and compress procurement cycles.
FDA cGMP standards, EMA MDR requirements, and Saudi SFDA halal certification protocols collectively shape market access barriers and product qualification timelines for cross-border capsule suppliers. Kosher certification from Orthodox Union and halal accreditation from Islamic Food and Nutrition Council of America impose additional audit layers that smaller producers struggle to fund. Stakeholders must monitor evolving religious authority recognition agreements between importing nations and certifying bodies to preempt supply disruptions.
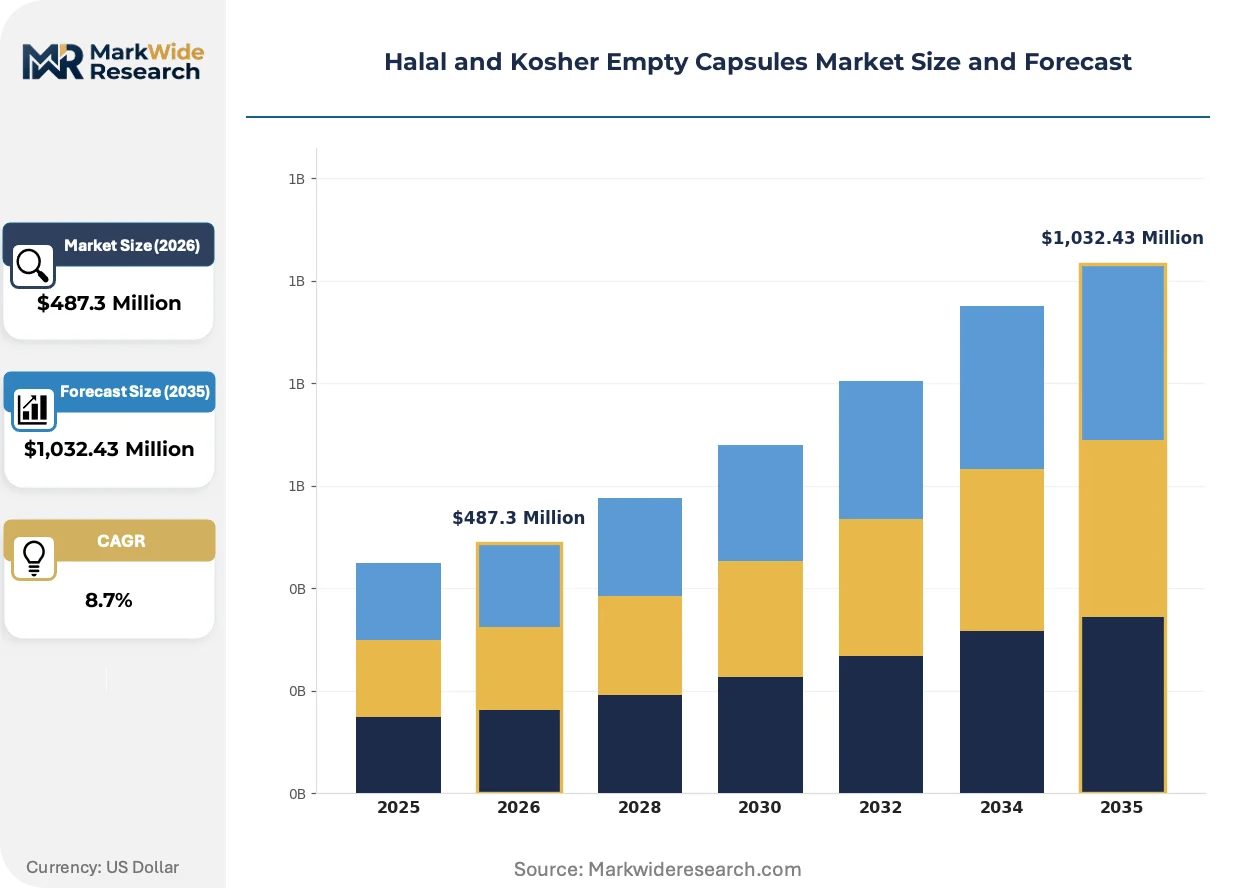
Market Dynamics
Religious certification mandates from Saudi SFDA and Indonesia's BPJPH are compressing supplier qualification timelines while contract manufacturers demand single-source halal-kosher dual certification to consolidate vendor bases.
Growth Catalysts
- SFDA Halal Mandates:Saudi Arabia's pharmaceutical regulator now requires halal certification for all imported empty capsules, forcing foreign suppliers to establish local audit partnerships or face market exclusion.
- Vegetarian Capsule Technology:Hydroxypropyl methylcellulose formulations are capturing share in Hindu-majority India where bovine gelatin faces religious rejection across nutraceutical contract manufacturing channels.
- Contract Manufacturing Concentration:Large-scale nutraceutical outsourcers in Malaysia and Indonesia are consolidating procurement through direct supplier relationships that bypass traditional distribution layers.
Market Restraints
- Gelatin Input Volatility:Bovine hide and bone prices fluctuate with livestock cycle conditions in Brazil and Argentina, compressing margins for gelatin-dependent capsule producers.
- Certification Cost Barriers:Smaller producers struggle to fund simultaneous Orthodox Union kosher and IFANCA halal audits, creating a supplier base skewed toward integrated multinationals.
- Vegetarian Performance Gaps:Pullulan capsules exhibit slower dissolution profiles than gelatin equivalents, limiting adoption in immediate-release pharmaceutical applications.
Strategic Opportunities
- UAE Pharmaceutical Outsourcing:MOHAP's streamlined halal certification pathway is attracting capsule producers to establish Jebel Ali free zone manufacturing for Middle East re-export.
- Dual-Certification Platforms:Single-production-line halal-kosher qualification is reducing SKU complexity for contract manufacturers serving both Muslim and Jewish dietary law markets.
- South Korean Export Pivot:MFDS-aligned pharmaceutical-grade halal certification is enabling Korean gelatin producers to capture Middle East API outsourcing demand.
Industry Challenges
- Cross-Authority Recognition Gaps:Lack of mutual recognition between Indonesia's BPJPH and Malaysia's JAKIM halal bodies forces redundant facility audits and extends product launch timelines.
- Specialized Technician Scarcity:Capsule shell manufacturing requires operators trained in both pharmaceutical cGMP and religious slaughter compliance protocols, a skill combination concentrated in limited geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal and Kosher Empty Capsules Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin Capsules, Vegetarian Capsules, Enteric-Coated Capsules, Softgel Capsules Application: Nutraceuticals, Pharmaceuticals, Dietary Supplements, Herbal Products End User: Contract Manufacturers, Healthcare Providers, Retail Pharmacies, E-commerce Platforms Distribution Channel: Online Retail, Wholesale Distribution, Retail Outlets, Direct Sales |
| Companies Covered | Suheung Co. Ltd., CapsCanada, Lonza Group, HealthCaps India, Natural Capsules Limited, ACG Associated Capsules, Shanxi Guangsheng Capsule Limited, Sunil Healthcare, Qualicaps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal and Kosher Empty Capsules Market Emerging Trajectories
Production automation and certification digitization are compressing batch release timelines while vegetarian formulations displace animal-derived inputs across South and Southeast Asian manufacturing hubs.
Vision-based inspection systems are automating defect detection in capsule shell production lines. Large contract manufacturers in Indonesia and Malaysia are deploying these systems to meet SFDA traceability requirements without expanding quality headcount. The technology is automating the final release bottleneck that previously delayed halal-certified batch shipments to Saudi Arabia.
EMA's updated MDR and F-Gas Regulation are tightening material traceability and fluorinated gas disclosure requirements for capsule producers exporting into the European single market. Manufacturers must now document gelatin sourcing back to slaughterhouse and demonstrate HFC-free drying processes. Swissmedic-audited facilities are absorbing disproportionate compliance investment as non-EU suppliers seek streamlined market access.
Direct procurement relationships are displacing wholesale distribution for high-volume capsule buyers. Large nutraceutical contract manufacturers in India and Malaysia are negotiating frame contracts with capsule producers that bypass traditional pharmaceutical ingredient distributors. This channel compression is most visible in Saudi Arabia where SFDA import licensing complexity favors established direct supplier relationships over spot market purchasing.
Halal and Kosher Empty Capsules Market Segmentation
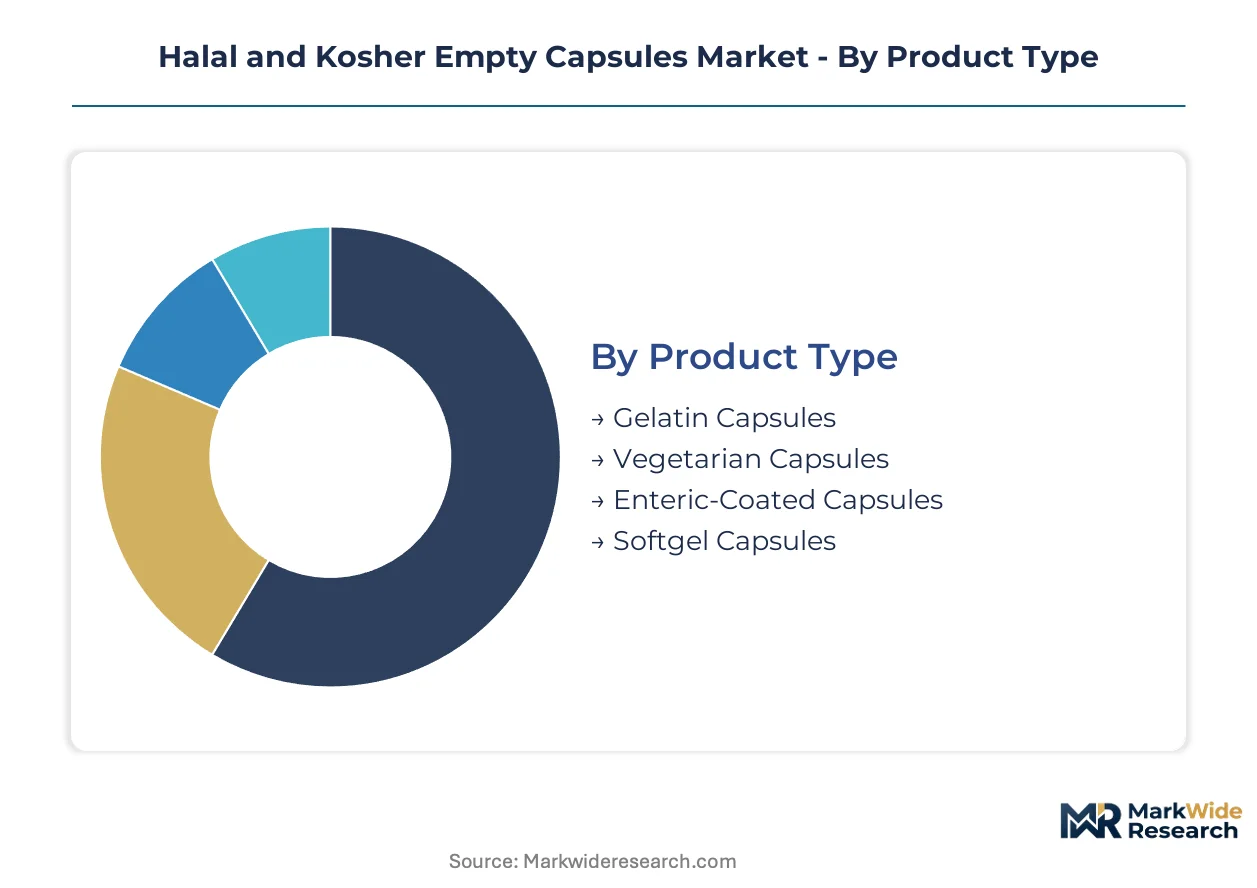
Religious certification requirements and vegetarian formulation advances are fragmenting procurement patterns across capsule categories. Contract manufacturers now specify dual-certification compatibility and dissolution performance as non-negotiable selection criteria.
Product Type:
Material composition dictates certification pathways and dissolution profiles, with gelatin formulations facing displacement from plant-derived alternatives in Hindu-majority markets.
- Gelatin Capsules:Bovine and porcine-derived shells remain the cost benchmark for immediate-release pharmaceuticals. Saudi SFDA mandates now require slaughterhouse-to-facility traceability for all gelatin imports, compressing supplier qualification timelines for traditional producers.
- Vegetarian Capsules:Hydroxypropyl methylcellulose and pullulan formulations eliminate animal-derived inputs entirely. Demand concentrates in India where Hindu dietary restrictions and vegan positioning across nutraceutical channels are displacing bovine gelatin at accelerating rates.
- Enteric-Coated Capsules:pH-resistant polymer coatings protect acid-labile actives through gastric transit.
- Softgel Capsules:Seamless gelatin or carrageenan shells accommodate liquid and semi-solid fills.
Gelatin Capsules leads on scale; Vegetarian Capsules leads on momentum.
Application:
End-use specifications diverge sharply between pharmaceutical cGMP compliance and nutraceutical speed-to-market priorities.
- Nutraceuticals:Vitamin, mineral, and botanical formulations dominate volume throughput. Malaysian and Indonesian contract manufacturers are consolidating procurement through direct supplier relationships that bypass wholesale markups and compress batch release cycles.
- Pharmaceuticals:Prescription drug applications demand validated dissolution profiles and batch-level certification documentation. Saudi Arabia's import substitution policies are accelerating local production partnerships for SFDA-compliant capsule supply.
- Dietary Supplements:Sports nutrition and wellness positioning drives SKU proliferation.
- Herbal Products:Traditional medicine formats require compatibility with hygroscopic botanical extracts.
Pharmaceuticals commands premium pricing; Nutraceuticals exhibits the steepest expansion trajectory.
End User:
Procurement scale and technical specification intensity separate high-volume contract manufacturers from fragmented retail channels.
- Contract Manufacturers:Large-scale nutraceutical outsourcers in Malaysia and Indonesia negotiate frame contracts with capsule producers. These direct relationships eliminate distributor margins and enable custom certification packaging for multi-market export.
- Healthcare Providers:Hospital and clinic pharmacies require institutional procurement compliance.
- Retail Pharmacies:Community pharmacy chains stock standard sizes for compounding.
- E-commerce Platforms:Direct-to-consumer capsule sales remain limited by pharmaceutical regulation.
Contract Manufacturers dominates volume absorption; Healthcare Providers maintains stable replenishment patterns.
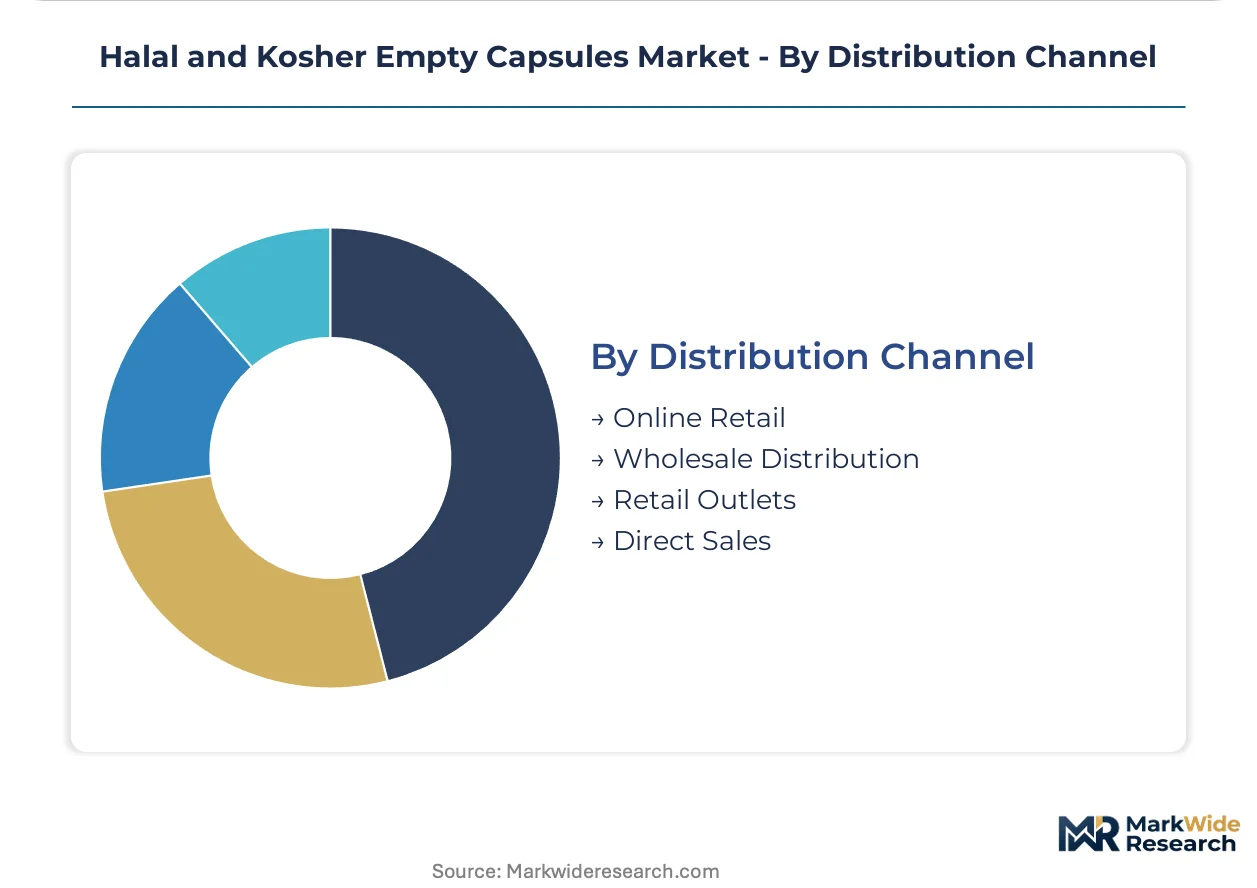
Distribution Channel:
Channel economics favor direct engagement at scale, with wholesale layers compressing under procurement centralization.
- Direct Sales:Producer-to-manufacturer relationships now dominate high-volume transactions. SFDA import licensing complexity in Saudi Arabia favors established direct supplier relationships over spot market purchasing, locking in multi-year procurement commitments.
- Wholesale Distribution:Traditional pharmaceutical ingredient distributors serve mid-tier manufacturers.
- Online Retail:Digital procurement platforms facilitate spot purchasing for small batches.
- Retail Outlets:Physical distribution remains relevant for compounding pharmacy supply.
Direct Sales captures margin efficiency; Online Retail gains share among emerging manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as capsule manufacturers relocate to jurisdictions with streamlined halal-kosher dual-certification pathways and lower audit cost burdens. South Korean and Indian producers leverage pharmaceutical-grade export frameworks to capture Middle East contract manufacturing demand. Southeast Asian facilities absorb volume from Chinese suppliers facing EU traceability compliance costs.
Saudi Arabia
SFDA halal mandates now require slaughterhouse-to-facility traceability for all imported gelatin capsules, compressing supplier qualification timelines. The regulator's updated pharmaceutical import rules favor established direct supplier relationships over spot purchasing. Jeddah and Riyadh industrial zones host expanding local production partnerships as import substitution policies accelerate domestic capsule manufacturing capacity.
Indonesia
BPJPH halal certification mandates from the national halal agency are forcing foreign capsule suppliers to establish local audit partnerships or face market exclusion. The country's pharmaceutical regulator aligns with religious authority protocols to streamline cross-border supply. Batam and Jakarta pharmaceutical clusters concentrate contract manufacturing demand as Malaysian and Indonesian outsourcers consolidate procurement through direct producer relationships.
India
Hindu dietary restrictions and vegan positioning across nutraceutical channels are displacing bovine gelatin at accelerating rates in favor of hydroxypropyl methylcellulose formulations. CDSCO pharmaceutical regulations and FSSAI food safety standards impose parallel compliance layers on capsule producers. Hyderabad and Mumbai manufacturing corridors host cost-optimized vegetarian capsule platforms serving domestic contract manufacturers and Middle East export markets.
South Korea
MFDS-aligned pharmaceutical-grade halal certification is enabling Korean gelatin producers to capture Middle East API outsourcing demand previously served by European suppliers. The regulator's streamlined export pathway reduces batch release timelines for halal-certified shipments. Seoul and Busan pharmaceutical clusters pivot toward integrated collagen supply chains that sustain kosher capsule exports across North American nutraceutical channels.
United Arab Emirates
MOHAP's streamlined halal certification pathway is attracting capsule producers to establish Jebel Ali free zone manufacturing for Middle East re-export. The regulator's framework bypasses redundant audits required in other Gulf jurisdictions. Dubai pharmaceutical logistics hubs concentrate frame contract negotiations as large-scale nutraceutical outsourcers seek consolidated vendor bases serving both Muslim and Jewish dietary law markets.
Halal and Kosher Empty Capsules Market Vendor Landscape
Swiss and Korean producers anchor one tier; Indian and Chinese specialists hold cost-optimized manufacturing positions. The vendor base splits between integrated multinationals funding simultaneous Orthodox Union and IFANCA audits and regional players competing on vegetarian capsule platforms. Three archetypes dominate: certification-integrated multinationals, cost-driven vegetarian specialists, and collagen-integrated gelatin producers. Capacity expansion and dual-certification platform development represent the dominant competitive moves as contract manufacturers demand single-source halal-kosher qualification.
Among certification-integrated multinationals, Lonza Group and ACG Associated Capsules exemplify the multinational archetype with regulatory-audited facilities spanning multiple jurisdictions. Suheung Co. Ltd. occupies a position within the collagen-integrated tier, leveraging geographic proximity to East Asian raw material sources. These three entities represent distinct strategic positions: Swissmedic-aligned European access, cost-optimized Indian manufacturing scale, and Korean upstream supply chain control.
| Leading Market Players |
|---|
| Suheung Co. Ltd. |
| CapsCanada |
| Lonza Group |
| HealthCaps India |
| Natural Capsules Limited |
| ACG Associated Capsules |
| Shanxi Guangsheng Capsule Limited |
| Sunil Healthcare |
| Qualicaps |
| Others |
Supply Flow & Price Mechanics
Bovine hide price indices in Brazil and Argentina cascade through gelatin supply chains into three-tier pricing structures across premium, standard, and economy levels for empty capsule producers. SFDA traceability mandates in Saudi Arabia and EMA MDR compliance costs in Europe compress margins at the procurement tier while contract manufacturers negotiate direct frame contracts that eliminate traditional distributor markups.
Pricing Analysis
Distributor margins of 15-25 percent in traditional pharmaceutical ingredient channels are collapsing as Malaysian and Indonesian contract manufacturers negotiate direct producer relationships that bypass wholesale layers entirely. Price differentiation hinges on dual-certification status (Orthodox Union kosher plus IFANCA halal) and validated dissolution performance for immediate-release pharmaceuticals. Pricing pressure stems from vegetarian capsule competition in India where HPMC formulations undercut bovine gelatin on input costs. Large-scale nutraceutical outsourcers exhibit lowest price sensitivity due to volume scale and multi-market certification requirements, while small compounding pharmacies remain highly price-sensitive and spot-market dependent.
Supply Chain Analysis
Dual-sourcing requirements from Saudi SFDA and Indonesia's BPJPH force contract manufacturers to qualify backup suppliers, extending procurement timelines but reducing single-source vulnerability. Geographic supply concentration centers on India, South Korea, and Switzerland for finished capsules, while Brazil and Argentina dominate bovine hide and bone inputs for gelatin production. Raw material dependencies encompass pharmaceutical-grade gelatin, hydroxypropyl methylcellulose, and pullulan for vegetarian alternatives. Supply chain risk manifests as regulatory restriction exposure where non-recognition between Indonesia's BPJPH and Malaysia's JAKIM halal bodies forces redundant facility audits. Distribution runs through direct sales channels for high-volume buyers, with wholesale distribution serving only mid-tier and spot-market purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Halal and Kosher Empty Capsules Market functions as a stable compounder anchored by irreversible regulatory mandates for religious certification across Muslim-majority pharmaceutical markets. SFDA, BPJPH, and JAKIM protocols create durable demand visibility that transcends cyclical fluctuations in end-use consumption.
For Market Incumbents: Cement market position through backward integration into pharmaceutical-grade gelatin production and captive halal certification audit capabilities. Lonza Group and ACG Associated Capsules demonstrate the defensive value of Swissmedic-audited facilities and cost-optimized vegetarian platforms respectively. Threat from South Korean collagen-integrated producers necessitates capacity addition in Jebel Ali free zones to capture UAE pharmaceutical outsourcing demand. Certification investment represents the priority lever for sustaining direct supplier relationships with consolidating contract manufacturers.
For New Entrants and Emerging Players: Begin with vegetarian capsule specialization targeting Indian nutraceutical contract manufacturers where Hindu dietary restrictions and vegan positioning displace bovine gelatin. The most penetrable white-space sits in dual-certification platforms serving both Muslim and Jewish dietary law markets from single production lines. Geographic entry should concentrate on MOHAP-streamlined UAE pathways rather than SFDA-compressed Saudi qualification timelines. Go-to-market angle centers on dissolution performance parity with gelatin equivalents for immediate-release applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with collagen-integrated mid-caps possessing existing pharmaceutical-grade halal certification and East Asian raw material proximity. Long-term viability over a five-to-ten year window rests on regulatory mandate durability rather than discretionary consumer preference. Acquisition target archetype encompasses South Korean producers with MFDS-aligned export pathways and underutilized capacity for Middle East API outsourcing expansion. Signal to watch is mutual recognition agreements between Indonesia's BPJPH and Malaysia's JAKIM halal bodies that would compress redundant audit costs and accelerate product launch timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Platform Development | Single-production-line halal-kosher qualification reduces SKU complexity for contract manufacturers serving multi-faith markets. |
| Backward Integration into Gelatin Production | In-house pharmaceutical-grade gelatin manufacturing insulates margin from Brazilian and Argentine livestock cycle volatility. |
| Jebel Ali Free Zone Manufacturing | MOHAP's streamlined halal certification pathway enables Middle East re-export without redundant Gulf jurisdiction audits. |
| Vegetarian Formulation R&D Investment | HPMC dissolution profile improvements address performance gaps limiting adoption in immediate-release pharmaceutical applications. |
| Direct Sales Channel Expansion | Producer-to-manufacturer relationships bypass wholesale markups and lock in multi-year frame contracts with consolidating outsourcers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with capsule manufacturing executives, regulatory affairs leads at halal certification bodies, procurement directors at Malaysian and Indonesian contract manufacturers, and pharmaceutical quality heads at Saudi importers with secondary validation. Secondary sources encompassed SFDA import licensing databases, EMA MDR guidance documents, BPJPH and JAKIM halal certification registries, and customs trade data for gelatin and empty capsule movements. Bottom-up volume builds across product type, application, end user, and distribution channel segments were triangulated against top-down market sizing from regulatory filing analysis.
Historical reference periods anchored the projection horizon through trend extrapolation of certification mandate adoption curves and contract manufacturing concentration patterns. Segmentation dimensions modeled encompassed material composition (gelatin versus vegetarian), end-use specification intensity (pharmaceutical cGMP versus nutraceutical speed-to-market), procurement scale (direct frame contract versus spot wholesale), and geographic regulatory cluster (SFDA-mandated, BPJPH-mandated, voluntary certification). CAGRs derived from regression analysis of certification penetration rates and outsourcing contract growth trajectories. Industry-specific forecast inputs included halal authority recognition agreement momentum and HPMC formulation dissolution profile advancement.
Several conditions sit outside the modeled scope, including abrupt halal authority recognition reversals, novel vegetarian capsule material breakthroughs, and pharmaceutical industry consolidation beyond contract manufacturing tier concentration. Forecasts reflect assumptions regarding regulatory mandate durability and certification cost trajectory stability. Deviation in mutual recognition between Indonesia's BPJPH and Malaysia's JAKIM halal bodies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Safflower Oil Market
Ingredients
Rice Bran Oil Market
Ingredients
Beetroot Powder Market
Ingredients
Chickpea Flour Market
Ingredients
Rose Hips Extract Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
South America Clean Ingredients Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Potato Granules Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Instant Dry Yeast Market
Ingredients
Amaranth Seed Oil Market
Ingredients
Omega-3 Encapsulation Market