
 Textured Wheat Protein Market | 2026-2036
Textured Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Textured Wheat Protein Market Analytics
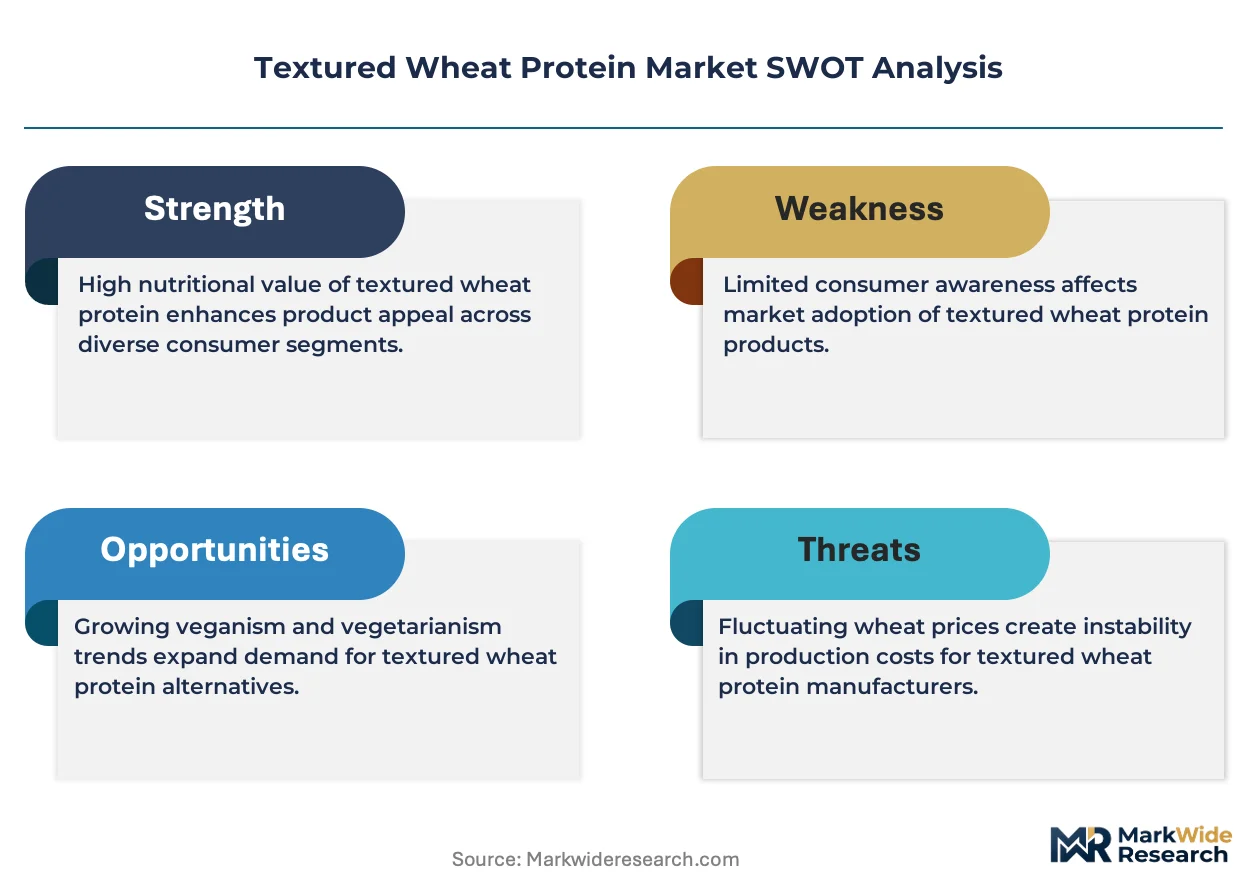
Clean-label specification tiers is reorganizing procurement priorities across the textured wheat protein value chain. ADM leverages its North American grain origination network to secure cost-advantaged wheat supply for protein extraction. Roquette Frères differentiates through European pea-wheat protein blending capabilities that address hybrid formulation demand. Kerry Group specializes in customized texture systems that bind water and fat in meat-analog applications, occupying a high-margin niche in ingredient solutions.
Textured wheat protein denotes wheat gluten that has been extruded under controlled heat and shear to create fibrous, elastic structures mimicking meat mouthfeel, typically containing 75-80% protein on a dry basis and rehydrating at ratios of 2.5-3.5 parts water to one part protein. The material functions primarily as a structural backbone in plant-based meat formulations, providing chew resistance and water-holding capacity that starch or soy isolates cannot replicate alone. Granules and flakes currently lead volume throughput in industrial meat-alternative processing due to their rapid hydration and uniform particle size distribution. Dry form commands the widest addressable market because ambient stability slashes cold-chain expenditure and extends export reach into developing food-processing sectors.
FDA GRAS self-affirmation pathways and USDA-FSIS labeling oversight govern textured wheat protein deployment in U.S. meat-analog products, while EFSA novel-food consultations and EU Regulation 1169/2011 allergen declarations shape European formulation transparency and market access conditions. China's SAMR national food safety standards and GB/T wheat gluten specifications impose protein-content minimums that filter low-grade imports from Southeast Asian suppliers. Stakeholders must monitor evolving allergen threshold debates and carbon-footprint disclosure mandates that threaten to recast wheat protein's competitive position against emerging fermentation-derived alternatives.
Market Dynamics
Clean-label specification tiers are reorganizing procurement priorities across the textured wheat protein value chain, as European food processors accelerate reformulation under EU Green Deal sustainability mandates and flexitarian dietary patterns reshape ingredient demand.
Growth Catalysts
- EU Green Deal mandates:Binding carbon-footprint disclosure requirements and clean-label ingredient standards are forcing European food processors to replace soy isolates with domestically sourced wheat protein in meat-analog formulations.
- Flexitarian dietary pivot:Consumer adoption of reduced-meat diets in Germany and the United States is expanding the addressable market for plant-based meat alternatives that rely on textured wheat protein as a structural backbone.
- Extrusion technology maturation:Advances in high-moisture extrusion systems are improving fiber alignment and mouthfeel replication, enabling textured wheat protein to displace methylcellulose in premium meat-analog applications.
Market Restraints
- Wheat gluten supply concentration:North American grain origination networks dominate cost-advantaged wheat supply, creating input cost volatility for European and Asian processors dependent on imported feedstock.
- Allergen labeling friction:EU Regulation 1169/2011 mandates prominent wheat allergen declarations that deter clean-label positioning and limit formulation flexibility in European retail products.
- Fermentation-derived protein emergence:Precision fermentation platforms producing functional proteins from biomass are threatening textured wheat protein's cost position in high-margin meat-analog segments.
Strategic Opportunities
- Hybrid protein blending:Convergence of pea protein isolate and textured wheat protein extrusion is opening formulation white space that addresses European demand for complete amino-acid profiles without soy allergen concerns.
- Southeast Asian processing expansion:China's SAMR national food safety standards and GB/T protein-content specifications are filtering low-grade imports, creating premium positioning opportunities for compliant suppliers in regional meat-alternative manufacturing.
- Direct-to-foodservice distribution:Bypassing traditional ingredient distributors to supply customized hydration systems and texture solutions directly to plant-based meat startups is compressing channel margins and capturing formulation partnership value.
Industry Challenges
- Extrusion operator skill scarcity:High-moisture extrusion requires precise control of heat, shear, and moisture profiles that few plant-based meat facilities can consistently execute, creating quality variability and yield loss.
- Cross-contamination certification timelines:Gluten-free facility audits and allergen segregation protocols required by European retailers are extending new supplier qualification cycles and inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textured Wheat Protein Market |
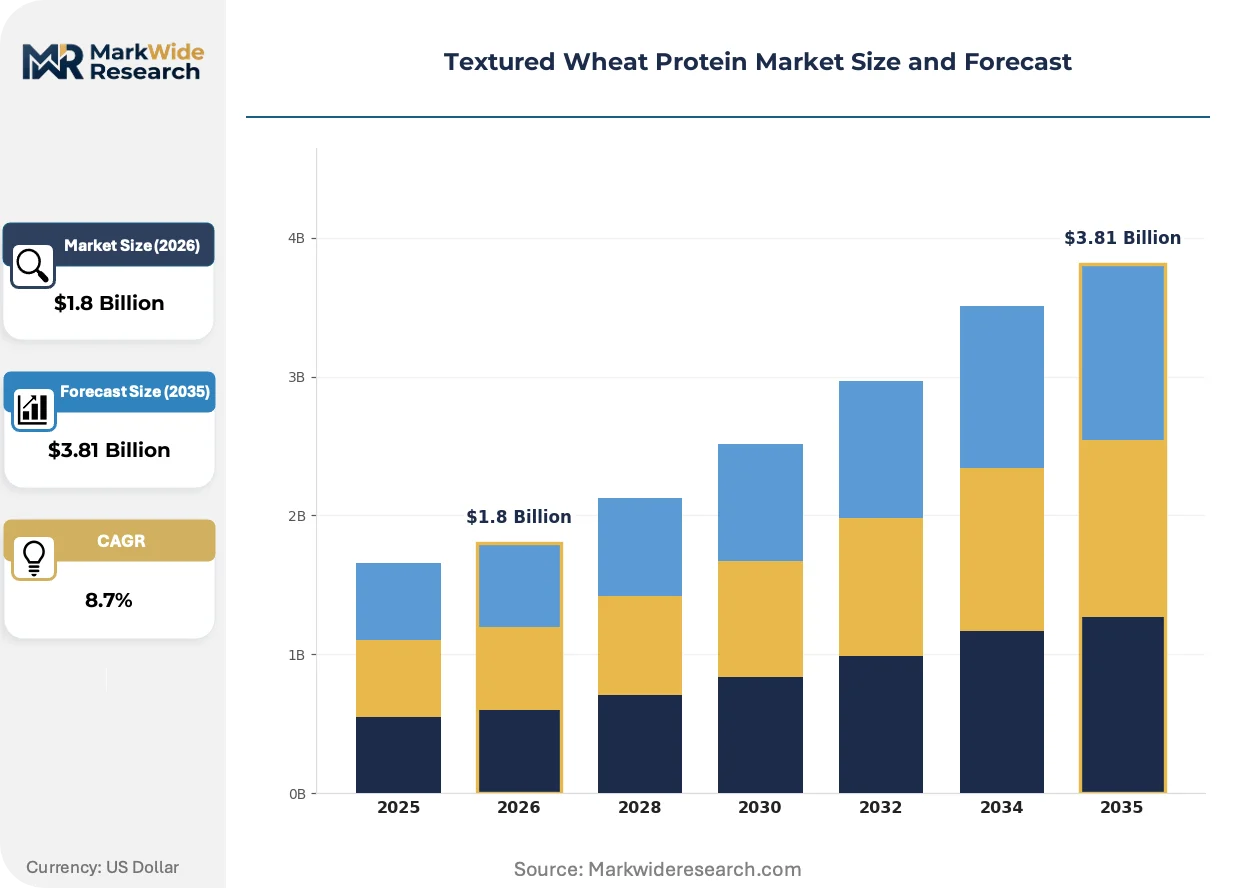
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slices, Nuggets, Granules, Flakes End Use Industry: Food Processing, Nutraceuticals, Animal Feed, Meat Alternatives Form: Dry, Frozen, Wet, Cooked Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | ADM, Cargill, Roquette Frères, MGP Ingredients, AGRANA Beteiligungs-AG, Manildra Group, Foodchem International Corporation, Kerry Group, Glico Nutrition Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textured Wheat Protein Market Evolving Landscape
Extrusion technology advancement and regulatory disclosure mandates are converging to reshape competitive positioning in textured wheat protein, as formulation science and supply chain transparency become inseparable value drivers.
High-moisture extrusion is decomposing the traditional dry-textured protein supply model by enabling continuous production of fibrous structures with meat-like anisotropy. Plant-based meat manufacturers in Germany and the Netherlands are adopting these systems at pilot scale, replacing batch-processed dry granules with fresh-frozen extrudates that reduce rehydration steps and improve finished-product yield. This technology is decomposing the historical advantage of ambient-stable dry forms by compressing cold-chain costs through localized production.
EFSA novel-food consultation pathways and EU Regulation 1169/2011 allergen disclosure requirements are tightening formulation transparency standards across European retail channels. Processors must now document protein-source provenance and carbon-intensity metrics that previously escaped scrutiny, elevating compliance costs for imported textured wheat protein. Small-format clean-label brands in France and Italy are responding by sourcing exclusively from EU-milled wheat with verified supply chain documentation.
Foodservice operators are consolidating procurement around pre-hydrated textured wheat protein slurries delivered in refrigerated totes rather than dry bulk bags requiring on-site reconstitution. This purchasing pattern shift is disrupting traditional ingredient distribution in the United States, where plant-based meat startups in California and New York are negotiating direct supply agreements that bypass national distributors. The model is most visible in quick-service restaurant chains piloting proprietary meat-analog formulations with shortened development cycles.
Textured Wheat Protein Market Segmentation
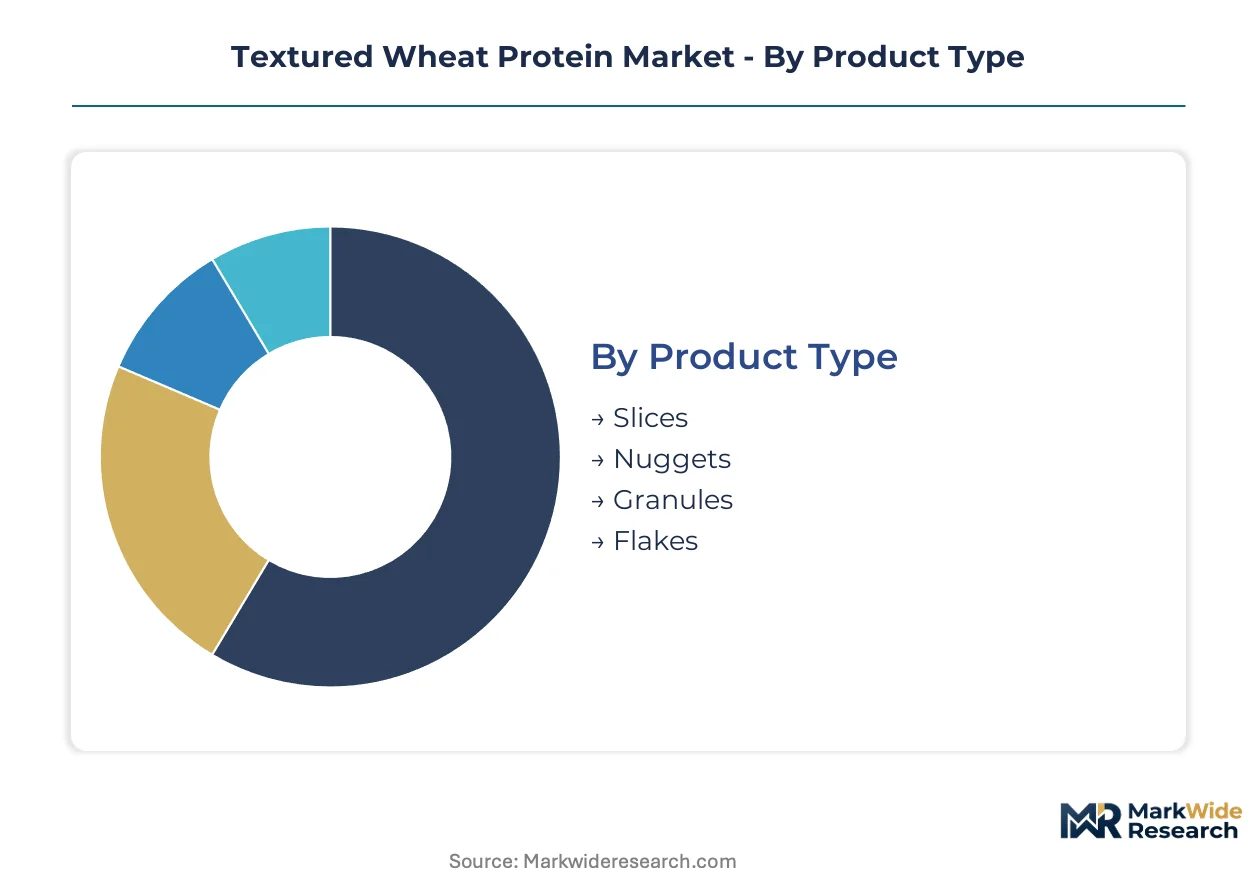
Textured wheat protein exhibits divergent margin profiles across physical formats and supply channels, with extrusion geometry and hydration state determining application suitability and pricing power. Procurement patterns in plant-based meat manufacturing are fragmenting traditional volume-concentration assumptions as foodservice operators demand pre-processed intermediates.
Product Type:
Granules command the deepest margin pools due to their universal compatibility with industrial rehydration systems and minimal downstream processing requirements.
- Granules:Spherical particles with rapid water absorption kinetics and uniform particle size distribution. Meat-alternative processors in Germany and the Netherlands favor granules for high-throughput extrusion lines that demand consistent feedstock flow. Their ambient stability slashes cold-chain expenditure versus competing geometries.
- Flakes:Laminated structures with anisotropic fiber alignment that mimics shredded meat texture. Premium plant-based chicken formulations in California foodservice channels specify flakes for their superior mouthfeel replication, though slower hydration limits line speeds.
- Slices:Pre-formed sheets targeting deli-meat analog applications with minimal downstream shaping.
- Nuggets:Irregular chunks for breaded meat-alternative products requiring freeze-thaw stability.
Granules hold installed capacity. Flakes are rotating up the share rankings.
End Use Industry:
Volume concentration tilts toward applications where wheat protein functions as irreplaceable structural backbone rather than commodity filler.
- Meat Alternatives:The dominant value-creation segment where textured wheat protein provides chew resistance and water-holding capacity that starch or soy isolates cannot replicate alone. Flexitarian dietary adoption in the United States and Germany is expanding formulation demand for hybrid protein systems combining wheat gluten with pea isolates.
- Food Processing:Industrial bakeries and prepared-meal manufacturers use textured wheat protein for moisture retention and protein fortification in European clean-label reformulations.
- Nutraceuticals:Protein powder applications with lower margin capture due to commodity competition from whey and soy isolates.
- Animal Feed:Cost-sensitive pet food and aquaculture formulations where wheat gluten competes on protein-content pricing.
Meat Alternatives capture formulation partnership value. Food Processing is climbing the fastest as EU Green Deal mandates accelerate reformulation.
Form:
Supply chain configuration determines addressable market radius, with hydration state dictating cold-chain dependency and export feasibility.
- Dry:Ambient-stable granules and flakes with protein content of 75-80% on a dry basis. This form reaches developing food-processing sectors in Southeast Asia without refrigerated logistics, though rehydration adds manufacturing steps.
- Frozen:Pre-hydrated extrudates delivered in refrigerated totes directly to plant-based meat startups in California and New York, bypassing traditional distributors.
- Wet:Slurry formats for foodservice operators consolidating procurement around ready-to-use intermediates.
- Cooked:Thermally treated products for ready-meal manufacturers seeking reduced preparation time.
Dry dominates export reach. Frozen is gaining share fastest as high-moisture extrusion localizes production.
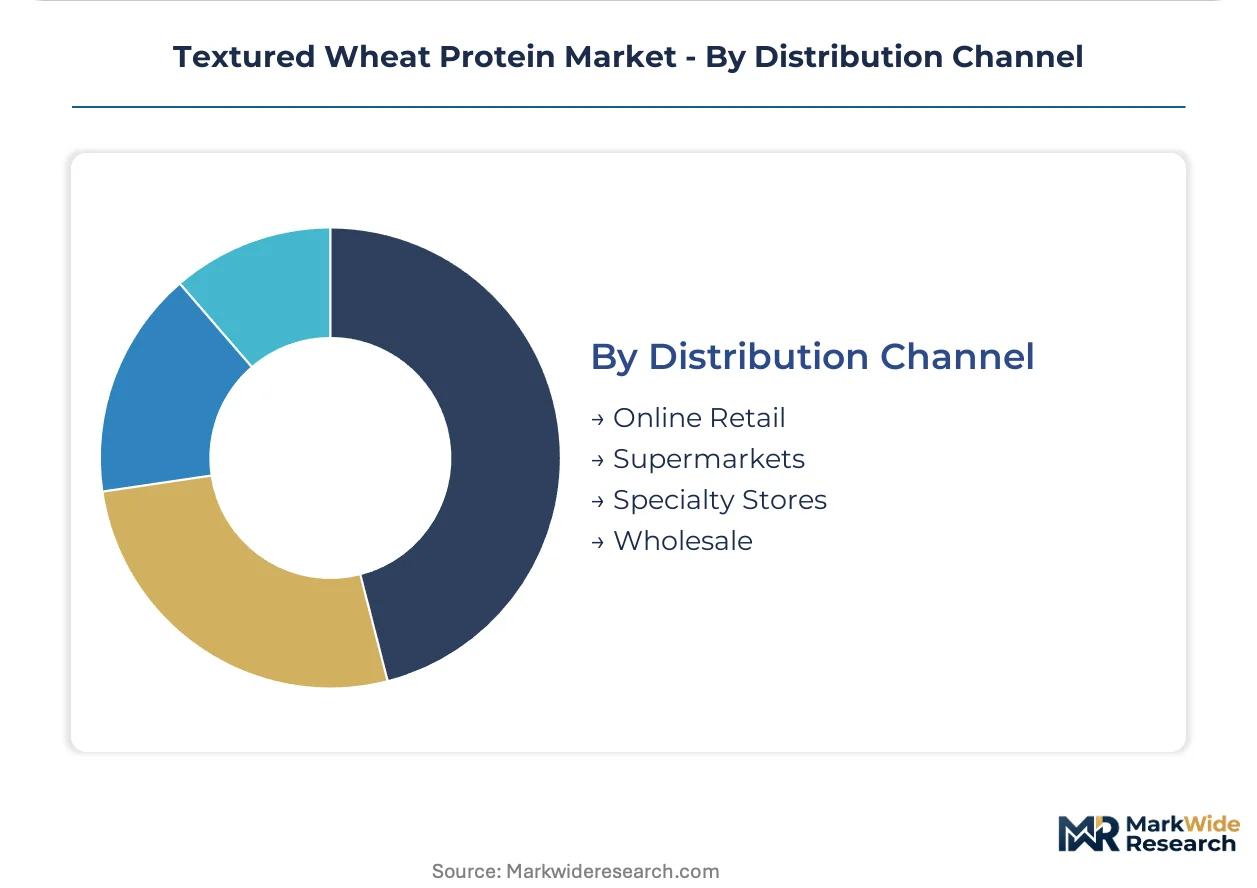
Distribution Channel:
Channel selection separates commodity volume plays from high-margin formulation partnerships.
- Wholesale:Bulk supply to industrial meat-alternative manufacturers with multi-ton procurement volumes and technical specification negotiations.
- Specialty Stores:Small-format ingredient sales to craft plant-based meat producers and clean-label brands in France and Italy sourcing EU-milled wheat with verified provenance.
- Supermarkets:Retail packaged proteins for home cooks in flexitarian households.
- Online Retail:Direct-to-consumer sales with limited current traction due to bulk packaging requirements.
Wholesale anchors volume throughput. Specialty Stores are rotating up the share rankings as clean-label documentation commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extrusion capacity supplies wheat protein formulations to Dutch and British meat-alternative processors, while Chinese production under SAMR standards feeds Southeast Asian food manufacturing expansion.
United States
Flexitarian household penetration in California and New York drives foodservice procurement of pre-hydrated protein slurries. FDA GRAS self-affirmation pathways govern meat-analog deployment, with USDA-FSIS labeling oversight shaping retail transparency requirements. Chicago-area grain origination networks anchor North American wheat supply for cost-advantaged protein extraction.
Germany
Clean-label reformulation mandates under EU Green Deal sustainability targets accelerate domestic wheat protein adoption in meat-alternative processing. EFSA novel-food consultation pathways and EU Regulation 1169/2011 allergen declarations impose formulation transparency standards. Cologne-Düsseldorf industrial corridors concentrate high-moisture extrusion pilot facilities serving premium plant-based chicken formulations.
China
Expanding middle-class protein diversification shifts food manufacturing toward hybrid wheat-pea protein systems in coastal provinces. SAMR national food safety standards and GB/T wheat gluten specifications filter low-grade imports through protein-content minimums. Yangtze River Delta processing hubs scale capacity for regional meat-alternative manufacturing under stricter compliance thresholds.
Netherlands
European distribution centrality positions Dutch ports as wheat protein re-export nodes for French and Italian clean-label brands. EFSA novel-food pathways and carbon-footprint disclosure requirements elevate documentation burdens on imported feedstock. Rotterdam logistics clusters facilitate direct-to-foodservice distribution models bypassing traditional ingredient wholesalers.
France
Small-format clean-label brands in Île-de-France and Provence-Alpes-Côte d'Azur source exclusively from EU-milled wheat with verified supply chain documentation. EU Regulation 1169/2011 allergen labeling and EU Green Deal carbon-intensity metrics reshape procurement specifications. Lyon food-processing corridors specialize in hybrid protein blending addressing complete amino-acid profile demands without soy allergen exposure.
Textured Wheat Protein Market Competitive Landscape
Listed leaders compete with private specialists across grain origination networks and extrusion technology tiers, creating a bifurcated structure where scale-driven commodity supply intersects with customized formulation partnerships. The vendor base organizes around three strategic archetypes: integrated grain processors controlling upstream wheat supply, European extrusion specialists commanding hybrid protein blending capabilities, and ingredient solution providers capturing high-margin texture system niches. Dominant competitive moves include backward integration into captive wheat supply and direct distribution channel compression bypassing traditional wholesalers.
Within the integrated processor tier, ADM leverages North American grain origination networks, while Cargill exemplifies scale-driven commodity positioning. Roquette Frères occupies a distinct European specialization vector through pea-wheat protein blending capabilities. Kerry Group anchors the ingredient solutions archetype with customized texture systems for meat-analog applications.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Roquette Frères |
| MGP Ingredients |
| AGRANA Beteiligungs-AG |
| Manildra Group |
| Foodchem International Corporation |
| Kerry Group |
| Glico Nutrition Foods |
| Others |
Value Network & Pricing Analysis
High-moisture extrusion displacing dry-textured protein systems simultaneously relocates production geography toward foodservice clusters and compresses margin structures for ambient-stable formats. European processors absorbing EU Green Deal carbon-footprint disclosure costs face divergent pricing economics against North American grain-origination competitors.
Pricing Analysis
Prior-generation dry granule pricing faces compression from next-generation fresh-frozen extrudate premiums. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with EU-milled wheat commanding documentation premiums over imported feedstock. Pricing pressure stems from fermentation-derived protein emergence in high-margin meat-analog segments. Foodservice operators exhibit lowest price sensitivity due to formulation partnership value, while industrial bulk buyers maximize procurement leverage.
Supply Chain Analysis
North American grain origination networks underwrite cost-advantaged wheat protein extraction for global export. Supply concentrates in the United States, Germany, and China as regional production hubs, with feedstock quality resting on protein-content specifications and gluten strength metrics. Single-source vulnerability concentrates in Chicago-area grain elevators and Yangtze River Delta processing corridors. Distribution runs through wholesale bulk channels for industrial meat-alternative manufacturers, with direct-to-foodservice models gaining traction in California and New York startup clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Textured wheat protein sits in early-cycle expansion as flexitarian dietary penetration accelerates reformulation demand across European and North American food processors.
For Market Incumbents: Secure captive wheat supply through backward integration into North American grain origination networks to defend margin position against fermentation-derived protein substitution. Invest in high-moisture extrusion capacity within Cologne-Düsseldorf and California foodservice corridors to capture premium positioning from localized fresh-frozen production.
For New Entrants and Emerging Players: EU organic certification fast-tracks market access for small-format clean-label brands in France and Italy demanding verified supply chain documentation. Target hybrid protein blending white space combining pea isolates with wheat gluten for complete amino-acid profiles. Pursue direct distribution partnerships with plant-based meat startups bypassing traditional ingredient wholesalers.
For Investors and Strategic Acquirers: Capital is best deployed toward European extrusion specialists with pea-wheat protein blending capabilities and established EFSA novel-food consultation pathways. Long-term viability hinges on differentiation from commodity-grade suppliers facing price erosion. Monitor precision fermentation platform scale-up as inflection indicator for structural displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive wheat supply locks in cost advantage against import-dependent European competitors under EU Green Deal carbon pricing. |
| High-Moisture Extrusion Capacity Expansion | Fresh-frozen extrudate production localizes supply chains for California and New York foodservice operators. |
| Hybrid Protein Blending R&D Investment | Pea-wheat formulations address European clean-label demand while circumventing soy allergen labeling friction. |
| Direct-to-Foodservice Distribution Model | Bypassing traditional wholesalers captures formulation partnership value with plant-based meat startups. |
| EU Organic Certification Program | Verified supply chain documentation commands premium positioning in French and Italian small-format retail channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS self-affirmation filings, EFSA novel-food consultation records, SAMR national food safety standards, and trade customs data. Interviews with extrusion technology directors, procurement leads at plant-based meat manufacturers, ingredient distribution channel partners, and regulatory affairs specialists informed demand-side validation. Bottom-up volume modeling triangulated against top-down value estimates from grain origination network disclosures and protein extraction capacity announcements.
Segmentation dimensions modeled include physical format geometry, hydration state, end-use application, and distribution channel structure across the analysis window. CAGRs derived from elasticity-adjusted demand projections incorporating flexitarian dietary penetration rates and EU Green Deal reformulation timelines. Industry-specific inputs encompass high-moisture extrusion adoption curves and allergen labeling compliance cost trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU carbon-footprint disclosure mandates and stable North American grain supply; material deviation in fermentation-derived protein cost curves would warrant model refresh. Practitioners should keep alternative scenarios live as precision fermentation scale-up and hybrid protein formulation preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Oyster Shell Powder Market
Ingredients
Specialty Malt Market
Ingredients
Wheat Starch Market
Ingredients
Fluid Lecithin Market
Ingredients
Salt Market
Ingredients
GCC Egg Powder Market
Ingredients
Cocoa Liquor Market
Ingredients
Rose Extract Market
Ingredients
North America Soybean Oil Market
Ingredients
Agarwood Oil Market
Ingredients
Fermented Ingredients Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
High Oleic Oil Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Glucosylglycerol Market