
 Latin America Postal Service Market | 2026-2036
Latin America Postal Service Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Postal Service Market Foresight
The gap between premium express delivery and standard postal service is broadening across Latin America. Brazilian Post anchors universal coverage through its nationwide retail network, while DHL Express differentiates via time-definite international express lanes. Chilexpress specializes in cross-border e-commerce fulfillment between Santiago and regional distribution nodes.
Latin America postal service encompasses physical mail, parcel logistics, and last-mile delivery infrastructure operating through integrated sorting hubs, ground transport fleets, and customs brokerage functions, with delivery performance measured in transit-time reliability and customs clearance velocity. Express Delivery captures margin pools from cross-border e-commerce shippers requiring bonded warehouse integration, while Standard Mail retains volume dominance through government correspondence and utility billing contracts. Drone Delivery remains nascent, constrained by aviation regulator certification timelines and mountainous terrain in Andean corridors.
Brazil's national telecommunications regulator and Mexico's federal competition authority enforce interconnection rules and pricing transparency that determine market access for private carriers versus incumbent postal operators. Chile's consumer protection agency mandates delivery-time disclosures that reshape service-level agreements for e-commerce platforms. Stakeholders must monitor how universal service fund contributions and cross-border data requirements for customs pre-clearance reshape cost structures across the region.
Market Dynamics
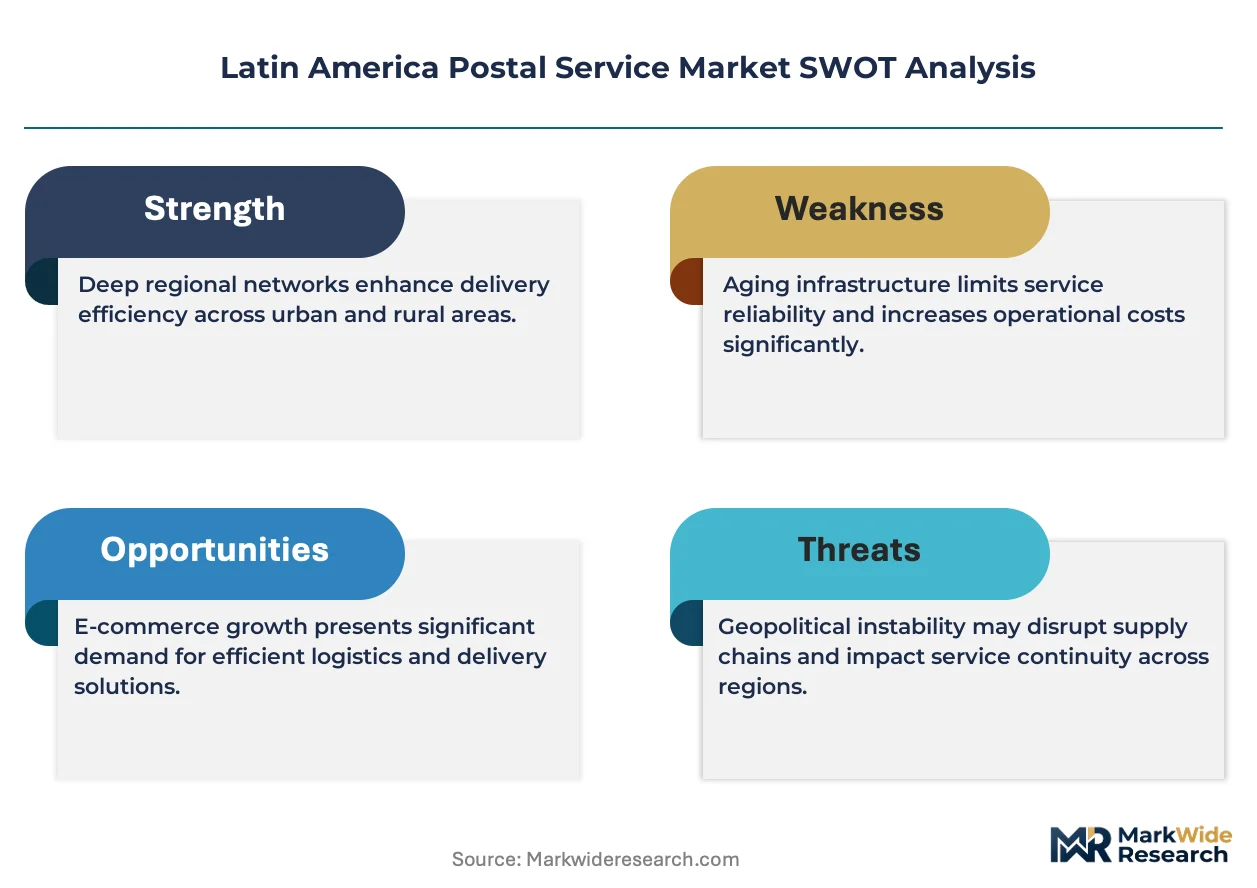
The divergence between premium express delivery and universal postal obligations is restructuring capital allocation across Latin American logistics networks. National regulators in Brazil, Mexico, and Chile are tightening service-level mandates while e-commerce platforms demand bonded warehouse integration and sub-48-hour fulfillment.
Growth Catalysts
- Cross-border e-commerce fulfillment:Chilexpress and regional carriers are expanding bonded warehouse capacity in Santiago and São Paulo to capture customs pre-clearance volume from Asia-Pacific shippers.
- ANVISA pharmaceutical distribution mandates:Brazil's national health regulator requires temperature-controlled last-mile protocols for biologics, creating specialized delivery infrastructure investments.
- Southeastern Brazil corridor concentration:São Paulo and Rio de Janeiro metropolitan zones generate disproportionate parcel density, enabling hub-and-spoke network economies for express operators.
Market Restraints
- Fuel price volatility:Ground transport fleets across Mexico and Brazil face diesel cost swings that compress margins on standard mail routes with fixed tariff ceilings.
- Andean terrain limitations:Mountainous corridors in Peru, Colombia, and Chile restrict truck payload efficiency and extend transit times versus coastal alternatives.
- Universal service fund obligations:Brazil's telecommunications regulator mandates cross-subsidy contributions that divert capital from competitive express infrastructure.
Strategic Opportunities
- Drone certification pathways:Chile's civil aviation authority is piloting beyond-visual-line-of-sight frameworks for remote Andean delivery, opening mountainous zones currently served only by ground couriers.
- Reverse logistics integration:E-commerce platforms in Mexico City and Guadalajara are unbundling returns processing from forward delivery, creating standalone service contracts.
- Data interoperability standards:Mercosur customs harmonization initiatives are enabling single-window clearance across Brazil, Argentina, and Uruguay, reducing cross-border friction.
Industry Challenges
- Customs broker talent scarcity:Cross-border e-commerce growth is outpacing trained personnel capable of managing HS code classification and duty optimization.
- Sorting hub automation capex:Legacy facilities in Buenos Aires and Lima require conveyor and optical character recognition upgrades to handle parcel volume surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Postal Service Market |
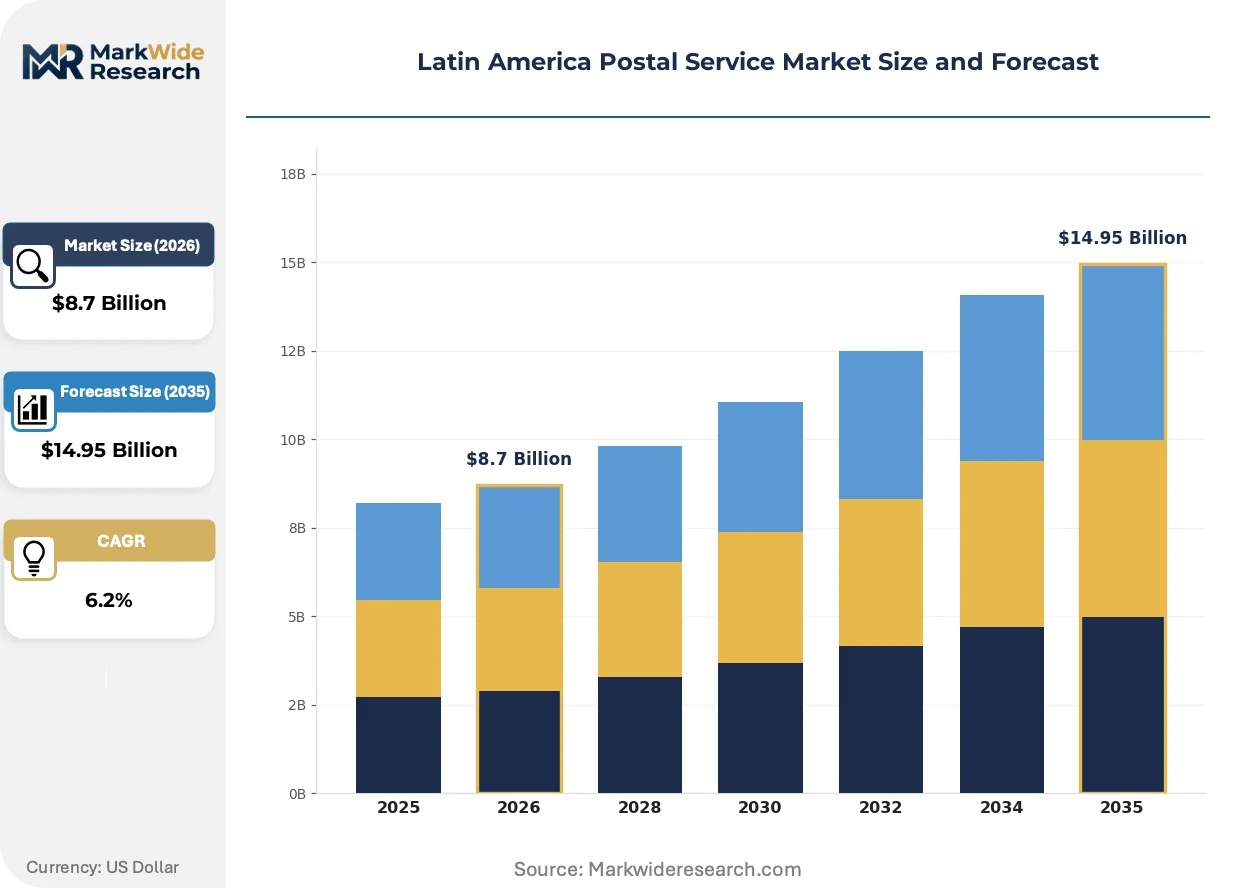
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Mail, Express Delivery, Registered Mail, International Shipping Customer Type: Individuals, Small Businesses, Corporations, Government Agencies Delivery Method: Air Freight, Ground Transport, Maritime Shipping, Drone Delivery Pricing Model: Flat Rate, Weight-Based, Volume-Based, Subscription Plans |
| Companies Covered | UPS Brazil, Chilexpress, Brazilian Post, Loggi, Serpost, Correos de México, FedEx Mexico, DHL Express, SkyPost, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Postal Service Market Shifts & Advancements
Digital freight platforms and automated sortation are compressing transit-time variance across Latin American postal networks. Regulatory pressure on emissions disclosure and consumer protection is forcing service-level transparency that reshapes carrier contracts.
Intelligent parcel lockers are unifying last-mile handoff points across Brazilian apartment complexes and Mexico City commercial districts. Property developers in São Paulo and Rio de Janeiro are pre-installing refrigerated and ambient locker banks, enabling carriers to consolidate delivery attempts. This infrastructure is unifying previously fragmented residential access and reducing failed-delivery rates that plagued single-attempt courier models.
Chile's consumer protection agency now mandates delivery-time disclosure windows for all e-commerce transactions, with penalties for missed commitments. Retail platforms are restructuring carrier contracts to pass liability downstream, forcing postal operators to invest in real-time tracking APIs. The regulation is compressing acceptable variance in Santiago-Valparaíso corridor service, where same-day and next-day tiers must now publish statistical performance guarantees.
Subscription box merchants are consolidating procurement of fulfillment services around integrated warehousing-plus-delivery contracts. Beauty and electronics verticals in Brazil are displacing spot-market courier relationships with annual volume commitments that include returns processing. This bundling is most visible in São Paulo's Guarulhos distribution cluster, where dedicated contract logistics space is displacing multi-tenant shared warehousing for mid-scale e-commerce sellers.
Latin America Postal Service Market Segmentation
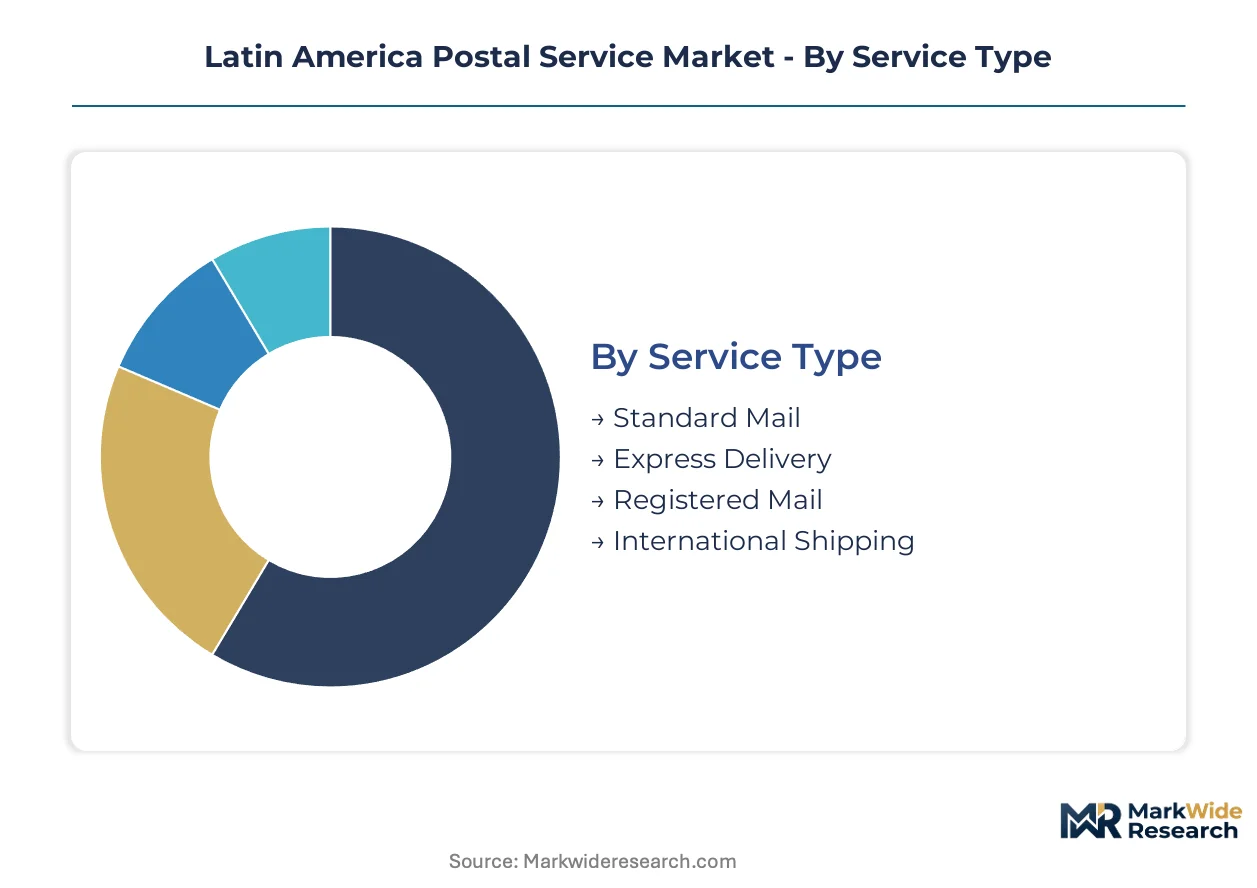
Segmentation across Latin America postal services reveals how infrastructure investments align with divergent service economics. Express operators prioritize bonded warehouse networks while universal service obligations anchor standard mail coverage. Understanding these divides clarifies where margin pools concentrate versus where volume scales.
Service Type:
Supply concentration in São Paulo and Rio de Janeiro corridors shapes which service tiers capture network economies.
- Standard Mail:Government correspondence and utility billing contracts sustain volume through Brazilian Post's retail network. Fixed tariff ceilings under universal service obligations limit margin expansion despite route density advantages in southeastern Brazil.
- Express Delivery:Time-definite international lanes with customs pre-clearance integration command premium positioning. E-commerce platforms in Santiago and São Paulo are consolidating procurement around sub-48-hour fulfillment guarantees with bonded warehouse handoffs.
- Registered Mail:Secure document chains with signature capture serve legal and financial institutions. Chile's consumer protection agency mandates delivery-time disclosures that reshape service-level agreements for this segment.
- International Shipping:Cross-border parcel flows require HS code classification and duty optimization capabilities. Mercosur customs harmonization is reducing friction for Brazil-Argentina-Uruguay corridors.
Express Delivery absorbs the bulk of installed capacity; Express Delivery is expanding most quickly.
Customer Type:
Cost tier differentiation separates procurement patterns across the customer base.
- Corporations:Annual volume commitments with integrated warehousing-plus-delivery contracts displace spot-market relationships. Beauty and electronics verticals in São Paulo's Guarulhos cluster are bundling returns processing into forward logistics agreements.
- Small Businesses:Subscription box merchants consolidate fulfillment procurement around standalone service contracts. Guadalajara and Mexico City sellers are unbundling returns processing from forward delivery.
- Individuals:Residential delivery relies on intelligent parcel locker consolidation across Brazilian apartment complexes. Failed-delivery rates are compressing as property developers pre-install refrigerated and ambient locker banks.
- Government Agencies:Universal service fund contributions mandate nationwide coverage regardless of route economics. Brazil's telecommunications regulator enforces cross-subsidy obligations that divert capital from competitive infrastructure.
Corporations absorb the bulk of installed capacity; Small Businesses are climbing the fastest.
Delivery Method:
Application-specific requirements dictate modal selection across terrain and customs complexity.
- Ground Transport:Diesel-powered fleets dominate standard mail routes with fixed tariff ceilings. Fuel price volatility compresses margins on routes serving universal service obligations in Mexico and Brazil.
- Air Freight:Temperature-controlled protocols for ANVISA-mandated pharmaceutical distribution require specialized last-mile infrastructure. Biologics handling is reshaping hub-and-spoke network design around São Paulo.
- Maritime Shipping:Bulk parcel consolidation for non-urgent cross-border flows leverages coastal corridor efficiency. Andean terrain limitations restrict truck payload efficiency, favoring maritime alternatives for Pacific-facing ports.
- Drone Delivery:Beyond-visual-line-of-sight frameworks under Chile's civil aviation authority pilot are opening mountainous zones. Certification timelines and Andean terrain constraints keep deployment nascent relative to ground alternatives.
Ground Transport absorbs the bulk of installed capacity; Drone Delivery is gaining share fastest.
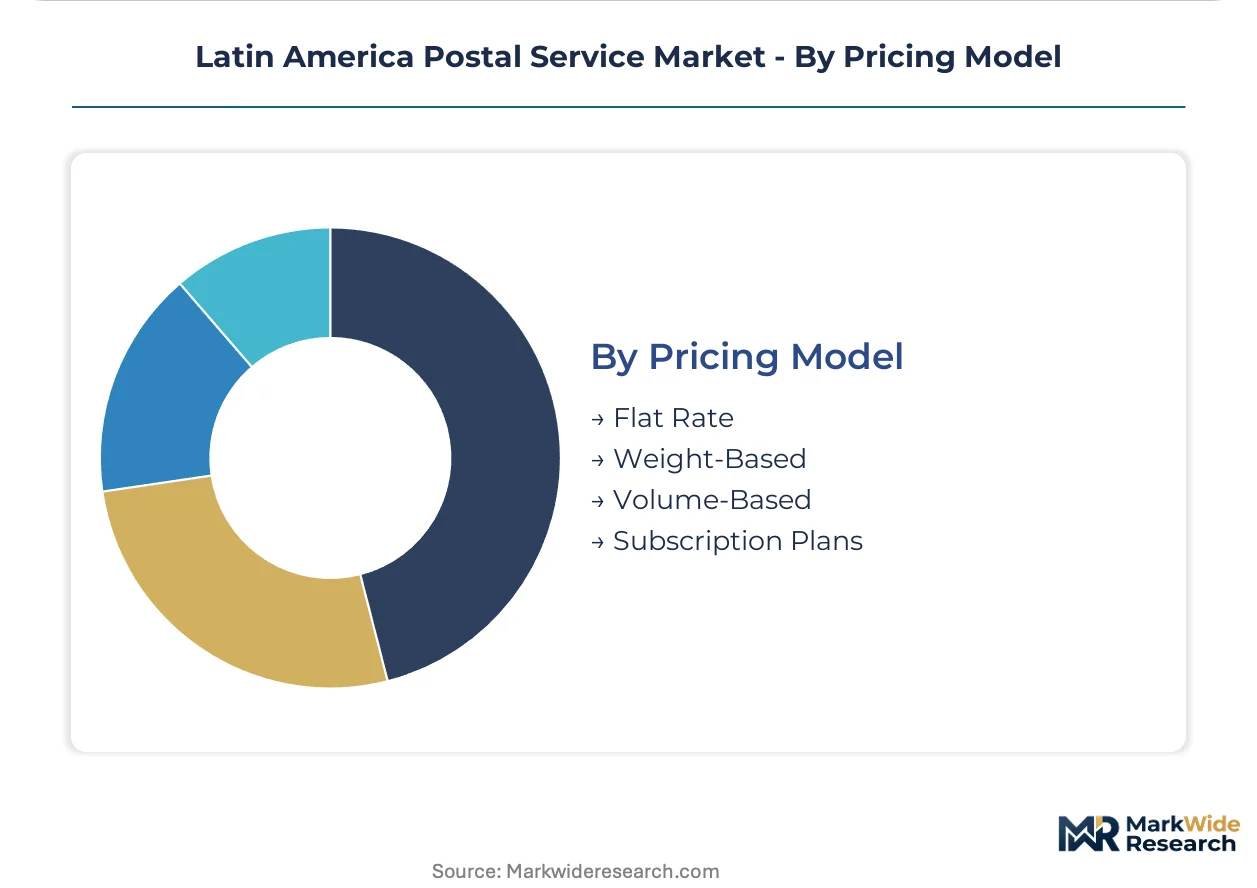
Pricing Model:
Margin structure varies sharply between fixed-commitment and variable-consumption arrangements.
- Volume-Based:Annual procurement contracts with tiered rate cards dominate mid-scale e-commerce seller relationships. São Paulo's dedicated contract logistics space is displacing multi-tenant shared warehousing under this model.
- Subscription Plans:Flat-fee structures for predictable shipping volumes reduce administrative overhead for platform sellers. Mercado Libre and regional marketplaces are negotiating enterprise subscriptions with performance guarantees.
- Weight-Based:Traditional postal tariffs apply dimensional weight calculations for parcel classification. Legacy sorting hubs in Buenos Aires and Lima require optical character recognition upgrades to handle surging volume under this model.
- Flat Rate:Simplified pricing for standardized envelope and small parcel formats retains dominance in individual correspondence. Brazilian Post's retail network anchors this tier through universal coverage mandates.
Volume-Based absorbs the bulk of installed capacity; Subscription Plans are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin American postal service demand through its southeastern Brazil corridor, where metropolitan parcel density enables hub-and-spoke network economies for express operators.
Brazil
E-commerce platforms in São Paulo and Rio de Janeiro drive express delivery adoption, while cross-border fulfillment from Asia-Pacific shippers concentrates in Guarulhos distribution clusters. ANVISA mandates temperature-controlled last-mile protocols for pharmaceutical distribution, reshaping biologics infrastructure investments. The southeastern corridor generates disproportionate parcel volume, enabling Brazilian Post to sustain universal coverage through retail network density.
Mexico
Mexico City and Guadalajara metropolitan zones unbundle returns processing from forward delivery, creating standalone reverse logistics contracts. The federal competition authority enforces interconnection rules and pricing transparency that determine private carrier market access versus incumbent postal operators. Nuevo León's industrial corridor attracts bonded warehouse investments for sub-48-hour e-commerce fulfillment guarantees.
Chile
Santiago-Valparaíso corridor service tiers must publish statistical performance guarantees under consumer protection agency mandates. The civil aviation authority pilots beyond-visual-line-of-sight frameworks for remote Andean delivery, opening mountainous zones currently served only by ground couriers. Cross-border e-commerce fulfillment concentrates in Santiago distribution nodes serving Asia-Pacific shippers.
Argentina
Buenos Aires sorting hubs require conveyor and optical character recognition upgrades to handle parcel volume surges under weight-based pricing models. Mercosur customs harmonization initiatives enable single-window clearance across Brazil-Argentina-Uruguay corridors, reducing cross-border friction. The metropolitan zone retains legacy infrastructure constraints that compress transit-time reliability versus Santiago or São Paulo benchmarks.
Colombia
Bogotá and Medellín corridors face Andean terrain limitations that restrict truck payload efficiency and extend transit times versus coastal alternatives. Maritime shipping consolidates bulk parcel flows through Pacific-facing ports, displacing ground transport for non-urgent cross-border volumes. The national postal operator navigates universal service obligations while private carriers target premium express lanes.
Latin America Postal Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service-tier and infrastructure-integration dimensions. The market structures around three tiers: incumbent national postal operators with universal service mandates, global express carriers with bonded warehouse networks, and regional specialists with corridor-specific density advantages. Strategic archetypes include the universal-coverage incumbent, the cross-border express integrator, and the last-mile technology platform. Competitive moves concentrate on hub automation capex and reverse logistics integration contracts.
Within the universal-coverage tier, Brazilian Post and Correos de México anchor nationwide retail networks through regulatory mandates. Among regional specialists, Chilexpress occupies a position exemplifying cross-border e-commerce fulfillment density between Santiago and distribution nodes. DHL Express represents the global integrator archetype with time-definite international lanes and customs pre-clearance capabilities.
| Leading Market Players |
|---|
| UPS Brazil |
| Chilexpress |
| Brazilian Post |
| Loggi |
| Serpost |
| Correos de México |
| FedEx Mexico |
| DHL Express |
| SkyPost |
| Others |
Supply & Pricing Matrix
E-commerce platform procurement consolidation around sub-48-hour fulfillment guarantees is compressing carrier margins and forcing infrastructure densification in São Paulo and Santiago corridors. This buyer-driven service-level escalation feeds back into pricing power concentration among bonded warehouse operators while squeezing standard mail routes under universal service obligations.
Pricing Analysis
Time-definite delivery guarantees with statistical performance commitments anchor value-based pricing for express operators serving Santiago-Valparaíso and São Paulo-Rio de Janeiro corridors. Three-tier pricing structure across premium express, standard parcel, and economy mail tiers separates carriers by customs pre-clearance capability and real-time tracking integration. Cost compression in standard mail intensifies because Brazil's telecommunications regulator enforces fixed tariff ceilings under universal service mandates. Small businesses and individual shippers exhibit highest price sensitivity, while corporations absorbing annual volume commitments with integrated warehousing show lowest elasticity.
Supply Chain Analysis
Diesel cost volatility across Mexico and Brazil ground transport fleets directly pressures route economics for universal service obligations. Supply concentration rests on southeastern Brazil's Guarulhos distribution cluster, Santiago's bonded warehouse nodes, and Mexico City's metropolitan sorting infrastructure. Sorting hub automation capex, temperature-controlled pharmaceutical handling equipment, and optical character recognition systems constitute critical input dependencies. Single-source vulnerability concentrates in customs brokerage talent pools trained on HS code classification. Distribution runs through hub-and-spoke networks anchored in coastal metropolitan zones, with maritime alternatives displacing ground transport for Pacific-facing Andean corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American postal services are transitioning from legacy retail-network coverage models to intelligent locker infrastructure and real-time tracking APIs. Automated sortation and digital freight platforms are displacing manual hub operations and paper-based customs processes.
For Market Incumbents: Deploy intelligent parcel locker networks across Brazilian apartment complexes and Mexico City commercial districts to defend residential access against last-mile technology platforms. Correos de México and Brazilian Post must accelerate optical character recognition upgrades in legacy Buenos Aires and Lima facilities to match volume surge handling capabilities. Channel control through pre-installed refrigerated and ambient locker banks reduces failed-delivery rates that plague single-attempt courier competitors. For New Entrants and Emerging Players: Subscription box merchants consolidating procurement around integrated warehousing-plus-delivery contracts represent the most penetrable buyer archetype for regional specialists. Santiago-Valparaíso corridor same-day tier performance guarantees offer white-space entry for drone certification holders under Chile's civil aviation authority pilot framework. Guadalajara and Mexico City returns processing unbundling creates standalone reverse logistics service contracts absent incumbent bundling. For Investors and Strategic Acquirers: Re-rating potential sits with bonded warehouse operators given Mercosur customs harmonization enabling single-window clearance across Brazil-Argentina-Uruguay corridors. Mid-scale e-commerce sellers displacing multi-tenant shared warehousing for dedicated contract logistics space in São Paulo's Guarulhos cluster represent acquisition target archetype with infrastructure-integration premiums. Monitor ANVISA pharmaceutical distribution mandate expansion as inflection indicator for temperature-controlled last-mile infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Bonded Warehouse Capacity Expansion | Captures customs pre-clearance volume from Asia-Pacific shippers in Santiago and São Paulo nodes. |
| Intelligent Parcel Locker Deployment | Consolidates last-mile handoff points across Brazilian residential complexes and Mexico City districts. |
| Optical Character Recognition Upgrade | Enables legacy Buenos Aires and Lima sorting hubs to handle parcel volume surges under weight-based tariffs. |
| Reverse Logistics Integration | Unbundles returns processing from forward delivery for Guadalajara and Mexico City e-commerce platforms. |
| Drone Certification Pathway | Opens mountainous Andean zones under Chile's civil aviation authority beyond-visual-line-of-sight pilot framework. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with express carrier operations directors, postal regulator policy leads, e-commerce platform logistics procurement managers, and customs brokerage firm principals combined with secondary validation from ANVISA pharmaceutical distribution mandates, Brazil telecommunications regulator universal service fund disclosures, and Chile consumer protection agency delivery-time disclosure requirements. Bottom-up parcel volume modeling and top-down macroeconomic triangulation reconciled segment-level outputs.
Data-stream reconciliation across shipment volume databases, carrier capacity disclosures, and e-commerce platform fulfillment contract structures informed the analytical framework. Segmentation dimensions modeled include service type, customer archetype, delivery method, and pricing model across the projection horizon. CAGRs were derived from trend extrapolation of bonded warehouse capacity expansion, intelligent locker installation rates, and cross-border e-commerce shipment growth curves. Temperature-controlled pharmaceutical distribution infrastructure investments and Mercosur customs harmonization implementation timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aviation regulator drone certification timelines, fuel price volatility effects on ground transport fleet economics, and universal service fund contribution rate adjustments by national telecommunications regulators. Forecasts reflect documented assumptions regarding e-commerce platform procurement consolidation patterns and customs pre-clearance technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
North America Postal Services Market
Communication Services
Pcaas Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Broadcasting Solutions Market
Communication Services
Global Communications Interface Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
Video Conferencing Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Green Communication Market
Communication Services
Consumer Communication Services Market
Communication Services
Meeting Solutions Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Web Conferencing Market