
 Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market | 2026-2036
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market Outlook
The over-the-air broadcast channel is narrowing as ATSC 3.0 transition timelines compress station upgrade cycles. Sinclair Broadcast Group leverages its station portfolio scale to anchor NextGen TV rollout across multiple DMAs. Pearl TV sustains broadcaster consortium coordination for spectrum-sharing and single-frequency network trials. ONE Media Technologies competes on software-defined broadcast architecture that reduces transmitter hardware dependency.
Advanced Television Systems Committee broadcast systems and services encompass terrestrial digital television transmission infrastructure employing OFDM modulation, IP-based transport streams, and hybrid broadcast-broadband delivery to enable 4K UHD, immersive audio, and targeted advertising. ATSC 3.0 technology segments lead capital deployment as stations replace ATSC 1.0 MPEG-2 infrastructure with HEVC and Dolby AC-4 codecs. Service type demand concentrates in live broadcast and emergency alert applications where low-latency IP distribution outperforms legacy architectures, while interactive services and data casting represent emerging margin pools as broadcasters seek addressable revenue beyond linear advertising.
The FCC governs spectrum allocation and mandated ATSC 3.0 transition procedures, while the U.S. Consumer Technology Association coordinates receiver certification standards that shape OEM market access. South Korea's MSIT and KCC accelerated early ATSC 3.0 deployment, providing regulatory precedent that influences FCC timing and technical parameter choices. Stakeholders must monitor receiver penetration thresholds and broadcaster simulcast obligations to calibrate infrastructure investment against actual consumer adoption curves.
Market Dynamics
The FCC's spectrum repack mandate compresses station upgrade cycles as broadcasters face simultaneous ATSC 3.0 transition obligations and channel relocation deadlines. Capital allocation tilts toward transmitter hardware and encoding infrastructure while advertising revenue recovery remains uneven.
Growth Catalysts
- NextGen TV deployment:Major metropolitan markets in the United States accelerate consumer receiver penetration through coordinated broadcaster consortium trials. Single-frequency network architecture reduces spectrum requirements per station.
- Emergency alert modernization:IP-based distribution enables geo-targeted alerts with lower latency than legacy architectures. Broadcasters leverage this capability for public service mandate fulfillment and competitive differentiation.
- HEVC codec adoption:Compression efficiency gains allow 4K UHD carriage within existing 6 MHz channels. Station groups prioritize this upgrade path for spectrum efficiency and future service scalability.
Market Restraints
- Transmitter hardware concentration:Specialized RF amplifier and antenna suppliers concentrate manufacturing in Germany and the United States, creating procurement bottlenecks during simultaneous station upgrade waves.
- Consumer receiver penetration lag:Television OEMs integrate ATSC 3.0 tuners gradually, with cost-sensitive models delaying adoption. Broadcasters face uncertain return timelines on infrastructure investment.
- Simulcast spectrum burden:FCC obligations require maintaining ATSC 1.0 service during transition periods, effectively halving available spectrum for NextGen TV services until viewer threshold milestones.
Strategic Opportunities
- Targeted advertising infrastructure:IP return path integration enables addressable spot insertion and impression-level measurement. Broadcasters compete directly with connected TV platforms for automotive and pharmaceutical ad budgets.
- South Korean export precedent:Early MSIT and KCC deployment provides proven technical parameters and receiver ecosystem models. Equipment vendors reference this regulatory precedent for FCC timing advocacy.
- Data casting services:Excess payload capacity supports automotive navigation updates, software distribution, and IoT firmware delivery. Broadcasters seek recurring revenue streams beyond linear advertising.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in OFDM modulation and SFN synchronization concentrates among retiring broadcast engineers. Station groups compete for limited contract engineering resources during peak deployment windows.
- Legacy facility integration:ATSC 1.0 master control and traffic systems require parallel operation during transition periods. Dual-path workflows strain operational staffing and introduce error risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market |
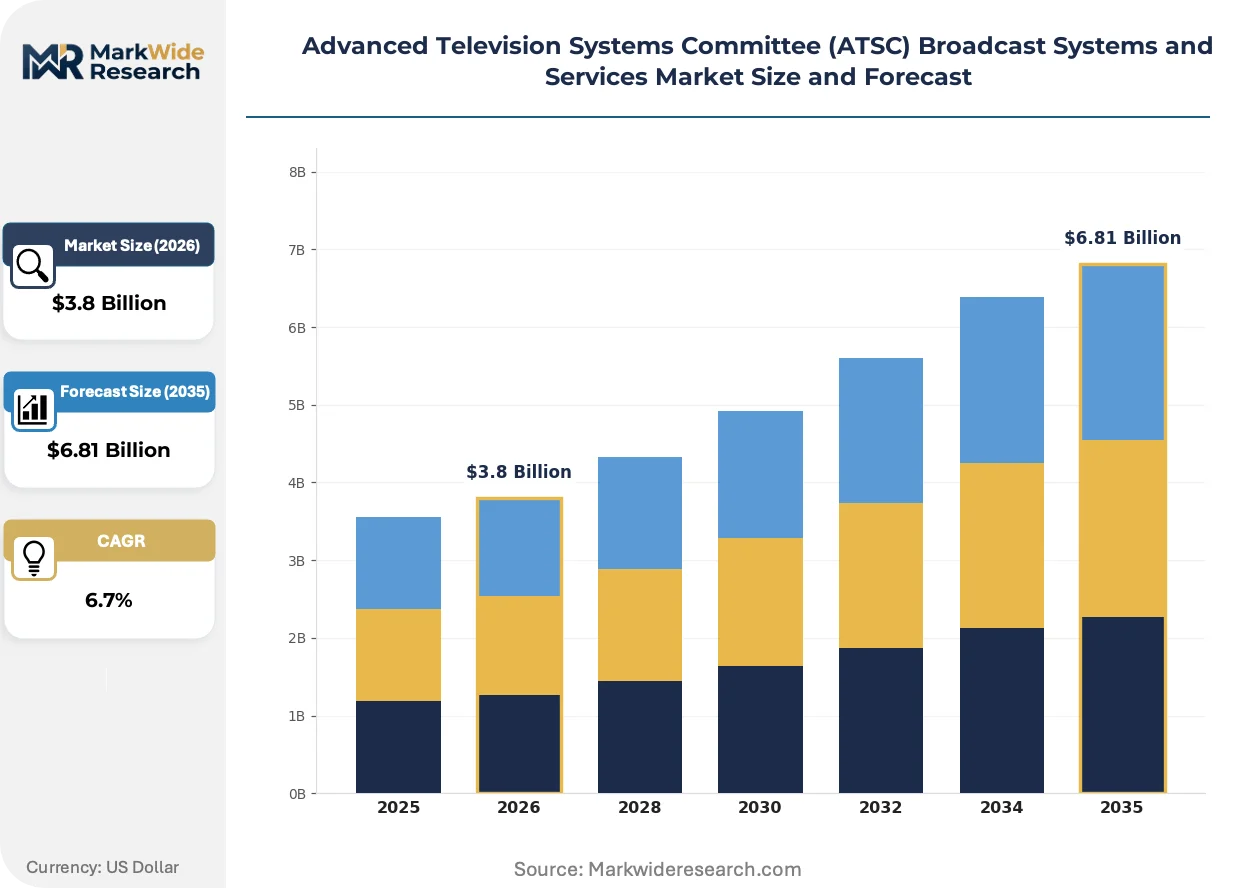
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: ATSC 1.0, ATSC 3.0, Digital Broadcasting, MPEG-2, Dolby AC-4, HEVC Service Type: Live Broadcast, Video On Demand, Multicast, Emergency Alert, Interactive Services, Data Casting Application: Television Broadcasting, Public Safety, Mobile TV, Smart TV, Connected Vehicles, Remote Monitoring End User: Broadcasters, Content Providers, Network Operators, Government Agencies, OEMs, Consumer Electronics Manufacturers |
| Companies Covered | ADTH, Pearl TV, Sinclair Broadcast Group, Mirakulo, Televes USA, ONE Media Technologies, ZapperBox, Globo, SiliconDust, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market Strategic Shifts
Software-defined architectures are displacing purpose-built hardware across transmission chains, compressing capital cycles and enabling remote operation models. Broadcast infrastructure vendors pivot toward service-based revenue as hardware margins erode.
Cloud-native encoding and multiplexing is virtualizing functions previously executed by on-premise appliances. Station groups in the United States deploy centralized processing hubs serving multiple transmitters. This architecture reduces site-specific equipment counts and enables dynamic service reconfiguration without truck rolls.
The FCC's 2023 update to NextGen TV simulcast rules accelerates sunset planning for ATSC 1.0 service. Broadcasters in major metropolitan markets file transition notices earlier than anticipated. Consumer Technology Association certification timelines compress as OEMs align product roadmaps with regulatory milestones.
Automotive OEM procurement of terrestrial broadcast connectivity is reshaping receiver demand patterns. Tier-1 suppliers integrate ATSC 3.0 tuners for real-time traffic and emergency alert delivery. South Korean and United States vehicle programs lead this specification shift, with European markets evaluating similar requirements.
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market Segmentation
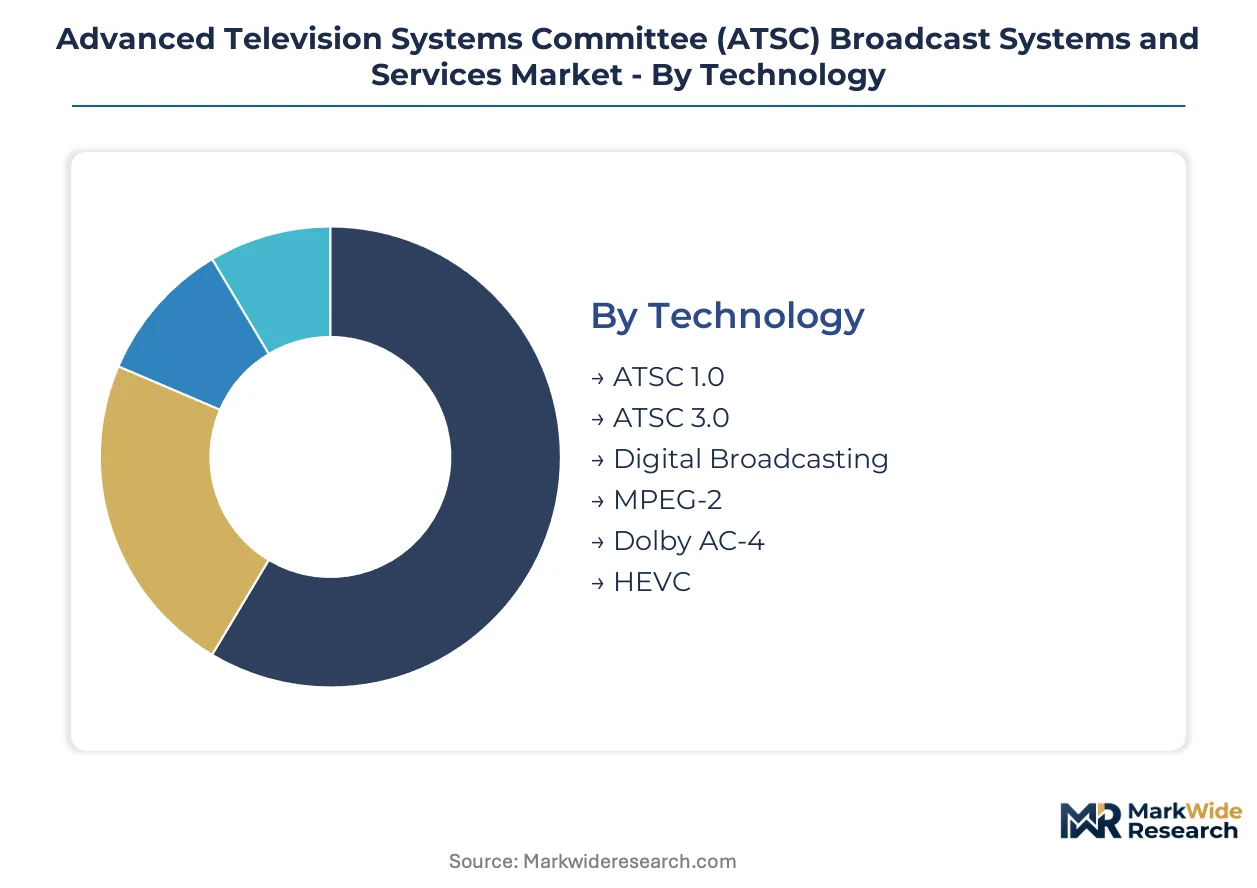
ATSC broadcast infrastructure investment flows through distinct technology generations and service models that reshape capital allocation priorities. Station groups calibrate upgrade sequencing across transmission standards, content delivery formats, and end-user equipment integration requirements.
Technology:
The use-case spectrum spans legacy MPEG-2 transmission through next-generation IP-native architectures, with codec efficiency and spectrum flexibility determining deployment economics.
- ATSC 3.0:OFDM-based physical layer enables 4K UHD, immersive audio, and hybrid broadcast-broadband delivery through scalable modulation. Sinclair Broadcast Group and Pearl TV consortium members prioritize this upgrade path in United States metropolitan markets where FCC transition timelines compress investment windows.
- HEVC:Compression efficiency roughly doubles versus MPEG-2, allowing enhanced services within existing 6 MHz channel allocations. South Korean broadcasters established early deployment precedent that influences United States station group codec procurement decisions.
- ATSC 1.0:Legacy MPEG-2 infrastructure remains operational under FCC simulcast mandates during transition periods. Stations maintain dual-path transmission chains until viewer threshold milestones permit service sunset.
- Digital Broadcasting:Terrestrial transmission infrastructure employing standardized modulation and transport stream protocols.
- MPEG-2:Legacy compression standard requiring full replacement for NextGen TV service carriage.
- Dolby AC-4:Immersive audio codec enabling object-based sound delivery and personalization features.
The dominant share belongs to ATSC 1.0, while ATSC 3.0 is closing the gap fastest.
Service Type:
Revenue models diverge between linear advertising-supported delivery and emerging addressable services that monetize IP return paths.
- Live Broadcast:Real-time linear programming remains the core revenue foundation for station groups, with low-latency IP distribution now replacing satellite and microwave backhaul in United States markets. Sports and election coverage drive premium advertising rates that justify infrastructure investment.
- Emergency Alert:Geo-targeted notification capabilities leverage ATSC 3.0's IP distribution architecture for lower latency than legacy EAS systems. FEMA and state emergency management agencies in the United States fund pilot deployments that demonstrate public service value.
- Video On Demand:Time-shifted content delivery through hybrid broadcast-broadband integration.
- Multicast:Multiple program streams within single 6 MHz channel allocation.
- Interactive Services:Two-way engagement features requiring return path connectivity.
- Data Casting:Non-television payload delivery for automotive, IoT, and software distribution applications.
Live Broadcast commands the largest revenue base, though Data Casting is expanding most quickly as broadcasters seek recurring revenue beyond linear advertising.
Application:
Deployment patterns cluster around consumer television reception, specialized mobility use cases, and public safety mandates with distinct technical requirements.
- Television Broadcasting:Primary consumer-facing application driving transmitter site upgrades and encoding infrastructure replacement across United States DMAs. Station groups coordinate market-by-market transitions through Pearl TV consortium arrangements.
- Connected Vehicles:Automotive OEM integration of ATSC 3.0 tuners for real-time traffic and emergency alert delivery. Hyundai and Kia programs in South Korea established technical precedent now influencing United States Tier-1 supplier specifications.
- Public Safety:First responder and emergency management communication infrastructure.
- Mobile TV:Handheld and vehicular reception requiring robust signal propagation.
- Smart TV:Integrated receiver devices with ATSC 3.0 tuner certification.
- Remote Monitoring:Broadcast-delivered sensor data and surveillance applications.
Television Broadcasting retains the dominant deployment share, while Connected Vehicles is gaining share fastest through automotive OEM procurement cycles.
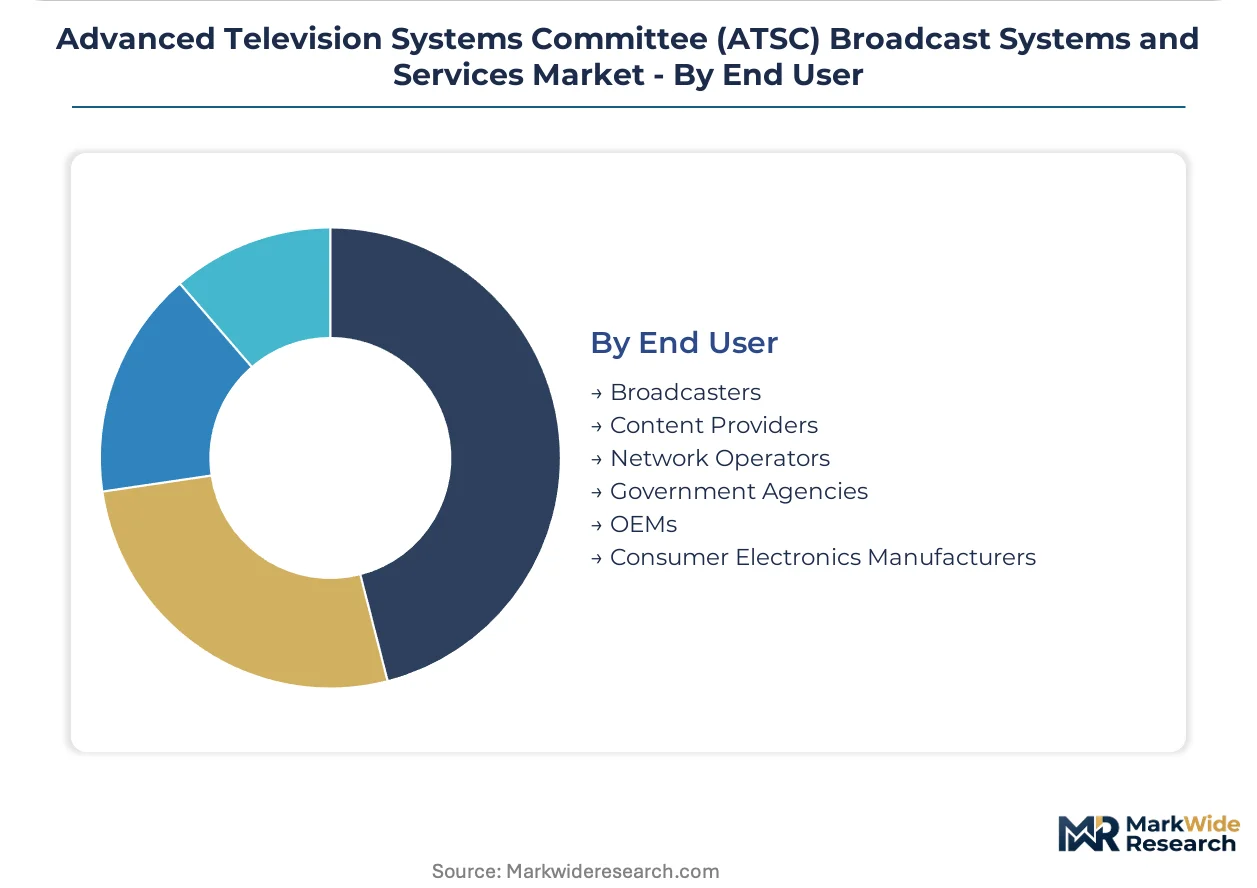
End User:
Procurement authority concentrates among station ownership groups and network affiliates with capital deployment timelines shaped by regulatory mandates.
- Broadcasters:Local television stations and station group owners control transmitter hardware and encoding infrastructure procurement. Nexstar Media Group and Tegna deploy capital across multiple DMAs under FCC-coordinated transition schedules.
- Government Agencies:Public safety and emergency management entities fund alert system modernization. United States Department of Homeland Security grants support ATSC 3.0 emergency communication pilot deployments.
- Content Providers:Programming entities requiring transmission carriage services.
- Network Operators:Affiliation and distribution network management entities.
- OEMs:Original equipment manufacturers integrating ATSC 3.0 reception capabilities.
- Consumer Electronics Manufacturers:Television and device producers seeking CTA certification.
Broadcasters hold the dominant procurement position, though Government Agencies are accelerating investment fastest through dedicated public safety modernization funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The terrestrial broadcast transmission grid underwrites national media distribution capacity across ATSC-standard territories, with fiber backhaul networks and tower infrastructure determining upgrade feasibility.
United States
Major metropolitan DMAs drive transmitter site modernization as FCC repack deadlines compress capital deployment windows. The FCC's 2023 NextGen TV simulcast rule updates accelerate ATSC 1.0 sunset planning. Los Angeles and New York anchor the Pearl TV consortium's single-frequency network trials.
South Korea
Seoul Capital Area broadcasters established early ATSC 3.0 deployment precedent that influences global technical parameter choices. MSIT and KCC spectrum policies provided regulatory frameworks for 4K UHD and mobile broadcast services. Busan-Ulsan transmission clusters demonstrate automotive integration use cases for connected vehicle programs.
Canada
Border-adjacent markets coordinate spectrum planning with United States repack timelines to maintain cross-border interference protections. Industry Canada and CRTC joint frameworks govern digital transition obligations. Toronto and Vancouver station groups evaluate ATSC 3.0 migration paths aligned with FCC milestone schedules.
Mexico
IFT spectrum harmonization with United States channel allotments shapes transmitter infrastructure procurement. Federal telecommunications reform mandates digital television penetration targets. Mexico City and Monterrey broadcast markets concentrate capital deployment for network affiliate upgrades.
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the RF amplification and encoding stack. Market structure tilts toward consolidated station group ownership alongside fragmented equipment supply. Three archetypes dominate: broadcaster consortiums coordinating market-level deployment, transmission infrastructure vendors, and software-defined architecture providers. Competitive moves concentrate on consortium formation for spectrum-sharing trials and cloud-native encoding partnerships that displace on-premise hardware.
Among United States-based broadcast operators, Sinclair Broadcast Group and Pearl TV occupy positions as deployment anchors across multiple DMAs. ONE Media Technologies exemplifies the software-defined architecture tier with reduced transmitter hardware dependency. ADTH represents international equipment supply positioning for North American infrastructure procurement cycles.
| Leading Market Players |
|---|
| ADTH |
| Pearl TV |
| Sinclair Broadcast Group |
| Mirakulo |
| Televes USA |
| ONE Media Technologies |
| ZapperBox |
| Globo |
| SiliconDust |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in German RF amplifier manufacturing is compressing transmitter hardware margins while simultaneously extending lead times for United States station groups facing FCC-mandated upgrade deadlines. This utilization imbalance forces procurement teams toward multi-source strategies that fragment volume discounts across smaller orders.
Pricing Analysis
Volume-discount tiering structures dominate transmitter procurement, with station groups securing standard-tier pricing for single-site deployments and premium-tier terms reserved for multi-DMA consortium arrangements led by Pearl TV. Price differentiation hinges on HEVC codec certification levels and after-sales service bundling. Cost compression in encoding hardware is intensifying because cloud-native alternatives displace purpose-built appliances. Government agencies exhibit lowest price sensitivity due to dedicated public safety modernization funding, while independent broadcasters face acute margin pressure.
Supply Chain Analysis
Contract-manufacturing concentration for RF power amplifiers sits with German and United States specialized foundries, with South Korean EMS providers capturing encoding equipment assembly. Geographic supply concentration spans Germany, the United States, and South Korea for finished transmitters, while semiconductor components draw from Taiwan and Japan. Raw material dependencies include gallium nitride substrates, high-purity copper, and specialized ceramic insulators. Single-source vulnerability in OFDM modulation chipsets threatens deployment timelines. Distribution runs through direct OEM relationships with station ownership groups, bypassing traditional broadcast equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market fragments across deployment models, creating niches as automotive OEM demand for terrestrial broadcast connectivity diverges from traditional television receiver specifications.
For Market Incumbents: Entrench consortium coordination advantages by deepening Pearl TV's single-frequency network architecture investments and securing exclusive encoding equipment partnerships that lock out emerging software-defined competitors. The threat of ONE Media Technologies' cloud-native platforms demands backward integration into managed services to capture recurring revenue beyond hardware margins.
For New Entrants and Emerging Players: Canadian border-adjacent markets present underpenetration opportunities where Industry Canada coordination lags FCC repack timelines, allowing agile vendors to establish reference deployments before incumbent saturation. Target data casting services for connected vehicle applications, leveraging South Korean automotive OEM relationships as proof points for United States Tier-1 supplier qualification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined architecture providers with service-based pricing models that displace capital-intensive hardware procurement. Long-term viability over the coming decade rests on IP return path monetization capabilities rather than transmission infrastructure ownership. Acquisition targets should demonstrate emergency alert system certifications as inflection indicators for public safety funding capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Single-Frequency Network Deployment | Pearl TV consortium trials in Los Angeles demonstrate spectrum-sharing economics that reduce per-station capital requirements. |
| Cloud-Native Encoding Migration | Virtualized processing hubs enable Sinclair Broadcast Group to serve multiple DMAs from centralized infrastructure. |
| Automotive OEM Integration Partnership | Hyundai and Kia programs establish ATSC 3.0 tuner specifications that influence United States Tier-1 supplier roadmaps. |
| Emergency Alert System Certification | FEMA pilot deployments unlock Department of Homeland Security grant funding for infrastructure modernization. |
| Software-Defined Architecture Development | ONE Media Technologies reduces hardware dependency through service-based revenue models that compress customer capital cycles. |
Study Parameters
Initial hypotheses were tested against primary input from broadcast engineering directors, FCC regulatory affairs specialists, station group procurement executives, and automotive Tier-1 supplier technology planners, then refined against secondary validation from FCC docket filings, CTA certification databases, SEC 10-K disclosures from publicly traded station groups, and South Korean MSIT policy documents. Bottom-up transmitter deployment tallies triangulated against top-down advertising revenue allocation models.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling technology generation transitions, service type revenue mix, application deployment patterns, and end-user procurement authority as core segmentation dimensions. CAGRs were derived from infrastructure investment trajectories calibrated against regulatory milestone schedules and receiver penetration curves. Industry-specific inputs included FCC repack completion timelines and automotive OEM program launch cadences.
Practitioners should monitor FCC simulcast rule modifications and CTA certification timeline compressions for early signals of ATSC 1.0 sunset acceleration. Forecasts reflect assumptions regarding consumer receiver adoption thresholds and broadcaster capital allocation priorities. Quarterly review of transmitter hardware order backlogs and automotive OEM specification releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Pcaas Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Speech to Speech Translation Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Global Passenger Information System Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Voip Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Industrial Communication Market
Communication Services
Web Conferencing Market
Communication Services
Cloud Communication Platform Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
North America Postal Services Market
Communication Services
Global Communications Interface Market
Communication Services
Green Communication Market
Communication Services
Walkie Talkie Market